
 Glycylglycine Market | 2026-2036
Glycylglycine Market Size, Share, and Industry Trends Forecast 2026-2036
Glycylglycine Market Foresight
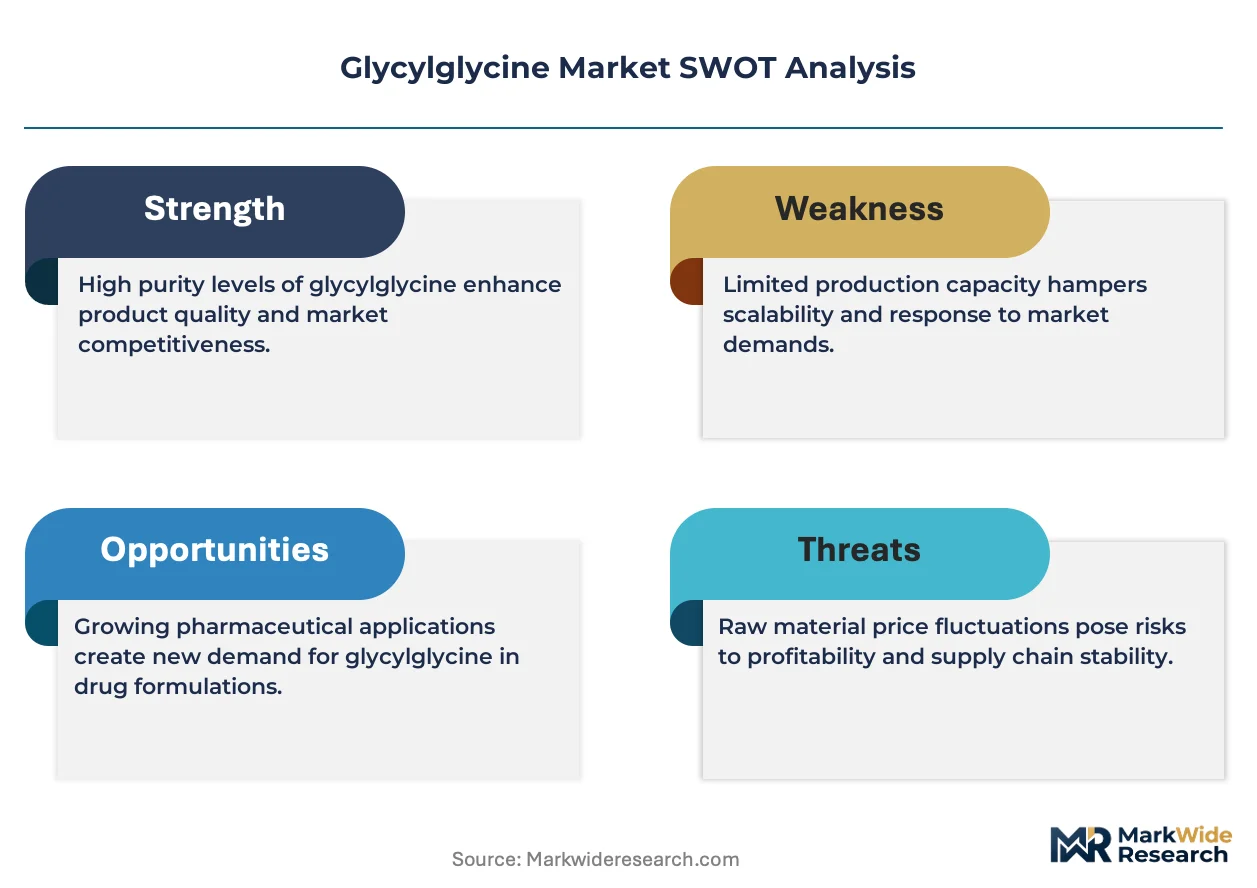
ISO 17025 accreditation is rotating as the primary gating standard for glycylglycine suppliers serving pharmaceutical and biotechnology customers. Hamari Chemicals Ltd. leverages its peptide synthesis expertise to anchor high-purity grades for research institutions. Carl Roth GmbH sustains broad European distribution through dense channel control across German-speaking laboratories. SIELC Technologies specializes in chromatography-grade glycylglycine, differentiating on analytical validation protocols.
Glycylglycine is a dipeptide composed of two glycine residues linked by a peptide bond, typically supplied at purity levels exceeding 99% for cell culture and buffer applications. Manufacturers produce it through solid-phase peptide synthesis or enzymatic condensation, with the compound serving as a buffering agent and stabilizer in protein formulation workflows. Pharmaceutical-grade material commands the dominant value share due to stringent endotoxin and heavy metal specifications. Biotechnology firms represent the fastest-growing end-user category as CRISPR-based cell line development expands peptide buffer consumption. Bulk packaging formats occupy the volume leadership position while sachet configurations capture premium pricing in specialty research channels.
EMA's ICH Q7 guidelines and USP general chapters on peptide excipients shape manufacturing documentation requirements for glycylglycine destined for injectable formulations. China's NMPA has tightened import registration for peptide raw materials, redirecting some supply chain qualification efforts toward domestic Chinese manufacturers. REACH registration obligations in Europe add compliance cost layers that favor established suppliers with dedicated regulatory affairs functions. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs as divergence creates formulation reformulation risks.
Market Dynamics
Pharmaceutical-grade peptide buffer demand from CRISPR-based cell line development is concentrating procurement power among biotechnology contract research organizations, reshaping supplier qualification protocols and purity specifications across the value chain.
Growth Catalysts
- REACH registration obligations:ECHA's chemical safety documentation requirements are elevating supplier barriers, favoring established European manufacturers with dedicated regulatory affairs infrastructure and driving consolidation among qualified vendors.
- Cell culture media expansion:Mammalian expression systems for monoclonal antibody production are consuming peptide buffers at accelerated rates, with CDMO networks in Germany and the United States scaling buffer preparation capacities.
- Enzymatic condensation methods:Biocatalytic peptide synthesis is reducing solvent waste profiles and lowering production costs for high-purity grades, attracting investment from sustainability-focused procurement teams.
Market Restraints
- Raw material glycine volatility:Petrochemical-derived glycine feedstock prices fluctuate with methanol and ammonia markets, compressing margins for manufacturers without backward integration into amino acid precursors.
- Supplier concentration in German-speaking Europe:Dense channel control by Carl Roth GmbH and regional distributors limits price competition and creates single-source vulnerability for smaller research institutions.
- Endotoxin specification escalation:USP general chapters on peptide excipients for injectable formulations are tightening acceptable endotoxin thresholds, requiring capital-intensive purification upgrades.
Strategic Opportunities
- Chinese domestic qualification pathways:NMPA's tightened import registration for peptide raw materials is redirecting supply chain efforts toward domestic Chinese manufacturers with established local regulatory relationships.
- Chromatography-grade specialization:Analytical validation protocols for HPLC and mass spectrometry applications command premium pricing and foster long-term service contracts with instrument vendors.
- Sachet configuration premium channels:Pre-weighed single-use formats for specialty research workflows reduce preparation time and contamination risk, capturing pricing power in proteomics and structural biology laboratories.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergence between USP, EP, and JP monographs for peptide excipients forces manufacturers to maintain multiple specification sets, complicating inventory management and batch release.
- ISO 17025 accreditation timelines:Third-party laboratory certification for analytical method validation extends supplier onboarding cycles, delaying contract awards and straining procurement planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycylglycine Market |
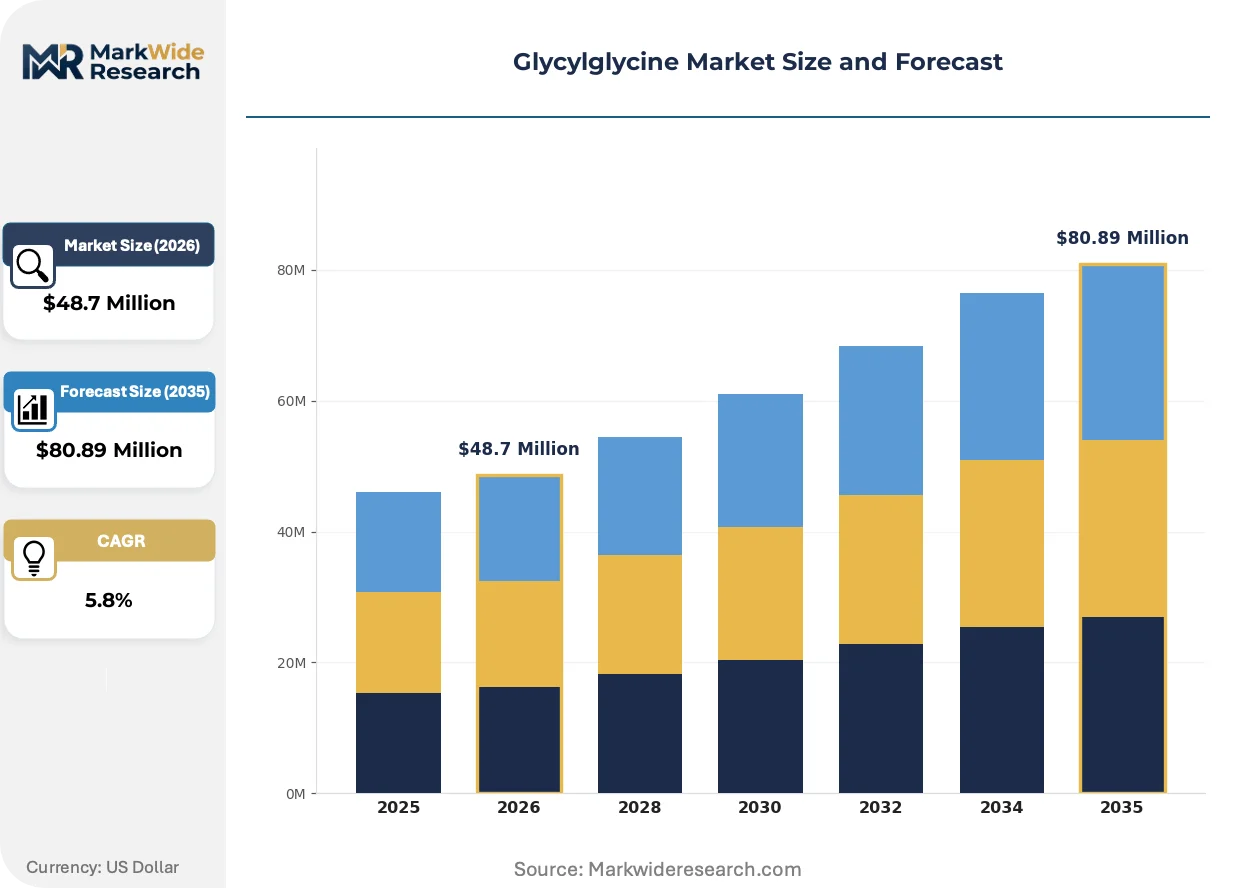
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutraceuticals, Cosmetics, Agrochemicals End User: Pharmacies, Biotechnology Firms, Research Institutions, Cosmetic Companies Packaging Type: Bulk Packaging, Bottles, Sachets, Blister Packs Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | SIELC Technologies, Hamari Chemicals Ltd., VWR AMRESCO, Sorachim, Carl Roth GmbH, Bio Basic Inc., RPI, Capot Chemical Co. Ltd, PhytoTech Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycylglycine Market Shifts & Advancements
Continuous processing technologies and digital batch records are converging to reshape peptide buffer manufacturing economics, while regulatory data integrity requirements accelerate technology adoption across quality control functions.
Enzymatic peptide synthesis platforms are fragmenting the traditional solid-phase manufacturing base. Biocatalytic condensation using engineered hydrolases achieves stereoselective bond formation without protecting group chemistry. Contract manufacturers in the Netherlands and Switzerland are retrofitting fermentation capacity to capture this transition. The technology is fragmenting established supplier hierarchies by enabling mid-scale producers to match purity profiles previously exclusive to large-scale chemical synthesis operations.
EMA's ICH Q7 guideline implementation for active pharmaceutical ingredient starting materials is tightening documentation requirements for glycylglycine destined for injectable formulations. Manufacturers must now demonstrate supply chain transparency back to amino acid precursors. European CDMOs are responding by qualifying dual-source glycine suppliers and investing in blockchain-based batch tracking systems to satisfy regulatory inspections.
Research institutions are consolidating peptide buffer procurement through group purchasing organizations and university consortium agreements. Centralized contracts with preferred suppliers replace individual laboratory ordering, compressing vendor counts and extending payment terms. This concentration is most visible in the United States National Institutes of Health-funded research clusters, where shared service centers now negotiate framework agreements covering multiple campuses and affiliated hospitals.
Glycylglycine Market Segmentation
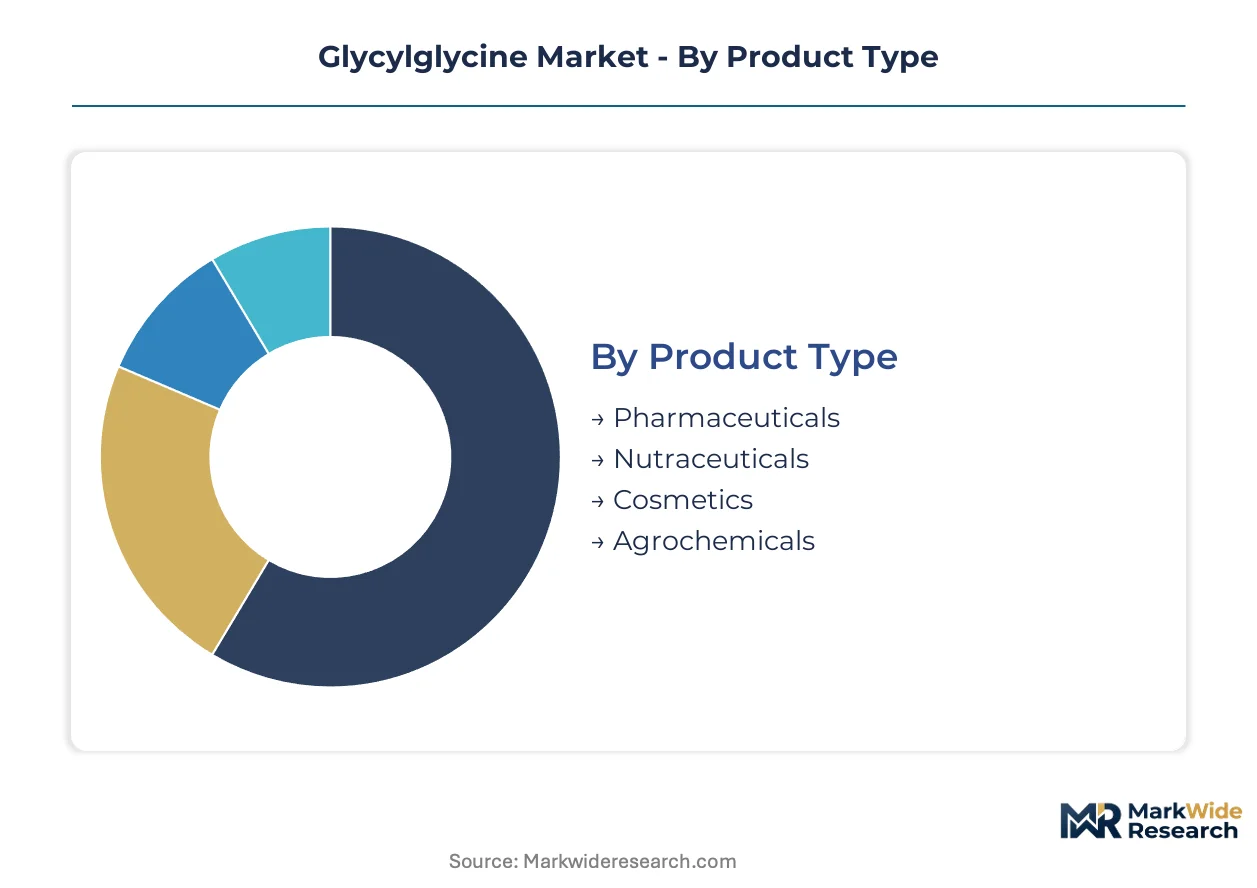
Glycylglycine procurement patterns diverge sharply across end-use applications, with pharmaceutical buffer specifications demanding endotoxin documentation that cosmetic and agrochemical grades rarely require. Segmentation reveals how regulatory tiering concentrates supplier qualification investments toward injectable-grade production while adjacent categories operate under lighter compliance burdens.
Product Type:
EMA's ICH Q7 guidelines and USP peptide excipient monographs create graduated compliance thresholds that pharmaceutical-grade manufacturers must satisfy, while nutraceutical and cosmetic categories face less stringent documentation requirements.
- Pharmaceuticals:Injectable-grade material demands endotoxin thresholds below established USP general chapter limits and heavy metal specifications traceable to amino acid precursors. CDMO networks in Germany and the United States concentrate procurement here as CRISPR-based cell line development expands buffer consumption for monoclonal antibody production workflows.
- Nutraceuticals:Oral delivery formats tolerate broader purity ranges, though FDA dietary supplement cGMPs still mandate identity testing and contamination screening. Demand clusters among North American contract manufacturers serving sports nutrition and cognitive health formulations where peptide bioavailability claims drive inclusion.
- Cosmetics:Peptide stabilizers for anti-aging formulations operate under EU Cosmetics Regulation safety dossier requirements without the batch-level documentation mandatory for pharmaceutical applications.
- Agrochemicals:Biostimulant and plant growth regulator applications utilize technical-grade material with minimal peptide purity enforcement beyond basic identity confirmation.
Established volume favors Pharmaceuticals; emerging adoption favors Nutraceuticals.
End User:
Procurement concentration among biotechnology contract research organizations is reshaping supplier qualification protocols, with framework agreements replacing fragmented laboratory purchasing.
- Biotechnology Firms:CRISPR-based cell line development operations consume peptide buffers at accelerated rates, with mammalian expression systems for monoclonal antibody production scaling buffer preparation capacities across CDMO networks. These firms negotiate multi-year supply agreements with ISO 17025-accredited vendors.
- Research Institutions:University consortium agreements and group purchasing organizations consolidate procurement through shared service centers, compressing vendor counts and extending payment terms. NIH-funded research clusters in the United States now negotiate framework agreements covering multiple campuses.
- Pharmacies:Compounding operations for specialized parenteral formulations require small-batch pharmaceutical-grade supply with rapid turnaround documentation.
- Cosmetic Companies:Peptide inclusion in premium skincare lines drives demand for cosmetic-grade material with marketing-friendly purity certifications rather than full pharmaceutical documentation.
Biotechnology Firms are climbing the fastest as cell therapy manufacturing scales; Research Institutions retain volume leadership through consolidated purchasing power.
Packaging Type:
Margin structures stratify sharply between bulk industrial formats and precision-dosed configurations serving proteomics laboratories.
- Bulk Packaging:Drum and pail configurations dominate CDMO and large-scale manufacturing procurement, with kilogram-scale orders capturing economies of scale in buffer preparation workflows. German and Chinese manufacturers optimize production runs for this high-volume, lower-margin segment.
- Sachets:Pre-weighed single-use formats command premium pricing in structural biology and proteomics applications where contamination risk reduction justifies per-gram cost multiples. Specialty research channels favor this configuration for time-sensitive experimental setups.
- Bottles:Standard laboratory containers serve mid-scale research operations with resealable storage for multi-experiment campaigns.
- Blister Packs:Unit-dose presentations support clinical trial material preparation and regulatory submission batches requiring precise allocation tracking.
Bulk Packaging anchors volume economics; Sachets capture margin expansion in precision research channels.
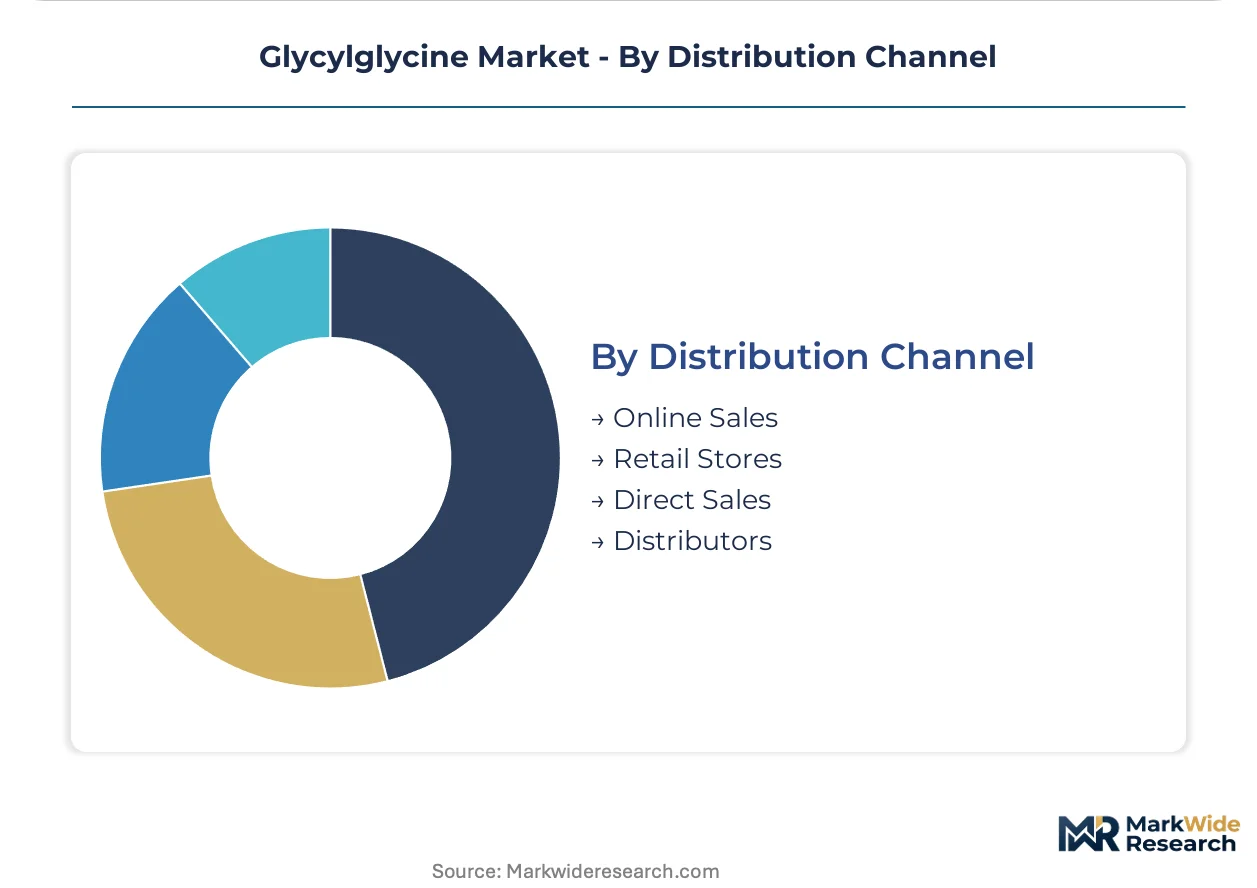
Distribution Channel:
Channel control patterns reflect the geographic concentration of qualified suppliers and the urgency of end-user procurement cycles.
- Distributors:Carl Roth GmbH and regional laboratory supply houses maintain dense channel control across German-speaking European markets, limiting price competition through established relationships with research institution procurement departments.
- Direct Sales:Pharmaceutical-grade manufacturers serving CDMO networks bypass intermediaries to manage regulatory documentation chains and custom specification negotiations directly.
- Online Sales:E-commerce platforms capture small-volume research orders with rapid fulfillment, though ISO 17025 accreditation requirements slow supplier onboarding for new entrants.
- Retail Stores:Limited to cosmetic-grade and nutraceutical applications with consumer-facing packaging, this channel remains marginal for technical and pharmaceutical grades.
Distributors retain institutional lock-in; Direct Sales are gaining share fastest as CDMO consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration obligations and NMPA import tightening are redirecting procurement toward qualified domestic manufacturers across key pharmaceutical clusters. Biotechnology contract research organizations concentrate demand in jurisdictions with established CDMO infrastructure and harmonized pharmacopeial standards.
Germany
EMA's ICH Q7 guidelines and REACH compliance requirements anchor supplier qualification protocols for injectable-grade peptide buffers. Carl Roth GmbH maintains dense distribution control across German-speaking laboratory networks. The Rhine-Main cluster around Frankfurt hosts multiple CDMO facilities scaling mammalian expression system capacity for monoclonal antibody production workflows.
United States
NIH-funded research clusters and CRISPR-based cell line development operations drive pharmaceutical-grade peptide buffer consumption. FDA cGMP enforcement and USP general chapter updates on peptide excipients tighten endotoxin documentation requirements. The Greater Boston biotech corridor consolidates procurement through university consortium agreements covering multiple campuses and affiliated hospitals.
China
NMPA's tightened import registration for peptide raw materials redirects supply chain qualification efforts toward domestic manufacturers with established regulatory relationships. Dual carbon goals accelerate enzymatic condensation method adoption for reduced solvent waste profiles. The Yangtze River Delta concentration of fermentation capacity supports biocatalytic peptide synthesis platform retrofits.
Switzerland
Swissmedic documentation requirements and EMA guideline alignment position the jurisdiction as a qualification gateway for European injectable formulations. Contract manufacturers retrofit fermentation infrastructure to capture enzymatic synthesis transitions. The Basel-Lucerne corridor anchors peptide buffer supply relationships with global pharmaceutical headquarters operations.
Netherlands
ECHA chemical safety documentation infrastructure supports REACH-registered suppliers serving pan-European CDMO networks. Continuous processing technology adoption reshapes manufacturing economics for mid-scale peptide buffer production. The Rotterdam-Antwerp port cluster facilitates amino acid precursor import logistics for manufacturers without backward integration into glycine feedstocks.
Glycylglycine Market Competitive Landscape
Player mix skews toward specialty chemical manufacturers with peptide synthesis expertise and broad laboratory distributors with dense channel control. Market structure concentrates around two strategic tiers: established European suppliers with dedicated regulatory affairs functions and mid-scale biocatalytic specialists fragmenting traditional solid-phase manufacturing. Competitive positioning hardens through ISO 17025 accreditation timelines and pharmacopeial harmonization investments. M&A activity targets enzymatic platform capabilities while strategic partnerships lock in amino acid precursor supply security.
Within the specialty chemical tier, Hamari Chemicals Ltd. and SIELC Technologies exemplify divergent specialization vectors—peptide synthesis expertise versus chromatography-grade analytical validation protocols. Carl Roth GmbH anchors broad European distribution archetype with channel control across German-speaking research institutions. These three occupy positions that map onto the market's core segmentation: high-purity pharmaceutical grades, analytical validation services, and institutional procurement consolidation.
| Leading Market Players |
|---|
| SIELC Technologies |
| Hamari Chemicals Ltd. |
| VWR AMRESCO |
| Sorachim |
| Carl Roth GmbH |
| Bio Basic Inc. |
| RPI |
| Capot Chemical Co. Ltd |
| PhytoTech Labs |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between CDMO networks and ISO 17025-accredited suppliers lock in both glycylglycine supply access and price visibility across multi-year CRISPR cell line development programs. These arrangements concentrate procurement power among biotechnology firms while insulating qualified vendors from spot market volatility in petrochemical-derived glycine feedstocks.
Pricing Analysis
Certification level creates the primary spread across pharmaceutical-grade, chromatography-grade, and technical-grade tiers. Three-tier pricing structure across premium, standard, and economy levels reflects endotoxin documentation depth and heavy metal traceability rather than purity alone. Pricing pressure stems from enzymatic condensation method adoption lowering production costs for mid-scale biocatalytic specialists. Academic research institutions exhibit highest price sensitivity due to consolidated group purchasing organization negotiations, while injectable-grade CDMOs prioritize supply security over unit cost.
Supply Chain Analysis
Backward integration into glycine precursors represents the critical chokepoint determining manufacturer margin resilience. Production gravity centers on Germany, China, and Switzerland where REACH-registered suppliers and NMPA-qualified domestic manufacturers anchor regional supply. Raw material dependencies encompass methanol and ammonia derivatives, fermentation-capable enzyme platforms, and chromatography resin systems. Single-source vulnerability concentrates in German-speaking European distribution networks controlled by dense channel relationships. Distribution runs through direct sales for pharmaceutical-grade CDMO procurement and specialized laboratory distributors for research institution fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glycylglycine market fragmentation creates entry niches as enzymatic synthesis platforms displace traditional solid-phase manufacturing hierarchies and biocatalytic specialists capture purity tiers previously exclusive to large-scale chemical operations.
For Market Incumbents: Secure amino acid precursor supply through dual-source glycine qualification and blockchain-based batch tracking investments to satisfy EMA ICH Q7 guideline inspections. Defend against enzymatic platform entrants by accelerating ISO 17025 accreditation timelines and locking CDMO networks into multi-year framework agreements with embedded capacity reservation clauses. For New Entrants and Emerging Players: Anchor in Chinese domestic qualification pathways as NMPA import tightening redirects supply chain efforts toward manufacturers with established local regulatory relationships. Target chromatography-grade specialization for HPLC and mass spectrometry applications where analytical validation protocols command premium pricing and foster long-term instrument vendor service contracts. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale biocatalytic specialists retrofitting fermentation infrastructure for enzymatic peptide synthesis platforms. Long-term viability hinges on capturing the transition from solid-phase chemical synthesis to stereoselective biocatalytic condensation. Monitor enzymatic platform patent filings and CDMO network consolidation announcements as inflection indicators for supplier hierarchy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Retrofit | Biocatalytic condensation methods reduce solvent waste profiles and attract sustainability-focused procurement teams. |
| Dual-Source Glycine Qualification | Supply chain transparency back to amino acid precursors satisfies EMA ICH Q7 documentation requirements for injectable formulations. |
| ISO 17025 Accreditation Investment | Third-party laboratory certification accelerates supplier onboarding cycles and unlocks biotechnology firm framework agreements. |
| Blockchain Batch Tracking Deployment | Distributed ledger systems demonstrate supply chain transparency for regulatory inspections and CDMO network compliance. |
| Sachet Configuration Premium Launch | Pre-weighed single-use formats capture pricing power in proteomics and structural biology contamination-sensitive workflows. |
Research Methodology
Desk research of pharmacopeial monograph databases, REACH registration filings, and CDMO capacity announcements preceded structured interviews with peptide synthesis chemists, regulatory affairs directors at biotechnology firms, procurement managers at research institutions, and distribution channel partners. Primary fieldwork validated secondary findings on enzymatic platform adoption rates and supplier qualification timelines. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis and production capacity assessments.
Variance decomposition across product grade tiers, end-use applications, packaging formats, and regional regulatory clusters shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporated CRISPR-based cell line development pipeline expansion, mammalian expression system capacity buildouts, and pharmacopeial harmonization progress between USP, EP, and JP standards.
Decision-makers should treat outputs as directional under assumptions of sustained biotechnology R&D funding and stable amino acid precursor supply; material deviation in glycine feedstock volatility or regulatory timeline compression would warrant model refresh. Practitioners should keep alternative scenarios live as enzymatic synthesis platform maturation and NMPA import policy evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market