
 Global Molecular Biosensors Market | 2026-2036
Global Molecular Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Biosensors Market Foresight
EU MDR is realigning the cost-of-entry calculus for molecular biosensor manufacturers seeking European market access. Abbott Laboratories leverages its vertical integration across diagnostics to sustain compliance advantages under evolving framework demands. Siemens Healthineers anchors its competitive position through deep manufacturing scale in electrochemical and optical platforms. Bio-Rad Laboratories specializes in surface plasmon resonance systems that navigate the new clinical validation thresholds.
Molecular biosensors are analytical devices that detect target molecules through transduction of biological recognition events into quantifiable signals, typically achieving detection limits in the picomolar to femtomolar range via optical, electrochemical, or piezoelectric transducers. Their primary commercial purpose centers on real-time, label-free quantification of biomolecular interactions for diagnostic, environmental, and pharmaceutical applications. Electrochemical biosensors occupy the largest installed base due to cost-efficient manufacturing and compatibility with point-of-care workflows, while nanotechnology-enabled platforms represent the fastest-expanding margin pool as graphene and quantum dot architectures displace conventional electrode materials. Label-free detection systems command premium positioning in drug discovery applications where kinetic binding data accelerates candidate screening timelines.
FDA's evolving guidance on clinical decision support software intersects with EPA monitoring mandates and Japan's PMDA quality management requirements to create a multi-jurisdictional compliance matrix for biosensor developers. ISO 13485 certification and IEC 62304 software lifecycle standards now function as baseline market access credentials rather than competitive differentiators. Stakeholders must monitor how regulatory convergence between FDA's pre-certification pathway and EU MDR's clinical evidence requirements reshapes R&D allocation across transatlantic development pipelines.
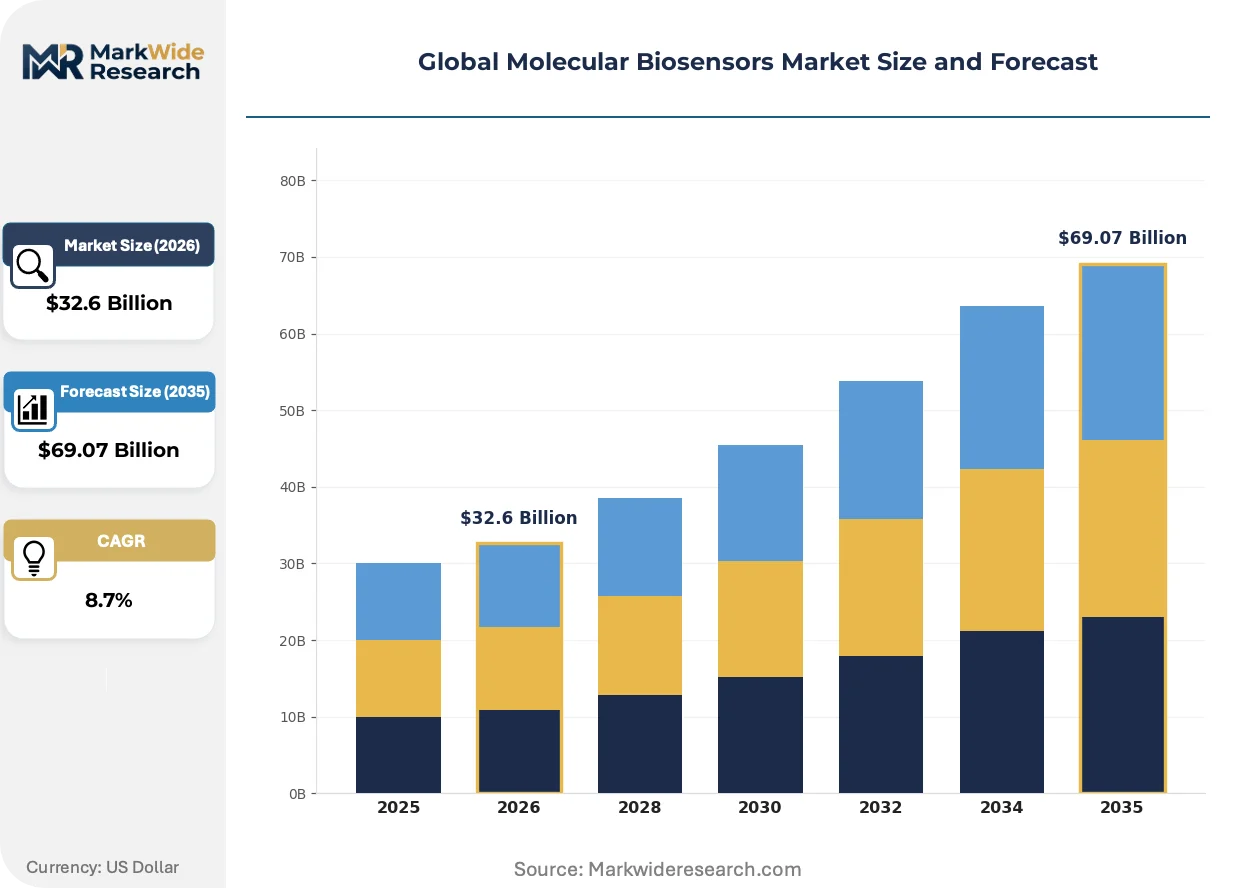
Market Dynamics
Label-free detection architectures are compressing development timelines in pharmaceutical workflows while EU MDR and FDA pre-certification pathways force simultaneous compliance investments across multiple jurisdictions.
Growth Catalysts
- EU AI Act validation mandates:Diagnostic platforms integrating machine learning for clinical decision support face mandatory conformity assessments, creating demand for compliant biosensor hardware that embeds audit-ready signal processing.
- Bioprocess control expansion:Pharmaceutical manufacturers deploy real-time affinity sensors for upstream titer monitoring, replacing offline HPLC assays with continuous glucose and lactate quantification in perfusion bioreactors.
- Graphene electrode commercialization:Carbon nanomaterial foundries in Germany and Japan achieve reproducible wafer-scale production, enabling femtomolar detection limits at electrode costs approaching traditional gold thin-films.
Market Restraints
- Palladium supply concentration:Electrochemical biosensor manufacturing depends on Russian and South African palladium for catalytic electrode coatings, exposing cost structures to geopolitical supply disruptions and LME price volatility.
- ISO 13485 certification timelines:Quality management system audits for IVD-class devices now average 14-18 months, delaying market entry for startups lacking prior notified body relationships.
- Lateral flow immunoassay substitution:Low-cost colorimetric strips dominate infectious disease screening in resource-limited settings, capping price ceilings for electrochemical alternatives in point-of-care tuberculosis and malaria testing.
Strategic Opportunities
- India CDSCO streamlined pathways:The country's 2023 Medical Device Rules create abridged registration for biosensors with prior US FDA or EU MDR approval, opening access to 1.4 billion population diagnostics procurement.
- Environmental contaminant monitoring:Japan's PMDA and EPA-aligned mandates for per- and polyfluoroalkyl substance detection in drinking water create demand for portable electrochemical sensors replacing centralized LC-MS workflows.
- CRISPR-guide RNA integration:Programmable nucleic acid recognition layers combined with field-effect transistor transducers enable single-molecule specificity without PCR amplification infrastructure.
Industry Challenges
- Surface chemistry talent scarcity:Functionalization protocols for thiol-gold and silane-oxide chemistries require specialized expertise concentrated in academic labs, constraining manufacturing scale-up for commercial sensor production.
- IEC 62304 software lifecycle compliance:Biosensor firmware managing real-time signal processing must meet Class C safety-critical standards, forcing redevelopment of legacy embedded codebases for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Biosensors Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $69.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Biosensors, Electrochemical Biosensors, Piezoelectric Biosensors, Thermal Biosensors, Magnetic Biosensors Technology: Label-based, Label-free, Nanotechnology-enabled, Microfluidics, Surface Plasmon Resonance Application: Disease Diagnosis, Environmental Monitoring, Food Safety Analysis, Drug Discovery, Bioprocess Control End User: Research Institutions, Pharmaceutical Developers, Environmental Agencies, Food Testing Labs, Biotechnology Firms |
| Companies Covered | Abbott Laboratories, Bio-Rad Laboratories, F. Hoffmann-La Roche, Medtronic, Siemens Healthineers, Thermo Fisher Scientific, Johnson & Johnson, Nova Biomedical, Molecular Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Biosensors Market Shifts & Advancements
Convergence between nanofabrication and regulatory science is redefining performance benchmarks across detection platforms, with three interconnected developments reshaping competitive positioning.
Quantum dot fluorophores are consolidating position in multiplexed immunoassay panels by enabling single-excitation, multi-emission detection of five or more analytes simultaneously. Diagnostic manufacturers in the United States and Germany integrate these semiconductor nanocrystals into cartridge-based systems for sepsis biomarker panels, compressing assay development timelines from 18 months to under 6 months while reducing instrument complexity.
Japan's PMDA revised software as a medical device guidance now explicitly addresses machine learning-enabled biosensor signal interpretation, requiring locked algorithm versions and prospective validation datasets for any adaptive thresholding. This regulatory clarity accelerates submissions from manufacturers with pre-established quality systems while excluding adaptive AI architectures from near-term approval pathways, favoring deterministic signal processing approaches in glucose and lactate monitoring devices.
Consolidated procurement by US hospital network purchasing organizations now bundles biosensor consumables with analyzer placement contracts, displacing standalone reagent purchasing. Integrated delivery networks in Texas and California negotiate 5-year exclusive supply agreements that lock out competing platform technologies, concentrating vendor relationships and raising switching costs for clinical laboratories seeking to diversify detection methodologies.
Global Molecular Biosensors Market Segmentation
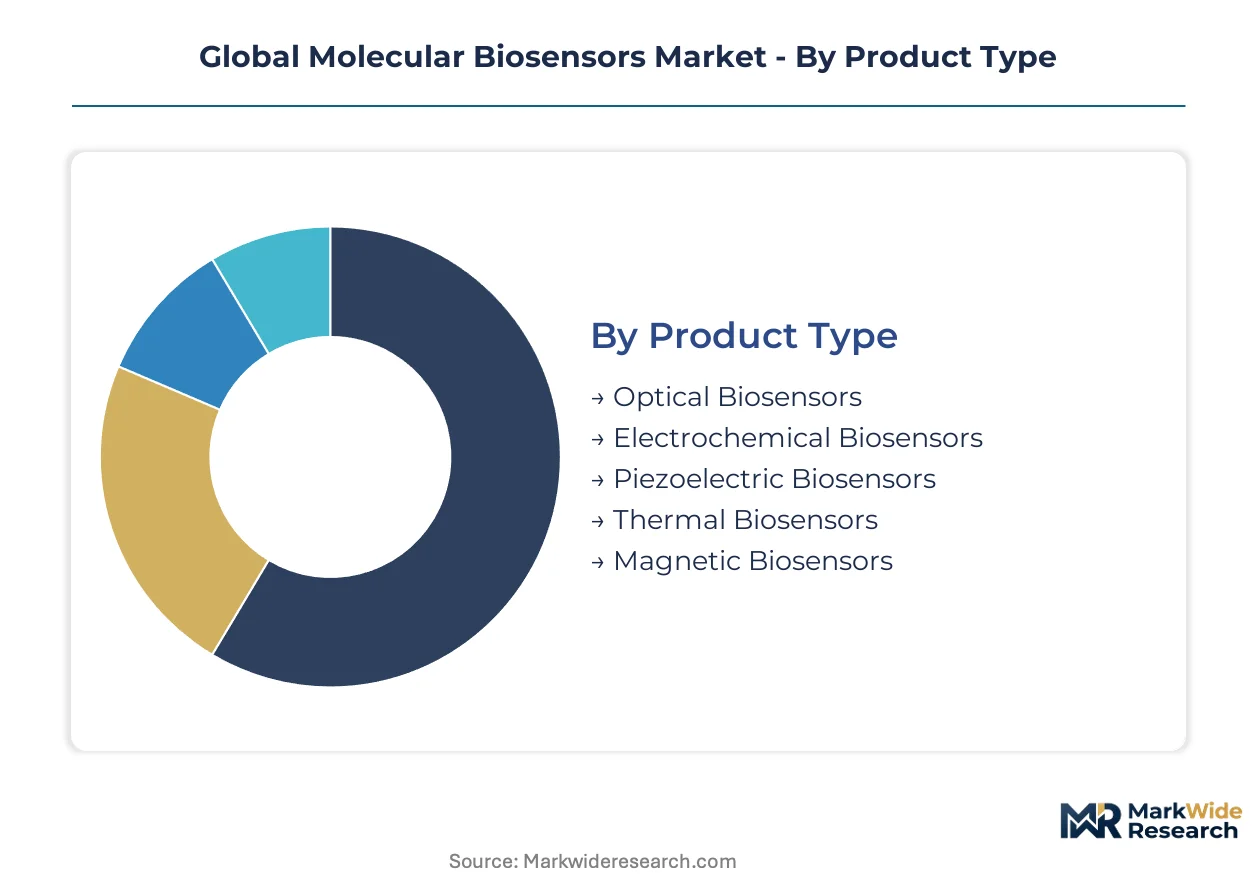
Segmentation in molecular biosensors reflects divergent manufacturing competencies and regulatory pathways. Each dimension—product architecture, detection methodology, use case, and customer type—carries distinct margin profiles and certification burdens that reshape vendor positioning.
Product Type:
Supply concentration in electrode materials and optical component foundries determines which platforms achieve cost-competitive scale.
- Optical Biosensors:These platforms exploit fluorescence, absorbance, or luminescence transduction with detection limits reaching single-molecule sensitivity. Demand clusters in German and US pharmaceutical workflows where surface plasmon resonance imaging accelerates kinetic screening. The EU MDR's clinical validation thresholds favor established optical platforms with extensive predicate device literature.
- Electrochemical Biosensors:Amperometric and potentiometric architectures dominate point-of-care glucose monitoring and lactate quantification through low-cost screen-printed electrodes. Japanese and German manufacturers anchor production scale here, though palladium supply exposure from Russian and South African sources constrains margin stability.
- Piezoelectric Biosensors:Quartz crystal microbalance systems detect mass changes from molecular binding events without labeling requirements.
- Thermal Biosensors:Calorimetric detection measures enthalpy changes from biochemical reactions in process analytical technology applications.
- Magnetic Biosensors:Giant magnetoresistance and spin-valve architectures enable wash-free detection in complex matrices like whole blood.
Electrochemical platforms absorb the bulk of installed capacity; nanotechnology-enhanced optical systems are expanding most quickly.
Technology:
Cost tier stratification separates premium label-free architectures from commoditized colorimetric alternatives.
- Label-based:Enzyme-linked and fluorescent reporter systems rely on secondary signal amplification for sensitivity, trading assay complexity for reagent cost efficiency. These dominate infectious disease screening in India and resource-limited settings where equipment minimization overrides workflow speed.
- Label-free:Direct binding detection via optical or electrochemical transducers eliminates washing steps and reduces assay time from hours to minutes. US and German drug discovery operations absorb the majority of label-free platform deployment, paying premium pricing for real-time kinetic data.
- Nanotechnology-enabled:Graphene, quantum dots, and carbon nanotubes amplify signal-to-noise ratios through enhanced surface area and quantum confinement effects.
- Microfluidics:Lab-on-chip architectures integrate sample preparation, reaction, and detection in disposable cartridges.
- Surface Plasmon Resonance:Evanescent wave-based binding detection remains the gold standard for affinity characterization in bioprocess development.
Label-based technologies command volume leadership through infectious disease applications; label-free platforms climb the fastest on pharmaceutical R&D demand.
Application:
Customer maturity varies sharply across use cases, with regulated diagnostic applications demanding heavier quality system investments than research-oriented deployments.
- Disease Diagnosis:Clinical biosensors for sepsis biomarkers, cardiac troponins, and infectious agents require FDA 510(k) or EU MDR conformity assessment. German hospital procurement networks and US integrated delivery systems concentrate demand here, bundling consumable contracts with analyzer placements.
- Environmental Monitoring:Portable electrochemical sensors for heavy metals, pesticides, and PFAS detection align with EPA mandates and Japan's drinking water quality standards. Field-deployable formats prioritize battery operation and minimal operator training over laboratory precision.
- Food Safety Analysis:Pathogen and allergen detection in supply chain checkpoints drives demand for rapid lateral flow and electrochemical alternatives to culture-based methods.
- Drug Discovery:High-throughput screening and lead optimization workflows consume label-free platforms for binding kinetics and thermodynamic characterization.
- Bioprocess Control:Real-time titer and metabolite monitoring in perfusion bioreactors replaces offline HPLC with continuous electrochemical or optical sensing.
Disease diagnosis captures the majority of revenue; bioprocess control is gaining share fastest on cell therapy manufacturing expansion.
End User:
Procurement sophistication separates institutional buyers with captive regulatory affairs teams from smaller operators dependent on vendor support.
- Research Institutions:Academic laboratories prioritize capital cost minimization and publication-grade sensitivity over regulatory compliance. US NIH and German DFG funding cycles drive instrument refresh timelines, with shared core facilities consolidating purchasing power across departments.
- Pharmaceutical Developers:Large-scale biopharma operations demand validated platforms with audit-ready documentation for GMP environments. Vertical integration into consumable manufacturing characterizes leading deployers, securing supply continuity for clinical trial materials production.
- Environmental Agencies:Government monitoring programs in Japan, Germany, and the US specify ruggedized field instruments with standardized calibration protocols.
- Food Testing Labs:Commercial laboratories serving retail and foodservice chains require high-throughput automation with multi-analyte detection capabilities.
- Biotechnology Firms:Emerging cell and gene therapy developers represent a growing customer segment with specialized bioprocess analytical technology needs.
Pharmaceutical developers account for the largest procurement volume; biotechnology firms represent the steepest expansion trajectory on manufacturing capacity buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biotechnology parks and Japanese medical device special zones concentrate precision manufacturing infrastructure for molecular biosensor production. Tax-advantaged research corridors in Bavaria and Kanagawa Prefecture anchor wafer-scale electrode fabrication and optical component assembly. Public procurement frameworks in these jurisdictions favor domestic suppliers for clinical diagnostic platforms.
United States
Integrated delivery networks in Texas and California negotiate exclusive five-year biosensor supply contracts that lock in analyzer placements. FDA pre-certification pathways for clinical decision support software intersect with EPA monitoring mandates for environmental contaminant detection. Greater Boston hosts sepsis biomarker panel developers integrating quantum dot fluorophores into multiplexed diagnostic cartridges.
Germany
Surface plasmon resonance system manufacturers cluster in Baden-Württemberg and Bavaria to serve pharmaceutical kinetic screening demand. EU MDR conformity assessment requirements favor established optical platforms with extensive predicate device documentation. Jena and Munich host carbon nanomaterial foundries achieving reproducible graphene electrode production at wafer scale.
Japan
PMDA software as a medical device guidance mandates locked algorithm versions for machine learning-enabled signal interpretation. METI-funded initiatives accelerate field-deployable electrochemical sensors for per- and polyfluoroalkyl substance monitoring in drinking water. Kanagawa Prefecture medical device zones concentrate glucose and lactate monitoring platform assembly for domestic hospital procurement.
India
CDSCO's 2023 Medical Device Rules create abridged registration pathways for biosensors with prior US FDA or EU MDR approval. Maharashtra and Gujarat pharmaceutical corridors absorb real-time affinity sensors for upstream bioreactor titer monitoring. Government diagnostics procurement programs for tuberculosis and malaria screening sustain demand for low-cost electrochemical alternatives to lateral flow strips.
China
NMPA quality management requirements for IVD-class devices align with international ISO 13485 standards to accelerate export-oriented manufacturing. Yangtze River Delta biotechnology parks host CRISPR-guide RNA integration projects combining programmable nucleic acid recognition with field-effect transistor transducers. Shanghai and Suzhou concentrate microfluidic cartridge fabrication for point-of-care diagnostic platforms.
Global Molecular Biosensors Market Competitive Landscape
US and German producers anchor the premium diagnostic tier; Japanese and Swiss specialists hold positions in precision optical instrumentation. The vendor base separates into three structural tiers: diversified healthcare conglomerates with captive regulatory affairs teams, mid-scale platform specialists with deep manufacturing scale in electrochemical architectures, and emerging nanotechnology players commercializing graphene and quantum dot transducers. Dominant competitive moves include backward integration into electrode material supply and strategic partnerships with pharmaceutical developers for bioprocess analytical technology co-development.
Within the diversified healthcare conglomerate tier, Abbott Laboratories and Siemens Healthineers exemplify vertical control across diagnostics value chains. Bio-Rad Laboratories occupies a position among mid-scale specialists with concentrated expertise in surface plasmon resonance platforms. These three entities represent distinct strategic archetypes: Abbott Laboratories demonstrates conglomerate-scale compliance navigation under EU MDR and FDA frameworks; Siemens Healthineers anchors electrochemical and optical manufacturing scale; Bio-Rad Laboratories exemplifies focused platform specialization for pharmaceutical kinetic screening workflows.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| Medtronic |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Johnson & Johnson |
| Nova Biomedical |
| Molecular Devices |
| Others |
Supply & Pricing Matrix
Japan's PMDA software-as-a-medical-device guidance gates qualified supply for machine learning-enabled biosensor platforms, restricting premium-tier pricing access to manufacturers with locked-algorithm architectures and prospective validation datasets. This regulatory filter concentrates pricing power among German and Japanese producers with established quality management systems while forcing adaptive AI architectures into lower-margin research-use-only positioning.
Pricing Analysis
Short lead-time premiums of 15-25% apply to electrochemical biosensor electrodes from German and Japanese foundries, while spot inventory of palladium-coated components trades at discounts reflecting Russian supply uncertainty. Contract-based long-term offtake agreements dominate pharmaceutical and diagnostic procurement, with price differentiation driven by ISO 13485 certification tier and after-sales technical support bundling. Cost compression in point-of-care glucose monitoring intensifies because Indian and Chinese manufacturers scale screen-printed electrode production. Biotechnology firms with cell therapy manufacturing buildouts show least price sensitivity, while environmental monitoring agencies in resource-constrained jurisdictions exhibit highest.
Supply Chain Analysis
Workforce availability in precision surface chemistry constrains manufacturing scale-up across German, Japanese, and US production clusters, where thiol-gold functionalization expertise concentrates in academic labs transitioning to commercial foundries. German carbon nanomaterial producers and Japanese optical component manufacturers anchor supply, with raw material dependencies on Russian and South African palladium, Chinese rare earth elements for quantum dot synthesis, and German graphene wafer substrates. Single-source vulnerability in palladium catalytic coatings exposes cost structures to LME price volatility and geopolitical disruption. Distribution runs through integrated delivery network procurement offices in Texas and California, hospital system GPO contracts, and pharmaceutical vertical integration into consumable manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 certification backlog functions as the binding capacity constraint, propping pricing for qualified suppliers while delaying market entry for emerging players lacking notified body relationships.
For Market Incumbents: Deepen backward integration into graphene electrode and quantum dot fluorophore production to secure supply continuity against palladium volatility and rare earth sourcing risk. Expand manufacturing footprint in Kanagawa Prefecture medical device zones to capture Japanese hospital procurement preference. Prioritize locked-algorithm deterministic signal processing architectures over adaptive AI to maintain PMDA compliance advantages.
For New Entrants and Emerging Players: CRISPR-guide RNA field-effect transistor platforms offer a technology-first wedge into nucleic acid detection markets underserved by PCR amplification infrastructure. Target India's CDSCO abridged registration pathway for biosensors with prior FDA or EU MDR approval, where government diagnostics procurement for tuberculosis and malaria screening sustains demand for low-cost electrochemical alternatives. Pursue co-development partnerships with emerging cell therapy developers seeking bioprocess analytical technology for perfusion bioreactor monitoring.
For Investors and Strategic Acquirers: FDA pre-certification pathway convergence with EU MDR clinical evidence requirements is the leading indicator that regulatory arbitrage opportunities are narrowing, favoring platforms with multi-jurisdictional validation investments. Over the projection horizon, vertically integrated mid-scale specialists with concentrated electrochemical manufacturing scale and established pharmaceutical relationships present acquisition targets with defensive positioning. Watch graphene electrode cost parity with gold thin-films as the inflection signal for nanotechnology-enabled platform margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Materials | Captive graphene and palladium coating production insulates German and Japanese manufacturers from supply disruption. |
| EU MDR Conformity Assessment Investment | Extensive predicate device documentation accelerates optical platform approvals for surface plasmon resonance systems. |
| Bioprocess Analytical Technology Co-Development | Pharmaceutical partnerships for real-time titer monitoring lock in consumable supply agreements for perfusion bioreactors. |
| Locked-Algorithm Software Architecture | Deterministic signal processing meets PMDA guidance for machine learning-enabled glucose and lactate devices. |
| India CDSCO Registration Pathway Utilization | Abridged approval for FDA-cleared biosensors opens government procurement for 1.4 billion population diagnostics. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA software guidance releases, and ISO 13485 certification databases, complemented by interviews with biomedical engineers, hospital GPO contracts managers, pharmaceutical bioprocess analytical technology leads, and regulatory affairs directors at IVD manufacturers. Secondary validation drew from EPA monitoring mandates, Japan's drinking water quality standards, and clinical diagnostic procurement records. Bottom-up platform deployment estimates triangulated against top-down market sizing by detection methodology and end-use application.
Segmented outputs by product architecture, detection technology, use case, and customer type fed into analytical framework calculations across the projection horizon. Modeled dimensions included regulatory certification tier, pharmaceutical versus diagnostic end-use, and geographic procurement sophistication. CAGRs derived from installed base expansion rates, replacement cycle timing, and emerging application penetration curves. Forecast inputs incorporated graphene electrode cost trajectories, palladium price volatility scenarios, and CRISPR-guide RNA integration timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, breakthrough nanofabrication techniques, and geopolitical trade restrictions on critical materials. Forecasts reflect assumptions about certification timeline stability and continued pharmaceutical R&D spending. A small set of named triggers warrants ongoing watch: FDA pre-certification pathway expansion, EU AI Act enforcement intensity, and palladium supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Biomarker Detection Systems Market