
 Global Textile Market | 2026-2036
Global Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Market Outlook
Buyer concentration among fast-fashion retailers is hardening as Inditex and VF Corporation consolidate supplier rosters toward vertically integrated partners. Toray Industries leverages its carbon fiber expertise to dominate technical textile supply for automotive and aerospace composites. Lenzing Group anchors the European market through Tencel lyocell production, sustaining premium positioning against conventional viscose alternatives.
Textiles encompass woven, knitted, and non-woven structures manufactured from natural, synthetic, or regenerated fibers with specifications ranging from 10 to 1,000 denier for applications requiring tensile strength, moisture management, or thermal resistance. Polyester fibers lead global volume due to cost scalability and performance adaptability across apparel and industrial applications, while specialty fibers in healthcare non-wovens command superior margin pools driven by surgical gown and filtration demand. Natural fibers face structural constraints from land and water intensity, yet cotton retains entrenched positions in premium apparel segments where brand positioning depends on fiber provenance.
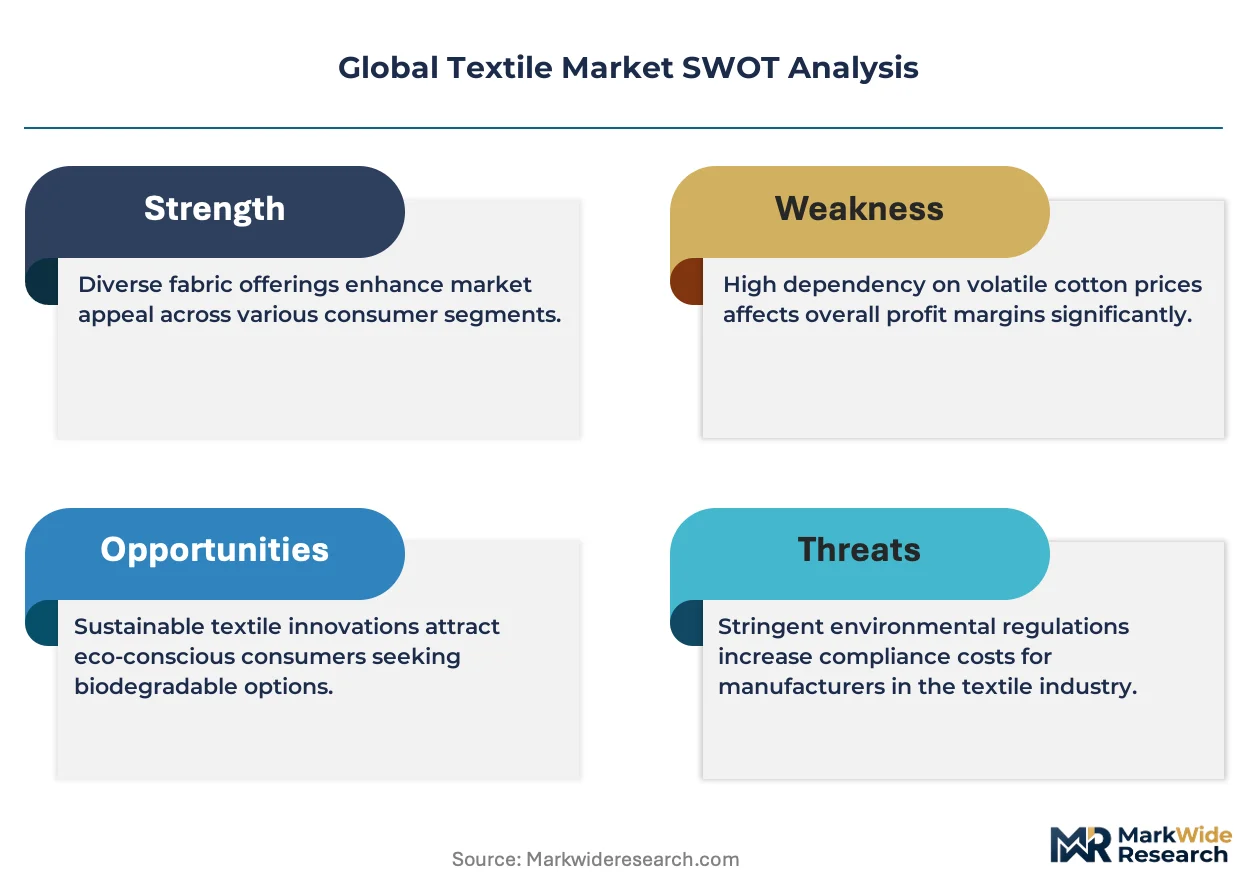
REACH and the EU Green Deal restrict hazardous chemical inputs across European textile supply chains, compelling reformulation of dyes and finishing agents to maintain market access. China's MEE enforces wastewater discharge standards that raise compliance costs for dyeing and finishing operations in Zhejiang and Jiangsu provinces. India's BIS certification requirements for textile quality and labeling create formalization pressure on unorganized sector producers. Stakeholders must monitor regulatory divergence between EU chemical restrictions and emerging economy enforcement capacity as a determinant of competitive positioning in technical textile segments.
Market Dynamics
Automotive electrification is redrawing fiber specifications as electric vehicle interiors demand lighter, flame-resistant technical textiles that replace conventional materials across seating, headliners, and battery compartment shielding.
Growth Catalysts
- EU Green Deal textile mandates:Circular economy requirements for fiber recycling are forcing capital deployment into chemical and mechanical recycling infrastructure across European supply chains.
- Technical textile penetration in EVs:Battery thermal management systems require non-woven aramid and carbon fiber composites that withstand thermal runaway events.
- Apparel manufacturing relocation to India:Gujarat and Tamil Nadu industrial corridors are capturing volume shifts from coastal China through dedicated textile parks and duty advantages.
Market Restraints
- Petrochemical feedstock volatility:Polyester staple fiber production remains tethered to paraxylene and MEG price swings that compress margin predictability for synthetic fiber producers.
- Water intensity in natural fiber cultivation:Cotton farming in Punjab and Maharashtra faces groundwater depletion constraints that limit acreage expansion regardless of price signals.
- REACH chemical compliance costs:European dye and finishing agent reformulation to eliminate restricted substances adds 15-25% to chemical input costs for exporters serving EU markets.
Strategic Opportunities
- Healthcare non-woven underpenetration in Southeast Asia:Surgical gown and filtration demand in Vietnam and Indonesia lags per-capita hospital bed ratios, creating import substitution potential for regional producers.
- Digital textile printing adoption:Waterless pigment ink systems are converging with AI-driven design-to-production workflows that compress sampling cycles from weeks to days.
- India PLI scheme for man-made fibers:Production-linked incentives for polyester and nylon filament yarn are attracting greenfield capacity in technical textile corridors.
Industry Challenges
- Skilled technician scarcity in advanced weaving:Jacquard and rapier loom operation requires training programs that outpace vocational education output in emerging manufacturing hubs.
- Legacy dyehouse effluent systems:Zero liquid discharge retrofitting demands capital outlays that strain unorganized sector balance sheets in Surat and Tiruppur clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Market |
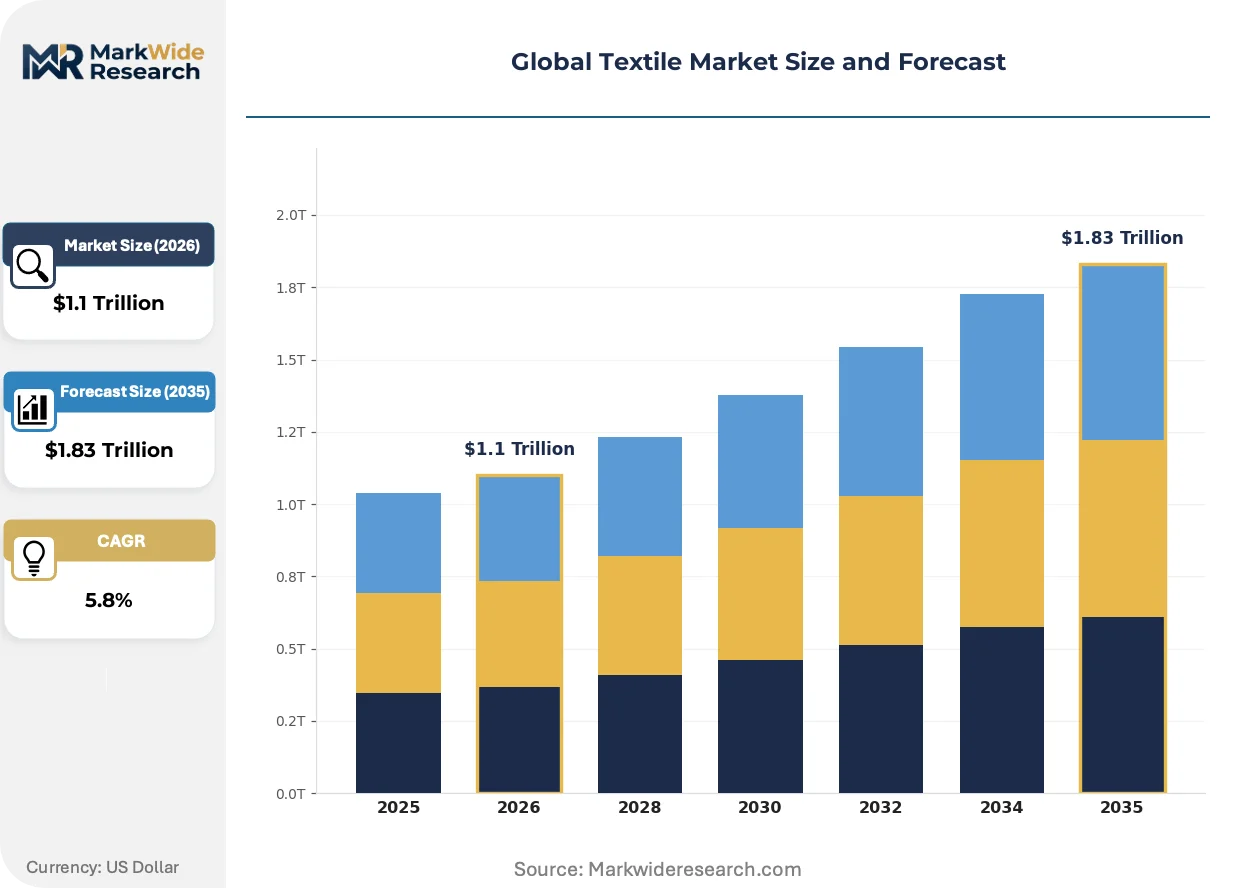
| Market Size in 2026 | $1.1 Trillion |
| Market Size in 2035 | $1.83 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Silk, Wool, Polyester Application: Apparel, Home Textiles, Industrial Textiles, Non-woven Fabrics Type of Fiber: Natural Fibers, Synthetic Fibers, Blended Fibers, Specialty Fibers End User: Fashion Industry, Automotive, Healthcare, Furniture |
| Companies Covered | Aditya Birla Group, VF Corporation, Inditex, Arvind Limited, Lenzing Group, Toray Industries, Shandong Ruyi Technology Group, DuPont, Reliance Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Market Strategic Shifts
Digitalization and material science convergence are compressing product development timelines while regulatory chemical restrictions are forcing formulation innovation across finishing and coating applications.
Lyocell solvent-spinning technology is expanding into denim and activewear segments as brands seek cotton alternatives with lower water footprints. Inditex and H&M Group are accelerating adoption through dedicated fiber procurement commitments. This expansion is displacing conventional viscose in premium casualwear as supply agreements with Lenzing and Birla Cellulose secure volume allocation.
REACH authorization requirements for chromium-based dyes and PFAS-containing water repellents are forcing reformulation across European-facing supply chains. Dye manufacturers in Zhejiang and Jiangsu provinces are investing in bio-based indigo and silicone-free durable water repellent chemistry to maintain market access. Technical outerwear and performance apparel segments bear the highest compliance burden, with lead times extending 6-9 months for chemistry validation.
Direct-to-garment digital printing is compressing minimum order quantities and sampling cycles for fast-fashion buyers. Screen printing capacity in Bangladesh and Vietnam faces displacement as on-demand production models gain traction among online-native brands. This shift concentrates in European and North American markets where inventory risk reduction outweighs unit cost premiums for small-batch production.
Global Textile Market Segmentation
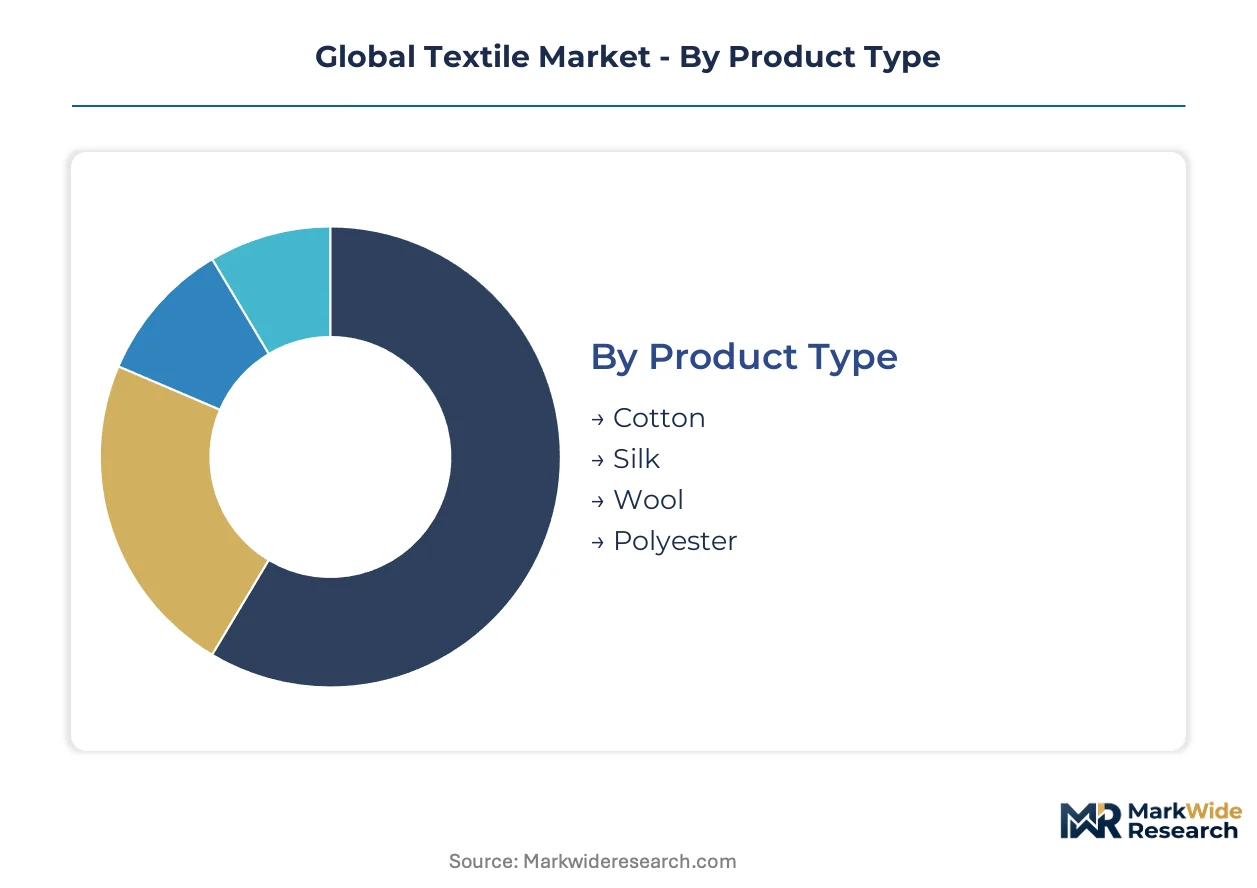
Textile procurement patterns diverge sharply across fiber chemistry and end-use specifications, with automotive and healthcare buyers demanding certified technical performance while fashion retailers prioritize cost scalability and dye compatibility. Segmentation clarity enables suppliers to align capacity investments with margin pools that vary by an order of magnitude between commodity apparel and medical-grade non-wovens.
Product Type:
Buyers in this category separate by price elasticity and performance requirements, with premium positioning hinging on fiber provenance and processing traceability.
- Cotton:Cellulosic staple fiber ranging from 20 to 40 micron diameter, valued for moisture absorption and dye affinity. Demand concentrates in Gujarat and Tamil Nadu spinning mills serving Inditex and H&M Group sourcing offices, constrained by groundwater depletion in Punjab and Maharashtra growing regions that limits acreage expansion regardless of price signals.
- Polyester:Thermoplastic polymer extruded into continuous filament or staple form with denier specifications from 0.5 to 20, offering dimensional stability and chemical resistance. Automotive upholstery buyers in Germany and South Korea are expanding procurement of technical polyester textiles for electric vehicle interiors, displacing conventional materials across seating and headliner applications.
- Silk:Natural protein fiber produced by Bombyx mori silkworms, characterized by triangular prism structure yielding distinctive luster. Surat and Mysore clusters dominate reeling and weaving, serving luxury apparel segments in France and Italy where fiber provenance commands certification premiums.
- Wool:Keratin-based animal fiber with crimped structure providing natural elasticity and thermal insulation. Australian Merino clips supply premium outerwear manufacturers, facing competition from synthetic thermal layers in performance apparel segments.
Polyester leads volumes today; cotton is gaining share fastest in sustainable fiber commitments despite structural supply constraints.
Application:
Margin structure in this category correlates with technical specification burden, from commodity apparel cut-and-sew to certified medical barrier properties.
- Apparel:Cut-and-sewn garments spanning woven shirting, knitted activewear, and denim categories. Bangladesh and Vietnam export processing zones concentrate fast-fashion volume, while Portugal and Romania mills capture near-shoring demand from EU retailers seeking compressed lead times.
- Industrial Textiles:High-tenacity fabrics for filtration, geotextiles, and composite reinforcement requiring tensile strength specifications from 200 to 2,000 N/cm. Toray Industries leverages carbon fiber expertise to dominate technical textile supply for automotive and aerospace composites, with battery thermal management systems driving aramid and carbon fiber composite demand for electric vehicle battery compartment shielding.
- Home Textiles:Bed linen, upholstery, and decorative fabrics where thread count and finishing chemistry determine positioning. Pakistani and Turkish mills compete on greige goods supply to European converters, with digital printing adoption compressing sampling cycles for seasonal collections.
- Non-woven Fabrics:Bonded fiber structures manufactured via spunbond, meltblown, or needle-punch processes without yarn formation. Healthcare non-woven underpenetration in Vietnam and Indonesia lags per-capita hospital bed ratios, creating import substitution potential for regional producers targeting surgical gown and filtration demand.
Apparel dominates value today; industrial textiles are expanding most quickly on electrification and infrastructure investment.
Type of Fiber:
Supply concentration in this category determines cost predictability, with petrochemical feedstock exposure creating margin volatility distinct from agricultural fiber cycles.
- Synthetic Fibers:Man-made polymers including polyester, nylon, and acrylic derived from petrochemical feedstocks. Paraxylene and MEG price swings compress margin predictability for producers, though India's PLI scheme for man-made fibers is attracting greenfield capacity in technical textile corridors.
- Natural Fibers:Plant and animal fibers including cotton, wool, silk, and bast fibers requiring cultivation or animal husbandry. Land and water intensity constrains structural expansion, yet cotton retains entrenched positions in premium apparel segments where brand positioning depends on fiber provenance.
- Blended Fibers:Intimate mixtures of natural and synthetic components optimizing cost-performance tradeoffs, typically 65/35 or 80/20 compositions. Tiruppur and Ludhiana knitting clusters favor cotton-polyester blends for durability and dye consistency in high-volume T-shirt production.
- Specialty Fibers:High-performance materials including aramid, carbon fiber, and ultra-high molecular weight polyethylene for ballistic and aerospace applications. Lyocell solvent-spinning technology is expanding into denim and activewear segments as brands seek cotton alternatives with lower water footprints.
Synthetic fibers lead volumes today; specialty fibers show the steepest expansion trajectory on technical textile penetration.
End User:
Certification requirements in this category fragment supplier bases, with medical and automotive buyers demanding traceability systems absent from furniture procurement.
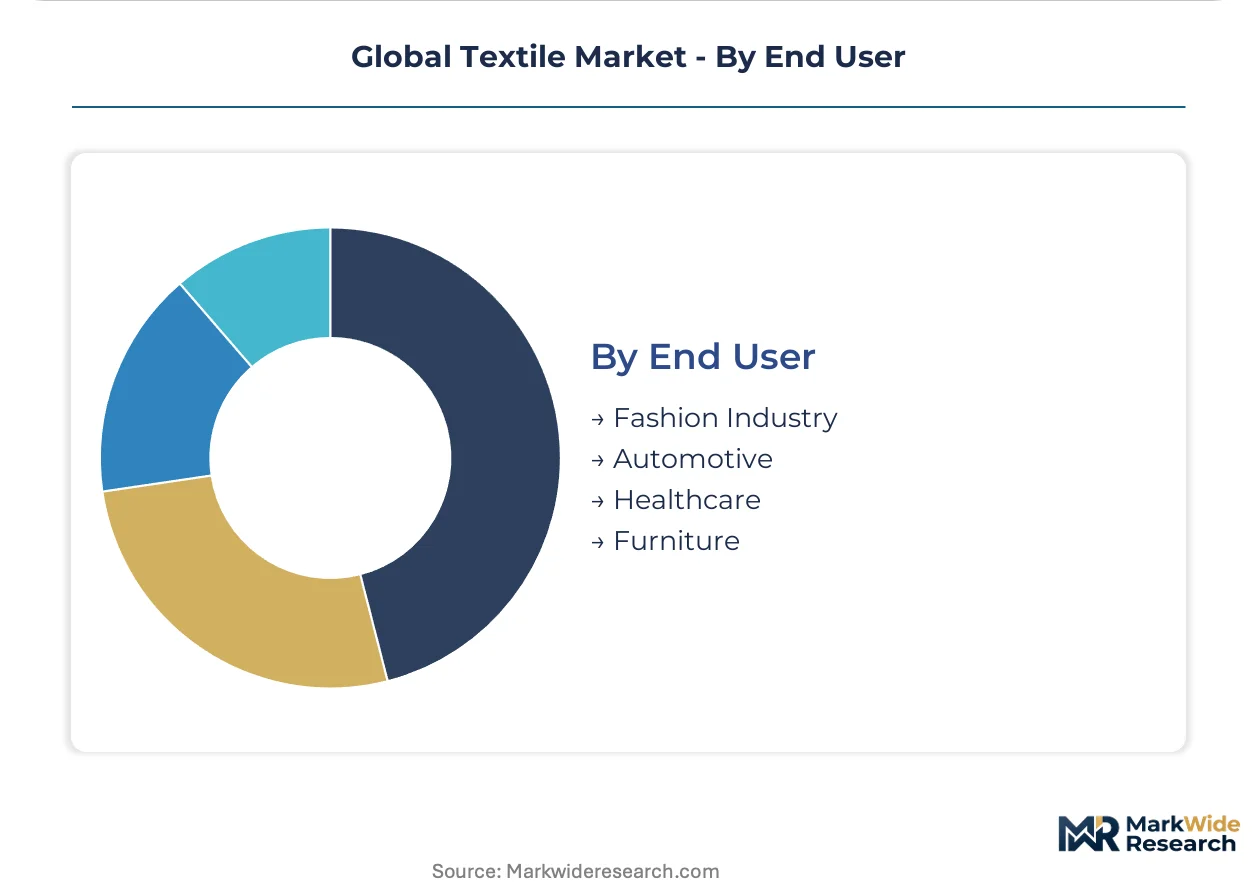
- Fashion Industry:Apparel brands and retailers spanning fast-fashion, premium, and luxury positioning. Buyer concentration among fast-fashion retailers is hardening as Inditex and VF Corporation consolidate supplier rosters toward vertically integrated partners with captive spinning and dyeing capacity.
- Healthcare:Medical device and hospital procurement of surgical gowns, drapes, and filtration media requiring biocompatibility certification. REACH and EU Green Deal chemical restrictions are forcing reformulation of dyes and finishing agents to maintain European market access, with lead times extending for chemistry validation in technical outerwear and performance apparel segments.
- Automotive:Tier-1 seating and interior suppliers specifying flame resistance, abrasion durability, and lightweighting properties. Battery thermal management systems in electric vehicles demand non-woven aramid and carbon fiber composites that withstand thermal runaway events, redrawing fiber specifications across seating, headliners, and battery compartment shielding.
- Furniture:Upholstery and decorative fabric buyers prioritizing cost efficiency and color consistency over technical performance. China's MEE enforces wastewater discharge standards that raise compliance costs for dyeing and finishing operations in Zhejiang and Jiangsu provinces serving this segment.
Fashion industry leads procurement volumes today; healthcare is climbing the fastest on infection control investment and aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dominance in polyester staple fiber output contrasts with India's accelerating capture of apparel cut-and-sew volume as manufacturing corridors in Gujarat and Tamil Nadu expand capacity. The EU Green Deal's circular economy mandates are forcing divergent compliance investments across European and Asian supply bases.
China
Automotive electrification is driving technical textile procurement from Zhejiang and Jiangsu dyeing clusters as EV battery compartment shielding specifications tighten. The MEE enforces wastewater discharge standards that raise compliance costs for finishing operations serving export markets. Shaoxing's chemical fiber producers are retrofitting effluent systems to maintain European market access under REACH restrictions.
India
Gujarat and Tamil Nadu industrial corridors are absorbing apparel manufacturing shifts from coastal China through dedicated textile parks and duty advantages. The PLI scheme for man-made fibers is attracting greenfield polyester and nylon filament capacity in technical textile zones. Tiruppur's knitting clusters face zero liquid discharge retrofitting demands that strain unorganized sector balance sheets.
Germany
Automotive upholstery buyers in Stuttgart and Munich are expanding technical textile procurement for electric vehicle interiors requiring flame-resistant specifications. The EU Green Deal's fiber recycling mandates are accelerating chemical and mechanical recycling infrastructure deployment across Bavarian supply chains. Baden-Württemberg's automotive tier-1 suppliers dominate battery thermal management system sourcing.
United States
Healthcare non-woven demand is climbing on infection control investment and aging demographics, with surgical gown procurement concentrating in Southeast hospital systems. The EPA regulates industrial wastewater from textile finishing operations under Clean Water Act permits. North Carolina's technical textile producers supply filtration media to domestic pharmaceutical manufacturers.
Vietnam
Export processing zones in Ho Chi Minh City and Binh Duong are capturing fast-fashion volume as Bangladesh faces lead time compression from digital printing displacement. The country's national quality regulator enforces labeling standards that formalize previously informal sector producers. Screen printing capacity faces structural pressure from on-demand production models gaining traction among online-native brands.
Global Textile Market Competitive Environment
East Asian producers anchor the synthetic fiber tier; European specialists hold regenerated cellulosic positioning through solvent-spinning technology. The vendor base separates into petrochemical-integrated conglomerates, forest-product diversified groups, and automotive-aerospace technical textile pure-plays. Three archetypes dominate: feedstock-backward integrated polyester giants, lyocell technology licensors, and carbon fiber composite specialists. Capacity expansion and strategic fiber procurement commitments represent the dominant competitive moves as brands secure volume allocation.
Among diversified industrial conglomerates, Reliance Industries and Aditya Birla Group occupy positions spanning petrochemical feedstock through finished fiber production. Toray Industries exemplifies the technical textile specialist archetype, leveraging carbon fiber expertise for automotive and aerospace composite supply. Lenzing Group anchors the European market through Tencel lyocell production, representing the regenerated cellulosic tier against conventional viscose alternatives. These three companies illustrate the geographic and technological segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Aditya Birla Group |
| VF Corporation |
| Inditex |
| Arvind Limited |
| Lenzing Group |
| Toray Industries |
| Shandong Ruyi Technology Group |
| DuPont |
| Reliance Industries |
| Others |
Value Chain & Pricing Dynamics
Fast-fashion retailer procurement concentration toward vertically integrated suppliers with captive spinning and dyeing capacity anchors a contract-based long-term offtake pricing model across global textile supply chains. This buyer archetype consolidation compresses margin pools for fragmented converters while rewarding scale-backed fiber producers with volume allocation security.
Pricing Analysis
Capacity additions in India under the PLI scheme for man-made fibers are reshaping price floors for polyester and nylon filament yarn across Asian supply chains. Three-tier pricing structure across premium, standard, and economy levels separates certified recycled fiber from conventional virgin grades from unbranded commodity output. Price differentiation hinges on REACH compliance certification and volume scale commitments, with European-facing exporters bearing 15-25% chemical input cost premiums. Cost compression in commodity apparel tiers is intensifying because digital printing adoption compresses minimum order quantities and sampling cycles.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions and Panama Canal constraints is amplifying landed cost differentials between Asian production hubs and European end-markets. Supply concentrates in China for polyester staple fiber, India for cotton spinning and apparel cut-and-sew, and Bangladesh for woven garment assembly. Raw material dependencies draw from paraxylene and MEG for synthetic fiber production, cotton lint from Punjab and Maharashtra growing regions, and carbon fiber precursor from acrylonitrile feedstocks. Single-source vulnerability in Zhejiang and Jiangsu dyeing clusters exposes European exporters to REACH compliance disruption. Distribution runs through vertically integrated retail supply chains, third-party logistics providers, and direct mill-to-brand relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal circular economy mandates impose capital-intensive recycling infrastructure requirements that Indian and Vietnamese producers can defer through delayed regulatory enforcement capacity.
For Market Incumbents: Extend backward integration into petrochemical feedstock or fiber recycling infrastructure to defend margin position against emerging mechanical and chemical recycling specialists. Capture PLI scheme incentives in Gujarat and Tamil Nadu technical textile corridors before greenfield capacity saturates filament yarn pricing. Prioritize REACH-compliant chemistry validation to maintain European market access as ECHA authorization requirements tighten. For New Entrants and Emerging Players: Launch via direct-to-garment digital printing partnerships with online-native brands seeking compressed sampling cycles and reduced inventory risk. Target healthcare non-woven penetration gaps in Vietnam and Indonesia where per-capita hospital bed ratios lag surgical gown and filtration demand. Pursue import substitution positioning for regional producers against incumbent Chinese medical-grade non-woven suppliers. For Investors and Strategic Acquirers: Automotive tier-1 seating suppliers are the most active acquirer in this space, consolidating technical textile capabilities for electric vehicle battery thermal management and flame-resistant interior specifications. Acquire solvent-spinning lyocell technology licensors or carbon fiber composite specialists with certified aerospace and automotive supply relationships. Watch EV battery thermal runaway safety standard adoption as the inflection indicator for aramid and carbon fiber composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recycling | EU Green Deal mandates force capital deployment into chemical and mechanical recycling infrastructure across Bavarian supply chains. |
| PLI Scheme Capacity Expansion | India's production-linked incentives attract greenfield polyester and nylon filament investment in Gujarat technical textile zones. |
| REACH Compliance Certification | ECHA authorization requirements for chromium-based dyes and PFAS-containing repellents extend chemistry validation lead times for exporters. |
| Digital Textile Printing Adoption | Waterless pigment ink systems compress sampling cycles from weeks to days for fast-fashion buyers in European markets. |
| Healthcare Non-Woven Regional Production | Vietnam and Indonesia import substitution potential targets surgical gown demand gaps against per-capita hospital bed ratios. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with spinning mill procurement directors, automotive tier-1 supplier engineers, fast-fashion sourcing office managers, and healthcare non-woven distribution channel partners combine with secondary validation from customs and trade data, BIS certification registries, ECHA authorization databases, and SEC filings from diversified fiber producers. Triangulation across these sources reconciles capacity utilization estimates with downstream demand signals.
Historical trendline analysis of fiber production volumes, trade flows, and end-use consumption patterns establishes baseline growth trajectories across the projection horizon. The analytical framework segments by fiber chemistry, application specification, end-use vertical, and regional production cluster, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules. Key forecast inputs include EV battery thermal management system adoption curves, REACH chemical restriction implementation timelines, and PLI scheme disbursement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock price volatility, EU-India regulatory enforcement divergence, and groundwater depletion constraints in Punjab cotton growing regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Waterproof Socks Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Smart Textile Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Quilt Market
Textile Innovations
Textile Felt Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
GCC Textile Market