
 Global Text to Speech (TTS) Software Market | 2026-2036
Global Text to Speech (TTS) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Text to Speech (TTS) Software Market Foresight
Automotive infotainment is shifting from basic navigation prompts to conversational voice assistants that manage climate, media, and scheduling. Google LLC leverages its Android Automotive platform to embed neural TTS across multiple OEM dashboards. Amazon Web Services, Inc. anchors enterprise call center deployments through Polly's integration with Alexa for Business. Microsoft Corporation dominates developer ecosystems by extending Azure Speech Services into Teams and Edge browser accessibility workflows.
Text to speech software converts written text into synthesized speech output using acoustic models, vocoders, and linguistic processors operating at sample rates from 16 kHz to 48 kHz. The technology serves commercial purposes ranging from automated customer service to assistive reading tools for visually impaired users. Cloud-based deployment leads in revenue contribution because hyperscalers bundle TTS APIs with storage and compute contracts. Deep learning and neural networks represent the fastest-expanding technology category as end-to-end models reduce artifacting and enable speaker cloning with under ten minutes of training audio. Embedded deployment remains niche but carries higher per-unit margins in aerospace and defense applications where connectivity is restricted.
The European Union's AI Act mandates disclosure obligations for synthetic media including TTS outputs, while the FDA scrutinizes voice-based diagnostic tools under digital health software guidelines. China's SAMR enforces GB standards for intelligent speech products sold to government agencies and educational institutions. Stakeholders must monitor how divergent disclosure regimes fragment model training datasets and complicate cross-border API delivery.
Market Dynamics
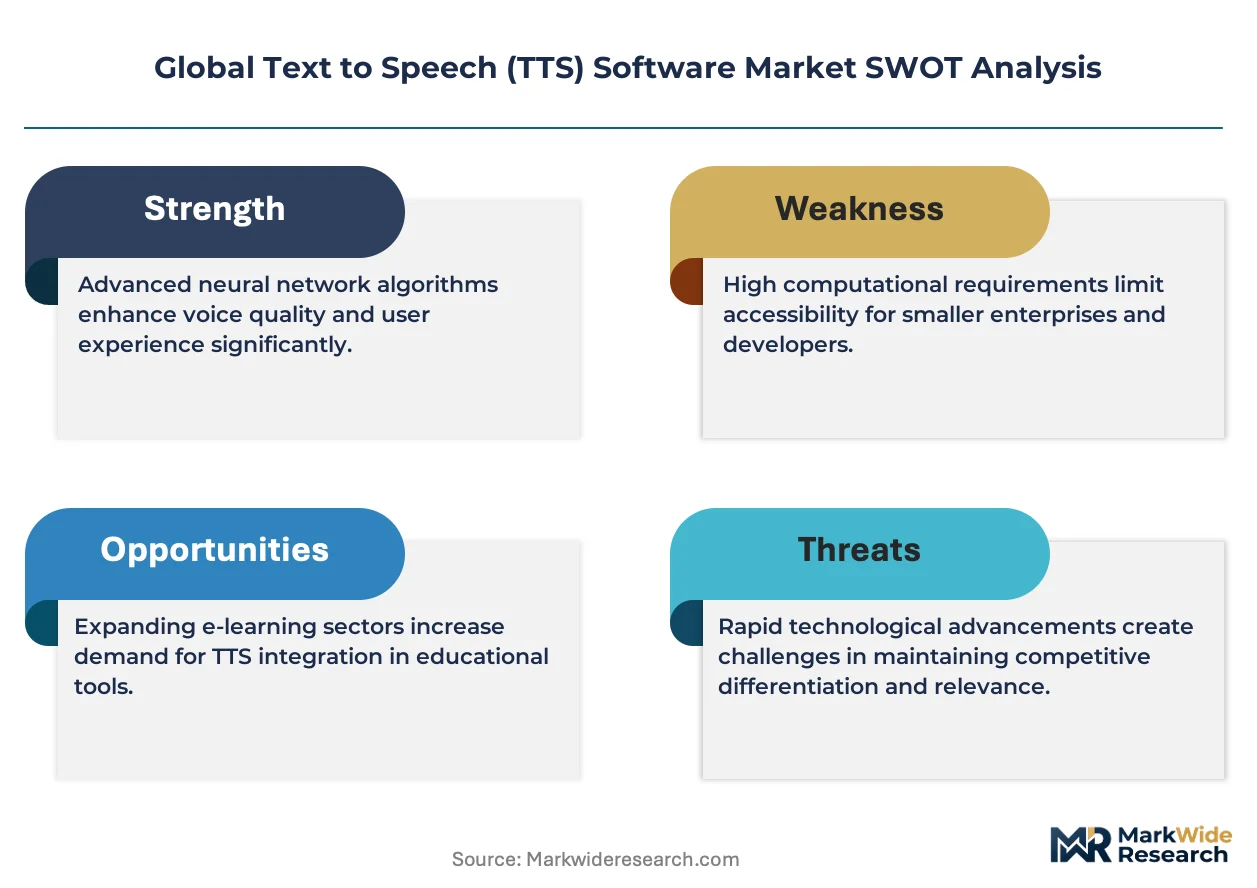
Neural TTS architectures are compressing development cycles from months to weeks, forcing legacy statistical parametric systems into obsolescence while hyperscalers lock in developer ecosystems through API bundling.
Growth Catalysts
- EU AI Act disclosure mandates:Synthetic voice labeling requirements are accelerating enterprise procurement of auditable TTS pipelines for customer-facing applications.
- Automotive voice assistants:OEMs in Germany, the United States, and China are embedding conversational TTS into infotainment stacks to differentiate connected vehicle experiences.
- Neural vocoder advances:End-to-end waveform generation is eliminating concatenative artifacts, opening clinical and entertainment use cases previously blocked by quality thresholds.
Market Restraints
- GPU compute cost volatility:Training large-scale TTS models requires sustained access to NVIDIA A100/H100 clusters, concentrating capability among cloud-backed vendors.
- FDA digital health validation:Voice-based diagnostic tools face 12-18 month clearance timelines, delaying revenue recognition for healthcare-focused developers.
- Substitution by human voice actors:Premium audiobook and animation studios retain organic talent for emotional nuance that neural models still miss.
Strategic Opportunities
- India's assistive technology gap:Low penetration of screen readers and literacy tools among regional language speakers creates whitespace for localized TTS deployment.
- Edge AI convergence:On-device neural inference is enabling offline TTS for aerospace and defense contractors operating in connectivity-denied environments.
- China SAMR procurement standards:Mandatory GB compliance for government and educational speech products is channeling public sector demand toward certified domestic and international suppliers.
Industry Challenges
- Phonetic annotation talent scarcity:Linguists capable of curating training corpora for low-resource languages command premium compensation, constraining model expansion.
- Cross-border data localization:Divergent requirements between EU GDPR, China PIPL, and US CLOUD Act are fragmenting training datasets and complicating multi-tenant API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Text to Speech (TTS) Software Market |
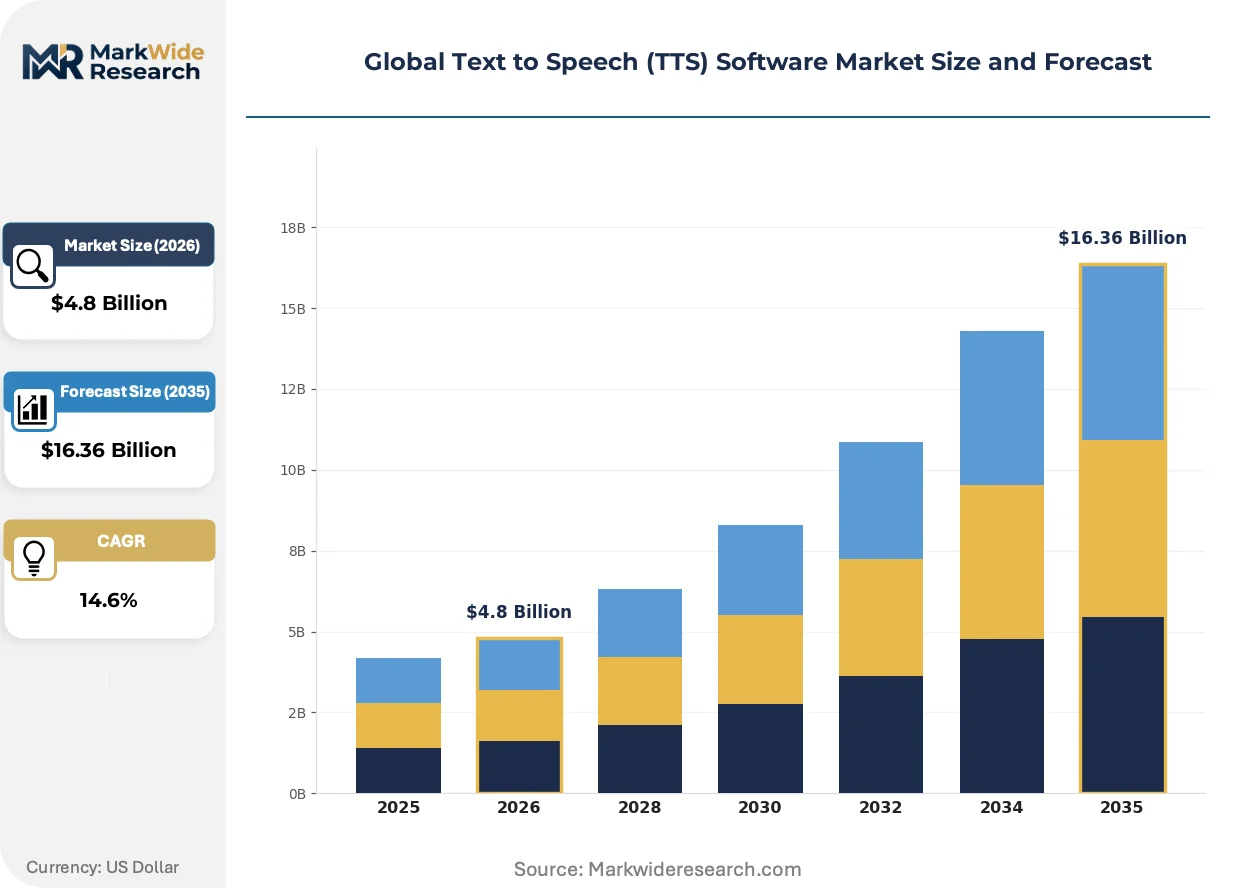
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Embedded Application: Virtual Assistants, E-Learning, Accessibility Tools, Call Centers, Automotive Infotainment Technology: Concatenative Synthesis, Parametric Synthesis, Deep Learning, Neural Networks End User: Enterprises, Educational Institutions, Content Creators, Telecom Operators, Government Agencies |
| Companies Covered | Google LLC, Amazon Web Services, Inc., Microsoft Corporation, Apple Inc., IBM Corporation, Baidu Inc., iFlytek Co., Ltd., Nuance Communications, Inc., ReadSpeaker B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Text to Speech (TTS) Software Market Shifts & Advancements
End-to-end neural synthesis is collapsing the traditional pipeline of text analysis, prosody prediction, and waveform generation into single-model architectures that learn directly from raw audio.
Diffusion-based vocoders are consolidating acoustic modeling and waveform generation into unified frameworks that reduce inference latency by half. Automotive OEMs in Stuttgart and Detroit are piloting these systems for real-time navigation prompts. The compression of pipeline stages is consolidating vendor differentiation around data scale rather than algorithmic novelty.
The EU AI Act's synthetic media disclosure obligations are forcing platform operators to embed provenance metadata into TTS outputs. Healthcare developers seeking CE marking must document training data sourcing and bias testing. German automotive suppliers are responding by segregating EU-facing voice models from other deployments to ensure compliance traceability.
Enterprise buyers are unbundling TTS from bundled cloud contracts and negotiating standalone API pricing based on character volume commitments. Call center operators in the United States are leading this shift, pressuring hyperscalers to disclose per-inference cost structures. The procurement pattern is most visible in financial services, where compliance teams demand auditable spend allocation across voice channels.
Global Text to Speech (TTS) Software Market Segmentation
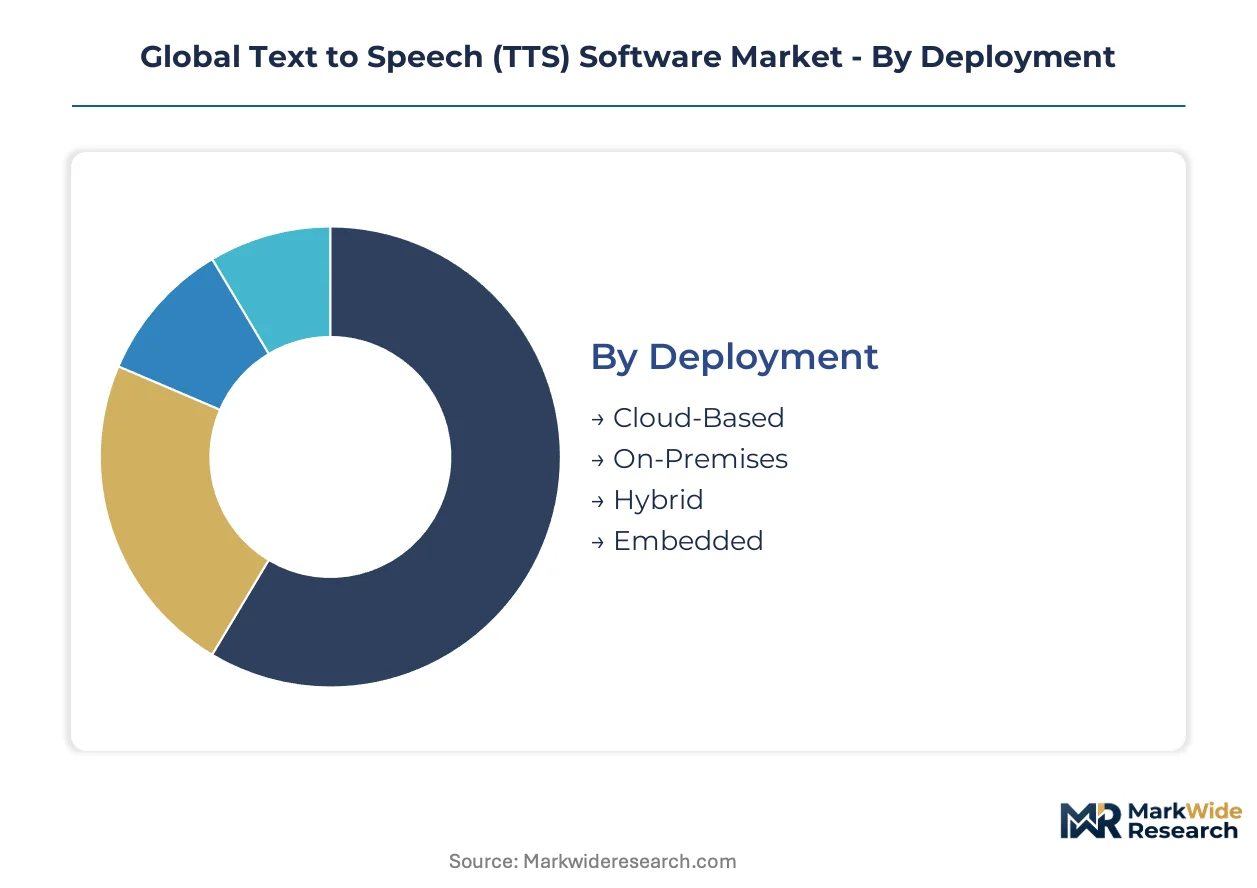
TTS software segmentation reveals how deployment constraints, application requirements, and regulatory exposure fragment procurement patterns. Buyers select configurations based on latency tolerance, data sovereignty mandates, and the specific acoustic quality thresholds their use cases demand.
Deployment:
Cloud-based deployments face the lightest certification burden, requiring only SOC 2 and ISO 27001 attestation, while embedded systems in aerospace and defense must satisfy ITAR and country-specific encryption export controls.
- Cloud-Based:Hyperscaler APIs deliver sub-200ms latency through distributed edge nodes. Demand concentrates in United States financial services and German automotive OEMs seeking rapid model updates without infrastructure ownership. The EU AI Act's disclosure mandates favor cloud audit trails for synthetic voice provenance.
- Embedded:On-device inference runs on ARM Cortex-M and Qualcomm Snapdragon platforms without network dependency. Defense contractors in the United States and aerospace suppliers in France prioritize this segment for connectivity-denied environments where ITAR and ANSSI certification gates apply.
- On-Premises:Private data center deployments satisfy Chinese PIPL and Saudi PDPL localization requirements for government and telecom voice systems.
- Hybrid:Split architectures process sensitive utterances locally while offloading model training to cloud clusters, common in Canadian healthcare and Swiss banking deployments facing Health Canada and FINMA scrutiny.
Cloud-Based sits at the top of the volume ranking, with Embedded climbing the fastest as edge AI silicon matures.
Application:
Application segments diverge sharply in acoustic fidelity requirements, with clinical and entertainment use cases demanding neural vocoder quality that concatenative systems cannot satisfy.
- Automotive Infotainment:Conversational assistants manage climate, navigation, and media through multi-turn dialogue. Stuttgart and Detroit OEMs embed these systems as differentiation features, with Germany's KBA enforcing functional safety standards for driver distraction mitigation.
- Call Centers:Real-time agent augmentation and full automation handle tier-1 support queries. United States financial services and telecommunications operators drive procurement, with FCC robocall disclosure rules and state-level biometric privacy laws creating compliance complexity.
- Virtual Assistants:Smart speaker and mobile device integration requires wake-word detection paired with natural prosody. Amazon and Google platform economics compress standalone pricing.
- E-Learning:Multilingual course narration and assessment feedback serve China's SAMR-certified educational publishers and India's NCERT-aligned content distributors.
- Accessibility Tools:Screen readers and literacy aids for visually impaired users face FDA digital health guidance in the United States and MHRA scrutiny in the United Kingdom for diagnostic voice applications.
Call Centers capture the highest transaction volume, while Automotive Infotainment gains share fastest as connected vehicle penetration accelerates.
Technology:
Technology selection determines capital intensity and talent requirements, with end-to-end neural architectures displacing legacy pipelines fastest in resource-rich development environments.
- Neural Networks:End-to-end models generate waveforms directly from text, enabling speaker cloning from under ten minutes of training audio. Entertainment studios in Los Angeles and audiobook producers in London adopt these for character voice libraries, though union agreements constrain synthetic replacement of contracted talent.
- Deep Learning:Hybrid architectures separate linguistic analysis from acoustic modeling, reducing compute requirements for real-time applications. Chinese developers favor this approach for GB-compliant government speech products where training data provenance must be documented to SAMR.
- Concatenative Synthesis:Diphone and unit-selection systems stitch recorded speech segments, surviving only in legacy IVR systems with minimal maintenance budgets.
- Parametric Synthesis:Statistical models like HMM-based vocoders persist in embedded medical devices where FDA 510(k) clearance cycles discourage architecture changes.
Neural Networks dominate new project initiations, with Deep Learning expanding most quickly among constrained-resource developers.
End User:
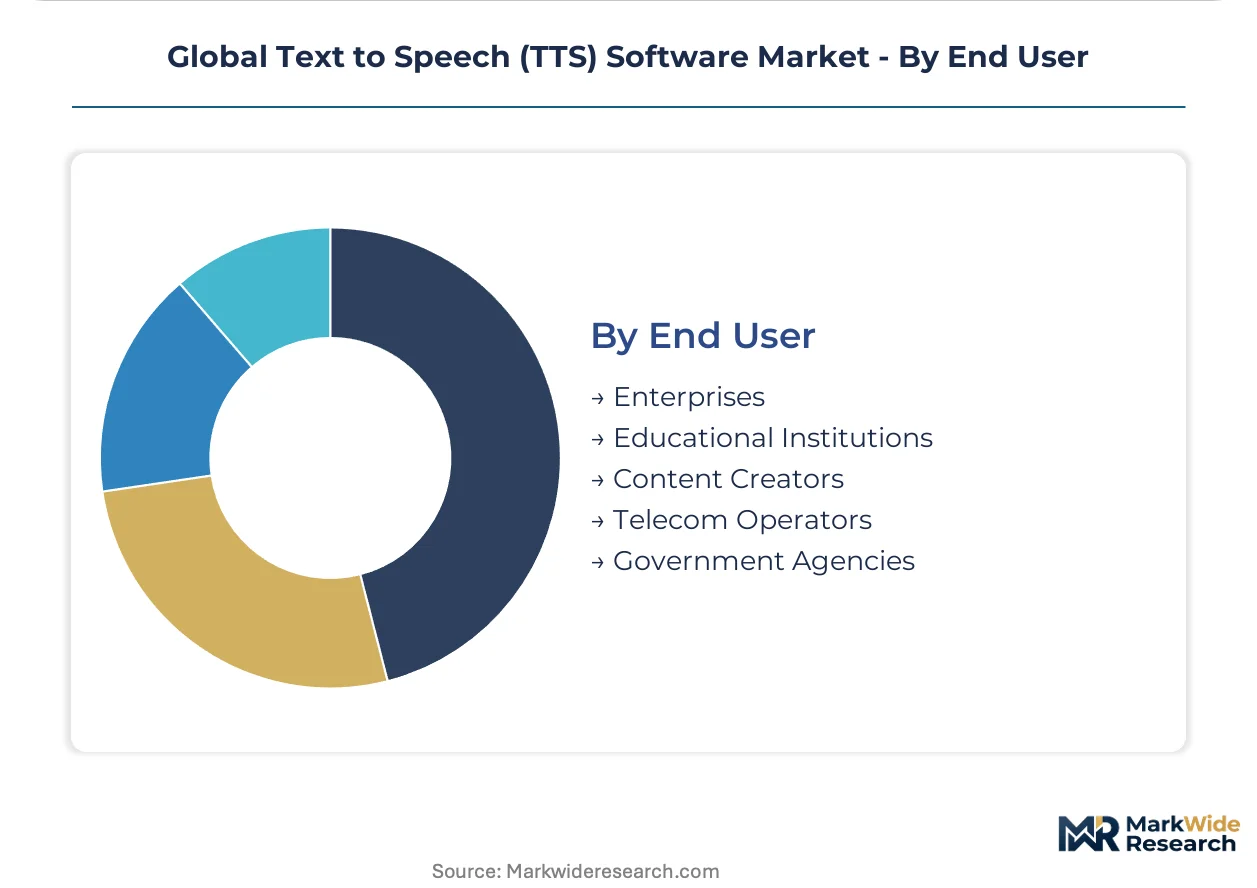
End user categories separate by procurement sophistication, with government and enterprise buyers imposing security audit requirements that exclude consumer-grade API providers.
- Government Agencies:Public sector deployments require FedRAMP authorization in the United States, CESG CHECK in the United Kingdom, and GB standard compliance in China for citizen-facing voice services. Procurement cycles run 18-36 months with mandatory bias testing and accessibility conformance.
- Enterprises:Fortune 500 call center and internal IT automation deployments negotiate enterprise licensing with volume commitments. GDPR Article 32 technical measures and SOC 2 Type II reports gate vendor selection in European and North American procurement.
- Educational Institutions:K-12 and university deployments prioritize regional language coverage and integration with learning management systems. India's NCERT and China's Ministry of Education set curriculum-aligned content standards.
- Telecom Operators:IVR modernization and voice biometric authentication drive replacement of legacy TTS infrastructure. TRAI in India and FCC in the United States regulate disclosure and consent for synthetic voice applications.
- Content Creators:Independent podcasters, game developers, and animation studios utilize SaaS APIs with per-character pricing, though SAG-AFTRA contract terms limit synthetic voice use in union-covered productions.
Enterprises generate the largest revenue base, with Government Agencies showing the steepest expansion trajectory as digital service mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting TTS development investment toward jurisdictions with clearer AI disclosure frameworks and lower compliance friction. The United States, China, Germany, India, and the United Kingdom collectively concentrate cloud infrastructure, automotive OEM demand, and government procurement that shapes regional deployment patterns.
United States
Automotive infotainment systems from Detroit OEMs and enterprise call center automation drive demand. The FDA scrutinizes voice-based diagnostic tools under digital health software guidelines, creating 12-18 month clearance timelines for healthcare developers. Silicon Valley hyperscalers anchor cloud TTS API distribution, while Boston-area healthtech clusters navigate HIPAA and FDA dual compliance for clinical voice applications.
China
Government and educational procurement through SAMR-certified channels concentrates demand for Mandarin and regional language TTS. GB standards enforcement mandates training data provenance documentation for public sector speech products. Shenzhen and Beijing host the dominant development clusters, with MIIT guiding intelligent speech product certification for smart device integration.
Germany
Stuttgart automotive suppliers embed conversational TTS into connected vehicle infotainment stacks as differentiation features. The EU AI Act's synthetic media disclosure obligations force platform operators to embed provenance metadata into outputs. Munich and Berlin clusters segregate EU-facing voice models from other deployments to ensure KBA functional safety and CE marking traceability.
India
Low screen reader penetration among regional language speakers creates whitespace for localized TTS deployment in assistive technology. TRAI regulates IVR disclosure and consent requirements for synthetic voice applications. Bangalore and Hyderabad development hubs target NCERT-aligned educational content distribution, while Maharashtra-based telecom operators modernize voice biometric infrastructure.
United Kingdom
Enterprise call center augmentation and audiobook production studios sustain commercial demand despite union constraints on synthetic talent replacement. MHRA scrutinizes diagnostic voice applications alongside FDA-aligned digital health frameworks. London's financial services sector negotiates standalone API pricing based on character volume commitments, pressuring hyperscalers for auditable spend allocation.
Global Text to Speech (TTS) Software Market Competitive Landscape
API bundling dominates the current landscape as hyperscalers lock in developer ecosystems through cloud storage and compute contract tie-ins. The vendor base concentrates around three hyperscalers with global infrastructure footprints, while mid-tier specialists occupy niche positions in embedded defense and clinical validation segments. Two strategic archetypes prevail: cloud-native platform operators leveraging neural model scale, and compliance-focused specialists serving regulated industries. Competitive moves center on M&A for linguistic talent acquisition and strategic partnerships with automotive OEMs for infotainment integration.
Within the cloud-native tier, Google LLC, Amazon Web Services, Inc., and Microsoft Corporation exemplify the platform-scale archetype. Google leverages Android Automotive to embed neural TTS across multiple OEM dashboards. Amazon anchors enterprise call center deployments through Polly's integration with Alexa for Business. Microsoft extends Azure Speech Services into Teams and Edge browser accessibility workflows, dominating developer ecosystem penetration. These three entities collectively shape API pricing norms and disclosure standard-setting through their influence on regulatory consultation processes.
| Leading Market Players |
|---|
| Google LLC |
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Apple Inc. |
| IBM Corporation |
| Baidu Inc. |
| iFlytek Co., Ltd. |
| Nuance Communications, Inc. |
| ReadSpeaker B.V. |
| Others |
Supply & Pricing Matrix
Fortune 500 call center operators in the United States and Germany's KBA-regulated automotive OEMs command divergent pricing structures, with enterprise volume commitments anchoring SaaS-tiered contracts while embedded aerospace deployments sustain premium per-unit licensing. Cloud API bundling with hyperscaler storage contracts compresses standalone TTS margins, forcing specialists toward ITAR-certified defense segments where compliance gating preserves pricing power.
Pricing Analysis
Direct-to-OEM discount structures dominate automotive procurement, with Stuttgart and Detroit manufacturers negotiating character-volume commitments that strip distributor margins from the value chain. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated clinical deployments from basic IVR automation, with certification grade as the primary differentiation driver. Price erosion runs through cloud API tiers as hyperscalers absorb inference costs to lock in developer ecosystems. Government agencies exhibit lowest price sensitivity due to 18-36 month procurement cycles and mandatory bias-testing budgets.
Supply Chain Analysis
ITAR and ANSSI certification gating concentrates embedded TTS silicon supply among United States, French, and Taiwanese defense-qualified foundries. Neural model training draws from NVIDIA A100/H100 GPU clusters concentrated in United States and Chinese cloud regions, with phonetic annotation talent scarcity in low-resource language markets creating single-source vulnerability for linguistic corpus development. Distribution runs through hyperscaler API marketplaces for cloud deployments and direct OEM integration teams for automotive infotainment stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between the EU AI Act's disclosure mandates and China's SAMR procurement standards creates geographic cost differentials for training data provenance documentation, rewarding vendors with segregated regional model pipelines.
For Market Incumbents: Anticipate enterprise buyer unbundling of TTS from cloud contracts by disclosing per-inference cost structures ahead of compliance-driven procurement audits. Defensive consolidation around linguistic talent acquisition in low-resource language markets counters emerging entrant specialization in India's assistive technology gap. Investment in GB-standard certification for Chinese government channels secures public sector revenue streams against domestic competitor expansion.
For New Entrants and Emerging Players: Enter via India's regional language screen reader whitespace, where NCERT-aligned educational content distribution lacks localized TTS penetration. Target edge AI convergence in aerospace and defense connectivity-denied environments, where ITAR certification barriers filter hyperscaler competition. Go-to-market through direct telecom operator partnerships for IVR modernization bypasses hyperscaler API marketplace saturation.
For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, seeking conversational TTS capabilities for software-defined vehicle differentiation. Long-term viability hinges on neural vocoder IP ownership and automotive infotainment integration partnerships rather than cloud API volume scale. Watch FDA digital health clearance timelines for voice-based diagnostic tools as signal for healthcare segment revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Vocoder IP Acquisition | End-to-end waveform generation eliminates concatenative artifacts for clinical and entertainment quality thresholds. |
| Automotive OEM Integration Partnership | Android Automotive and native infotainment stack embedding secures multi-year platform revenue. |
| GB Standard Certification Investment | SAMR compliance opens Chinese government and educational procurement channels to international suppliers. |
| Edge AI Silicon Co-Development | Qualcomm Snapdragon and ARM Cortex-M optimization enables ITAR-compliant on-device inference. |
| Linguistic Talent Acquisition | Phonetic annotators for low-resource languages constrain model expansion and command premium compensation. |
Research Methodology
Multiple input streams — primary interviews with TTS platform engineers, automotive OEM procurement leads, and healthcare regulatory affairs specialists, alongside secondary validation through FDA 510(k) filings, SAMR certification databases, and hyperscaler capex disclosures — were reconciled through bottom-up and top-down triangulation. Conversations with call center operators in United States financial services and German KBA functional safety auditors informed deployment constraint modeling.
Historical neural TTS adoption curves were cross-referenced against panel input from cloud infrastructure planners and edge AI silicon vendors. Segmentation dimensions modeled include deployment architecture, application vertical, technology architecture, and end-user procurement sophistication, with CAGRs derived from diffusion-rate analysis across the projection horizon. Automotive infotainment penetration rates and FDA digital health clearance velocity served as industry-specific forecast inputs.
Inputs from EU AI Act consultation documents and China MIIT intelligent speech product guidelines were available through the study window; gaps in real-time GPU cluster pricing transparency introduce uncertainty bands around cloud deployment cost assumptions. A model refresh is warranted upon material change in neural vocoder inference latency benchmarks or automotive OEM platform standardization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Online Recruitment Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Japan IT Services Market
Software & Services
Adaptive Learning Software Market
Software & Services
Custom Software Development Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Global Project Software Market
Software & Services
Online Donation Software Market
Software & Services
Video Communications Software Market
Software & Services
Global App Design Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Reporter Systems Market