
 Retail Space Planning Software Market | 2026-2036
Retail Space Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Space Planning Software Market Insights
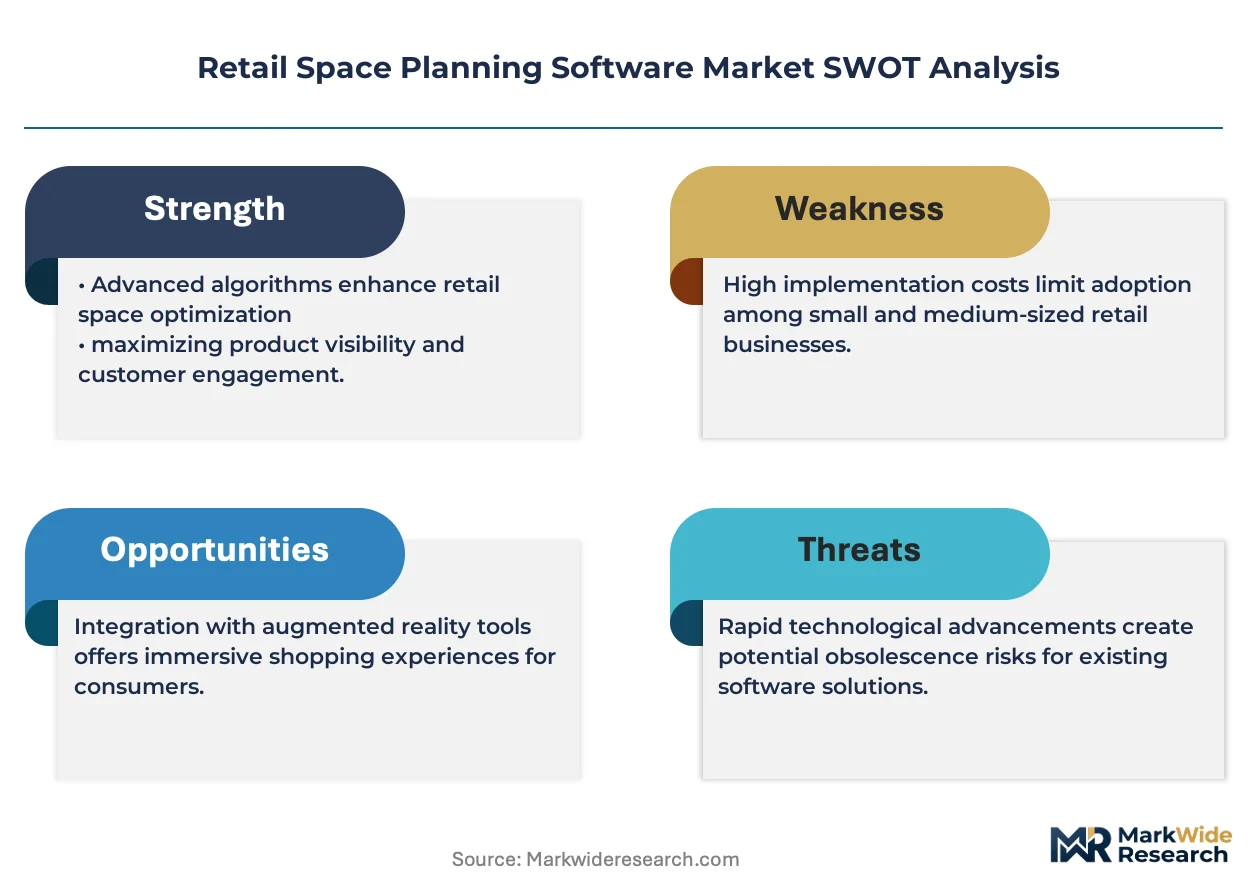
Store planner talent scarcity is collapsing implementation timelines for enterprise rollouts. Blue Yonder Space Management leverages its supply chain heritage to anchor multi-site deployments for grocery chains. RELEX Solutions differentiates through AI-native assortment optimization that extends beyond fixture layout into demand forecasting. Quant Retail competes on modular pricing that occupies the mid-market segment between enterprise suites and point solutions.
Retail space planning software denotes digital platforms that generate fixture layouts, planograms, and floor plans using parameterized shelving dimensions, traffic flow algorithms, and sales density heatmaps to maximize revenue per square meter. These systems ingest point-of-sale telemetry and inventory feeds to automate shelf-space allocation against category strategy. Cloud-based deployment leads the market as retailers prioritize remote collaboration across distributed store networks, while on-premise installations persist among operators with strict data residency requirements. Analytics dashboard functionality represents the fastest-expanding segment as merchants demand real-time performance visualization alongside static planogram output.
FDA guidelines on nutritional labeling placement influence planogram compliance modules for US grocery operators, while EU GDPR constraints shape cloud data architecture decisions for European deployments. Japan's METI energy efficiency standards for retail buildings indirectly drive floor planning software adoption through space optimization mandates. Stakeholders must evaluate integration depth with ERP systems and e-commerce platforms before committing to deployment architecture, as retrofit costs escalate once store networks scale beyond pilot phases.
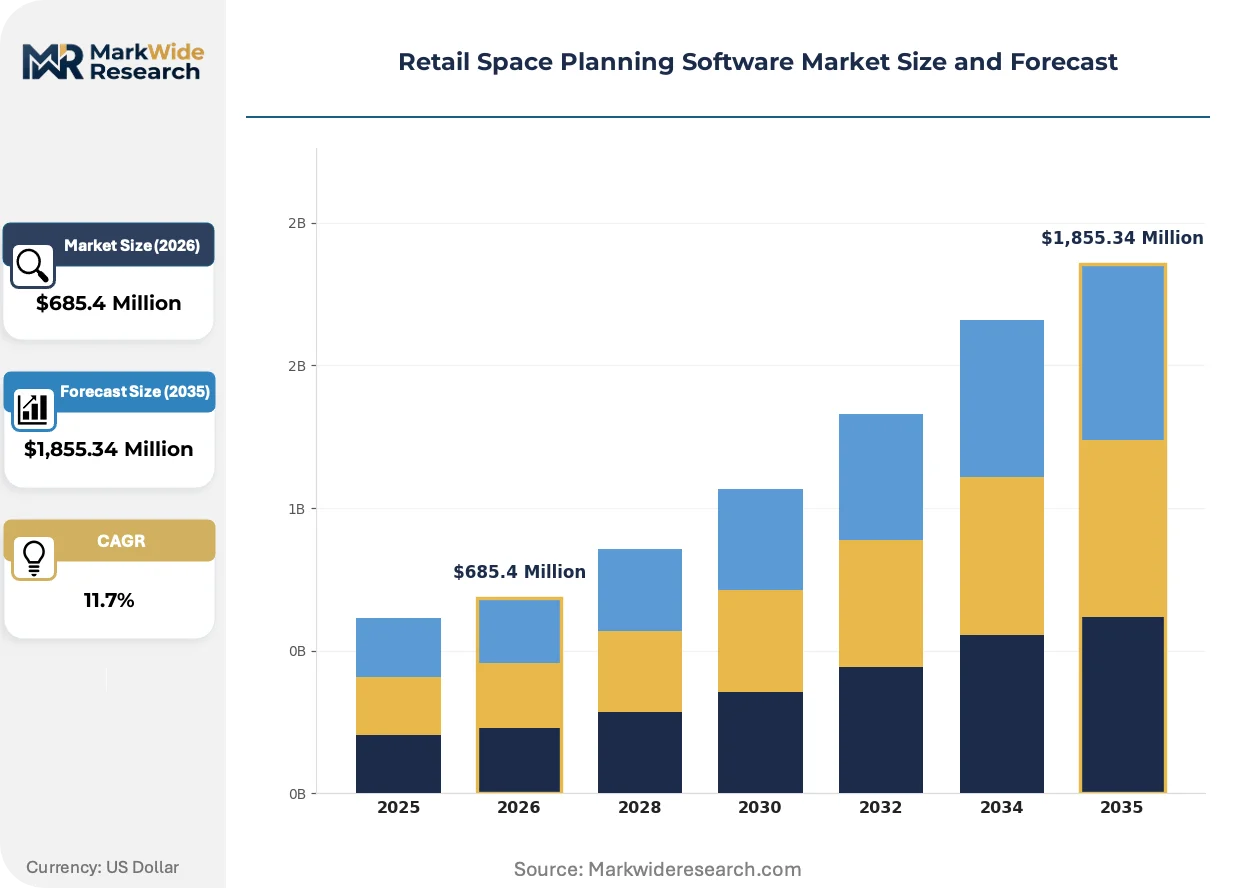
Market Dynamics
Cloud migration mandates under data sovereignty frameworks are compressing replacement cycles for legacy on-premise installations, forcing retailers to re-architect their space planning infrastructure around jurisdictional data residency requirements.
Growth Catalysts
- Specialty retailer expansion:Planogram optimization tools are penetrating independent pharmacy chains and pet specialty stores seeking shelf productivity gains comparable to grocery leaders.
- FDA nutritional labeling mandates:Compliance modules for front-of-package placement requirements are driving software refresh investments among US grocery operators managing thousands of SKUs.
- AI-native demand forecasting:Machine learning pipelines that merge traffic heatmaps with inventory telemetry are compressing planogram revision cycles from quarterly to monthly.
Market Restraints
- Implementation talent scarcity:Certified store planner professionals command premium rates that extend enterprise rollout timelines by 40-60 percent.
- Data localization costs:EU GDPR-compliant cloud architectures require redundant infrastructure investments that inflate total cost of ownership for mid-market retailers.
- Legacy ERP integration friction:Proprietary data formats from 1990s-era merchandising systems resist API connectivity, forcing expensive middleware development.
Strategic Opportunities
- Japan METI energy standards:Building efficiency mandates are creating indirect demand for floor planning software that optimizes HVAC load through spatial configuration.
- Quick-service restaurant penetration:Drive-thru layout optimization represents an adjacent application with minimal competitive saturation.
- Edge computing convergence:On-shelf camera feeds combined with real-time planogram adjustment algorithms enable dynamic shelf-space reallocation.
Industry Challenges
- Multi-site deployment complexity:Pilot-phase success metrics rarely survive scaling beyond 50 locations due to store-format heterogeneity.
- Cross-functional coordination gaps:Merchandising, operations, and IT teams maintain conflicting KPIs that stall software configuration decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Space Planning Software Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
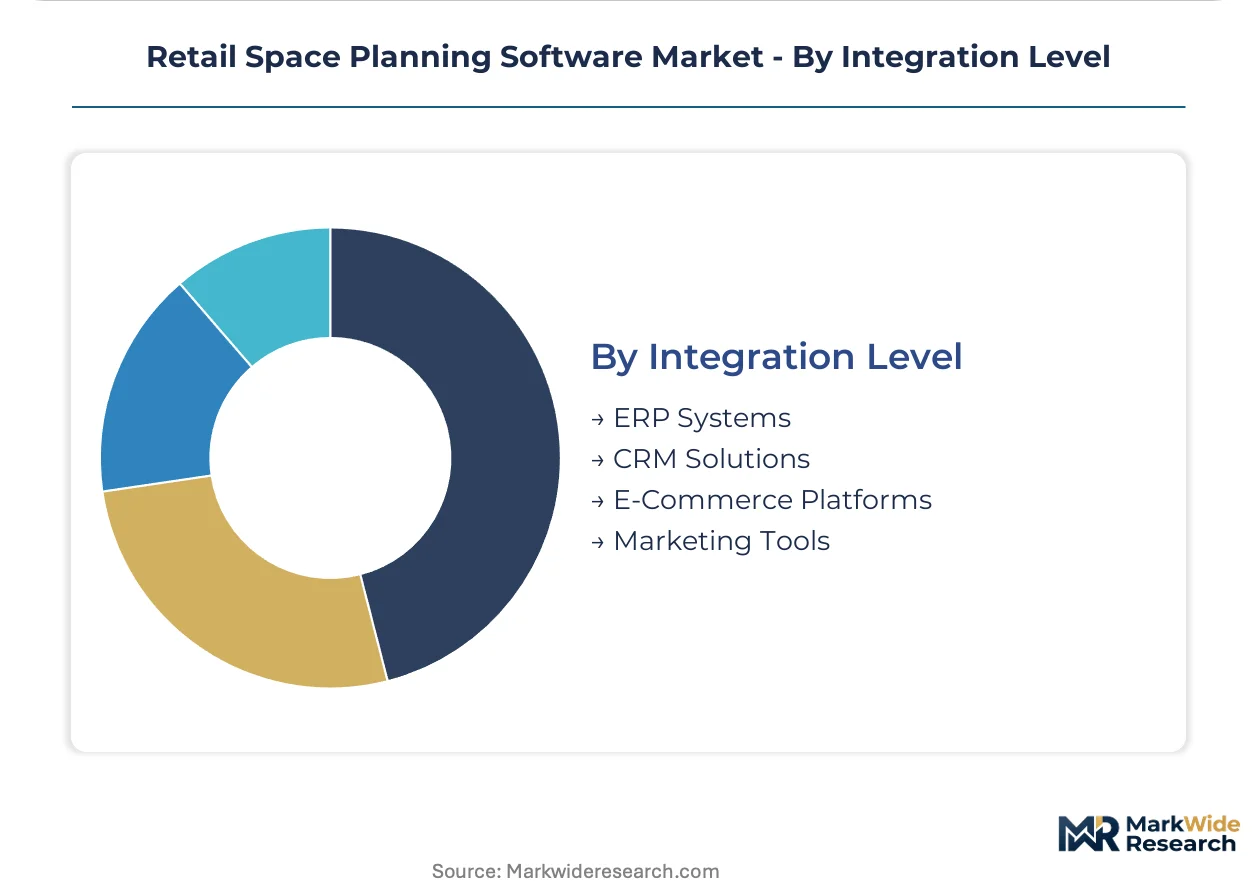
| Segmentation | Product Type: 3D Modeling, Inventory Management, Analytics Dashboard, Floor Planning End User: Store Planners, Visual Merchandisers, Retail Managers, Sales Analysts Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Integration Level: ERP Systems, CRM Solutions, E-Commerce Platforms, Marketing Tools |
| Companies Covered | SymphonyAI Retail CPG, DotActiv, Blue Yonder Space Management, Quant Retail, Pazo, RELEX Solutions, Accruent Space Intelligence, Vision Group, One Door, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Space Planning Software Market Trends and Innovations
Generative layout algorithms and real-time sensor fusion are transforming static planogram design into continuous optimization loops that respond to same-day sales velocity.
Digital twin technology for retail environments is decomposing the traditional boundaries between space planning and supply chain execution. Grocery chains with 500-plus locations are deploying these virtual store replicas to simulate assortment changes before physical implementation. The technology is decomposing legacy category management workflows by collapsing the time between insight and floor execution.
EU GDPR constraints are reshaping cloud architecture decisions for European deployments. Data residency requirements now mandate sovereign cloud instances that prevent cross-border analytics aggregation. German and French retailers are responding by demanding region-locked deployment options that fragment vendor platform roadmaps.
Subscription-based pricing for analytics modules is displacing perpetual license models among mid-market specialty retailers. Buyers now expect consumption-aligned fees tied to store count rather than upfront capital commitments. This shift is most visible in the United States where private-equity-backed retail rollups prioritize operational expense treatment for technology investments.
Retail Space Planning Software Market Segmentation
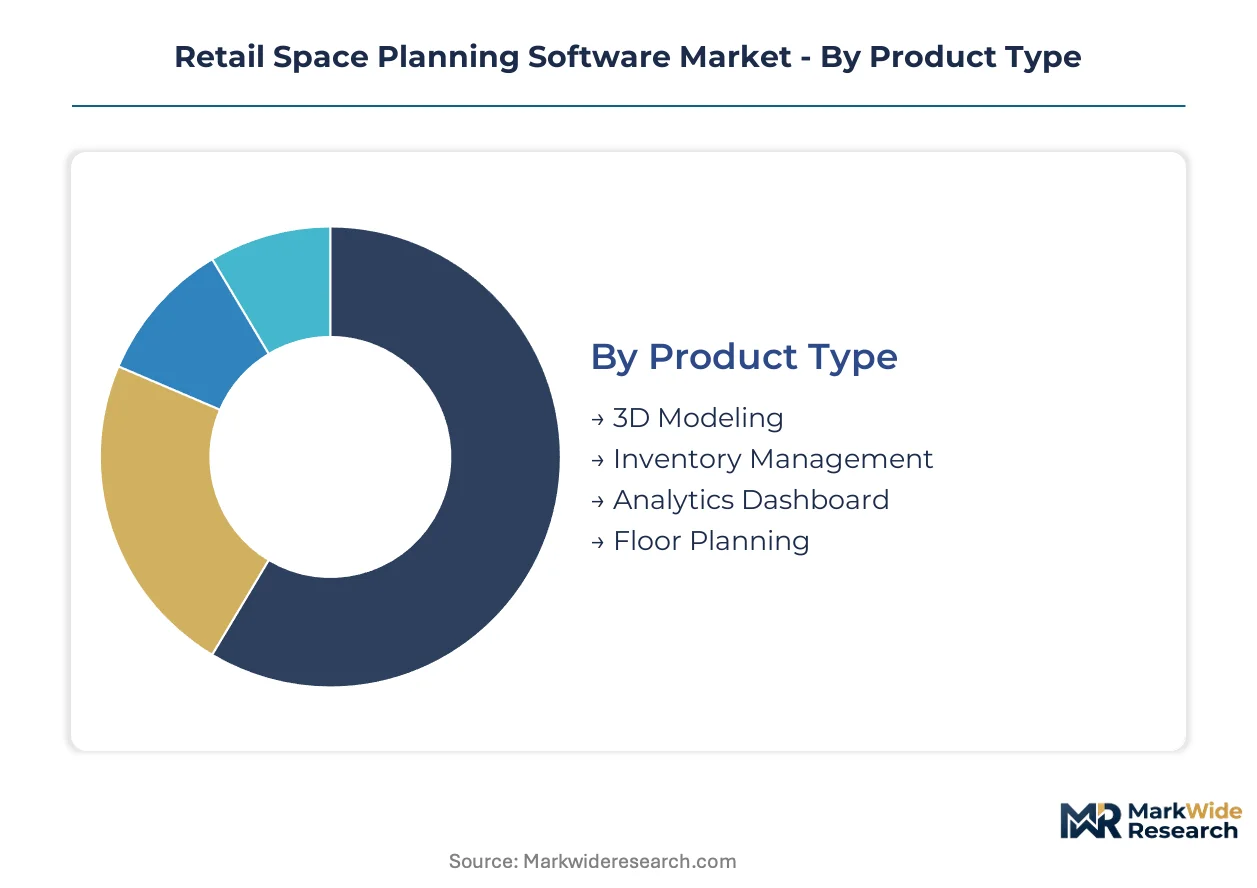
Retail space planning software segments diverge sharply by technical architecture and user workflow. Deployment choices determine data residency compliance, while integration depth dictates whether systems function as standalone tools or enterprise orchestration layers.
Product Type:
FDA nutritional labeling mandates and EU GDPR data handling requirements create divergent feature prioritization across product categories.
- Analytics Dashboard:Real-time visualization modules aggregate point-of-sale telemetry, traffic heatmaps, and inventory feeds into configurable performance views. Specialty pharmacy chains in Germany deploy these dashboards to monitor shelf productivity against METI-inspired efficiency targets. Cloud data sovereignty frameworks accelerate replacement cycles for legacy reporting tools.
- Floor Planning:Parametric layout engines generate fixture configurations using building dimension constraints and HVAC load optimization algorithms. Japanese retailers leverage these tools to comply with METI energy efficiency standards for retail buildings. The segment compresses implementation timelines for flagship store networks.
- 3D Modeling:Photorealistic store rendering enables virtual walkthroughs before physical fixture installation.
- Inventory Management:Automated shelf-space allocation algorithms synchronize planogram output with warehouse stock levels.
Analytics Dashboard handles the majority of throughput; Floor Planning is the fastest mover on share.
End User:
User specialization determines workflow complexity and pricing tier acceptance across the customer base.
- Store Planners:Certified professionals configure parameterized shelving dimensions and traffic flow algorithms to maximize revenue per square meter. Talent scarcity in the United States extends enterprise rollout timelines by 40-60 percent, forcing vendors to embed automation that reduces manual configuration dependency.
- Retail Managers:Operations-focused users demand mobile-first interfaces for distributed store network oversight. German grocery chains prioritize these tools for multi-site deployment coordination under GDPR-compliant cloud architectures.
- Visual Merchandisers:Aesthetic-focused users require high-fidelity rendering capabilities for brand consistency enforcement.
- Sales Analysts:Data-driven users extract category performance insights to inform assortment strategy revisions.
Store Planners dominate current deployment volumes; Retail Managers are expanding most quickly as self-service adoption spreads.
Deployment:
Data localization costs and sovereignty frameworks fragment architecture decisions by geography.
- Cloud-Based:Remote collaboration platforms enable distributed store network coordination without on-site infrastructure. EU GDPR constraints mandate sovereign cloud instances that prevent cross-border analytics aggregation, inflating total cost of ownership for mid-market retailers. Subscription-based pricing aligns fees with store count rather than upfront capital commitments.
- On-Premise:Local installations persist among operators with strict data residency requirements or legacy ERP integration friction. Japanese retailers with METI compliance obligations often maintain hybrid architectures that segregate sensitive operational data.
- Hybrid:Split deployments balance remote accessibility with localized control over critical systems.
- SaaS:Consumption-aligned licensing reduces barrier to entry for independent pharmacy chains and pet specialty stores.
Cloud-Based carries the largest installed base; SaaS is climbing the fastest as private-equity-backed retail rollups prioritize operational expense treatment.
Integration Level:
Connectivity depth determines whether space planning functions as an isolated tool or enterprise-wide orchestration layer.
- ERP Systems:Merchandising and financial data synchronization enables automated planogram-to-procurement workflows. Proprietary data formats from 1990s-era systems resist API connectivity, forcing expensive middleware development for US grocery operators managing thousands of SKUs.
- E-Commerce Platforms:Unified inventory visibility across physical and digital channels supports omnichannel fulfillment strategies. German retailers demand these integrations to coordinate flagship store networks with online operations.
- CRM Solutions:Customer segmentation data informs localized assortment customization by store format.
- Marketing Tools:Campaign calendar synchronization enables promotional space allocation planning.
ERP Systems anchors the integration landscape; E-Commerce Platforms show the steepest expansion trajectory as channel convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands a 35-40 percent premium over equivalent deployments in Germany, reflecting talent scarcity and compliance module complexity that inflate implementation costs.
United States
FDA nutritional labeling mandates for front-of-package placement drive software refresh cycles among grocery operators managing thousands of SKUs. HIPAA-adjacent data handling protocols shape cloud architecture decisions for pharmacy chains. Chicago-based specialty retailers anchor demand for AI-native assortment optimization tools that compress planogram revision timelines.
Germany
GDPR-compliant sovereign cloud instances fragment vendor platform roadmaps and inflate total cost of ownership for mid-market retailers. EU Green Deal efficiency targets indirectly accelerate floor planning software adoption through building optimization mandates. The Rhine-Ruhr metropolitan corridor concentrates flagship store network investments from grocery chains demanding ERP integration depth.
Japan
METI energy efficiency standards for retail buildings create indirect demand for floor planning software that optimizes HVAC load through spatial configuration. JIS standards compliance shapes modular pricing acceptance among regional retail rollups. The Kanto region surrounding Tokyo hosts the densest concentration of pilot-to-scale deployments for digital twin technology in grocery environments.
United Kingdom
Post-Brexit data localization requirements accelerate replacement cycles for legacy cloud architectures previously dependent on EU-wide analytics aggregation. CSRD reporting obligations extend software procurement criteria to include carbon footprint visualization modules. London anchors demand for subscription-based analytics dashboards among private-equity-backed retail rollups prioritizing operational expense treatment.
India
BIS certification requirements for imported software modules create friction for multinational vendors seeking rapid market entry. PLI scheme incentives for retail technology adoption concentrate in organized grocery chains exceeding 100 locations. Maharashtra and Karnataka host the majority of domestic system integrators building middleware for legacy ERP connectivity.
Retail Space Planning Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the market structure. Enterprise-grade AI-native platforms command premium positioning through supply chain integration depth, while modular point solutions occupy the mid-market with consumption-aligned pricing. Three archetypes dominate: integrated suite vendors extending from adjacent enterprise software, pure-play specialists with category-specific optimization engines, and emerging SaaS-native entrants targeting independent retail chains. Competitive moves concentrate on strategic partnerships with ERP providers and geographic expansion through region-locked cloud deployments.
Within the integrated suite tier, Blue Yonder Space Management and RELEX Solutions exemplify archetypes that leverage supply chain heritage to anchor multi-site grocery deployments. Quant Retail occupies a distinct mid-market position between enterprise suites and point solutions through modular pricing structures. SymphonyAI Retail CPG represents the AI-native specialist archetype with machine learning pipelines that merge traffic heatmaps with inventory telemetry. These three companies collectively illustrate the competitive tension between depth of integration and speed of implementation that shapes procurement decisions across the United States, Germany, and Japan.
| Leading Market Players |
|---|
| SymphonyAI Retail CPG |
| DotActiv |
| Blue Yonder Space Management |
| Quant Retail |
| Pazo |
| RELEX Solutions |
| Accruent Space Intelligence |
| Vision Group |
| One Door |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation timelines for enterprise rollouts compress supplier negotiation windows and amplify pricing power for certified store planner professionals. This lead-time pressure concentrates vendor selection around pre-integrated suite providers while forcing mid-market buyers toward modular SaaS tiers that trade customization depth for deployment speed.
Pricing Analysis
The customization-premium spread separates enterprise-configured deployments from standardized SaaS tiers by a substantial margin. Subscription-based SaaS licensing dominates, with consumption-aligned fees tied to store count displacing perpetual licenses among private-equity-backed retail rollups. Price differentiation centers on integration depth with ERP systems and AI-native analytics capabilities. Cost compression in the mid-market intensifies as vendors compete for independent pharmacy chains and pet specialty stores with limited implementation budgets. Independent retailers exhibit highest price sensitivity, while grocery chains with 500-plus locations prioritize total cost of ownership over upfront licensing.
Supply Chain Analysis
Inventory compression in cloud infrastructure provisioning shortens vendor delivery cycles to 30-45 days for standard deployments. Software development concentrates in the United States, Germany, and Japan, with regional data centers anchoring GDPR-compliant and METI-aligned architectures. Raw material dependencies center on GPU compute capacity for AI-native modules, sovereign cloud infrastructure for data residency compliance, and specialized talent pipelines for store planner certification. Single-source vulnerability in certified implementation talent extends rollout timelines and inflates service delivery costs. Distribution runs through direct enterprise sales for grocery chains and channel partners for mid-market specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock buyers into integrated suites once ERP connectivity and multi-site deployment complexity accumulate. Regulatory entrenchment through FDA compliance modules and GDPR sovereign cloud requirements further deepens incumbent advantages.
For Market Incumbents: Fortify platform stickiness by embedding AI-native demand forecasting that collapses planogram revision cycles and deepens ERP integration depth. Acquire specialized middleware providers to neutralize legacy system connectivity friction that stalls competitor deployments. Expand region-locked cloud instances ahead of data sovereignty enforcement in Japan and post-Brexit United Kingdom to preempt emerging entrant geographic expansion.
For New Entrants and Emerging Players: Differentiate on edge computing convergence for real-time shelf-space reallocation, targeting quick-service restaurant drive-thru layout optimization where competitive saturation remains minimal. Penetrate independent pharmacy chains in Germany through modular analytics dashboards priced below enterprise suite thresholds. Pursue partnership-first go-to-market with domestic system integrators in India to navigate BIS certification friction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-market fragmentation between point solutions and enterprise suites creates roll-up opportunity for platforms with AI-native architecture and regional cloud compliance capabilities. Target acquisition archetypes: SaaS-native entrants with consumption-aligned pricing and established middleware connectivity to 1990s-era merchandising systems. Monitor FDA enforcement intensity on nutritional labeling placement as signal for compliance module demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Platform Integration | Machine learning pipelines merging traffic heatmaps with inventory telemetry compress revision cycles from quarterly to monthly. |
| Sovereign Cloud Deployment | Region-locked instances satisfy GDPR and METI data residency mandates while fragmenting competitor platform roadmaps. |
| Middleware Acquisition | Legacy ERP connectivity capabilities neutralize integration friction that stalls 40-60 percent of enterprise rollouts. |
| Edge Computing Convergence | On-shelf camera feeds with real-time adjustment algorithms enable dynamic shelf-space reallocation without cloud latency. |
| Quick-Service Restaurant Expansion | Drive-thru layout optimization represents adjacent application with minimal competitive saturation and distinct buyer profiles. |
Research Methodology
Initial hypotheses were tested against primary input from retail space planning software vendors, grocery chain IT procurement officers, certified store planner professionals, and ERP integration specialists and refined through secondary validation. Primary research encompassed structured interviews with merchandising executives at specialty pharmacy chains, operations directors at pet specialty retailers, and platform engineers at cloud infrastructure providers. Secondary sources included SEC filings from publicly traded software vendors, FDA guidance documents on nutritional labeling, EU GDPR implementation reports, METI energy efficiency standards, and customs records tracking retail technology imports. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Variance decomposition across deployment models, end-user workflows, integration complexity tiers, and regional regulatory clusters anchored the analytical framework. Segmentation dimensions modeled encompass cloud versus on-premise architecture, store planner versus retail manager user types, ERP versus e-commerce integration depth, and sovereign cloud deployment patterns. CAGRs were derived from fitted growth curves calibrated to replacement cycle observations and cloud migration mandate timelines. Industry-specific forecast inputs included FDA enforcement intensity projections, GDPR compliance cost trajectories, and METI building efficiency standard adoption curves.
Material uncertainties — regulatory enforcement timing, certified talent pipeline expansion, and legacy ERP system retirement rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about cloud infrastructure cost trajectories and data sovereignty framework evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global HMI Software Market
Software & Services
Global Policy Management Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Asia Pacific Content Services Platform Market
Software & Services
Global Portal Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Europe Drone Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Saas Based HRM Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Clustering Software Market
Software & Services
DevOps Market
Software & Services
Data Preparation Tools Market