
 Japan IT Services Market | 2026-2036
Japan IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Japan IT Services Market Insights
Enterprise procurement channels in Japan are tilting toward outcome-based managed services contracts with multi-year tenures. Fujitsu Ltd. leverages its domestic datacenter footprint to anchor large manufacturing accounts seeking hybrid cloud migration. NEC Corp. competes through deep vertical specialization in public sector and healthcare IT infrastructure. NTT Data Corp. extends its position via global delivery networks that complement onshore Japanese consulting teams.
Japan IT Services encompasses systems integration, application management, infrastructure operations, and digital transformation consulting delivered through onshore, offshore, and hybrid resourcing models. Service level agreements typically specify availability thresholds above 99.9% with penalty clauses and security compliance tied to JIS Q 27001 standards. Cloud Services and Managed Services together command the largest revenue pools as enterprises exit legacy mainframe operations. AI Solutions within the Technology dimension is expanding fastest as financial services and manufacturing deploy machine learning for predictive maintenance and fraud detection.
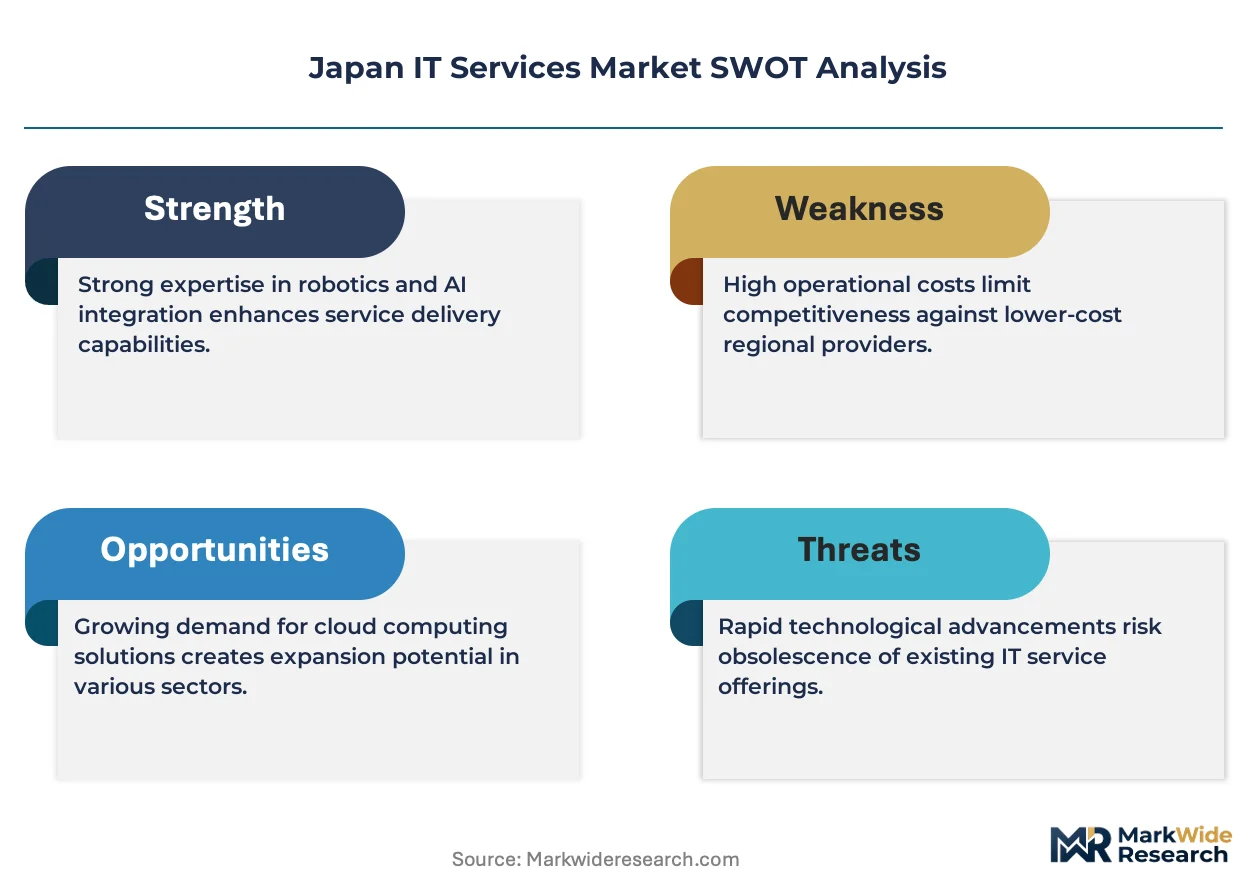
METI's cloud-by-default guidelines and the Personal Information Protection Commission's data localization expectations shape vendor qualification and contract structures. JIS standards for information security management and the Ministry of Economy, Trade and Industry's cybersecurity framework for critical infrastructure create compliance thresholds that favor established domestic players with certified delivery centers. Stakeholders must weigh the trade-off between offshore cost arbitrage and domestic regulatory proximity when restructuring service delivery footprints.
Market Dynamics
METI's cloud-first directives and the Personal Information Protection Commission's data localization mandates are compressing vendor qualification timelines while elevating compliance costs for foreign entrants seeking Japanese enterprise contracts.
Growth Catalysts
- Society 5.0 Framework:METI's national digitization blueprint accelerates smart factory investments across automotive and electronics manufacturing clusters in Aichi and Kanagawa prefectures.
- Core System Modernization:Financial institutions in Tokyo and Osaka are expanding outsourcing contracts for legacy mainframe replacement with hybrid cloud architectures.
- Operational Technology Convergence:Manufacturers are deploying edge computing platforms to integrate production line sensors with enterprise ERP systems for real-time quality control.
Market Restraints
- Domestic Datacenter Concentration:Certified facility scarcity in Greater Tokyo elevates colocation costs and extends provisioning lead times for compliant cloud deployments.
- JIS Q 27001 Certification Burden:Information security management system audits create 12-18 month vendor onboarding cycles that disadvantage smaller systems integrators.
- Mainframe Skill Attrition:Retiring COBOL and assembler programmers constrain legacy system maintenance capacity during multi-year migration windows.
Strategic Opportunities
- Kansai Manufacturing Belt:Osaka, Kyoto, and Hyogo prefectures show underpenetrated managed services adoption among precision machinery and pharmaceutical producers.
- AI-Infused Predictive Maintenance:Machine learning models analyzing vibration and thermal sensor data are opening new service revenue streams in steel and chemical processing plants.
- Fukuoka Startup Corridor:Kyushu's emerging fintech and gaming software clusters create demand for mid-market cloud-native development partnerships.
Industry Challenges
- Bilingual Solution Architecture Talent:Scarcity of Japanese-English fluent cloud engineers constrains global delivery model scaling for domestic vendors.
- Multi-Cloud Integration Complexity:Enterprise demand for AWS-Azure-Google workload portability creates architectural standardization delays and cost estimation uncertainty.
- Supply Chain Cybersecurity Audits:METI's critical infrastructure framework mandates tier-n supplier security assessments that elongate procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan IT Services Market |
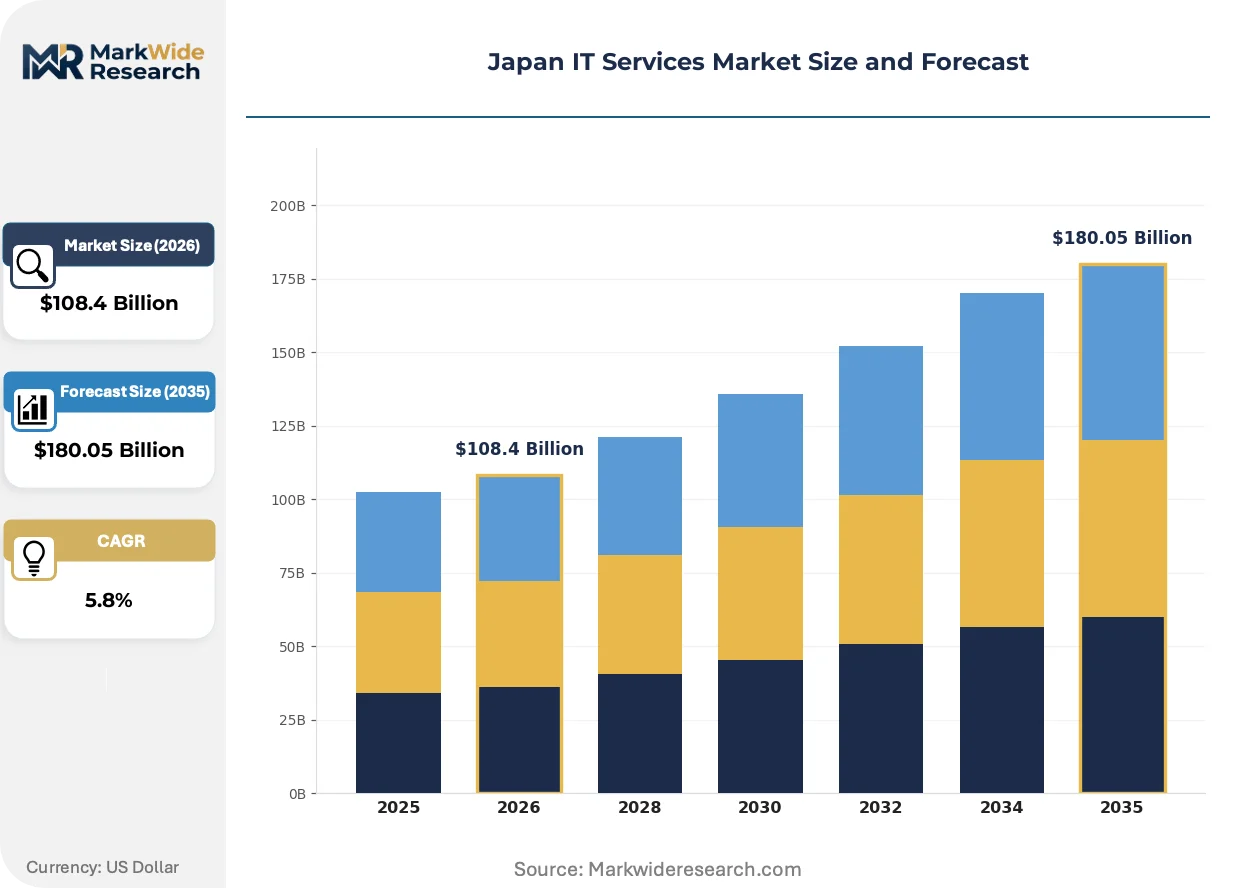
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $180.05 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Cybersecurity, IT Consulting, Managed Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Healthcare, Financial Services, Retail, Manufacturing Technology: AI Solutions, Big Data Analytics, Blockchain, IoT Platforms |
| Companies Covered | Nomura Research Institute, Japan Business Systems, Inc., NEC Corp., Ubitus Inc., Fusion Systems Group, Fujitsu Ltd., Fuji Soft, EIRE Systems, NTT Data Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan IT Services Market Trends and Innovations
Containerized microservices architectures and generative AI coding assistants are compressing application development cycles while forcing established systems integrators to retrain delivery teams.
Serverless computing platforms are eliminating infrastructure provisioning overhead for event-driven workloads. Regional banks and insurance carriers in Nagoya and Sapporo are migrating batch processing to function-as-a-service environments. This operational model shift is rendering obsolete traditional three-year hardware refresh contracts with fixed capacity planning.
METI's cloud-by-default procurement guidelines now mandate SaaS-first evaluation for new government systems. Municipalities in Hokkaido and Shikoku are consolidating legacy siloed applications into shared prefectural platforms. Public sector IT budgets are reallocating from capital expenditure to recurring subscription models with embedded security compliance.
Enterprise buyers are unbundling monolithic outsourcing agreements into modular service components with discrete pricing. Manufacturing procurement teams in Chubu and Tohoku regions now separately contract infrastructure operations, application maintenance, and digital transformation consulting. This decomposition trend is most visible among automotive tier-1 suppliers seeking agile vendor substitution rights.
Japan IT Services Market Segmentation
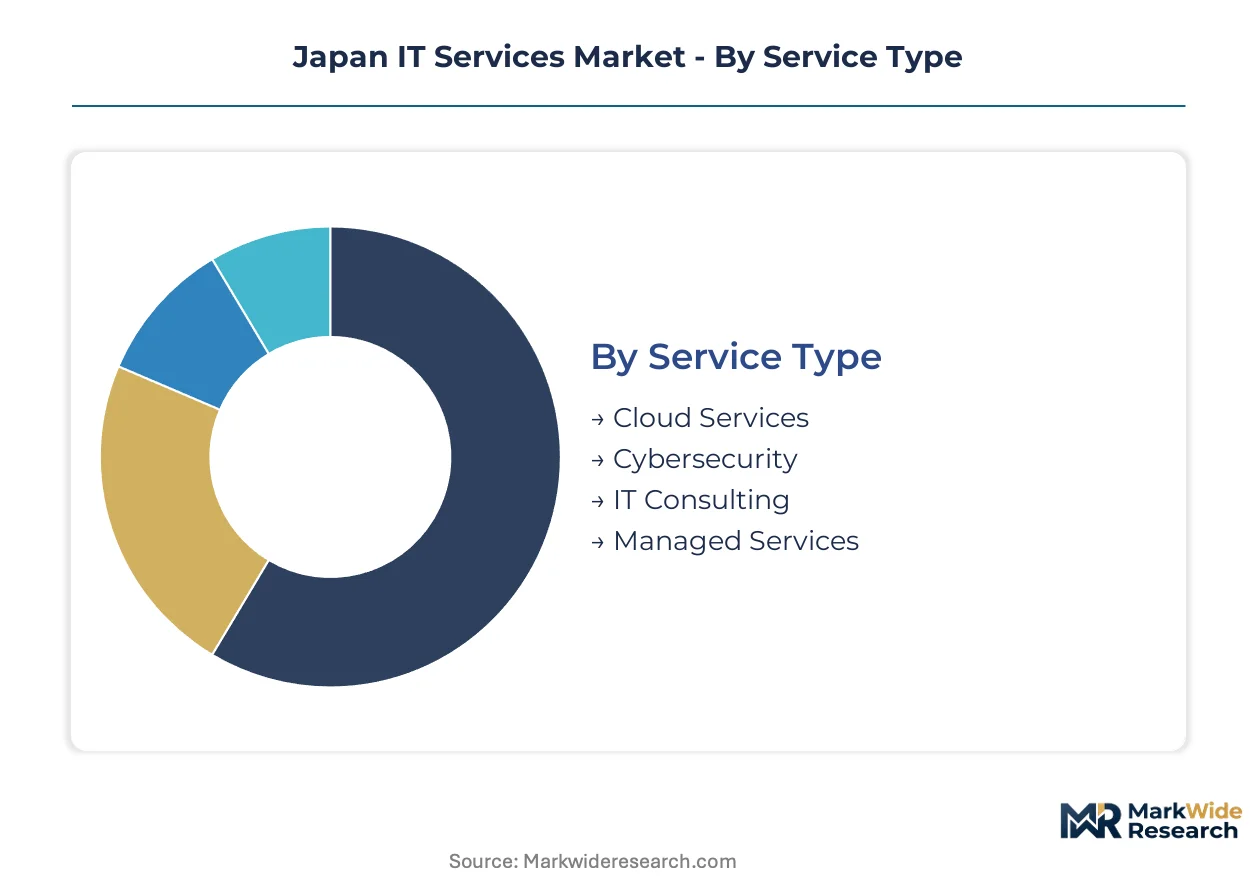
Japan IT Services market segmentation reveals distinct procurement patterns across service delivery modes, infrastructure architectures, and vertical applications. Each dimension carries specific regulatory and operational constraints that shape vendor qualification and contract structuring.
Service Type:
Use-case spectrum spans from infrastructure abstraction to strategic advisory, with procurement teams unbundling monolithic contracts into discrete service components.
- Cloud Services:Infrastructure-as-a-service and platform-as-a-service offerings enable workload migration from legacy mainframes to scalable environments. Financial institutions in Tokyo and Osaka dominate demand as METI's cloud-first policies accelerate vendor selection timelines for core system modernization.
- Managed Services:Outcome-based contracts covering infrastructure operations, application maintenance, and security monitoring with availability thresholds above 99.9%. Manufacturers in Aichi and Kanagawa prefectures favor multi-year tenures as they seek operational technology integration without expanding internal IT headcount.
- Cybersecurity:Managed detection and response, identity access management, and compliance auditing aligned with JIS Q 27001 standards. Critical infrastructure operators face elongated procurement cycles due to METI's tier-n supplier security assessment mandates.
- IT Consulting:Digital transformation roadmapping, cloud migration strategy, and enterprise architecture redesign delivered through hybrid resourcing models. Regional banks in Nagoya and Sapporo drive mid-market demand for serverless computing transition planning.
Established volume favors Managed Services; emerging adoption favors Cloud Services.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises ownership from operational expenditure models with compliance-driven localization requirements.
- Hybrid Cloud:Workload portability across on-premises infrastructure and public cloud platforms addresses data residency constraints while enabling burst capacity. Automotive tier-1 suppliers in Chubu region prioritize this architecture for ERP integration with production line sensors.
- Private Cloud:Dedicated infrastructure deployments within certified domestic datacenters satisfy Personal Information Protection Commission localization expectations. Scarcity of compliant facilities in Greater Tokyo elevates colocation costs and extends provisioning lead times.
- Public Cloud:Shared infrastructure services from hyperscale providers with region-specific availability zones. Municipalities in Hokkaido and Shikoku leverage SaaS-first procurement guidelines to consolidate legacy siloed applications.
- On-Premises:Traditional owned-and-operated infrastructure retained for latency-sensitive workloads and legacy application dependencies. Steel and chemical processing plants maintain edge computing nodes for real-time quality control systems.
Procurement concentration centers on Hybrid Cloud; steepest expansion trajectory belongs to Private Cloud as compliance requirements tighten.
End User:
Customer type determines contract scale, security classification, and solution complexity across regulated and competitive sectors.
- Financial Services:Banks, insurers, and securities firms requiring high-availability transaction processing and fraud detection capabilities. Core system modernization initiatives in Tokyo and Osaka generate sustained outsourcing demand for legacy mainframe replacement.
- Manufacturing:Automotive, electronics, and precision machinery producers deploying predictive maintenance and smart factory platforms. Aichi and Kanagawa prefectures lead investment under METI's Society 5.0 digitization blueprint.
- Healthcare:Hospitals, clinics, and pharmaceutical companies managing electronic health records and clinical trial data. Public sector IT infrastructure specialization creates procurement preference for vendors with deep vertical certification.
- Retail:Department stores, e-commerce platforms, and convenience chains optimizing supply chain visibility and customer analytics. Omnichannel integration requirements drive demand for real-time inventory synchronization across distributed locations.
Contract value concentration favors Financial Services; technology refresh intensity favors Manufacturing.
Technology:
Maturity gradient separates established analytics platforms from emerging architectures with unproven enterprise scale.
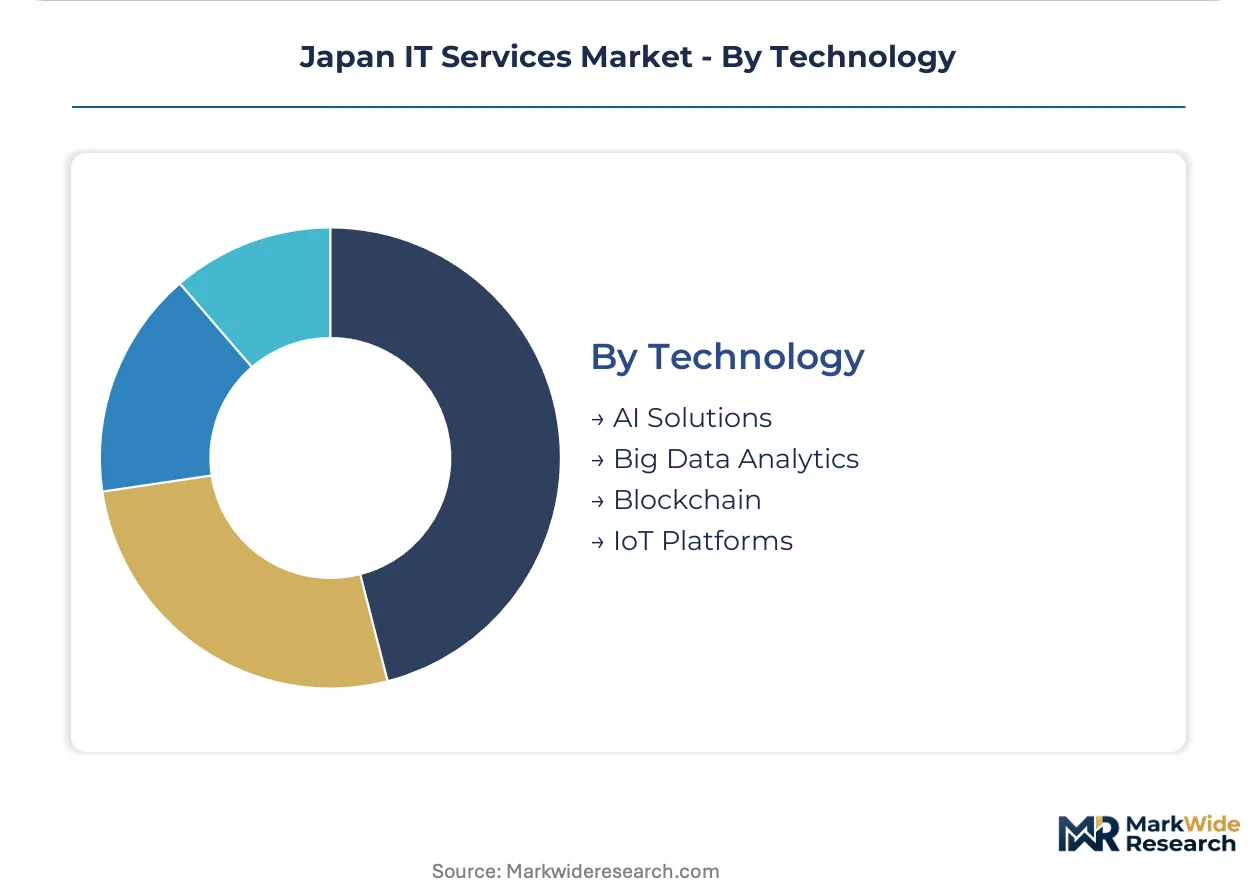
- AI Solutions:Machine learning models for predictive maintenance, fraud detection, and generative coding assistance. Steel and chemical processing plants in Kansai Manufacturing Belt deploy vibration and thermal sensor analysis for new service revenue streams.
- Big Data Analytics:Enterprise data warehousing, visualization platforms, and batch processing optimization. Regional banks migrate historical transaction analysis to function-as-a-service environments under serverless computing initiatives.
- IoT Platforms:Edge computing frameworks connecting production line sensors to enterprise systems. Operational technology convergence in automotive clusters enables real-time quality control and automated defect response.
- Blockchain:Distributed ledger applications for supply chain traceability and cross-border settlement. Fintech startups in Fukuoka Corridor experiment with mid-market cloud-native development partnerships.
Commercial deployment maturity favors Big Data Analytics; capability investment intensity favors AI Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokyo-Osaka Shinkansen corridor underwrites Japan's IT services concentration, compressing travel times between the two primary demand centers to under three hours and enabling same-day consulting deployments across the nation's economic spine.
Kanto/Tokyo
Financial institutions in Tokyo's Marunouchi and Nihonbashi districts drive core system modernization contracts, with METI's cloud-first procurement guidelines accelerating vendor qualification timelines. The Personal Information Protection Commission's data localization expectations shape contract structures for domestic datacenter deployments. Megabanks and securities firms in the Tokyo Bay area sustain the nation's largest concentration of managed services demand.
Kansai/Osaka
Precision machinery and pharmaceutical producers in Osaka, Kyoto, and Hyogo prefectures show expanding managed services adoption under operational technology convergence initiatives. METI's Society 5.0 framework channels digitization investment into smart factory platforms across the manufacturing belt. Osaka-based financial institutions mirror Tokyo's outsourcing patterns for legacy mainframe replacement.
Chubu/Nagoya
Automotive tier-1 suppliers in Aichi prefecture deploy edge computing platforms integrating production line sensors with enterprise ERP systems. Regional banks in Nagoya migrate batch processing to serverless computing environments under function-as-a-service procurement models. The Toyota production system heritage creates distinctive demand for predictive maintenance and real-time quality control integration.
Kyushu
Fukuoka's emerging fintech and gaming software clusters generate mid-market demand for cloud-native development partnerships. Municipalities across Kyushu consolidate legacy siloed applications into shared prefectural platforms under METI's SaaS-first guidelines. The startup corridor's lower operational costs attract satellite delivery centers from established systems integrators.
Hokkaido
Municipal governments in Sapporo and regional centers reallocate IT budgets from capital expenditure to recurring subscription models with embedded security compliance. Agricultural cooperatives and food processors deploy IoT platforms for supply chain visibility across the island's dispersed production bases. Cold climate advantages support growing datacenter facility interest from domestic cloud operators.
Japan IT Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in security, AI model development, and vertical-specific applications. The vendor base organizes around three archetypes: full-service systems integrators with domestic datacenter footprints, specialized managed services providers, and emerging cloud-native consultancies. Competitive positioning depends on JIS Q 27001 certification depth and METI cybersecurity framework compliance. Consolidation pressure favors acquisition of mid-tier specialists by platform players seeking vertical capabilities.
Within the full-service integrator tier, Fujitsu Ltd. and NEC Corp. anchor established positions through certified delivery center networks and public sector specialization. NTT Data Corp. occupies a distinctive position combining global delivery scale with onshore Japanese consulting presence. These three exemplify the compliance-proximity competitive vector that shapes enterprise procurement preferences.
| Leading Market Players |
|---|
| Nomura Research Institute |
| Japan Business Systems, Inc. |
| NEC Corp. |
| Ubitus Inc. |
| Fusion Systems Group |
| Fujitsu Ltd. |
| Fuji Soft |
| EIRE Systems |
| NTT Data Corp. |
| Others |
Pricing and Supply Chain Analysis
Greater Tokyo's certified datacenter scarcity constrains compliant cloud capacity, elevating colocation premiums and compressing margins for foreign entrants seeking JIS Q 27001-qualified delivery footprints. METI's cloud-first mandates accelerate procurement velocity while the Personal Information Protection Commission's localization expectations tether pricing power to domestic facility access.
Pricing Analysis
Volume-discount tiering structures separate enterprise managed services contracts from mid-market SaaS subscriptions and startup-tier development partnerships. Pricing stratifies across premium certified tiers, standard domestic delivery, and economy offshore-hybrid arrangements, with JIS Q 27001 certification depth and onshore engineer ratios as primary differentiation drivers. Cost compression in the economy tier is intensifying because hyperscale public cloud providers are absorbing commodity infrastructure workloads. Regional banks and municipal governments in secondary prefectures exhibit highest price sensitivity; Tokyo megabanks and critical infrastructure operators demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Fujitsu Ltd., NEC Corp., and NTT Data Corp. anchor domestic systems integration capacity through certified delivery center networks across Japan, Taiwan, and select Southeast Asian nodes. The supply chain draws from specialized semiconductor components for edge computing platforms, proprietary mainframe migration tools, and bilingual solution architecture talent pools concentrated in Greater Tokyo and Osaka. Single-source vulnerability persists in legacy COBOL and assembler programming expertise as retiring practitioners constrain maintenance capacity. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and emerging cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan IT Services market is recovering from mainframe skill attrition and compliance-driven vendor consolidation, with cyclical expansion supported by METI's Society 5.0 investment acceleration across manufacturing clusters.
For Market Incumbents: Entrench JIS Q 27001 certification depth across delivery centers to defend against emerging cloud-native consultancies and hyperscale provider encroachment. Acquire mid-tier AI specialists in the Kansai Manufacturing Belt to secure predictive maintenance capabilities before operational technology convergence matures. Prioritize bilingual engineer retention programs as the critical lever against global delivery model scaling constraints. For New Entrants and Emerging Players: Kyushu's Fukuoka Startup Corridor offers underpenetrated mid-market demand for cloud-native development partnerships among fintech and gaming software clusters. Target precision machinery producers in Osaka, Kyoto, and Hyogo prefectures with modular managed services components unbundled from monolithic outsourcing agreements. Establish satellite delivery centers leveraging lower operational costs with METI SaaS-first procurement guidelines as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core IT services units lacking vertical specialization depth. Long-term viability centers on compliance-proximity competitive positioning sustained by regulatory localization mandates. Monitor JIS Q 27001 certification backlog durations as the inflection indicator for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Q 27001 Certification Expansion | Domestic datacenter certification depth determines qualification for METI critical infrastructure contracts. |
| AI Specialist Acquisition | Predictive maintenance capabilities in Kansai Manufacturing Belt open steel and chemical processing revenue streams. |
| Bilingual Engineer Retention Program | Japanese-English fluent cloud engineer scarcity constrains global delivery scaling for domestic vendors. |
| Cloud-Native Development Partnership | Fukuoka fintech and gaming clusters generate mid-market demand outside Tokyo-Osaka concentration. |
| Modular Service Unbundling | Automotive tier-1 suppliers in Chubu seek discrete infrastructure and application maintenance contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CIOs at Tokyo megabanks, IT procurement officers at Aichi automotive manufacturers, platform engineers at hyperscale cloud providers, and channel partners in the Kansai region. Secondary validation incorporated METI policy documentation, JIS standards filings, Personal Information Protection Commission guidance, SEC disclosures from listed systems integrators, and prefectural government procurement records. Bottom-up service line sizing and top-down macroeconomic calibration were triangulated to ensure consistency across estimation approaches.
Calibration against historical contract value disclosures and vendor revenue reporting established baseline trajectory credibility across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end-user vertical, and technology maturity tier, with additional granularity on compliance certification status and delivery resourcing mix. CAGRs were derived from trend extrapolation adjusted for policy acceleration effects and vendor capacity constraints. Forecast inputs incorporated METI cloud-first procurement velocity, mainframe skill attrition rates, and datacenter commissioning lead times.
Practitioners should monitor JIS Q 27001 audit queue lengths, hyperscale cloud region expansion announcements, and Society 5.0 implementation grant disbursements for early signals of vendor qualification timeline compression or demand acceleration. Forecasts reflect documented assumptions regarding regulatory stability and certification capacity growth. Quarterly review of METI policy updates, Personal Information Protection Commission enforcement patterns, and tier-n supplier security assessment completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Dealership Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Saas Based HRM Market
Software & Services
Global Cloud Testing Market
Software & Services
Parametric Design Software Market
Software & Services
Global Childcare Management Software Market
Software & Services
Global User Interface Service Market
Software & Services
Talent Management Software Market
Software & Services
Test Management Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Consignment Software Market
Software & Services
Global Presentation Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
Global Internal Communications Software Market