
 Asia-Pacific Saas-Based SCM Market | 2026-2036
Asia-Pacific Saas-Based SCM Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Saas-Based SCM Market Insights
Cloud-native microservices architecture is narrowing the gap between enterprise-grade and mid-market supply chain platforms across Asia-Pacific. SAP SE leverages its S/4HANA Cloud footprint to anchor multi-tier supplier networks in Japan and South Korea. Oracle Corporation competes through autonomous database integration that reduces latency for real-time inventory visibility. Blue Yonder, Inc. specializes in AI-driven demand sensing for consumer goods manufacturers navigating fragmented retail channels.
Asia-Pacific SaaS-based SCM delivers supply chain orchestration through browser-accessible software hosted on distributed cloud infrastructure, typically employing API-first design with sub-second refresh rates for inventory telemetry and predictive analytics engines processing demand signals across multi-echelon networks. The primary commercial purpose centers on replacing on-premise ERP modules with elastic, subscription-priced platforms that synchronize procurement, logistics, and fulfillment decisions without capital-intensive hardware deployment. Public Cloud deployments lead volume adoption among small and mid-sized distributors seeking rapid provisioning without dedicated infrastructure teams, while Hybrid Cloud configurations capture margin pools from manufacturers in regulated sectors requiring on-premises data residency for sensitive supplier pricing. Demand Planning applications are accelerating fastest as semiconductor and automotive OEMs in Taiwan and Vietnam rebuild buffer stock strategies after recent supply shocks exposed the limitations of spreadsheet-based forecasting.
Japan's METI enforces data localization standards through its cloud security guidelines, compelling SCM vendors to maintain in-country processing nodes for sensitive trade documentation. China's SAMR and MIIT jointly administer cross-border data transfer rules under the Personal Information Protection Law, creating compliance thresholds that favor domestic cloud operators or heavily audited foreign platforms. India's TRAI and Ministry of Electronics and Information Technology are drafting cloud service certification frameworks that will determine which SaaS SCM providers qualify for government-linked manufacturing digitization subsidies. Stakeholders must evaluate whether their architecture investments align with diverging national cloud sovereignty regimes or risk exclusion from procurement shortlists in the region's fastest-adopting industrial verticals.
Market Dynamics
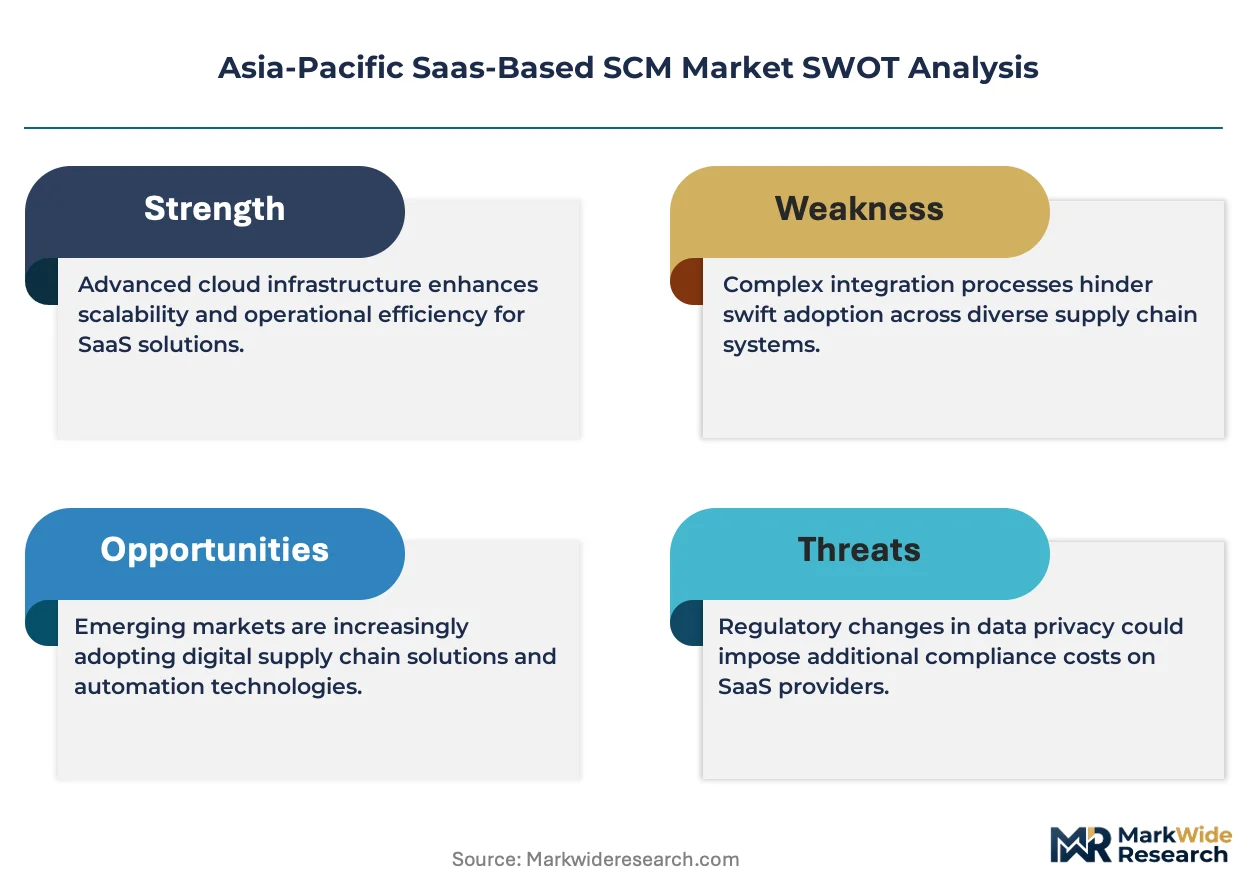
Cloud sovereignty mandates from Japan's METI, China's MIIT, and India's TRAI are fragmenting platform architectures across Asia-Pacific, forcing SaaS SCM vendors to deploy jurisdiction-specific processing nodes rather than centralized regional hubs.
Growth Catalysts
- Japan's METI digital supply chain directives:Mandates for real-time supplier visibility are compelling automotive and electronics OEMs to replace legacy EDI systems with API-native cloud platforms.
- Semiconductor buffer stock rebuilding:Taiwan and Vietnam-based chip fabricators are adopting demand planning modules to manage multi-echelon inventory after recent supply shocks exposed spreadsheet limitations.
- Southeast Asian e-commerce fulfillment networks:Third-party logistics providers in Indonesia and Thailand are accelerating cloud-native platform adoption to handle same-day delivery complexity.
Market Restraints
- Cross-border data transfer compliance costs:China's Personal Information Protection Law administered by SAMR and MIIT creates audit thresholds that favor domestic cloud operators over foreign platforms.
- Mid-market talent scarcity:Shortages of cloud-native SCM architects in India and Vietnam constrain deployment velocity for distributors outside tier-one cities.
- Hybrid cloud infrastructure premiums:Manufacturers in regulated sectors face 40-60% higher total cost of ownership for on-premises data residency configurations versus public cloud alternatives.
Strategic Opportunities
- Australia's mining-to-port logistics corridors:Underpenetrated heavy-asset operators in Western Australia and Queensland present whitespace for predictive maintenance-integrated SCM suites.
- India's PLI-linked manufacturing digitization subsidies:TRAI and MeitY certification frameworks will determine vendor eligibility for government-linked procurement, creating first-mover advantage for compliant platforms.
- AI-driven demand sensing convergence:Machine learning telemetry fused with IoT sensor networks enables consumer goods manufacturers to navigate fragmented retail channels across Southeast Asia.
Industry Challenges
- Legacy ERP integration complexity:On-premise SAP and Oracle systems in Japanese and South Korean enterprises require custom API middleware that extends implementation timelines.
- Multi-jurisdiction certification timelines:Vendors must obtain separate data localization approvals from METI, MIIT, and TRAI, creating 12-18 month go-to-market delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Saas-Based SCM Market |
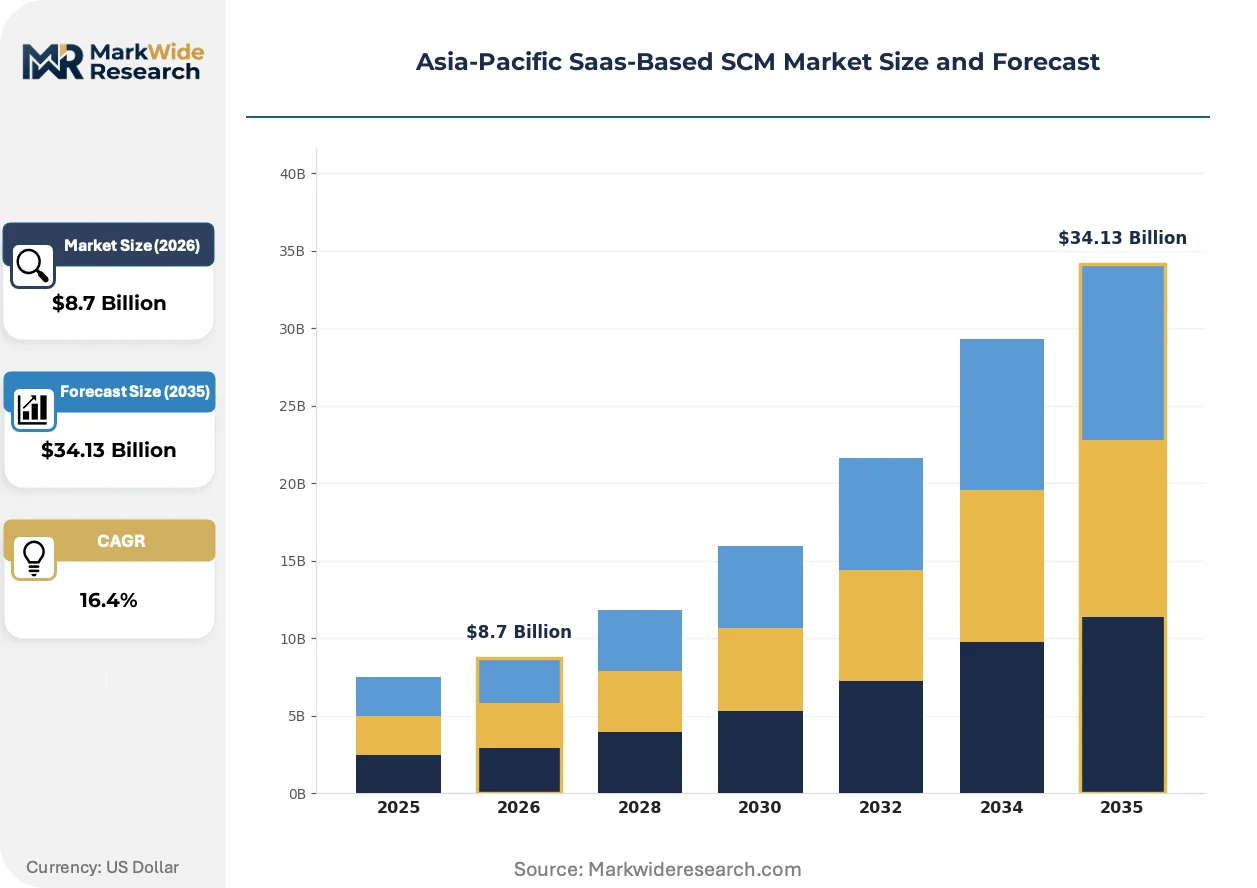
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Inventory Management, Order Fulfillment, Demand Planning, Supplier Collaboration End User: Manufacturers, Retailers, Distributors, Wholesalers Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Consulting, Implementation, Maintenance, Training |
| Companies Covered | IBM Corporation, Accenture PLC, Oracle Corporation, SAP SE, The Descartes Systems Group, Inc., Manhattan Associates, Inc., Blue Yonder, Inc., Infor, Inc., Kinaxis, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Saas-Based SCM Market Trends and Innovations
API-first microservices architectures are compressing deployment cycles for mid-market distributors, while sovereign cloud mandates reshape competitive positioning across Asia-Pacific's fragmented regulatory landscape.
Containerized microservices architecture is collapsing the traditional gap between enterprise-grade and mid-market supply chain platforms. Third-party logistics providers in India and Southeast Asia now provision multi-tenant SCM instances through browser-accessible portals without dedicated infrastructure teams. This compression eliminates the historical 18-24 month implementation advantage held by on-premise ERP incumbents.
China's MIIT cloud computing guidelines and cross-border data transfer rules under the Personal Information Protection Law are tightening data sovereignty requirements. Foreign SaaS SCM vendors must maintain audited in-country processing nodes or risk exclusion from procurement shortlists. Domestic cloud operators including Alibaba Cloud and Huawei Cloud capture margin pools from manufacturers requiring on-premises data residency for sensitive supplier pricing.
Subscription-priced platform procurement is displacing perpetual license models among Australia's mining-to-port logistics operators. Heavy-asset distributors in Western Australia now favor elastic consumption-based pricing that scales with commodity shipment volumes rather than fixed capital deployments. This shift concentrates vendor selection criteria on real-time inventory telemetry refresh rates and predictive analytics engine performance.
Asia-Pacific Saas-Based SCM Market Segmentation
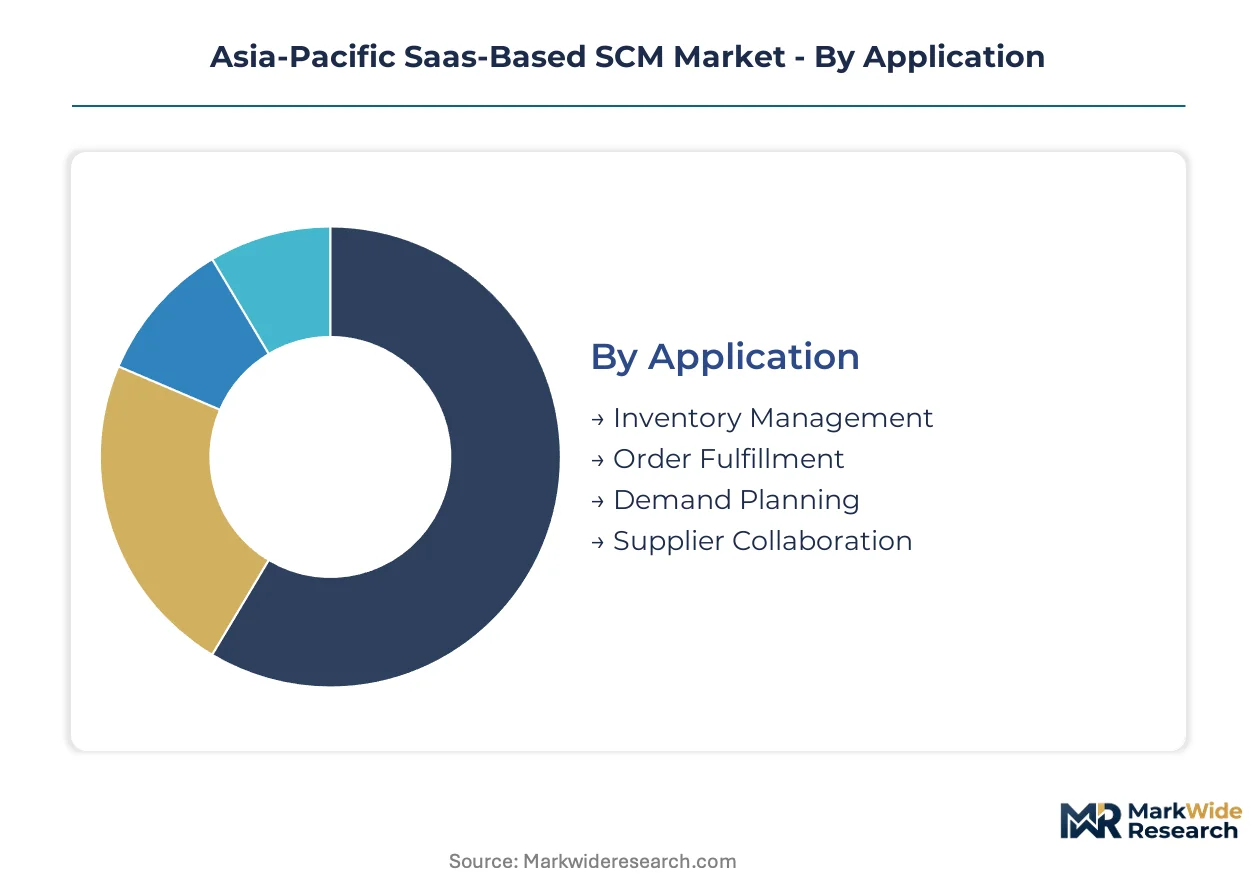
SaaS-based SCM platforms in Asia-Pacific serve divergent operational needs across supply chain functions, deployment architectures, and buyer maturity levels. Segmentation reveals where cloud-native solutions displace legacy systems versus where hybrid configurations preserve data sovereignty compliance.
Application:
Use-case spectrum spans reactive inventory tracking through predictive demand orchestration, with each application tier demanding distinct API throughput and analytics latency specifications.
- Demand Planning:Machine learning engines process multi-echelon demand signals with sub-second refresh rates for semiconductor and automotive OEMs in Taiwan and Vietnam. Buffer stock rebuilding after supply shocks accelerates module adoption as spreadsheet-based forecasting proves inadequate for volatility.
- Inventory Management:Real-time telemetry across distributed warehouses requires IoT sensor integration and API-first microservices architecture. Australia's mining-to-port logistics operators in Western Australia and Queensland deploy these systems for commodity shipment visibility.
- Order Fulfillment:Same-day delivery complexity in Southeast Asian e-commerce networks drives cloud-native platform adoption among third-party logistics providers in Indonesia and Thailand.
- Supplier Collaboration:Multi-tier supplier visibility mandates from Japan's METI compel automotive and electronics OEMs to replace legacy EDI systems with API-native platforms.
The dominant share belongs to Inventory Management, while Demand Planning is closing the gap fastest.
End User:
Buyer sophistication determines deployment velocity, with capital intensity and regulatory exposure shaping platform selection criteria across manufacturing and distribution verticals.
- Manufacturers:Regulated sectors require hybrid cloud configurations with on-premises data residency for sensitive supplier pricing, incurring 40-60% total cost of ownership premiums over public cloud alternatives. China's MIIT guidelines and Japan's METI directives enforce in-country processing nodes.
- Distributors:Mid-market distributors outside India's tier-one cities provision multi-tenant instances through browser-accessible portals without dedicated infrastructure teams, compressing traditional 18-24 month implementation timelines.
- Retailers:Fragmented retail channels across Southeast Asia drive AI-driven demand sensing adoption for consumer goods manufacturers navigating multi-echelon networks.
- Wholesalers:Elastic consumption-based pricing models displace perpetual licenses among heavy-asset operators scaling platform costs with shipment volumes.
Manufacturers command the largest deployment base, though Distributors are expanding most quickly as microservices architectures democratize access.
Deployment:
Infrastructure configuration directly reflects data sovereignty mandates and latency requirements across Asia-Pacific's fragmented regulatory landscape.
- Public Cloud:Small and mid-sized distributors seeking rapid provisioning without dedicated infrastructure teams lead volume adoption. Browser-accessible software hosted on distributed cloud infrastructure eliminates capital-intensive hardware deployment.
- Hybrid Cloud:Margin pools concentrate among manufacturers requiring on-premises data residency for sensitive trade documentation under China's SAMR and MIIT cross-border data transfer rules.
- Private Cloud:Single-tenant deployments serve defense-adjacent manufacturers and critical infrastructure operators with stringent isolation requirements.
- Multi-Cloud:Jurisdiction-specific processing nodes across Alibaba Cloud, Huawei Cloud, and foreign platforms mitigate exclusion risk from procurement shortlists under diverging national cloud sovereignty regimes.
Public Cloud retains the broadest footprint, yet Hybrid Cloud is gaining share fastest as METI, MIIT, and India's TRAI certification frameworks tighten.
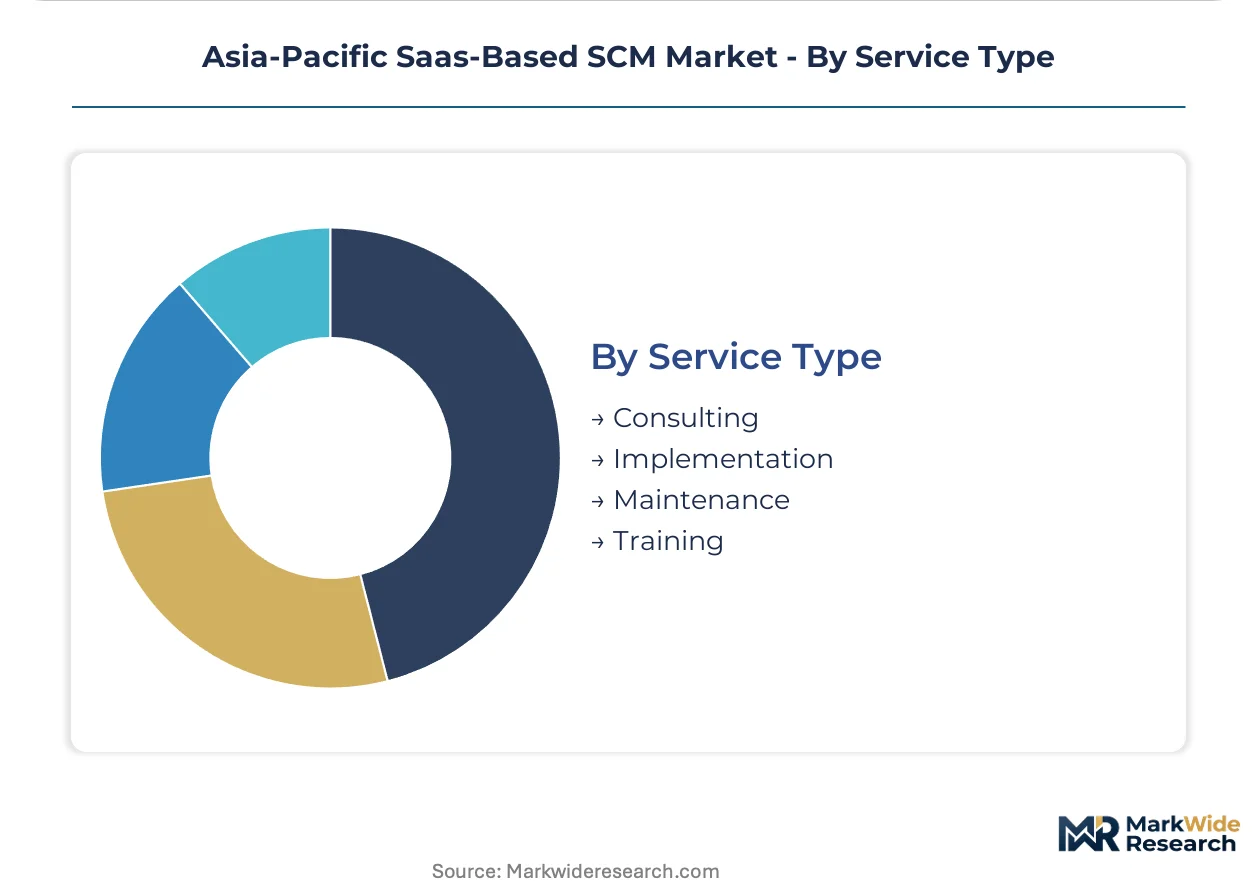
Service Type:
Value capture shifts from perpetual license revenue toward recurring service attachments as subscription-priced platforms displace on-premise ERP modules.
- Implementation:Custom API middleware for legacy SAP and Oracle integration in Japanese and South Korean enterprises extends project timelines but commands premium pricing.
- Consulting:Cloud-native SCM architects in India and Vietnam remain scarce, constraining deployment velocity and inflating day rates for tier-one city specialists.
- Maintenance:Continuous compliance updates for METI, MIIT, and TRAI data localization approvals create 12-18 month recurring revenue streams.
- Training:Mid-market talent scarcity drives knowledge transfer investments as distributors build internal platform administration capabilities.
Implementation generates the highest absolute revenue, while Consulting exhibits the steepest expansion trajectory amid talent shortages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's mining-to-port logistics corridors export iron ore and coal to China, Japan, and South Korea, generating concentrated demand for predictive maintenance-integrated SCM suites across Western Australia and Queensland.
China
Semiconductor fabricators in Taiwan and Vietnam source equipment through Chinese distributors, accelerating cloud-native platform adoption for multi-echelon inventory management. MIIT cloud computing guidelines and SAMR cross-border data transfer rules under the Personal Information Protection Law enforce in-country processing nodes. Yangtze River Delta manufacturers deploy hybrid cloud configurations to preserve data residency for sensitive supplier pricing.
Japan
Automotive and electronics OEMs rebuild supplier networks after recent disruptions, replacing legacy EDI systems with API-native platforms. METI digital supply chain directives mandate real-time supplier visibility and enforce data localization standards through cloud security guidelines. Kanto region manufacturers in Tokyo and surrounding prefectures anchor demand for multi-tier supplier network orchestration.
India
Third-party logistics providers outside tier-one cities provision multi-tenant SCM instances to handle e-commerce fulfillment complexity for domestic and export markets. TRAI and MeitY cloud service certification frameworks determine vendor eligibility for PLI-linked manufacturing digitization subsidies. Maharashtra and Karnataka industrial corridors concentrate deployment velocity as mid-market distributors compress traditional implementation timelines.
Australia
Heavy-asset mining operators in Western Australia and Queensland favor elastic consumption-based pricing that scales with commodity shipment volumes rather than fixed capital deployments. National data sovereignty requirements intersect with state-level mining regulations to shape platform selection criteria. Perth-to-Pilbara logistics corridors drive demand for real-time inventory telemetry and predictive analytics engine performance.
Southeast Asia
Indonesian and Thai third-party logistics providers accelerate cloud-native platform adoption to manage same-day delivery complexity across fragmented retail channels. Divergent national cloud frameworks in Indonesia, Thailand, Vietnam, and Singapore create multi-jurisdiction certification requirements. Jakarta and Bangkok metropolitan fulfillment networks concentrate demand for AI-driven demand sensing integrated with IoT sensor networks.
Asia-Pacific Saas-Based SCM Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages concentrate among established platform vendors. The vendor base organizes around three strategic archetypes: enterprise ERP incumbents with cloud migration capabilities, pure-play SCM specialists with AI-native architectures, and systems integrators with implementation scale. Dominant competitive moves include geographic node deployment for data sovereignty compliance and API-first microservices development for mid-market penetration.
Within the enterprise ERP tier, SAP SE and Oracle Corporation occupy positions anchored by existing customer relationships and database integration capabilities. Blue Yonder, Inc. exemplifies the AI-native specialist archetype with demand sensing capabilities. IBM Corporation and Accenture PLC represent the systems integrator tier with implementation and consulting scale. Each archetype faces distinct constraints: ERP incumbents navigate legacy integration complexity, specialists confront certification timeline delays, and integrators compete for scarce cloud-native SCM architect talent.
| Leading Market Players |
|---|
| IBM Corporation |
| Accenture PLC |
| Oracle Corporation |
| SAP SE |
| The Descartes Systems Group, Inc. |
| Manhattan Associates, Inc. |
| Blue Yonder, Inc. |
| Infor, Inc. |
| Kinaxis, Inc. |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta cloud infrastructure clusters anchor capacity deployment for SaaS SCM platforms, concentrating compute supply in Shanghai and Hangzhou nodes that shape downstream subscription pricing power across Chinese manufacturing verticals.
Pricing Analysis
Cost-plus contracts with API transaction volume indexation dominate enterprise procurement in Japan and South Korea. Three-tier pricing structure across premium, standard, and economy levels separates multi-tenant public cloud deployments from hybrid configurations with on-premises data residency. Cost compression in mid-market segments is intensifying because containerized microservices architectures eliminate historical implementation premiums. Small distributors in India's tier-two cities exhibit highest price sensitivity, while Japanese automotive OEMs prioritize real-time telemetry performance over subscription cost.
Supply Chain Analysis
Upstream feedstock for cloud-native SCM platforms draws from semiconductor fabrication in Taiwan, data center construction materials in China, and specialized engineering talent pools in India and Vietnam. Platform development rests on GPU compute clusters, low-latency networking hardware, and API middleware libraries. Single-source vulnerability concentrates in Taiwan's advanced chip packaging capacity for AI inference engines. Distribution runs through direct enterprise sales teams in Japan and South Korea, partnered systems integrators in Australia, and hyperscaler marketplaces in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cloud-native SCM architects capable of navigating Japan's METI certification requirements and China's MIIT data localization rules constrains deployment velocity across the region's fastest-growing manufacturing corridors.
For Market Incumbents: Insulate recurring revenue streams by embedding predictive analytics modules deeply into existing S/4HANA and Oracle Cloud footprints, creating switching costs that resist pure-play AI-native specialists. Prioritize vertical integration into sovereign cloud node operations across Tokyo, Shanghai, and Mumbai to preempt certification delays that favor domestic operators. For New Entrants and Emerging Players: Pursue whitespace in Australia's mining-to-port logistics corridors where predictive maintenance-integrated SCM suites remain underpenetrated among Western Australian heavy-asset operators. Target mid-market distributors in India's Maharashtra and Karnataka industrial corridors through browser-accessible microservices platforms that compress traditional implementation timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-native demand sensing specialists with proven API-first architectures over legacy ERP migration services. Long-term viability hinges on compliance automation capabilities that reduce 12-18 month certification timelines across METI, MIIT, and TRAI frameworks. Watch for inflection when India's PLI-linked manufacturing digitization subsidies release approved vendor shortlists.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Node Deployment | METI and MIIT compliance requirements favor vendors with in-country Tokyo and Shanghai processing infrastructure. |
| API-First Microservices Development | Containerized architectures compress 18-24 month implementation timelines for India's mid-market distributors. |
| AI-Driven Demand Sensing Integration | Machine learning telemetry fused with IoT networks serves Southeast Asian consumer goods manufacturers. |
| Legacy ERP Middleware Investment | Custom SAP and Oracle integration capabilities capture premium implementation revenue in Japanese enterprises. |
| PLI Certification Pre-Positioning | TRAI and MeitY framework alignment determines eligibility for India's government-linked manufacturing subsidies. |
Research Methodology
A standing panel of cloud platform engineers, supply chain operations directors, regulatory compliance officers, and IT procurement managers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews with CTOs at Japanese automotive OEMs, logistics heads at Australian mining operators, and integration specialists at Indian third-party logistics providers combined with MIIT policy filings, TRAI certification databases, hyperscaler capex disclosures, and customs trade data. Bottom-up deployment estimates triangulated against top-down cloud infrastructure spending projections.
Scenario-bracketing around data sovereignty enforcement intensity and microservices adoption velocity shaped projections across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted subscription pricing trajectories and infrastructure capacity expansion curves. Forecast inputs incorporated semiconductor buffer stock rebuilding patterns and e-commerce fulfillment network buildouts.
Sensitivities concentrate around MIIT cross-border data transfer rule enforcement and TRAI certification timeline delays. Forecasts reflect documented assumptions regarding sovereign cloud mandate adoption rates. Cross-checking against hyperscaler regional revenue disclosures and industrial cloud spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Proofing Software Market
Software & Services
Gym Management Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Talent Management Software Market
Software & Services
Device Tracking Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Fitness App Market
Software & Services
Software Market
Software & Services
Global Document Control Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Cemetery Management Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Global App Builder Software Market
Software & Services
Interior Design Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market