
 Emotion Recognition and Sentiment Analysis Software Market | 2026-2036
Emotion Recognition and Sentiment Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Emotion Recognition and Sentiment Analysis Software Market Foresight
The capability gap between cloud-native platform providers and legacy on-premise vendors is unwinding competitive dynamics across the sector. Microsoft leverages its Azure cognitive services infrastructure to anchor enterprise deployments at scale. IBM sustains differentiation through specialized Watson NLP toolkits tailored to regulated industries. Affectiva competes by dominating automotive cabin monitoring applications with proprietary facial coding algorithms.
Emotion recognition and sentiment analysis software encompasses computational systems that detect, classify, and interpret human affective states through multimodal signal processing of text, facial micro-expressions, vocal prosody, and biometric patterns. These platforms employ deep learning architectures including convolutional neural networks for image-based analysis and transformer models for linguistic sentiment scoring, primarily serving commercial objectives in customer experience optimization, mental health screening, and adaptive human-machine interface design. Text analysis solutions occupy mature margin pools in social media monitoring and brand intelligence, while video analytics represents the fastest-expanding segment driven by real-time processing demands in retail footfall analysis and broadcast audience measurement. Cloud-based deployment leads volume adoption though edge computing configurations are gaining traction where latency constraints govern interactive applications such as in-vehicle driver alertness systems.
The EU AI Act classifies emotion recognition in workplaces and educational settings as high-risk AI, mandating conformity assessments and human oversight protocols that directly shape product architecture decisions for vendors seeking European market access. The FDA exercises oversight through software-as-medical-device pathways when these tools claim diagnostic utility for psychiatric or neurological conditions, creating a bifurcated regulatory landscape between wellness-adjacent and clinical-grade applications. China's SAMR and GB standards frameworks impose algorithmic transparency and data localization requirements that condition how multinational providers structure their China-facing operations. Stakeholders must monitor evolving jurisdictional definitions of biometric data and consent mechanisms as these determine both technical feasibility and market entry viability across deployment scenarios.
Market Dynamics
The EU AI Act's high-risk classification of workplace emotion recognition is forcing architectural redesigns across vendor product roadmaps, compressing deployment timelines for European market entry while elevating compliance costs.
Growth Catalysts
- Telehealth patient monitoring:Healthcare providers deploy multimodal affect detection during virtual consultations to flag depression markers and medication adherence signals. The FDA's software-as-medical-device pathway creates reimbursement visibility for clinical-grade tools.
- EU AI Act transparency mandates:Workplace emotion recognition systems face mandatory conformity assessments and human oversight protocols. Vendors investing early in explainable AI architectures capture first-mover positioning in European enterprise accounts.
- Automotive cabin monitoring:Driver drowsiness and distraction detection systems integrate facial coding and gaze tracking. Edge computing configurations address latency constraints for real-time intervention triggering.
Market Restraints
- Biometric data localization requirements:China's SAMR and GB standards frameworks mandate algorithmic transparency and domestic data storage. Multinational providers face operational fragmentation between China-facing and global infrastructure.
- Facial action unit annotation costs:Ground-truth labeling of micro-expressions requires specialized psychology-trained annotators. Labor scarcity in affective computing datasets constrains model training scale.
- Substitute signal sources:Wearable biometric sensors and voice-only sentiment classifiers capture overlapping use cases at lower privacy friction. Text analytics maintains mature margin pools without visual consent complexity.
Strategic Opportunities
- Retail footfall analytics:Real-time shopper emotion tracking in physical stores enables dynamic merchandising and staff deployment. Privacy-preserving edge processing addresses surveillance concerns in European and North American deployments.
- Convergence of transformer NLP and computer vision:Unified multimodal architectures reduce inference costs and enable cross-modal sentiment validation. Broadcast audience measurement vendors adopt fused text-image-audio pipelines for engagement scoring.
- India's digital public infrastructure:The country's telemedicine expansion and mental health screening programs create procurement pathways for affective computing tools. BIS certification frameworks for AI systems are stabilizing vendor entry requirements.
Industry Challenges
- Cross-cultural affect annotation:Facial expression interpretation varies across demographic groups, introducing bias risks that trigger regulatory scrutiny under GDPR and emerging algorithmic accountability frameworks.
- Integration with legacy contact center infrastructure:Real-time sentiment APIs must interface with decades-old telephony and CRM systems. Deployment complexity extends sales cycles and elevates professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emotion Recognition and Sentiment Analysis Software Market |
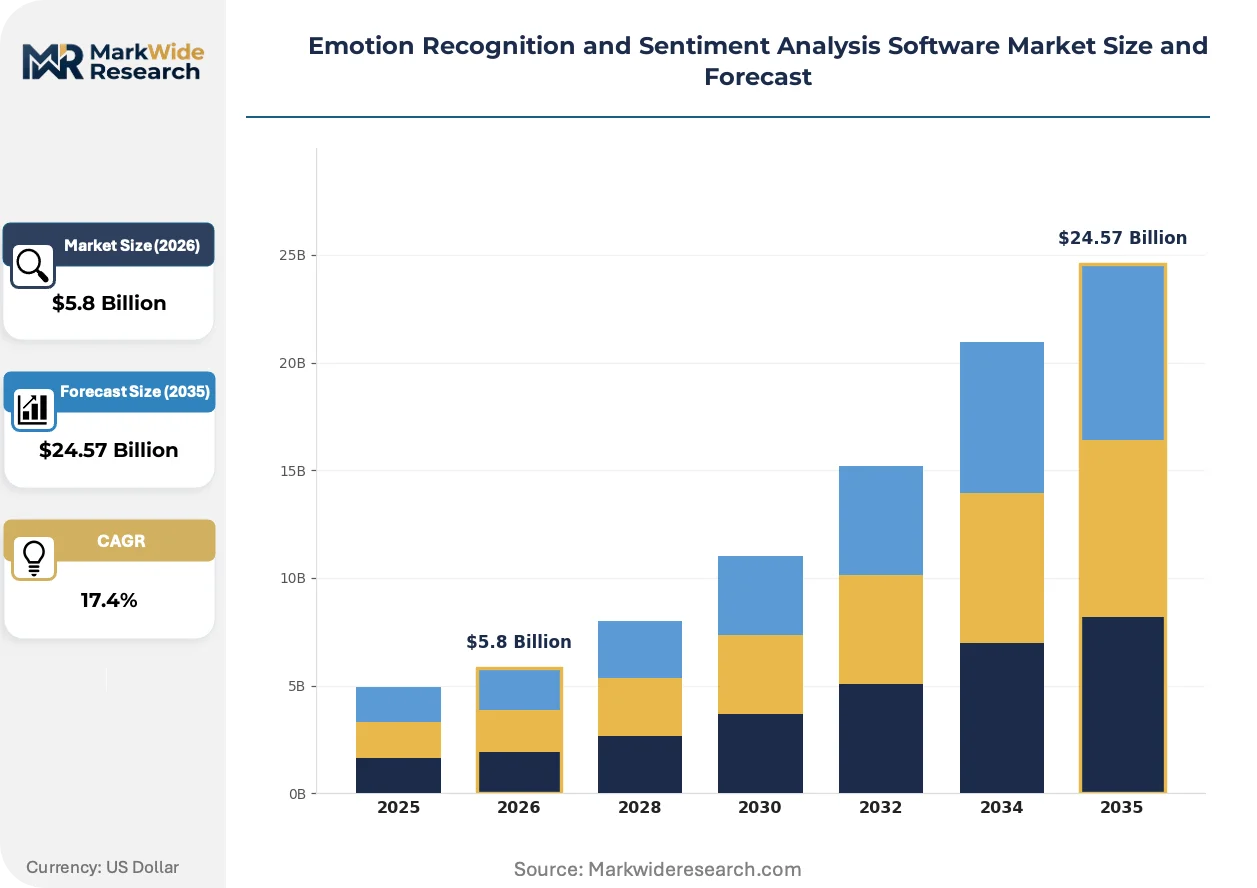
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $24.57 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Analysis, Facial Recognition, Speech Recognition, Video Analytics Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Retail, Healthcare, Education, Media Solution: API, SDK, Standalone Software, Integrated Platform |
| Companies Covered | IBM, Microsoft, Google, Apple, NEC Corporation, Affectiva, Intel, Noldus Information Technology, Realeyes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emotion Recognition and Sentiment Analysis Software Market Shifts & Advancements
Transformer-based architectures are collapsing the historical separation between text sentiment analysis and visual affect recognition, enabling unified multimodal platforms that reduce vendor fragmentation and inference costs.
Federated learning architectures are decomposing centralized model training for facial and vocal affect recognition. Healthcare systems and automotive OEMs adopt privacy-preserving collaborative learning to pool behavioral signals without raw biometric data exchange. This compression of data sovereignty constraints accelerates deployment in GDPR-regulated European markets and HIPAA-covered US health networks.
The EU AI Act's high-risk classification for workplace and educational emotion recognition imposes mandatory conformity assessments and human-in-the-loop protocols. Product teams rearchitect real-time dashboards to embed explanation layers and operator override mechanisms. Vendors targeting French and German enterprise accounts prioritize these features to secure procurement eligibility.
Enterprise buyers increasingly unbundle emotion recognition software from bundled customer experience suites. Standalone API-first vendors capture procurement preference through modular integration with existing contact center infrastructure. This pattern concentrates in US-based enterprise call centers where IT departments prioritize composable architecture over monolithic platform replacement.
Emotion Recognition and Sentiment Analysis Software Market Segmentation
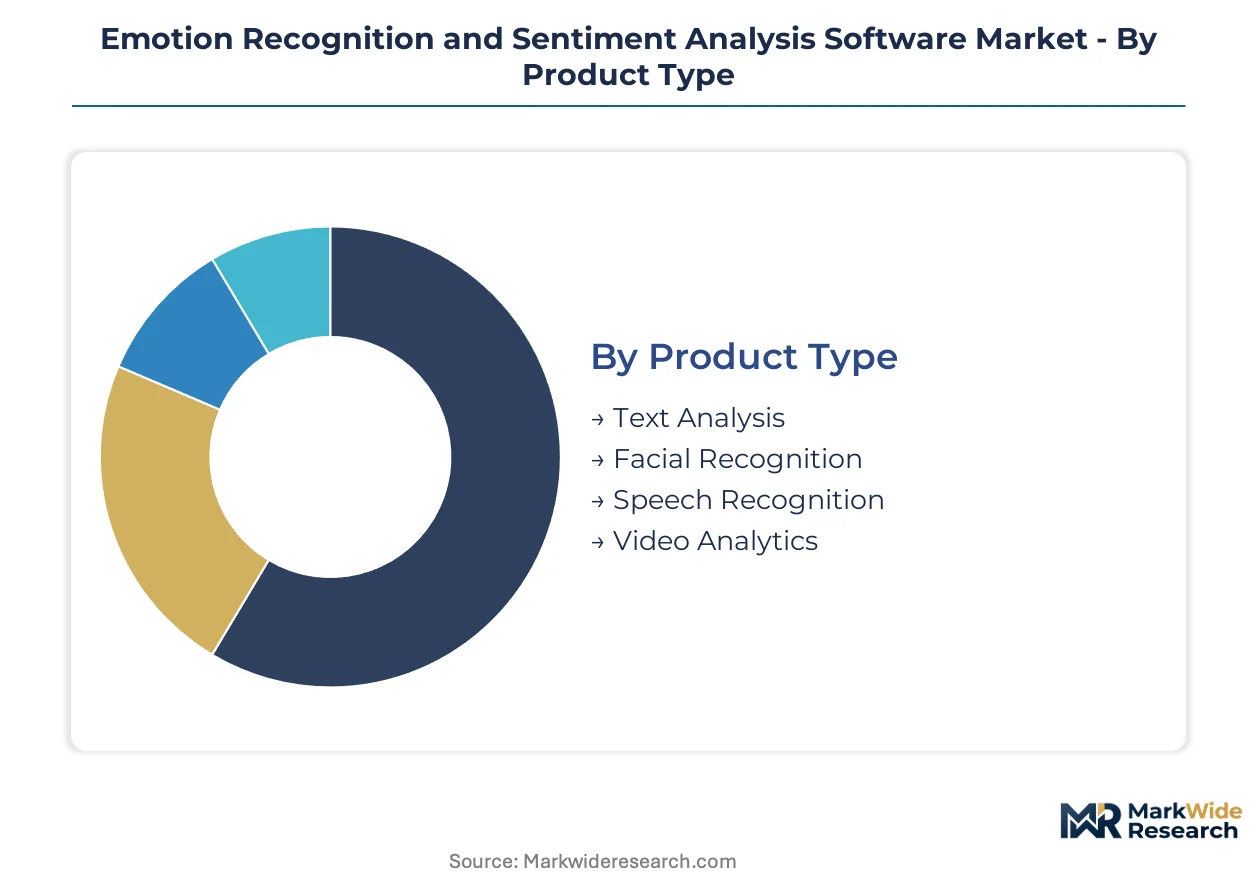
Segmentation in emotion recognition and sentiment analysis software reveals how technical architecture choices reshape competitive boundaries. Vendors must align product configurations with deployment constraints, end-use compliance requirements, and integration preferences that vary sharply across healthcare, retail, and media verticals.
Product Type:
Text analysis solutions face intensifying substitution pressure from large language model APIs, while video analytics segments defend differentiation through proprietary edge-optimized inference engines.
- Text Analysis:Linguistic sentiment scoring systems parse social media, reviews, and customer communications using transformer-based architectures. Enterprise call centers in the United States drive procurement for real-time agent coaching dashboards, though commoditization pressure from general-purpose NLP APIs compresses pricing power.
- Facial Recognition:Micro-expression decoding platforms employ convolutional neural networks trained on facial action unit datasets. Automotive cabin monitoring applications in Germany and Japan sustain premium positioning through regulatory alignment with driver safety mandates.
- Speech Recognition:Prosodic analysis tools extract emotional valence from vocal pitch, rhythm, and spectral features.
- Video Analytics:Multimodal platforms fuse facial, gestural, and contextual cues for real-time audience measurement.
Text analysis anchors the volume base while video analytics gains share at the steepest rate.
Deployment:
Cost tier stratification separates high-touch enterprise implementations from self-serve API consumption, with hybrid architectures capturing mid-market accounts seeking gradual cloud migration.
- On-Premise:Self-managed installations within enterprise data centers address stringent data residency requirements. Financial services institutions in Switzerland and Singapore maintain on-premise deployments for trader communication surveillance under national banking secrecy frameworks.
- Cloud-Based:Scalable SaaS delivery models enable rapid provisioning for seasonal campaign analytics. Marketing agencies across France and the United Kingdom favor consumption-based pricing for brand sentiment monitoring during product launches.
- Hybrid:Split architectures process sensitive biometric data locally while aggregating analytics in cloud environments.
- Edge Computing:Embedded inference engines minimize latency for interactive applications.
Cloud-based deployment commands the largest revenue pool while edge computing expands most quickly in automotive and retail footfall use cases.
End User:
Application maturity varies dramatically, with healthcare and retail representing proven revenue verticals while education faces regulatory headwinds from the EU AI Act's high-risk classification.
- Healthcare:Clinical-grade affect detection supports telehealth depression screening and medication adherence monitoring. The FDA's software-as-medical-device pathway creates reimbursement visibility for diagnostic tools deployed in US health systems.
- Retail:Shopper emotion tracking enables dynamic merchandising and staff deployment optimization. Privacy-preserving edge processing addresses surveillance concerns in European and North American physical store networks.
- Education:Student engagement monitoring systems face compliance complexity under GDPR and emerging algorithmic accountability frameworks.
- Media:Broadcast audience measurement vendors adopt fused pipelines for engagement scoring.
Healthcare anchors the volume base while retail climbs the fastest as physical stores invest in competitive differentiation against e-commerce.
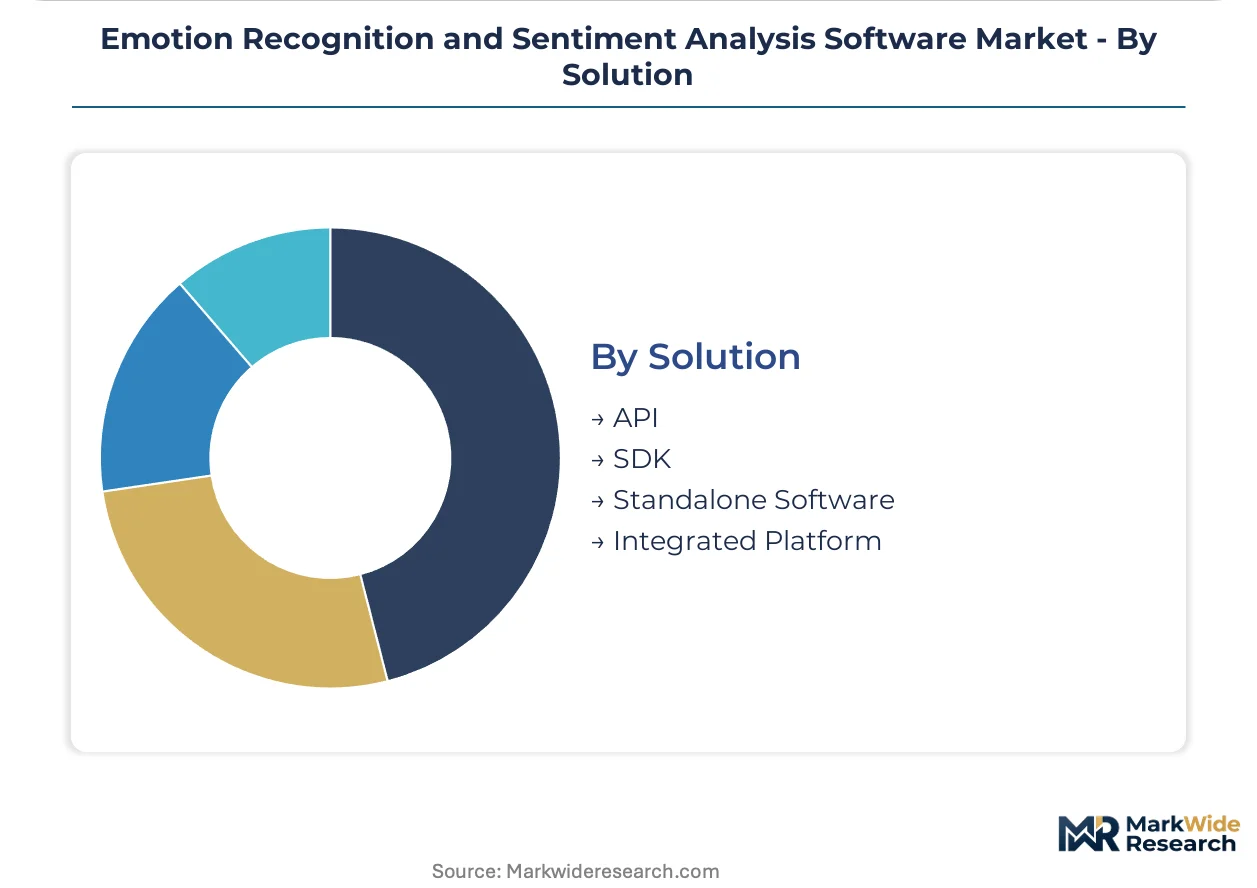
Solution:
Customer type preferences split between developer-centric tooling and business-user platforms, with API-first vendors capturing procurement preference in IT-led organizations.
- API:RESTful and gRPC endpoints enable modular integration with existing contact center infrastructure. US-based enterprise IT departments prioritize composable architecture over monolithic platform replacement.
- SDK:Native client libraries for iOS, Android, and embedded systems support automotive OEM integration timelines.
- Standalone Software:Full-featured applications with proprietary user interfaces target line-of-business buyers.
- Integrated Platform:Bundled customer experience suites face unbundling pressure as buyers seek best-of-breed components.
API solutions anchor the volume base while SDK offerings gain share fastest in automotive and mobile developer ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in the United States deploy multimodal affect detection during telehealth consultations, while German automotive OEMs prioritize cabin monitoring for driver safety compliance, and Chinese platforms navigate algorithmic transparency mandates under SAMR frameworks.
United States
Enterprise call centers in Dallas and Atlanta drive procurement for real-time customer sentiment tracking APIs. The FDA's software-as-medical-device pathway creates reimbursement visibility for clinical-grade depression screening tools. Boston-area health networks integrate affective computing into virtual mental health consultations.
Germany
Automotive manufacturers in Stuttgart and Munich embed facial coding systems for drowsiness detection in premium vehicle lines. The EU AI Act mandates conformity assessments for workplace emotion recognition, forcing architectural redesigns in enterprise software. Frankfurt's financial services sector maintains on-premise deployments for trader surveillance under national banking secrecy frameworks.
China
Domestic technology platforms process sentiment signals for social media monitoring and brand intelligence at massive scale. SAMR and GB standards frameworks impose algorithmic transparency and data localization requirements. Beijing and Shanghai clusters concentrate development of voice-only sentiment classifiers that circumvent visual consent complexity.
United Kingdom
Marketing agencies in London favor consumption-based cloud pricing for campaign analytics during product launches. GDPR enforcement shapes biometric data consent mechanisms for retail footfall analytics deployments. Manchester and Birmingham contact centers unbundle emotion recognition APIs from monolithic customer experience suites.
India
Telemedicine expansion and national mental health screening programs create procurement pathways for affective computing vendors. BIS certification frameworks for AI systems stabilize market entry requirements. Bengaluru and Hyderabad clusters host development centers for edge-optimized inference engines targeting automotive and mobile applications.
Emotion Recognition and Sentiment Analysis Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-native platform providers unwinding legacy on-premise vendor positions through scalable infrastructure. The market structure separates horizontally integrated cognitive service suites from vertically specialized facial coding and prosodic analysis toolkits. Two strategic archetypes dominate: enterprise platform vendors leveraging existing cloud footprints, and domain-specific specialists commanding premium positioning in regulated verticals. Competitive moves concentrate on API-first modularization to capture unbundling preferences, and federated learning architectures to address data sovereignty constraints.
Within the integrated platform tier, Microsoft and IBM exemplify divergent positioning strategies, with the former anchoring enterprise deployments through cognitive services infrastructure and the latter sustaining differentiation through specialized NLP toolkits for regulated industries. Affectiva occupies a specialist position representing automotive cabin monitoring applications. NEC Corporation sits within the diversified technology conglomerate archetype, while Google and Apple represent consumer-facing platform extensions into affective computing capabilities.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Apple |
| NEC Corporation |
| Affectiva |
| Intel |
| Noldus Information Technology |
| Realeyes |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with hyperscale cloud providers lock in both GPU cluster access and inference cost visibility for emotion AI vendors serving European enterprise accounts under EU AI Act compliance timelines. These arrangements insulate procurement teams from spot-market volatility in AI accelerator hardware while embedding price predictability into multi-year SaaS agreements.
Pricing Analysis
Professional services and API overage tiers drive lifetime value in emotion recognition software, with vendors bundling implementation support and custom model retraining into enterprise contracts. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade FDA-cleared tools from wellness-adjacent applications and basic sentiment APIs. Cost compression in text analytics is intensifying because general-purpose large language models absorb linguistic sentiment scoring use cases without specialized licensing. Mid-market healthcare IT departments exhibit highest price sensitivity, while automotive OEMs prioritize latency performance and regulatory alignment over unit economics.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Los Angeles trade lane periodically constrain edge hardware delivery timelines for automotive cabin monitoring deployments. GPU and AI accelerator supply concentrates in Taiwan, South Korea, and the United States, with NVIDIA and AMD fabrication tethered to TSMC's advanced node capacity. Specialized facial action unit annotation labor draws from psychology-trained workforces in India and Eastern Europe, creating single-source vulnerability in ground-truth dataset production. Distribution runs through direct enterprise sales teams for regulated verticals and self-serve API portals for developer-centric adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent emotion recognition vendors face substitution pressure from general-purpose multimodal AI platforms that absorb sentiment scoring as a commodity feature. Defense requires structural repositioning rather than incremental product improvement.
For Market Incumbents: Secure first-mover positioning in EU AI Act-compliant explainable AI architectures before conformity assessment deadlines harden procurement eligibility. Deepen backward integration into proprietary facial action unit datasets to differentiate from API-commoditized text sentiment tools. Vertical integration into edge-optimized inference engines protects automotive cabin monitoring margins against hyperscaler encroachment. For New Entrants and Emerging Players: BIS certification fast-tracks for India's telemedicine and mental health screening programs open procurement pathways without entrenched vendor relationships. Target retail footfall analytics in European and North American physical store networks where privacy-preserving edge processing creates technical differentiation against cloud-native incumbents. API-first modular positioning captures unbundling preferences in US enterprise call centers seeking composable architecture over monolithic replacement. For Investors and Strategic Acquirers: Capital is best deployed toward federated learning specialists with privacy-preserving architectures that unlock GDPR-regulated European healthcare and automotive deployments. Long-term viability hinges on regulatory moats rather than model performance alone. Watch FDA software-as-medical-device clearance velocity as the inflection indicator distinguishing clinical-grade reimbursement visibility from wellness-adjacent commodity positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Mandatory human-in-the-loop protocols reshape product architecture for European market access eligibility. |
| Federated Learning Deployment | Privacy-preserving collaborative learning pools behavioral signals without raw biometric data exchange under GDPR. |
| Edge-Optimized Inference Engine | Embedded processing minimizes latency for real-time driver drowsiness detection in automotive cabin systems. |
| API-First Modularization | RESTful endpoints capture procurement preference in US enterprise IT departments prioritizing composable architecture. |
| FDA Software-as-Medical-Device Pathway | Reimbursement visibility for clinical-grade depression screening tools differentiates from wellness-adjacent applications. |
Research Methodology
Operator-level perspectives from CTOs at enterprise call centers, biomedical engineers at US health networks, automotive platform integration leads, and AI procurement officers at European retailers anchored the qualitative base. These primary interviews combined with secondary validation against FDA 510(k) filings, EU AI Act implementation guidance, SAMR algorithmic transparency disclosures, and hyperscaler cognitive services pricing documentation. Bottom-up deployment estimates across cloud, edge, and on-premise configurations triangulated against top-down addressable market sizing by vertical application.
Sensitivity analysis tested forecast outputs against alternative regulatory implementation timelines and GPU supply constraint scenarios across the analysis window. The analytical framework modeled segmentation dimensions including deployment architecture, solution type, end-use vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating telehealth adoption rates, automotive safety mandate enforcement schedules, and retail footfall analytics investment cycles. Industry-specific inputs included FDA software-as-medical-device clearance pipelines and EU AI Act conformity assessment completion rates.
Underlying assumptions cover sustained cloud infrastructure investment, stable BIS certification timelines for India entry, and gradual EU AI Act enforcement without retroactive application, with deviation risk concentrated in facial annotation labor supply constraints and hyperscaler platform consolidation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Semiconductor Fabrication Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Ad Creation Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Global Funeral Home Software Market
Software & Services
Server Software Market
Software & Services
Global Document Control Software Market
Software & Services
Lending Software Market
Software & Services
Subscription Management Software Market
Software & Services
Global Salesforce Appexchange Tools Market