
 Video Communications Software Market | 2026-2036
Video Communications Software Market Size, Share, and Industry Trends Forecast 2026-2036
Video Communications Software Market Insights
The gap between proprietary codecs and open standards is narrowing as WebRTC and AV1 compression protocols mature. Zoom Video Communications leverages its native codec optimization to sustain low-latency performance at scale. Microsoft Corporation anchors its enterprise position through deep Azure integration and Teams ecosystem lock-in. Cisco Systems competes on security-certified infrastructure for government and financial verticals.
Video communications software encompasses real-time audio-visual transmission platforms that encode, route, and decode media streams across IP networks using H.264, VP9, or AV1 codecs with sub-200ms latency targets. These systems serve commercial and institutional users for remote collaboration, telehealth delivery, virtual instruction, and digital customer engagement. Cloud-based deployment leads in new subscriber additions due to elastic scaling and reduced capital burden, while on-premise installations retain preference among defense contractors and regulated financial institutions where data sovereignty overrides cost considerations. The education end-user segment shows structural expansion as Learning Management System integrations become standard procurement requirements.
FCC net neutrality rulings in the United States, GDPR data residency requirements in Europe, and China's MIIT cybersecurity review standards collectively shape product architecture and geographic market access decisions. HIPAA encryption mandates for healthcare transmissions and EU AI Act transparency obligations for automated meeting transcription further complicate compliance engineering. Stakeholders must weigh codec licensing costs against interoperability guarantees when selecting platform architectures for multi-jurisdiction deployments.
Market Dynamics
Cloud migration among enterprise buyers is compressing infrastructure decision cycles from multi-year CapEx planning to elastic OpEx scaling, forcing incumbent vendors to rearchitect delivery models around containerized deployment and consumption-based metering.
Growth Catalysts
- HIPAA encryption mandates:Healthcare providers in the United States must deploy end-to-end encrypted transmission for telemedicine reimbursement eligibility, creating procurement urgency for certified platforms.
- AV1 codec maturation:Royalty-free compression is reducing bandwidth costs for high-resolution video delivery, accelerating adoption among education technology platforms and remote instruction providers.
- Germany:Industrial Mittelstand firms are consolidating dispersed engineering teams through unified communications, driving seat expansion in manufacturing verticals previously resistant to cloud adoption.
Market Restraints
- Codec licensing cost volatility:H.264 and H.265 patent pool obligations create unpredictable royalty burdens for vendors serving high-volume transmission use cases.
- Data center concentration risk:Hyperscaler reliance on Virginia, Frankfurt, and Tokyo regions creates single-point-of-failure exposure for latency-sensitive financial trading floor deployments.
- GDPR data residency friction:Cross-border media routing between EU member states and third countries requires architectural segmentation that inflates operational complexity.
Strategic Opportunities
- Japan METI digital workplace incentives:Government subsidies for SMB cloud adoption are opening underpenetrated mid-market segments outside Tokyo-Osaka corridors.
- AI-powered real-time translation:Convergence of neural machine translation with low-latency streaming is enabling monolingual enterprise buyers to support multilingual customer service operations without human interpreter overhead.
- Edge computing distribution:5G network slicing is creating new channel partnerships with telecommunications carriers for on-premise media processing at manufacturing plant floors.
Industry Challenges
- WebRTC engineering talent scarcity:Specialized real-time media pipeline development skills command premium compensation, constraining vendor R&D velocity.
- EU AI Act transparency timelines:Automated meeting transcription and sentiment analysis features require algorithmic audit documentation that extends compliance engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Communications Software Market |
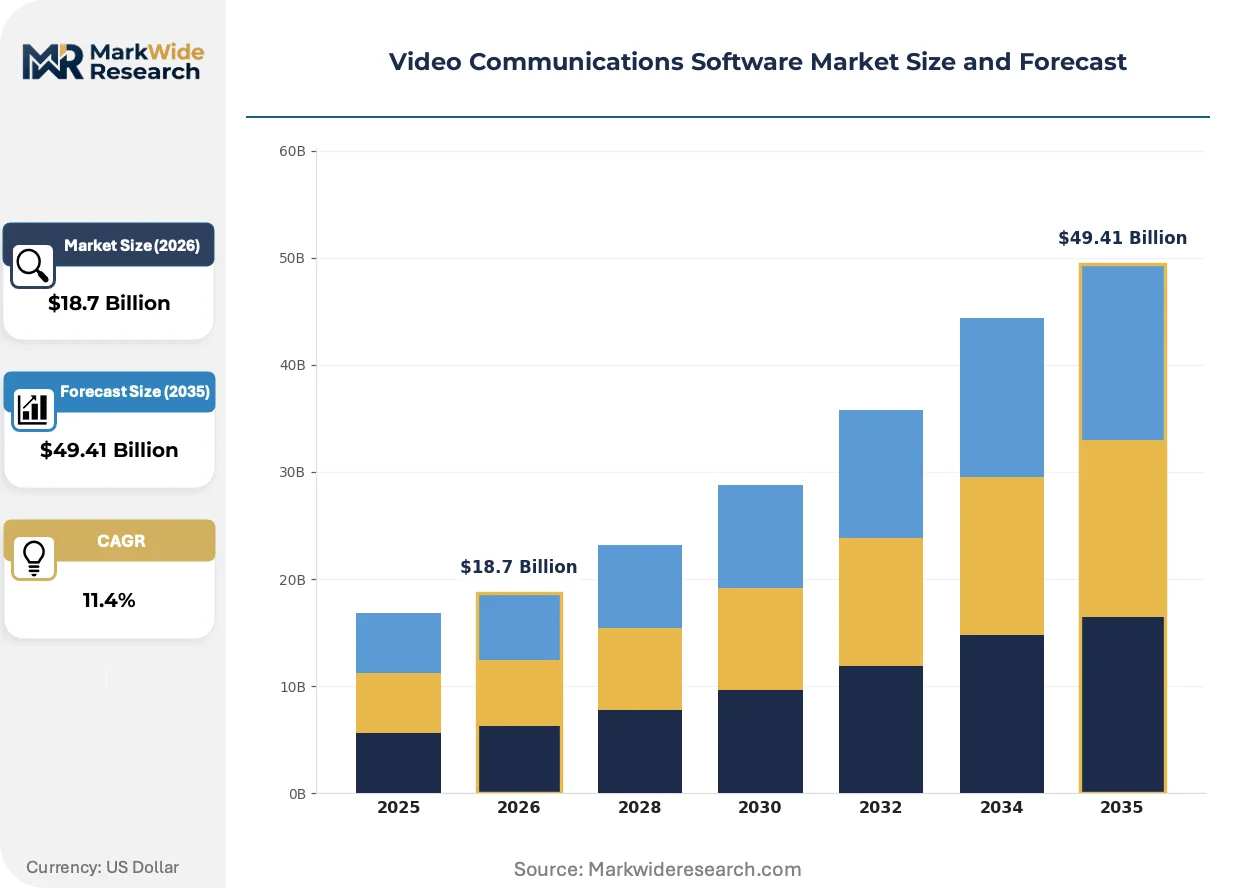
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Enterprise, Education, Healthcare, Government Feature: Screen Sharing, Recording, Virtual Backgrounds, Chat Integration Service Type: Webinars, Conferencing, Support, Training |
| Companies Covered | Zoom Video Communications, Microsoft Corporation, Cisco Systems, Google, Adobe Systems, Huawei Technologies, Avaya, Polycom, Logitech International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Communications Software Market Trends and Innovations
Compression efficiency breakthroughs and regulatory transparency mandates are simultaneously reshaping technical roadmaps and compliance engineering priorities across vendor organizations.
AV1 open-source codec deployment is rendering obsolete legacy H.264 infrastructure for 4K and 8K enterprise streaming. Telehealth networks and broadcast journalism workflows are migrating encoding stacks within eighteen-month replacement cycles. Hardware decoder availability in consumer devices is compressing the transition window for mass-market platform operators.
FCC net neutrality rulings in the United States are forcing traffic prioritization disclosures from broadband-dependent video service providers. Infrastructure vendors must now document Quality-of-Service handling for enterprise SLA enforcement. Financial services buyers in New York and Chicago are demanding contractual bandwidth guarantees that reflect these transparency obligations.
Consumption-based licensing is displacing perpetual seat agreements in mid-market procurement. Channel partners are unbundling implementation services from software subscriptions to compete with direct self-service onboarding. This pattern is most visible among United States education technology coordinators managing district-wide Learning Management System integrations.
Video Communications Software Market Segmentation
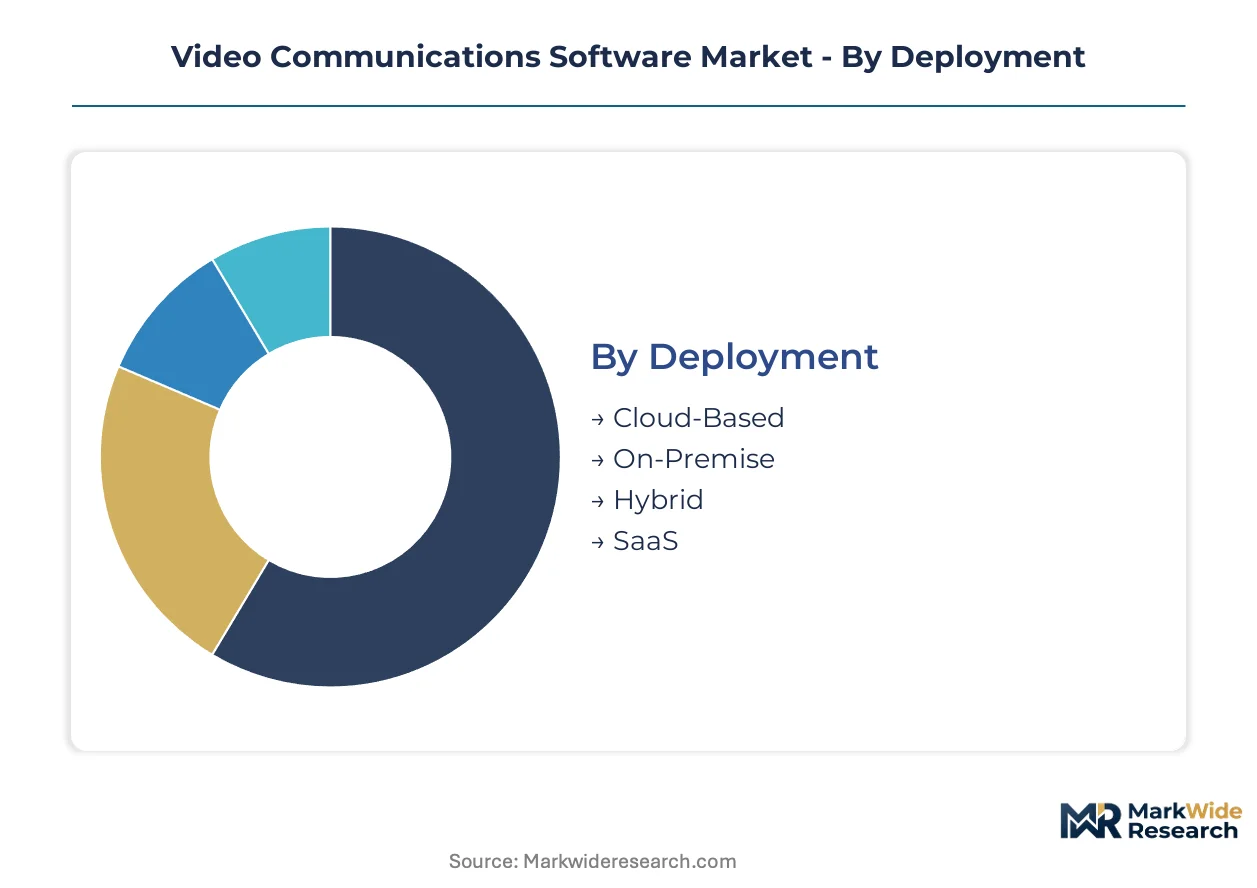
Video communications software serves fundamentally different operational needs across deployment architectures, institutional settings, and functional capabilities. Understanding how demand fragments across these dimensions clarifies why vendors maintain divergent engineering priorities and pricing architectures despite converging on common codec standards.
Deployment:
Cloud migration patterns split procurement behavior between elastic scaling imperatives and data sovereignty constraints.
- Cloud-Based:Multi-tenant infrastructure delivers sub-hour provisioning for distributed workforces without capital expenditure. HIPAA-compliant healthcare providers in the United States and GDPR-bound financial institutions in Germany drive seat expansion here despite latency sensitivity for real-time trading applications.
- On-Premise:Dedicated hardware installations maintain air-gapped security for defense contractors and classified government facilities. Japan's defense procurement guidelines and United States FedRAMP certification requirements sustain this segment against cloud cost advantages.
- Hybrid:Split architectures route sensitive sessions through private infrastructure while leveraging public cloud burst capacity. German automotive Mittelstand firms deploy this model to balance engineering collaboration speed with intellectual property protection.
- SaaS:Pre-configured subscription tiers accelerate time-to-value for mid-market buyers lacking dedicated IT operations. United States education technology coordinators favor this model for district-wide Learning Management System integrations.
Established volume favors On-Premise installations in regulated verticals; emerging adoption favors Cloud-Based deployment among mid-market enterprises.
End User:
Institutional procurement authority shapes feature roadmaps more than individual user preferences.
- Enterprise:Seat counts exceeding ten thousand demand centralized policy administration, custom branding, and API ecosystem access. Azure integration and Teams lock-in characterize procurement decisions at this scale.
- Education:Learning Management System interoperability has become a non-negotiable procurement filter. K-12 districts in the United States and university consortia in Germany are consolidating previously fragmented point solutions.
- Healthcare:HIPAA encryption mandates and telemedicine reimbursement eligibility create procurement urgency for end-to-end encrypted transmission. United States hospital systems are replacing legacy telehealth infrastructure within compressed replacement cycles.
- Government:FedRAMP, FISMA, and country-specific security certifications dominate vendor selection. Defense and civilian agencies maintain separate approved product lists with minimal overlap.
Healthcare and Education segments are expanding most quickly; Enterprise retains revenue concentration.
Feature:
Functional differentiation increasingly concentrates in AI-augmented capabilities rather than core transmission quality.
- Screen Sharing:Real-time desktop and application streaming with annotation overlays remains the baseline expectation across all user categories. Engineering teams in Japan and Germany demand sub-frame latency for CAD collaboration.
- Recording:Cloud storage integration with automated transcription and searchable archives serves compliance and training use cases. EU AI Act transparency obligations are extending engineering cycles for automated meeting analysis features.
- Virtual Backgrounds:AI-segmented background replacement reduces bandwidth requirements while maintaining professional presentation standards. This capability has commoditized across vendor offerings.
- Chat Integration:Persistent messaging thread synchronization with video sessions creates workflow continuity. Slack and Microsoft Teams API partnerships determine competitive positioning here.
Recording features command premium pricing; Chat Integration is becoming table stakes.
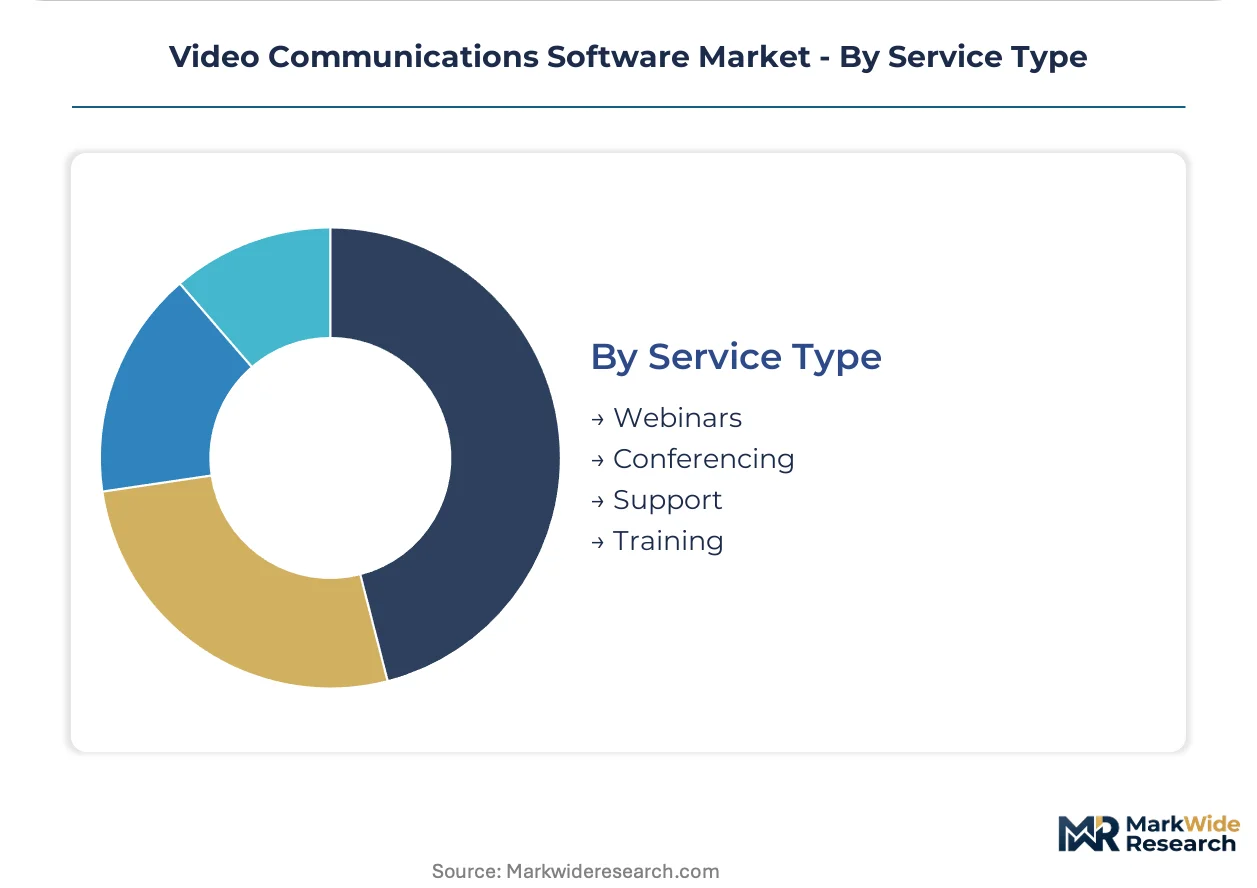
Service Type:
Delivery modality shapes infrastructure architecture and revenue recognition patterns.
- Webinars:One-to-many broadcast topology with audience engagement tools serves marketing and corporate communications. Scalability to ten thousand concurrent viewers distinguishes enterprise-grade platforms.
- Conferencing:Many-to-many real-time collaboration with dynamic layout control dominates daily operational use. AV1 codec deployment is rendering legacy H.264 infrastructure obsolete for 4K enterprise streaming in this category.
- Support:Cobrowse and remote diagnostic capabilities integrate with ticketing systems for technical assistance workflows. Session recording for quality assurance creates storage cost complexity.
- Training:Scheduled curriculum delivery with progress tracking and certification integration serves corporate learning departments. Consumption-based licensing is displacing perpetual agreements in this segment.
Conferencing generates the highest transaction volume; Training shows the steepest expansion trajectory as skills gaps widen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export video communications platforms to enterprise buyers in Germany and Japan, while cloud infrastructure providers concentrate data center capacity in Virginia, Frankfurt, and Tokyo corridors.
United States
HIPAA encryption mandates and FCC net neutrality rulings accelerate healthcare and financial sector procurement. Hospital systems in Texas and California replace legacy telehealth infrastructure within compressed replacement cycles. Virginia data centers anchor hyperscaler capacity for latency-sensitive trading floor deployments.
Germany
GDPR data residency requirements and industrial Mittelstand consolidation drive unified communications seat expansion. Automotive engineering clusters in Baden-Württemberg deploy hybrid architectures balancing collaboration speed with intellectual property protection. Frankfurt hosts primary EU cloud infrastructure for cross-border media routing.
Japan
METI digital workplace subsidies open underpenetrated SMB segments beyond Tokyo-Osaka corridors. Defense procurement guidelines sustain on-premise installations against cloud cost advantages. Nagoya manufacturing plants pilot 5G network slicing for edge computing media processing partnerships.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border data flows with EU member states. London financial services buyers demand contractual bandwidth guarantees reflecting transparency obligations. Education technology coordinators consolidate fragmented point solutions for district-wide Learning Management System integrations.
India
TRAI data localization consultations and PLI scheme incentives attract cloud infrastructure investment. Bangalore and Hyderabad technology parks host engineering centers for WebRTC pipeline development. Mid-market enterprises accelerate SaaS adoption as consumption-based licensing displaces perpetual agreements.
Video Communications Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Native codec optimization and hyperscaler integration separate premium platforms from commodity alternatives. Strategic archetypes include cloud-native specialists, legacy infrastructure incumbents, and hardware-software integrators. Dominant competitive moves encompass Azure ecosystem lock-in and security certification stacking for government verticals.
Among United States-based platform providers, Zoom Video Communications exemplifies the cloud-native specialist archetype through native codec optimization for low-latency performance. Microsoft Corporation anchors the enterprise integration tier through deep Azure embedding and Teams ecosystem density. Cisco Systems occupies the security-certified infrastructure position for government and financial verticals requiring FedRAMP compliance.
| Leading Market Players |
|---|
| Zoom Video Communications |
| Microsoft Corporation |
| Cisco Systems |
| Adobe Systems |
| Huawei Technologies |
| Avaya |
| Polycom |
| Logitech International |
| Others |
Pricing and Supply Chain Analysis
Codec licensing cost volatility from H.264 and H.265 patent pool obligations determines both tiered pricing spreads across deployment models and the geographic clustering of engineering talent for alternative codec development. This royalty uncertainty compresses margins for high-volume transmission vendors while accelerating AV1 migration investments in cost-sensitive education and healthcare segments.
Pricing Analysis
Technology-generation pricing gaps separate AV1-native platforms from legacy H.264 infrastructure and emerging 8K-ready next-generation stacks. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and integration complexity. Pricing pressure stems from consumption-based licensing displacing perpetual agreements among United States education technology coordinators. Mid-market SaaS buyers exhibit highest price sensitivity; defense contractors with FedRAMP requirements show lowest.
Supply Chain Analysis
Upstream feedstock for real-time media pipelines centers on specialized WebRTC engineering talent concentrated in the United States, India, and Germany. Cloud infrastructure draws from hyperscaler capacity in Virginia, Frankfurt, and Tokyo; hardware decoder components source from Taiwan and South Korea fabrication. Single-source vulnerability exists for low-latency network optimization expertise. Distribution runs through direct enterprise sales, telecommunications carrier partnerships, and education technology channel integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video communications software demand follows enterprise capital expenditure cycles, with cloud migration urgency creating recovery momentum as deferred telehealth and unified communications investments release from procurement backlogs.
For Market Incumbents: Harden FedRAMP and HIPAA certification moats against emerging cloud-native challengers through accelerated compliance engineering investment. Deepen vertical integration into proprietary codec optimization to escape H.265 royalty pool exposure. Secure channel control over education technology LMS integration partnerships before point-solution consolidation completes.
For New Entrants and Emerging Players: Pursue Japan METI-subsidized SMB segments outside Tokyo-Osaka corridors where incumbent presence remains thin. Target German automotive Mittelstand hybrid deployment white space balancing engineering collaboration with IP protection requirements. Lead with AI-powered real-time translation as differentiated go-to-market wedge against monolingual platform limitations.
For Investors and Strategic Acquirers: The market sits at a codec-transition phase that favors AV1-native specialists with healthcare vertical penetration. Long-term viability hinges on regulatory compliance automation capabilities across HIPAA, GDPR, and EU AI Act requirements. Acquisition target archetype: mid-scale platforms with established education sector LMS integrations and containerized deployment architecture. Signal to watch: WebRTC engineering compensation inflation as talent scarcity indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AV1 Codec Migration | Royalty-free compression reduces bandwidth costs for 4K telehealth and education streaming deployments. |
| Platform Integration | Azure and Teams ecosystem embedding locks enterprise buyers into consumption-based licensing arrangements. |
| Security Certification Stacking | FedRAMP and HIPAA compliance layering opens defense and hospital procurement channels against uncertified rivals. |
| Edge Computing Partnership | 5G carrier alliances enable on-premise media processing for latency-sensitive manufacturing floor applications. |
| AI Translation Development | Neural machine translation convergence eliminates interpreter overhead for multilingual customer service expansion. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with CTOs, IT procurement officers, platform engineers, and channel partners across healthcare, education, and enterprise verticals; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie platform metrics, and FCC regulatory dockets. Bottom-up seat expansion modeling triangulated against top-down market sizing from cloud infrastructure spend patterns.
Forecast inputs considered deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs derived from elasticity-adjusted seat growth curves and codec transition velocity assumptions. Healthcare telemedicine reimbursement policy changes and education LMS procurement standardization served as sector-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT budget cycles and cloud infrastructure investment rates would shift the trajectory. Cross-checking against hyperscaler quarterly earnings disclosures and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Specification Management Software Market
Software & Services
Global App Builder Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Bankruptcy Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Torque Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Audit Management Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Grant Management Software Market
Software & Services
Global Data Discovery Software Market