
 Global App Design Software Market | 2026-2036
Global App Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global App Design Software Market Foresight
India is reshaping the competitive terrain with Bangalore and Hyderabad emerging as centers for UX talent and offshore design operations. Adobe leverages its Creative Cloud ecosystem to sustain cross-selling momentum across enterprise accounts. Figma competes through real-time collaboration architecture that anchors distributed product teams. Google LLC extends its reach by embedding design tools within broader cloud productivity suites.
App design software comprises digital platforms that enable the creation, prototyping, and iteration of user interfaces through vector-based rendering engines, component libraries, and interactive preview environments. These tools serve the commercial purpose of reducing time-to-market for digital products while standardizing design-to-development handoffs. Cloud-based deployment leads the solution mix as remote workflows mature, while UX Analytics represents the fastest-expanding segment as product teams prioritize behavioral validation over aesthetic intuition. Wireframing remains a mature margin pool for vendors serving agency customers with predictable renewal patterns.
The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on software incorporating automated design recommendations or user behavior tracking. The US Federal Trade Commission scrutinizes subscription billing practices and interoperability claims in SaaS markets, shaping vendor pricing architectures and API openness strategies. Stakeholders must monitor how regulatory fragmentation between Brussels and Washington influences feature roadmaps and geographic go-to-market sequencing.
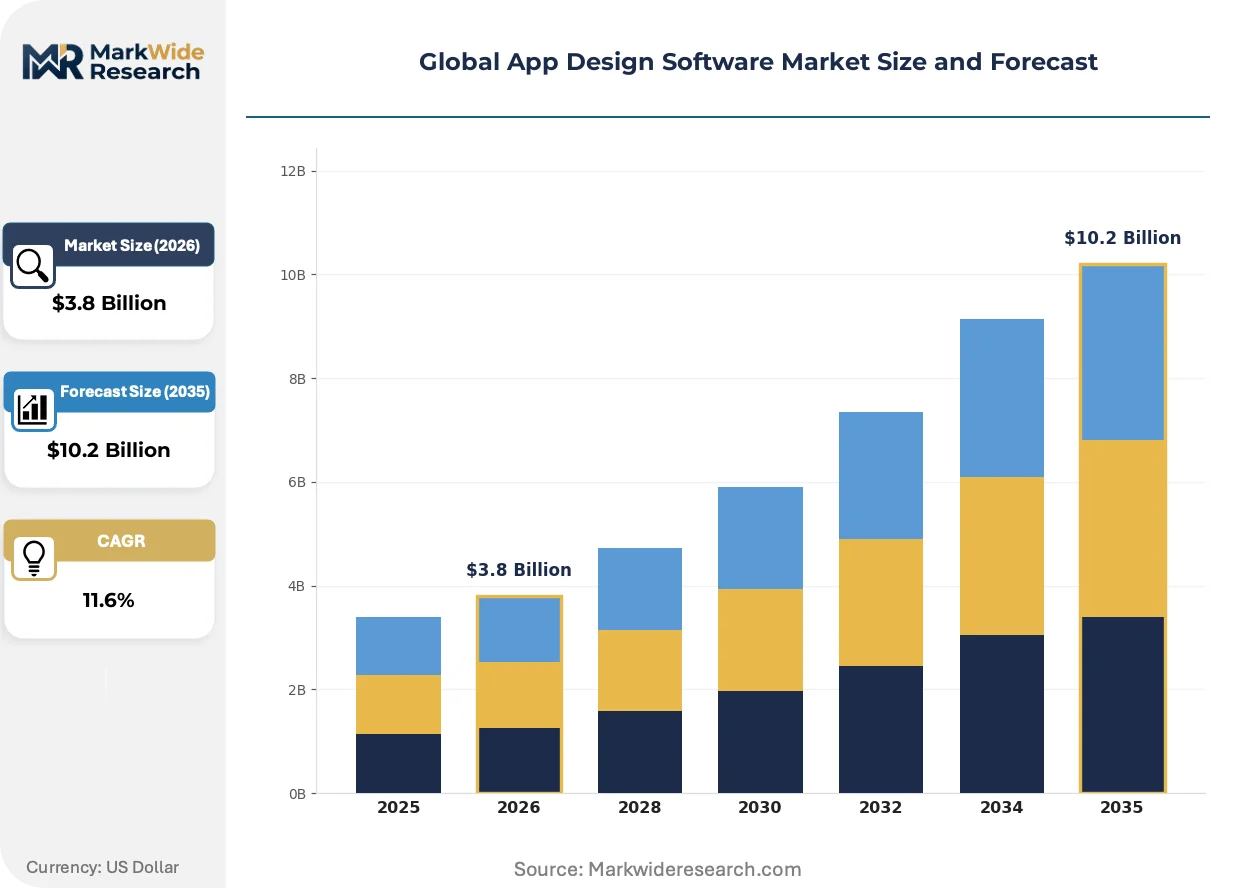
Market Dynamics
Cloud-native collaboration architectures are compressing design-to-deployment cycles while regulatory pressure from the EU AI Act and GDPR forces vendors to rebuild data pipelines around privacy-by-default engineering.
Growth Catalysts
- EU AI Act compliance mandates:Automated design recommendation engines must embed algorithmic transparency and audit trails, creating upgrade cycles across installed bases.
- Enterprise remote-work normalization:Distributed product teams in technology, financial services, and healthcare verticals now require synchronous co-editing as a baseline procurement criterion.
- UX Analytics segment expansion:Behavioral validation tools are displacing aesthetic-first workflows as product managers demand quantitative heatmaps and conversion-path analysis.
Market Restraints
- Specialized talent scarcity:The shallow pool of designers fluent in both interaction design systems and front-end component architecture inflates implementation costs.
- API interoperability friction:Proprietary file formats and restricted export capabilities in dominant platforms create switching costs that lock mid-market accounts into suboptimal tools.
- GDPR data-localization requirements:Cross-border cloud synchronization of user-behavior datasets triggers complex jurisdictional reviews, delaying rollout timelines.
Strategic Opportunities
- India's offshore design operations:Bangalore and Hyderabad service centers present white-space demand for collaboration tools optimized for 12-hour timezone handoffs with US and EU headquarters.
- AI-assisted component generation:Convergence of large language models with vector-rendering engines enables natural-language prototyping, compressing wireframe-to-mockup timelines.
- US FTC interoperability scrutiny:Anticipated enforcement against SaaS lock-in practices creates openings for API-first challengers promising seamless migration paths.
Industry Challenges
- Design-system governance complexity:Enterprise teams struggle to maintain component libraries across Figma, Sketch, and Adobe XD simultaneously without version-drift errors.
- Accessibility certification backlog:WCAG 2.1 AA compliance testing for interactive prototypes extends quality-assurance cycles, delaying release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global App Design Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile, Desktop Solution: Wireframing, Prototyping, UI Design, UX Analytics, Collaboration Tools Use Case: Enterprise Software, Consumer Applications, Educational Tools, E-Commerce Platforms, Gaming Interfaces Customer Type: Startups, Small Businesses, Agencies, Freelancers, Large Corporations |
| Companies Covered | Figma, Adobe, Sketch, InVision Software, Axure, Microsoft Corporation, Google LLC, Webflow, Balsamiq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global App Design Software Market Shifts & Advancements
Real-time multiplayer editing and AI-generated interface components are converging to collapse the boundary between design and functional prototyping, while regulatory fragmentation between Brussels and Washington forces parallel product roadmaps.
Generative AI is digitizing the transition from static mockups to interactive, code-ready prototypes. Mid-market SaaS companies and e-commerce operators are adopting these tools at the fastest clip, replacing manual handoff documentation with automated design-token extraction. The technology is digitizing the role of front-end developers in early-stage product validation, compressing headcount requirements for MVP launches.
GDPR Article 35 data-protection impact assessments now extend to design tools capturing user-behavior telemetry. Vendors must document lawful basis for processing heatmap and session-replay data, adding compliance overhead to feature releases. European enterprise procurement teams are prioritizing vendors with pre-certified privacy architectures, shifting competitive advantage toward incumbents with dedicated legal-engineering functions.
Subscription fatigue among creative-tool buyers is driving unbundling of all-in-one suites into modular, API-connected point solutions. Agency customers in particular are assembling best-of-breed stacks rather than accepting bundled analytics or asset-management add-ons. This pattern is most visible in the United States, where procurement teams compare per-seat costs across specialized wireframing, prototyping, and user-testing platforms.
Global App Design Software Market Segmentation
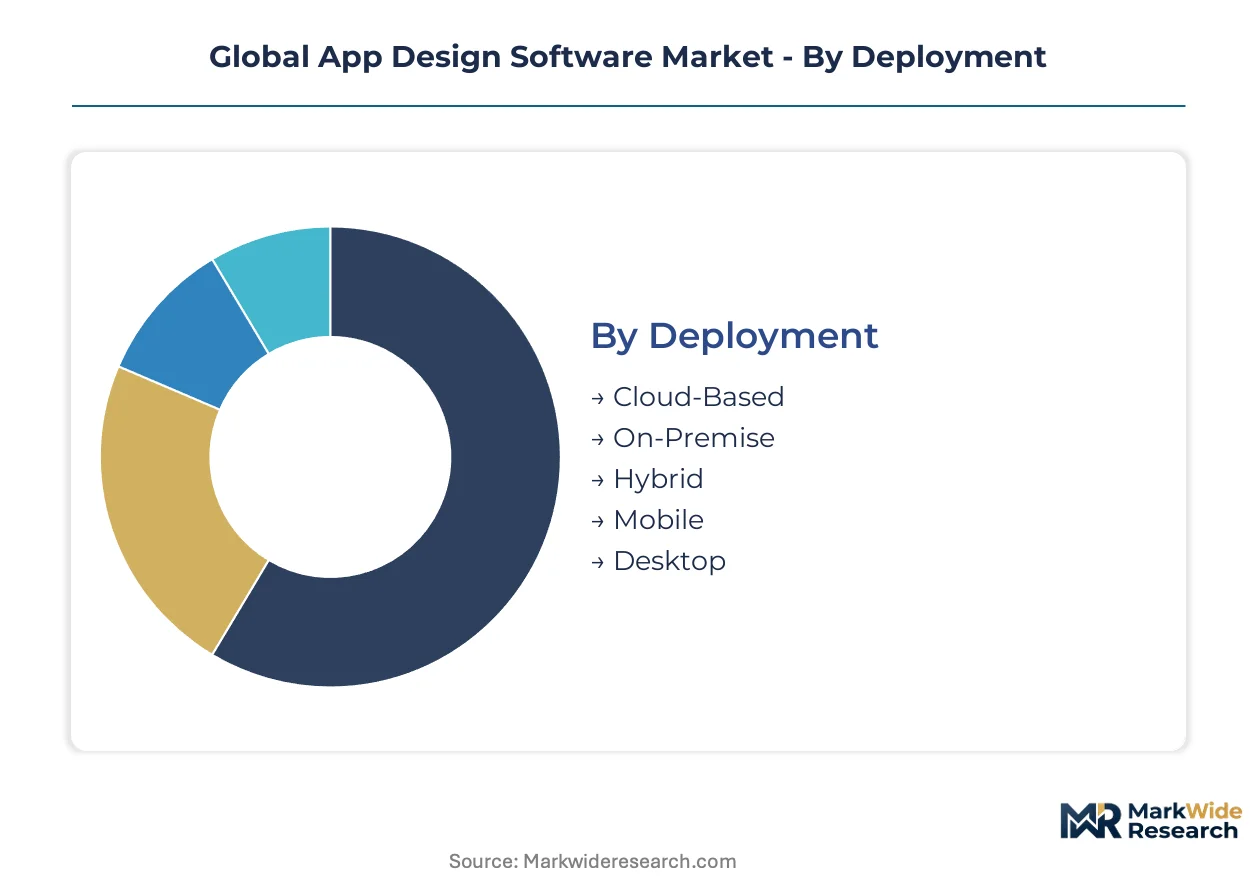
Segmentation in app design software reveals divergent procurement rhythms. Cloud-native solutions refresh on 12-18 month cycles while on-premise installations persist for 3-5 years. Understanding these temporal patterns guides vendor resource allocation and sales forecasting precision.
Deployment:
Cloud-based architectures compress procurement cycles to quarterly reviews, whereas desktop and on-premise deployments lock customers into multi-year amortization schedules with slower feature adoption curves.
- Cloud-Based:Browser-rendered environments with real-time synchronization across distributed teams. Silicon Valley SaaS companies and New York creative agencies drive premium seat expansion as remote collaboration becomes non-negotiable in vendor selection.
- On-Premise:Self-hosted server installations with air-gapped data residency for regulated industries. German automotive manufacturers and Japanese financial institutions mandate these deployments to satisfy national data-sovereignty requirements.
- Hybrid:Split architectures keeping sensitive assets local while leveraging cloud rendering for collaboration.
- Mobile:Touch-optimized tablet applications for field-based design review and rapid iteration.
- Desktop:Native OS applications with offline functionality and GPU-accelerated rendering pipelines.
Cloud-based deployment anchors the volume base while mobile-native solutions gain share at the steepest rate.
Solution:
Cost stratification separates commodity wireframing tools from premium analytics suites, with mid-market vendors bundling adjacent functions to escape price compression in mature categories.
- Wireframing:Low-fidelity layout tools for rapid structural validation before visual polish. Established agencies in London and Paris maintain predictable renewal patterns here, treating these as cost-of-doing-business utilities rather than differentiators.
- UX Analytics:Behavioral telemetry platforms capturing heatmaps, session replays, and conversion-path analysis. Fintech product teams in Singapore and healthcare app developers in Tel Aviv prioritize these tools for regulatory submission documentation.
- Prototyping:Interactive simulation environments with click-through logic and animated transitions.
- UI Design:Vector-based visual systems with component libraries and design-token generation.
- Collaboration Tools:Comment threading, version control, and stakeholder review workflows.
Wireframing solutions generate the steadiest recurring revenue while UX Analytics climbs fastest as product teams abandon intuition-based decision frameworks.
Use Case:
Application context determines compliance burden and integration complexity, with enterprise software and gaming presenting opposite extremes of security requirements versus creative velocity.
- Enterprise Software:Internal tool design with SSO integration and audit-log requirements. Banking technology divisions in Zurich and insurance IT departments in Sydney drive demand for GDPR and HIPAA-compliant feature sets.
- E-Commerce Platforms:Conversion-optimized storefront interfaces with A/B testing infrastructure. Direct-to-consumer brands in Los Angeles and marketplace operators in São Paulo invest heavily here during peak shopping season preparation.
- Consumer Applications:Mass-market mobile apps with localization and accessibility mandates.
- Educational Tools:Learning management interfaces with accessibility certification and parental control features.
- Gaming Interfaces:HUD systems and menu architectures with real-time performance constraints.
Enterprise software use cases dominate current procurement volumes while e-commerce platform investment is expanding most quickly as retail digitalization accelerates.
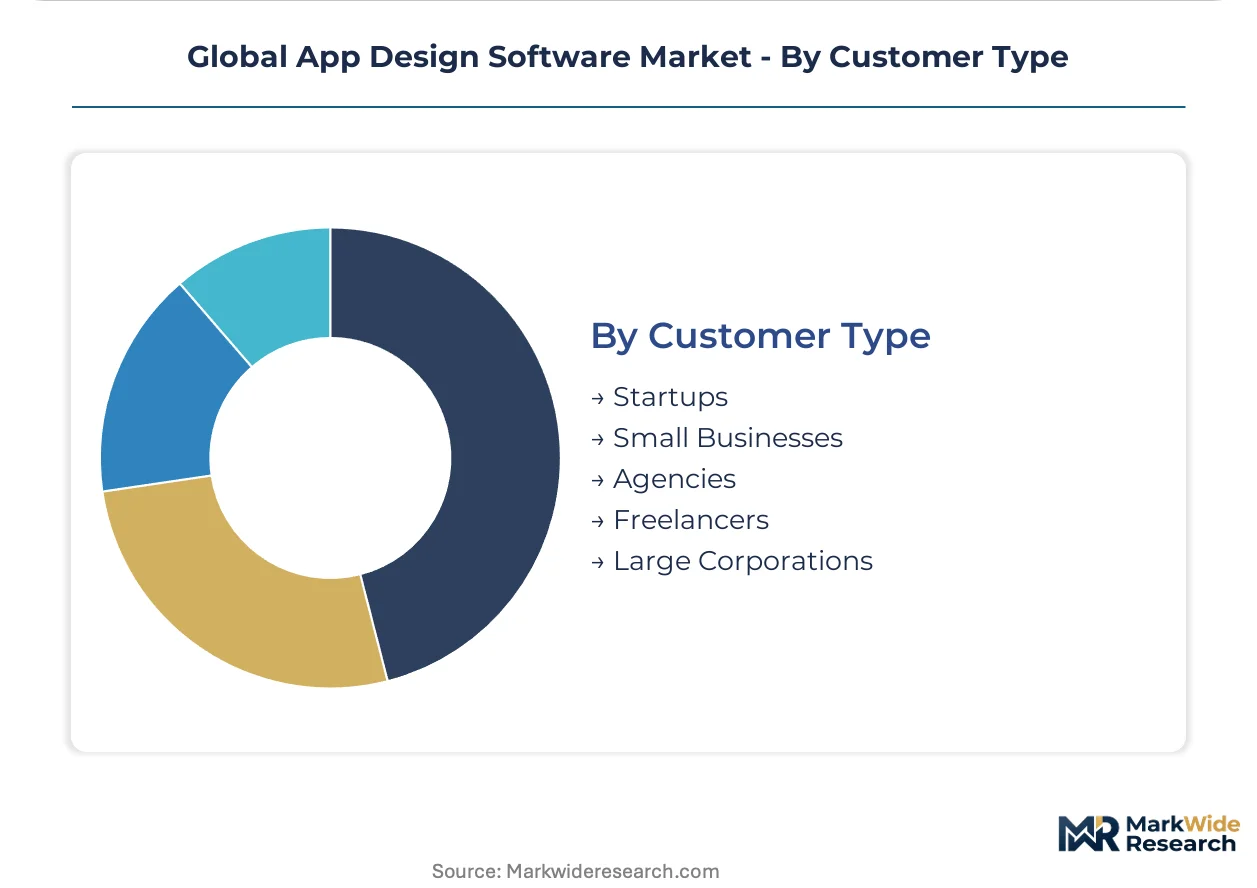
Customer Type:
Organizational scale correlates with price sensitivity and support expectations, creating five distinct sales motions from self-serve startup onboarding to multi-year corporate framework agreements.
- Large Corporations:Centralized procurement with security review committees and custom SLA negotiations. Fortune 500 technology and healthcare conglomerates in the United States negotiate enterprise-wide licenses spanning thousands of seats.
- Agencies:Project-based licensing with client-billable seat rotation and white-label export requirements. Creative services firms in Amsterdam and Copenhagen cycle tools rapidly to match client technology stacks.
- Startups:Growth-stage companies with venture-backed tool budgets and rapid headcount scaling.
- Small Businesses:Owner-operator design needs with limited technical support requirements.
- Freelancers:Individual practitioners with subscription cost sensitivity and portfolio export priorities.
Large corporations provide the revenue foundation while agency relationships deliver the highest logo velocity and product feedback density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC scrutinizes subscription billing practices in the United States, shaping vendor pricing architectures across the dominant geography. Silicon Valley and New York agency clusters drive premium subscription volumes as enterprise software teams expand tool budgets. Cloud-based collaboration has become standard procurement criteria in this market.
United States
Enterprise remote-work normalization demands synchronous co-editing capabilities from banking technology divisions in New York and insurance IT departments in Chicago. The FTC's interoperability scrutiny creates openings for API-first challengers promising seamless migration paths. Silicon Valley SaaS companies anchor premium seat expansion as distributed product teams require real-time collaboration infrastructure.
Germany
Automotive manufacturers mandate self-hosted server installations to satisfy national data-sovereignty requirements under GDPR Article 35. The EU AI Act forces vendors to rebuild data pipelines around privacy-by-default engineering for automated design recommendations. Berlin and Munich service centers present white-space demand for tools optimized with EU headquarters.
United Kingdom
Creative services firms in London and Amsterdam-facing agencies cycle tools rapidly to match client technology stacks. GDPR compliance requirements push vendors toward built-in privacy-by-design features for enterprise procurement teams. The London-Southeast corridor maintains predictable renewal patterns for wireframing utilities treated as cost-of-doing-business infrastructure.
India
Bangalore and Hyderabad emerge as centers for UX talent and offshore design operations serving US and EU headquarters. The country's national data protection framework triggers complex jurisdictional reviews for cross-border cloud synchronization. Karnataka and Telangana service centers drive demand for collaboration tools optimized for 12-hour timezone handoffs with Western markets.
Japan
Financial institutions in Tokyo require air-gapped data residency for regulated design-tool deployments. METI standards influence procurement criteria for enterprise software with audit-log requirements. The Kanto region anchors domestic demand as healthcare app developers prioritize behavioral validation tools for regulatory submission documentation.
Global App Design Software Market Competitive Landscape
Capability concentration sits with specialized UX analytics vendors; scale advantage sits with cloud productivity suite incumbents. The vendor landscape organizes around three strategic archetypes: browser-native collaboration platforms, legacy creative suite extenders, and API-first developer-tooling specialists. Dominant competitive moves include portfolio diversification into adjacent analytics modules and strategic partnerships with cloud infrastructure providers to embed design capabilities within broader productivity ecosystems.
Within the browser-native tier, Figma and Sketch occupy positions exemplifying real-time multiplayer editing architectures. Adobe represents the legacy creative suite archetype leveraging cross-selling momentum across enterprise accounts. Google LLC sits within the cloud productivity embedding strategy, extending reach by integrating design tools within broader collaboration suites. These three anchors illustrate the competitive tension between specialized capability depth and platform-scale distribution advantages.
| Leading Market Players |
|---|
| Figma |
| Adobe |
| Sketch |
| InVision Software |
| Axure |
| Microsoft Corporation |
| Google LLC |
| Webflow |
| Balsamiq |
| Others |
Supply & Pricing Matrix
GDPR data-localization mandates for user-behavior telemetry determine both tiered subscription spreads and cloud infrastructure deployment patterns across the app design software market. Vendors absorb compliance overhead differently, forcing price stratification between privacy-certified enterprise tiers and standard offerings while redirecting supply chain investments toward EU-based server capacity.
Pricing Analysis
Silicon Valley SaaS companies pay 40-60% premiums over Bangalore service centers for equivalent seat counts. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation resting on SSO integration depth and audit-log retention. Cost compression in the mid-market tier is intensifying because agencies assemble best-of-breed stacks rather than accepting bundled analytics add-ons. Freelancers and small businesses exhibit highest price sensitivity, while Fortune 500 technology conglomerates prioritize security certification over per-seat economics.
Supply Chain Analysis
Amazon Web Services, Microsoft Azure, and Google Cloud Platform hold dominant capacity for rendering infrastructure serving this market. Compute resources concentrate in the United States, Ireland, and Singapore to minimize latency for distributed design teams. Raw material dependencies span GPU silicon from Taiwan, submarine cable capacity across the Atlantic, and renewable energy certificates for carbon-neutral data center claims. Single-source vulnerability sits with concentrated hyperscaler availability zones. Distribution runs through direct self-serve portals for startups and field sales organizations for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-era overbuild as enterprise software teams normalize hybrid work tool budgets. Cloud collaboration spend cycles now track quarterly business planning rather than emergency procurement.
For Market Incumbents: Harden GDPR Article 35 compliance architectures to defend European enterprise accounts against API-first challengers. Deepen vertical integration into vector-rendering engines by acquiring specialized GPU optimization firms. Channel control through certified implementation partners in India protects margin position against offshore price competition.
For New Entrants and Emerging Players: Build out white-space demand in UX Analytics for healthcare app developers in Tel Aviv and fintech product teams in Singapore. The most penetrable segment is mid-market SaaS companies replacing manual handoff documentation with automated design-token extraction. A developer-relations-led go-to-market angle bypasses incumbent procurement blockades.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized UX analytics vendors with pre-certified privacy architectures. Long-term viability hinges on regulatory-engineering capabilities spanning Brussels and Washington enforcement patterns. The signal to watch is FTC interoperability enforcement creating forced-migration windows for locked-in accounts.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Certification | EU AI Act compliance accelerates vendor selection for European banking technology divisions. |
| Real-Time Collaboration Architecture | Browser-native multiplayer editing anchors distributed product team procurement decisions. |
| API-First Platform Strategy | Seamless migration paths exploit FTC scrutiny of proprietary file format lock-in practices. |
| India Service Center Partnership | Bangalore and Hyderabad presence captures 12-hour timezone handoff optimization demand. |
| AI-Assisted Component Generation | Natural-language prototyping compresses wireframe-to-mockup timelines for MVP launches. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory submissions preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Primary fieldwork with design system leads at Fortune 500 technology conglomerates and agency creative directors in London and New York validated secondary estimates. Bottom-up seat-count modeling and top-down enterprise software spend analysis were triangulated against cloud infrastructure capacity data.
Macroeconomic conditions including remote-work normalization and regulatory enforcement timelines were held fixed across the projection horizon, while AI adoption curves and interoperability policy developments were stress-tested. Segmentation dimensions modeled span deployment model, organization size, vertical industry, and regional adoption pattern. CAGRs were derived from cohort-based retention analysis and expansion revenue patterns. Forecast inputs include GDPR compliance cost pass-through rates and FTC enforcement probability assessments.
Stress conditions across cloud infrastructure pricing, cross-border data transfer restrictions, and generative AI capability diffusion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise procurement cycle normalization. Quarterly review of regulatory submission timelines and hyperscaler regional capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Defined Broadcasting Market
Software & Services
Custom Software Development Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Global Quoting Software Market
Software & Services
Global App Builder Software Market
Software & Services
Web Scraping Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Network Documentation Software Market
Software & Services
Global Permit Management Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Aviation Software Market
Software & Services
Data Migration Software Services Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Embedded Operating Systems Market