
 Construction Software As A Service Market | 2026-2036
Construction Software As A Service Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Software As A Service Market Insights
North American SaaS infrastructure is hardening as data center capacity expands across Virginia, Texas, and Oregon to serve construction technology workloads. Procore Technologies leverages its vertical specialization in project management to sustain pricing power among general contractors. Autodesk anchors the design-to-construction workflow through deep BIM integration, while Oracle competes across the enterprise stack with unified financial and operations platforms.
Construction Software As A Service denotes cloud-hosted applications delivered via subscription that manage project lifecycles, resource allocation, and stakeholder collaboration through centralized databases accessible from distributed job sites. These platforms typically operate on multi-tenant architectures with API ecosystems enabling integration with estimating, accounting, and field data collection tools. Project Management and Collaboration Platforms occupy the largest addressable segments due to universal deployment across contractor tiers, while Scheduling Software and Quality Control modules represent faster-growing pockets as owners impose stricter milestone accountability. Cloud-Based deployment dominates new sales, though Hybrid configurations persist among infrastructure developers managing sensitive geotechnical data.
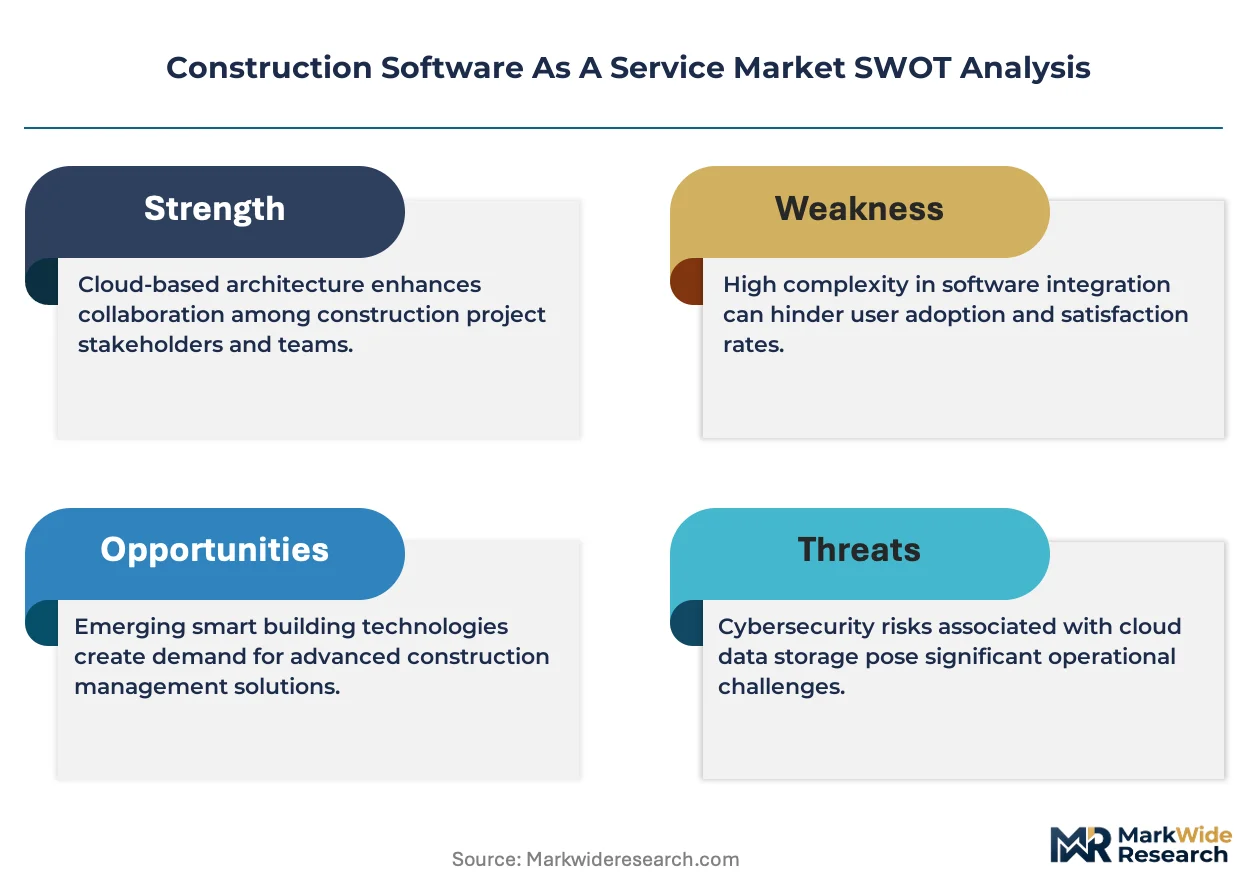
FDA oversight intersects indirectly where construction SaaS supports pharmaceutical facility validation, while OSHA recordkeeping rules drive field safety module adoption. The EU AI Act and GDPR shape algorithmic scheduling and cross-border data residency requirements for platforms serving multinational contractors. Stakeholders must evaluate regulatory divergence between the SEC's cybersecurity disclosure mandates and emerging EU CSRD sustainability reporting rules when architecting product roadmaps.
Market Dynamics
Cloud migration among general contractors is compressing deployment cycles for project management platforms, while building energy codes in California and the European Union mandate digital documentation workflows that lock in subscription-based procurement models.
Growth Catalysts
- OSHA Recordkeeping Mandates:Field safety module adoption accelerates as contractors digitize incident reporting to comply with federal workplace safety documentation requirements in the United States.
- Building Energy Codes:California's Title 24 and the EU Energy Performance of Buildings Directive compel digital handover protocols that embed SaaS platforms into project closeout workflows.
- API Ecosystem Maturity:Open integration architectures enable construction firms to connect estimating, accounting, and field data collection tools without custom development overhead.
Market Restraints
- Geotechnical Data Sensitivity:Infrastructure developers in Germany and Australia retain hybrid deployments for subsurface engineering data, limiting pure cloud addressable market expansion.
- Subscription Cost Accumulation:Mid-tier contractors face margin pressure from multi-module SaaS stacking across project management, scheduling, and quality control functions.
- Cross-Border Data Residency:GDPR and emerging EU AI Act requirements fragment platform architectures, raising compliance engineering costs for vendors serving multinational contractors.
Strategic Opportunities
- Quality Control Module Expansion:Owner-imposed milestone accountability standards in Australia drive faster adoption of inspection and defect-tracking workflows than in mature project management segments.
- SEC Cybersecurity Disclosures:Public contractor disclosure mandates create demand for SaaS platforms with embedded audit trails and third-party security certification.
- AI-Enabled Scheduling Convergence:Machine learning algorithms integrated with resource allocation engines offer differentiation in competitive procurement environments.
Industry Challenges
- Field-to-Office Integration Complexity:Construction firms struggle to synchronize real-time mobile data capture with legacy enterprise resource planning systems.
- BIM Specialist Talent Scarcity:Shortages of digitally fluent project engineers constrain deployment velocity for design-to-construction workflow platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Software As A Service Market |
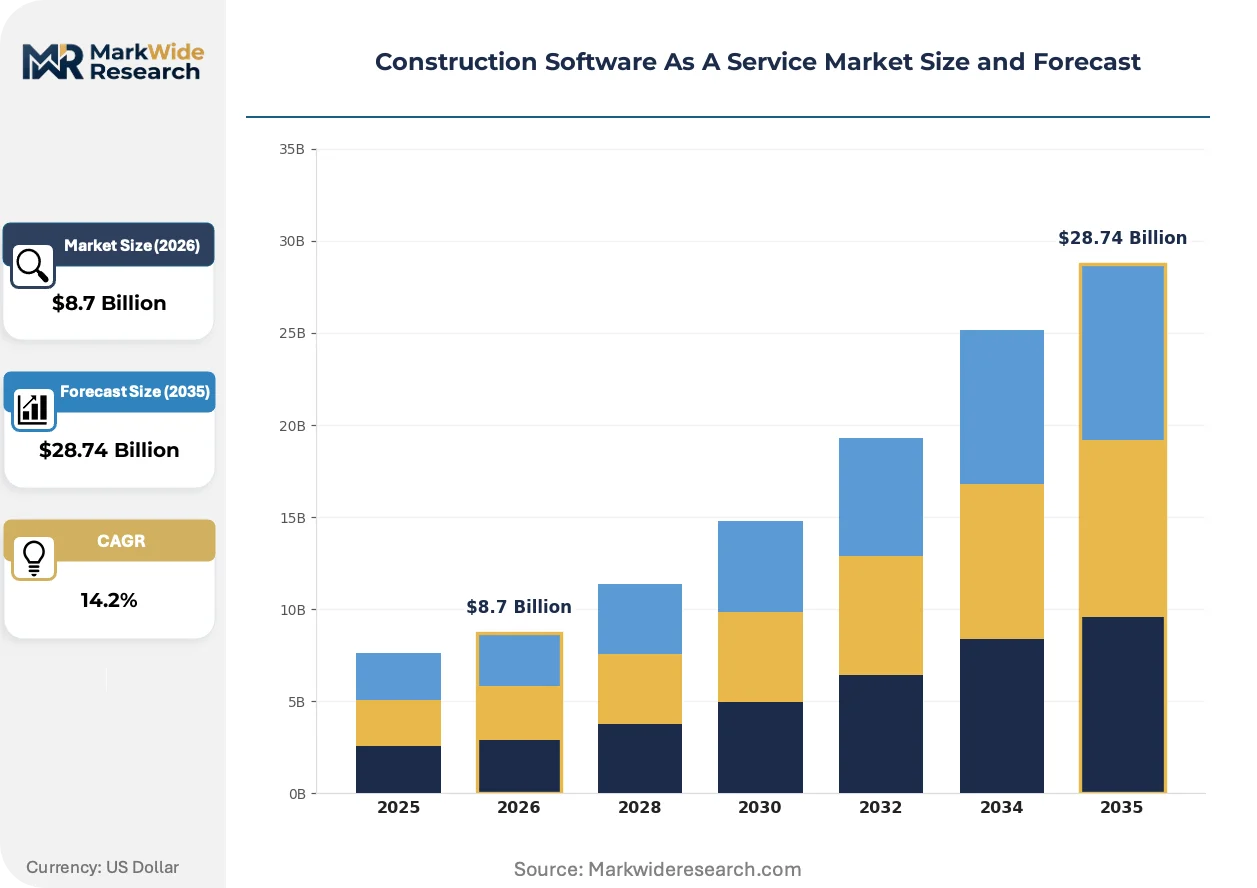
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Project Management, Estimation & Budgeting, Document Control, Scheduling Software, Quality Control, Collaboration Platforms Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Services Application: Commercial Construction, Residential Building, Infrastructure Development, Specialty Contracting, Public Works End User: General Contractors, Subcontractors, Engineering Firms, Consulting Agencies |
| Companies Covered | Procore Technologies, Oracle, Autodesk, Trimble, Bentley Systems, Sage Group, Buildertrend, Jonas Construction Software, Newforma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Software As A Service Market Trends and Innovations
Construction technology vendors are embedding artificial intelligence into core workflows while regulatory pressure on data governance intensifies, reshaping how platforms compete on compliance automation rather than feature breadth alone.
Generative design algorithms are overtaking traditional manual scheduling in complex commercial projects, enabling general contractors to simulate resource conflicts across multi-phase developments before ground breaks. Mid-size firms in Texas and Virginia deploy these tools to compress pre-construction timelines. The technology is overtaking rule-based legacy systems that required dedicated planning engineers for scenario modeling.
The EU AI Act's risk classification framework for algorithmic decision-making imposes documentation burdens on predictive scheduling modules deployed across European job sites. Vendors must now maintain technical files and conformity assessments for AI components previously treated as standard software features. German general contractors are responding by demanding vendor transparency on training data provenance and model governance.
Subscription fatigue among contractor finance departments is fragmenting procurement authority, with project managers increasingly selecting point solutions through corporate credit cards rather than centralized IT procurement. This shadow-IT phenomenon concentrates in the United States where decentralized project accounting prevails. Equipment rental firms and specialty subcontractors represent the fastest-adopting segment under this decentralized purchasing pattern.
Construction Software As A Service Market Segmentation
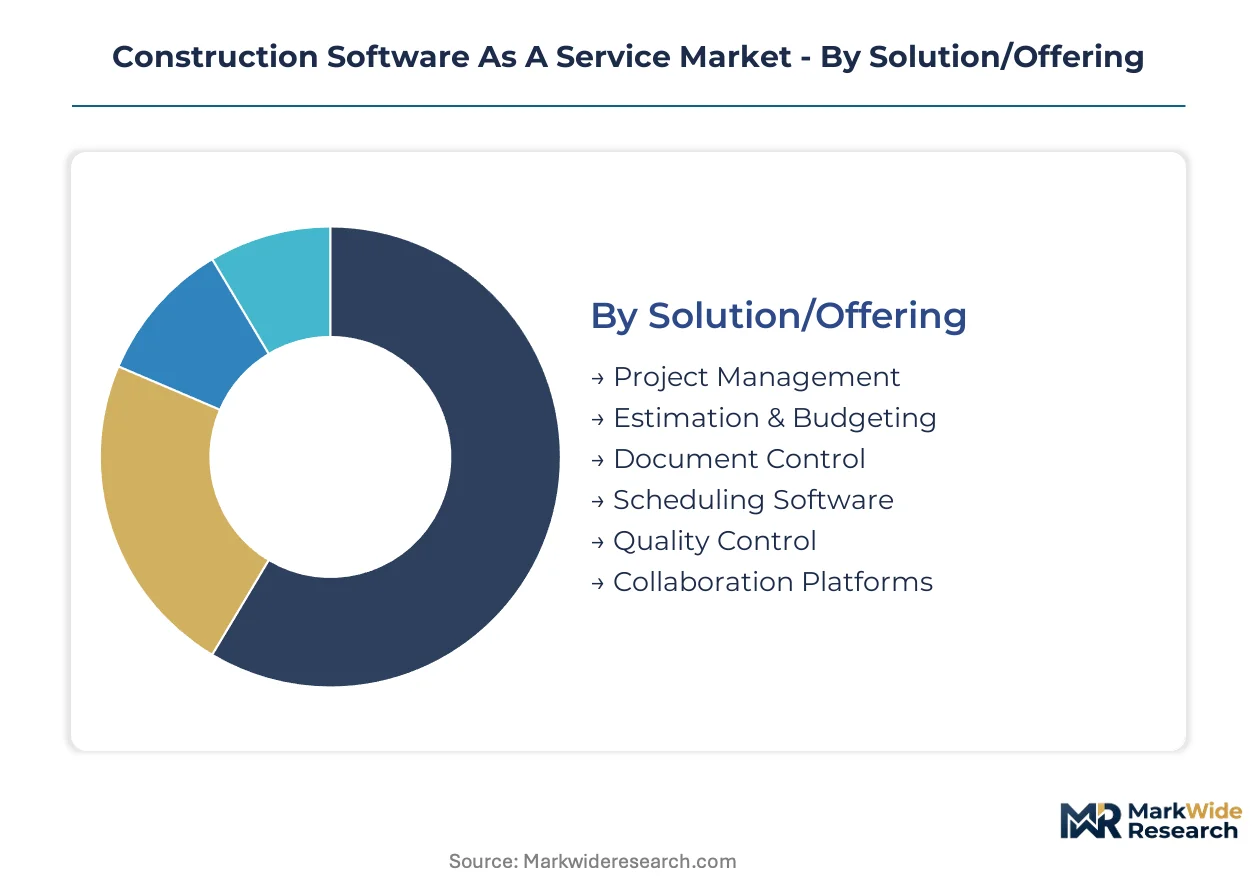
Construction SaaS vendors architect pricing and deployment models around distinct operational workflows, with capital requirements varying sharply between project management suites and specialized field modules. Segmentation clarity enables procurement teams to match subscription tiers against contractor size and compliance exposure.
Solution/Offering:
Capital intensity concentrates in platforms requiring multi-tenant infrastructure and API ecosystem maintenance, while point solutions demand lighter engineering investment.
- Project Management:Centralized dashboards coordinate resource allocation, subcontractor communications, and financial tracking across distributed job sites. General contractors in the United States deploy these platforms universally, with OSHA recordkeeping mandates accelerating digitization of field documentation workflows.
- Scheduling Software:Machine learning algorithms now displace rule-based legacy systems for scenario modeling across multi-phase developments. German contractors demand vendor transparency on training data provenance under the EU AI Act's risk classification framework.
- Estimation & Budgeting:Cloud-hosted quantity takeoff and cost forecasting tools integrate with accounting systems via open APIs.
- Document Control:Digital handover protocols mandated by California's Title 24 and the EU Energy Performance of Buildings Directive embed these modules into project closeout workflows.
- Quality Control:Inspection and defect-tracking workflows gain traction fastest in Australia where owner-imposed milestone accountability standards are strictest.
- Collaboration Platforms:Real-time stakeholder communication hubs serve as the entry point for mid-tier contractors facing subscription stacking pressure.
Project Management absorbs the bulk of installed capacity; Scheduling Software is expanding most quickly.
Deployment:
Subscription economics and data sovereignty requirements shape infrastructure decisions, with hybrid architectures commanding premium engineering resources.
- Cloud-Based:Multi-tenant SaaS architectures dominate new sales through rapid provisioning and automatic updates. Virginia, Texas, and Oregon data center expansions harden North American infrastructure for construction technology workloads.
- Hybrid:Sensitive geotechnical data handling drives adoption among infrastructure developers in Germany and Australia, limiting pure cloud addressable market expansion.
- On-Premises:Legacy installations persist in defense and critical infrastructure sectors with air-gapped security requirements.
- Hosted Services:Single-tenant managed deployments serve multinational contractors navigating GDPR cross-border data residency fragmentation.
Cloud-Based deployments capture the majority of new subscription value; Hybrid configurations command the highest per-seat pricing.
Application:
Regulatory complexity and project scale determine platform customization depth, with commercial and infrastructure segments requiring the most compliance engineering.
- Commercial Construction:Complex stakeholder coordination across multi-phase developments demands integrated design-to-construction workflows. Texas and Virginia mid-size firms deploy generative scheduling algorithms to compress pre-construction timelines.
- Infrastructure Development:Long-duration projects with public oversight require embedded audit trails and third-party security certification under SEC cybersecurity disclosure mandates.
- Residential Building:Volume production homebuilders prioritize estimation and budgeting modules with supplier integration.
- Specialty Contracting:Equipment rental firms and trade contractors represent the fastest-adopting segment under decentralized procurement patterns.
- Public Works:Prevailing wage reporting and certified payroll requirements drive demand for financial operations platforms with government audit compatibility.
Commercial Construction anchors platform revenue; Infrastructure Development shows the steepest expansion trajectory as federal spending flows accelerate.
End User:
Procurement authority fragmentation creates divergent sales motions, with centralized IT departments and shadow-IT project managers requiring distinct channel strategies.
- General Contractors:Full-stack platform adoption spans project management, scheduling, and quality control functions. Subscription fatigue concentrates in this tier as multi-module stacking pressures margins.
- Subcontractors:Point solution purchases through corporate credit cards bypass centralized IT procurement, particularly in the United States where decentralized project accounting prevails.
- Engineering Firms:BIM integration requirements and specialist talent scarcity constrain deployment velocity for design-to-construction workflow platforms.
- Consulting Agencies:Advisory services bundling software implementation and change management command premium pricing.
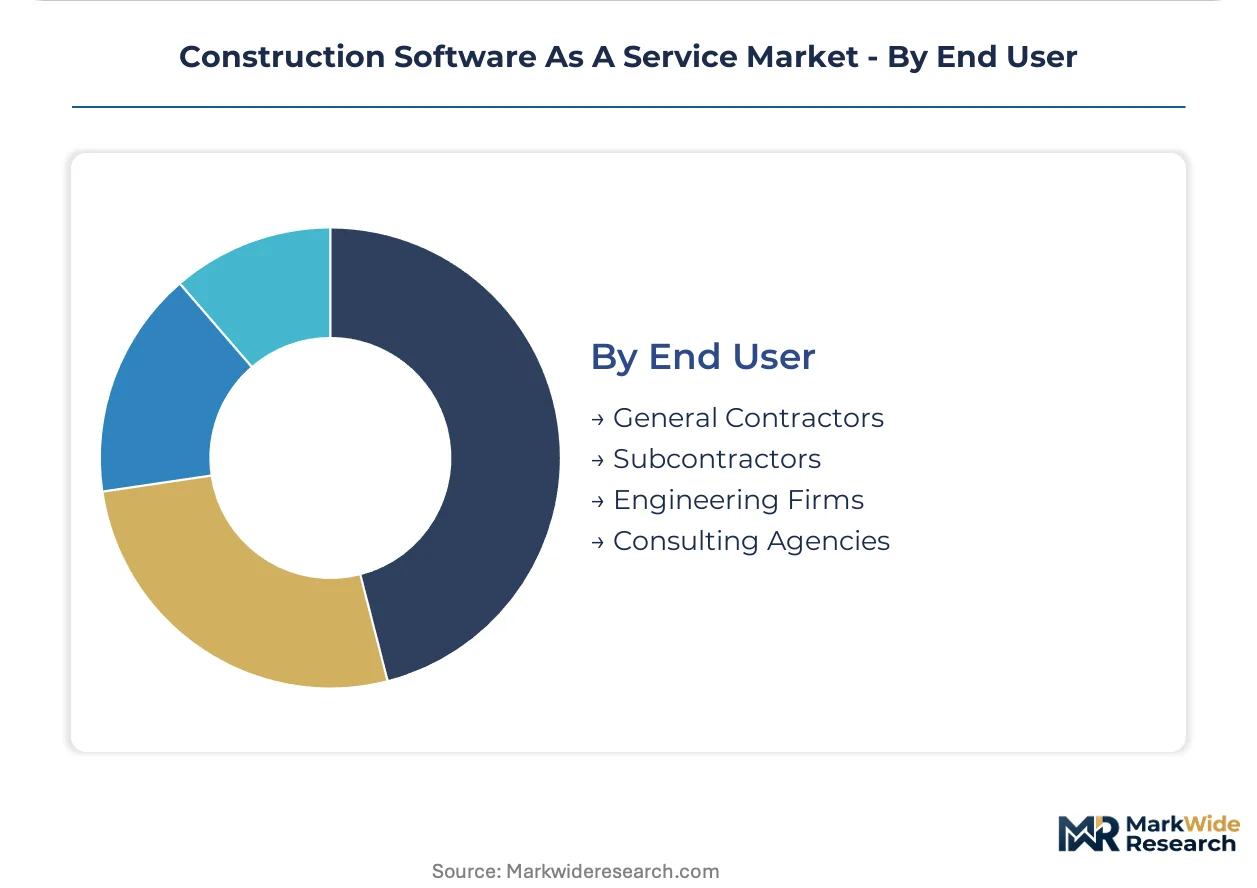
General Contractors represent the deepest account penetration; Subcontractors are gaining share fastest as decentralized purchasing patterns spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital flows anchor SaaS development clusters in the United States, while German engineering standards and Australian infrastructure investment create parallel demand centers for construction technology platforms.
United States
OSHA recordkeeping mandates and SEC cybersecurity disclosure rules drive field safety module adoption among general contractors. California's Title 24 building energy codes compel digital handover protocols that embed SaaS platforms into project closeout workflows. Texas and Virginia mid-size firms deploy generative scheduling algorithms to compress pre-construction timelines.
Germany
EU AI Act risk classification frameworks impose documentation burdens on predictive scheduling modules deployed across European job sites. German general contractors demand vendor transparency on training data provenance and model governance under emerging algorithmic accountability rules. Infrastructure developers in Bavaria and North Rhine-Westphalia retain hybrid deployments for sensitive geotechnical data handling.
Australia
Owner-imposed milestone accountability standards accelerate inspection and defect-tracking workflow adoption faster than in mature project management segments. Federal infrastructure spending flows and state-level building codes create concentrated demand in New South Wales and Victoria. Sydney and Melbourne construction clusters drive quality control module expansion across commercial and public works segments.
United Kingdom
GDPR cross-border data residency requirements fragment platform architectures for multinational contractors operating across European and Commonwealth markets. CSRD sustainability reporting rules intersect with construction documentation workflows, creating compliance automation demand. London-based engineering firms and regional general contractors in the Midlands pursue BIM-integrated design-to-construction platforms despite specialist talent scarcity.
Japan
METI industrial digitization programs and aging construction workforce demographics accelerate cloud-based project management adoption among mid-tier contractors. JIS standards alignment requirements shape procurement criteria for platforms serving public works and infrastructure development. Tokyo-Osaka construction corridors concentrate SaaS demand as general contractors modernize legacy paper-based documentation systems.
Construction Software As A Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized field modules and AI-enabled scheduling convergence. The vendor base stratifies across full-stack platform providers, vertical specialists, and point-solution developers serving decentralized procurement patterns. Three archetypes dominate: design-to-construction workflow integrators, project management pure-plays, and financial operations platform extenders. Competitive moves concentrate on API ecosystem expansion and compliance automation engineering to satisfy divergent regulatory requirements.
Among North American platform developers, Procore Technologies, Oracle, and Autodesk represent the primary competitive anchors. Procore Technologies exemplifies the vertical specialist archetype through sustained pricing power in general contractor segments. Oracle occupies a position across the enterprise technology stack with unified financial and operations platform architectures. Autodesk anchors design-to-construction workflow integration through deep building information modeling connectivity. These three companies collectively illustrate the competitive tension between vertical depth and horizontal platform breadth that shapes vendor positioning strategies.
| Leading Market Players |
|---|
| Procore Technologies |
| Oracle |
| Autodesk |
| Trimble |
| Bentley Systems |
| Sage Group |
| Buildertrend |
| Jonas Construction Software |
| Newforma |
| Others |
Pricing and Supply Chain Analysis
Subscription fatigue among mid-tier general contractors in the United States is forcing vendors to unbundle quality control and scheduling modules from core project management suites, compressing effective per-seat pricing while elevating engineering costs for API ecosystem maintenance.
Pricing Analysis
Warranty and implementation service bundling separates premium-tier deployments from standard self-service subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by API integration depth and SOC 2 certification status. Cost compression in the mid-market intensifies because decentralized procurement through corporate credit cards bypasses volume discount negotiations. Subcontractors and specialty trade contractors exhibit the highest price sensitivity, while infrastructure developers with SEC disclosure mandates accept premium pricing for embedded audit trails.
Supply Chain Analysis
Cloud infrastructure talent scarcity in Virginia, Texas, and Oregon constrains data center expansion velocity for construction SaaS workloads. Platform engineering draws from semiconductor fabrication in Taiwan, enterprise server manufacturing in China, and specialized cooling systems from Germany. Single-source vulnerability concentrates in hyperscaler compute contracts with AWS, Azure, and Google Cloud. Distribution runs through direct enterprise sales teams for general contractors and self-service digital channels for decentralized subcontractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for algorithmic decision-making erects compliance engineering barriers that favor established vendors with dedicated conformity assessment resources, locking out lean entrants from European predictive scheduling markets.
For Market Incumbents: Extend API ecosystem coverage to capture field-to-office integration budgets before point-solution developers consolidate mobile data capture workflows. Procore Technologies and Autodesk anchor positions through BIM integration depth, but emerging AI-native scheduling entrants threaten module substitution. Vertical integration into geotechnical data handling infrastructure preserves hybrid deployment pricing power among German and Australian infrastructure developers. For New Entrants and Emerging Players: California's Title 24 building energy code opens a window for document control specialists targeting digital handover compliance gaps in commercial construction closeout workflows. Quality control modules for owner-imposed milestone accountability in Australia represent the most penetrable segment given faster adoption velocity than saturated project management suites. Channel partnerships with equipment rental firms bypass entrenched IT procurement gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing EU AI Act technical file documentation and established training data governance protocols given algorithmic accountability enforcement acceleration. Long-term viability across a five-to-ten-year window favors vendors with hybrid deployment architectures serving GDPR-fragmented multinational contractor operations. Watch for SEC cybersecurity disclosure mandate expansion to private contractors as inflection indicator for audit trail module demand.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Open integration architectures reduce custom development overhead for Procore Technologies and Oracle enterprise deployments. |
| AI-Enabled Scheduling Convergence | Machine learning resource allocation engines differentiate procurement bids for Texas and Virginia mid-size commercial contractors. |
| Compliance Automation Engineering | Embedded EU AI Act conformity assessments protect Autodesk's European market position against leaner competitors. |
| Hybrid Infrastructure Investment | Geotechnical data sovereignty solutions capture premium pricing from German and Australian infrastructure developers. |
| Decentralized Channel Development | Self-service platforms with corporate credit card billing penetrate subcontractor segments bypassing centralized IT procurement. |
Research Methodology
Document review covered SEC cybersecurity disclosure filings, EU AI Act implementation guidance, and California Title 24 regulatory text, complemented by interviews with construction technology CTOs, general contractor IT procurement officers, platform integration specialists, and field operations directors. Secondary validation drew from hyperscaler data center expansion announcements, OSHA recordkeeping mandate enforcement data, and building energy code adoption tracking across member states. Bottom-up deployment estimates triangulated against top-down SaaS market sizing from software industry associations.
Cross-reference between historical subscription growth patterns and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, contractor tier by employee count, vertical application, integration complexity with legacy ERP systems, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by adoption ceiling estimates and compliance mandate enforcement timelines. Forecast inputs incorporated API ecosystem maturity indices and BIM specialist talent availability by metropolitan construction cluster.
Caveats apply where EU AI Act enforcement intensity, SEC cybersecurity disclosure expansion to private contractors, or hyperscaler pricing volatility could materially shift the outlook. Forecasts reflect documented assumptions about regulatory implementation schedules and contractor digitization budget persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Bridge Analysis Software Market
Software & Services
SRM Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Subscription Management Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Global Note Taking App Market
Software & Services
HVAC Solution Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Talent Management Software Market
Software & Services
Global Driving School Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Photogrammetry Software Market