

RIP Software Market Size, Share, and Industry Trends Forecast 2026-2036
RIP Software Market Insights
The RIP software landscape is consolidating around a sharp split between premium color-managed suites and commodity rasterization tools. Electronics for Imaging leverages its integrated hardware-software stack to dominate high-end commercial installations. Caldera sustains leadership in wide-format textile workflows through specialized RIP kernels optimized for dye-sublimation and direct-to-garment presses. SA International competes aggressively in the signage and CNC-adjacent segment, where its nesting and cutting path algorithms anchor differentiated value.
RIP software translates vector graphics, raster images, and color profiles into device-specific print instructions through halftoning, ink limiting, and media compensation algorithms, typically processing 16-bit color spaces at resolutions up to 2400 dpi for industrial inkjet heads. Cloud-based deployment is displacing on-premises licensing among mid-tier print houses that prioritize subscription flexibility over perpetual ownership. Color management modules command premium pricing as brand owners enforce tighter Delta-E tolerances across packaging and proofing applications. Workflow automation represents the fastest-expanding solution type, driven by web-to-print integration and JDF-compliant job ticketing.
REACH chemical restrictions and the EU F-Gas Regulation constrain solvent ink formulations, pushing RIP vendors to optimize low-VOC UV and water-based output curves. The US EPA enforces emissions thresholds on commercial print facilities, creating compliance demand for ink-usage tracking embedded in RIP dashboards. Stakeholders must weigh captive color science development against partnerships with independent profiling houses as ICC specification evolution and substrate diversification accelerate.
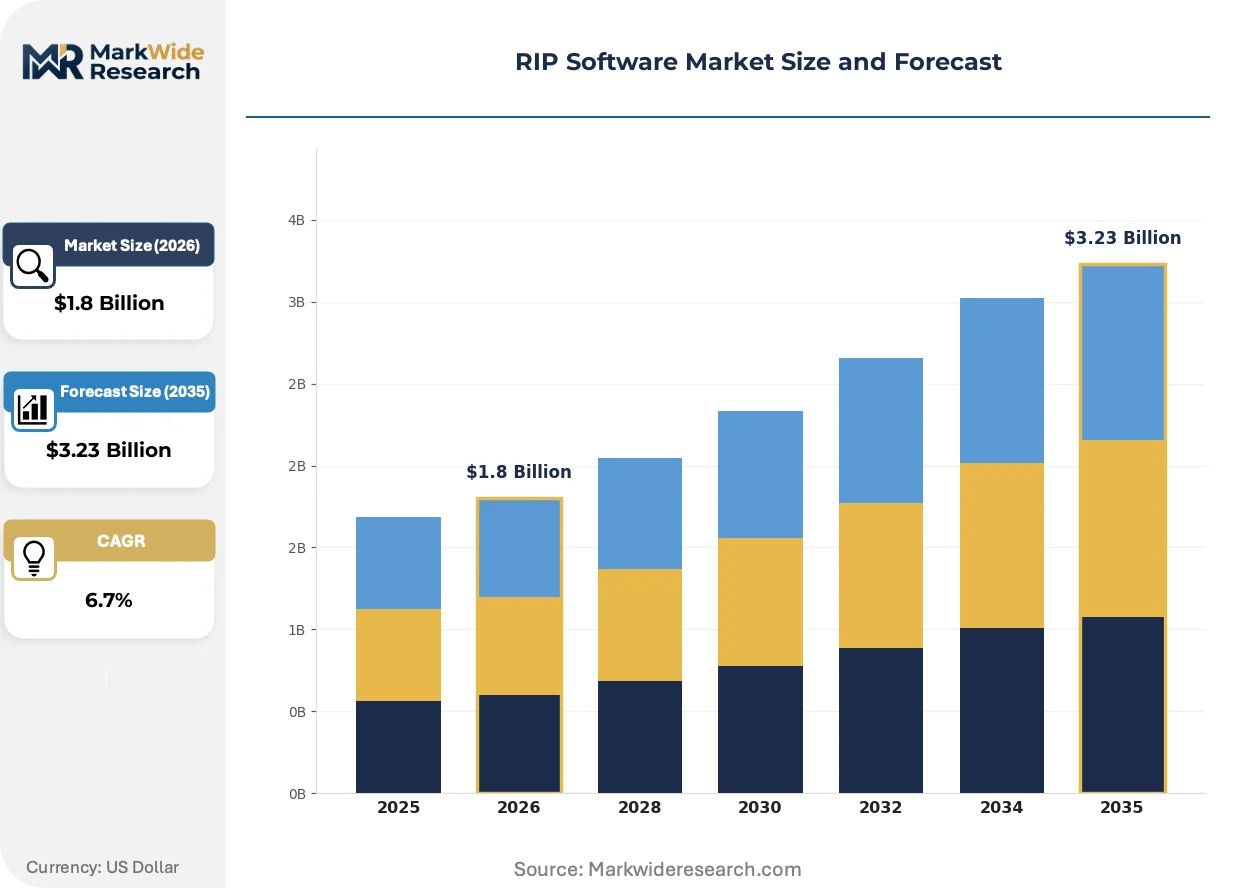
Market Dynamics
Cloud-native RIP architectures are compressing traditional perpetual-license economics while forcing vendors to rebuild recurring-revenue engines around consumption-based metering and API-integrated workflow stacks.
Growth Catalysts
- UV-curable inkjet displacement:Commercial print houses in Germany and Japan are retiring solvent-based flexo lines, requiring RIP kernels with multi-pass UV optimization and LED-curing curve calibration.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in industrial processes push wide-format operators toward water-based latex systems that demand reformulated color-limiting algorithms.
- Web-to-print integration:Mid-tier packaging converters are embedding JDF-compliant RIP nodes directly into e-commerce storefronts, collapsing prepress turnaround from hours to minutes.
Market Restraints
- Premium color science talent scarcity:ICC profiling specialists command compensation premiums that inflate implementation costs for independent RIP vendors without captive color labs.
- Substrate diversification friction:Each new textile or rigid media formulation requires validated output curves, stretching vendor QA resources across incompatible material chemistries.
- Perpetual-license revenue collapse:Cloud migration destroys upfront cash flows that previously funded multi-year R&D cycles for halftoning algorithm development.
Strategic Opportunities
- India packaging automation:Domestic pharmaceutical serialization mandates under CDSCO are creating demand for track-and-trace RIP modules that integrate variable-data printing with anti-counterfeiting layers.
- AI-driven nesting convergence:Machine-learning path optimization for textile cutting tables is absorbing adjacent CAM software functions, expanding RIP addressable market into CNC-adjacent workflows.
- US EPA emissions tracking:Ink-usage monitoring dashboards embedded in RIP platforms capture compliance budgets from commercial print facilities facing facility-wide VOC reporting thresholds.
Industry Challenges
- Delta-E tolerance compression:Brand owners in luxury packaging now enforce sub-1.0 color variance specifications that exceed standard ICC profile capabilities, forcing custom closed-loop calibration development.
- Legacy MIS integration debt:Print houses running 15-year-old job-ticketing systems face API mismatch friction when connecting cloud RIP nodes to on-premises ERP infrastructure.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RIP Software Market Trends and Innovations
Computational color science and edge-deployment architectures are redistributing processing loads while regulatory chemistry constraints rewrite ink-output optimization requirements.
Neural-network halftoning is absorbing traditional error-diffusion algorithms in high-end proofing installations. Commercial print houses in the Netherlands and California are piloting GPU-accelerated screening that learns substrate-specific dot-gain compensation from spectrophotometer feedback loops. This compression of color-matching iteration cycles is absorbing premium service revenue from independent profiling consultancies.
REACH chemical restrictions on N-methyl-2-pyrrolidone and other solvent carriers are forcing reformulation of ink limiting curves across European wide-format installations. RIP vendors must now model low-VOC UV ink rheology with viscosity-temperature compensation tables that were unnecessary for solvent chemistries. German textile printers are responding by consolidating vendor relationships around suppliers with integrated ink-RIP validation programs.
Subscription billing for RIP seats is displacing perpetual licensing among mid-tier signage shops that prioritize cash-flow flexibility over depreciation schedules. Channel partners in France and the UK are unbundling installation and training services from core software fees, creating transparent cost structures that accelerate competitive switching. This procurement model evolution is most visible in commercial print clusters where private-equity ownership demands predictable operational expenditure profiles.
RIP Software Market Segmentation
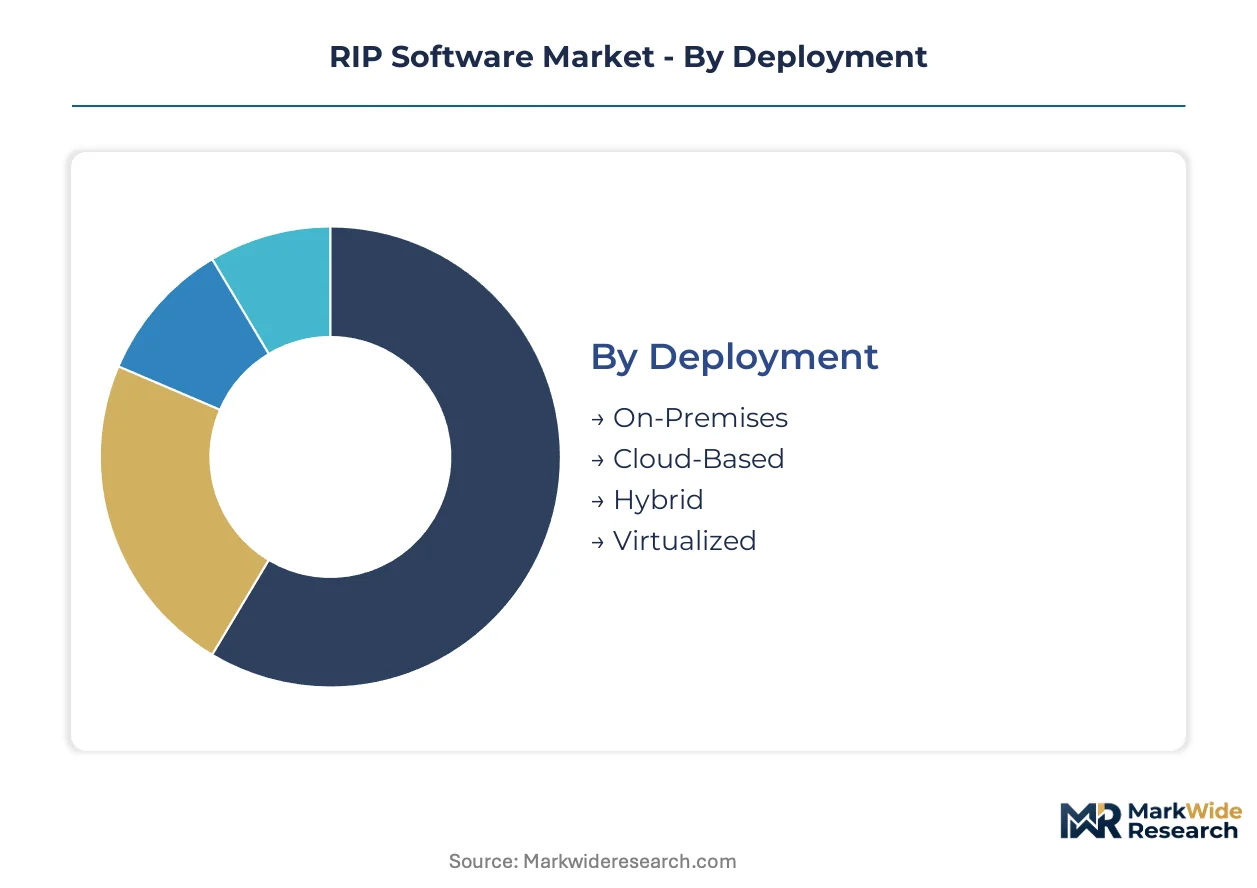
RIP software purchasing decisions pivot on integration complexity and recurring cost structures. Deployment architecture determines upfront capital allocation, while solution type governs ongoing operational expenditure profiles across print workflows.
Deployment:
Capital intensity varies sharply across deployment modes, with perpetual licensing and dedicated hardware imposing the heaviest initial outlays.
- On-Premises:Perpetual licenses paired with dedicated server infrastructure dominate high-volume commercial installations in Germany and Japan. Heidelberg and Koenig & Bauer anchor clusters where local data sovereignty and sub-millisecond job queuing justify seven-figure hardware commitments.
- Cloud-Based:Subscription metering compresses entry costs for mid-tier French and UK signage shops. Private-equity-owned print houses prioritize operational expenditure predictability over depreciation schedules, accelerating displacement of perpetual models.
- Hybrid:Split architectures preserve sensitive color profiles on-premises while offloading routine rasterization to elastic cloud nodes. Packaging converters in the Netherlands pilot this configuration to balance IP protection with burst capacity.
- Virtualized:Containerized RIP kernels enable multi-tenant print service bureaus to share GPU-accelerated screening resources across client silos.
On-Premises absorbs the bulk of installed capacity; Cloud-Based is expanding most quickly.
Solution Type:
Application complexity and integration depth separate premium-priced modules from commodity rasterization engines.
- Raster Image Processing:Core halftoning and ink-limiting algorithms process 16-bit color spaces at resolutions up to 2400 dpi for industrial inkjet heads. German textile printers demand multi-pass UV optimization and LED-curing curve calibration as solvent lines retire.
- Color Management:Delta-E tolerance compression in luxury packaging now enforces sub-1.0 variance specifications. Custom closed-loop calibration development commands premium pricing as standard ICC profiles prove inadequate.
- Workflow Automation:JDF-compliant job ticketing collapses prepress turnaround from hours to minutes. Mid-tier packaging converters embed RIP nodes directly into e-commerce storefronts.
- Print Optimization:Neural-network halftoning learns substrate-specific dot-gain compensation from spectrophotometer feedback loops in Dutch and Californian proofing installations.
- File Rippling:Distributed processing architectures parallelize large-format job rendering across compute clusters for deadline-critical signage workflows.
Raster Image Processing commands the deepest installed base; Workflow Automation is climbing the fastest.
Application:
Substrate chemistry and regulatory exposure shape solution customization requirements across verticals.
- Digital Printing:UV-curable inkjet displacement drives demand for reformulated output curves as EU F-Gas Regulation restricts fluorinated greenhouse gases. Commercial print houses retire solvent-based flexo lines.
- Textile Printing:REACH restrictions on N-methyl-2-pyrrolidone force viscosity-temperature compensation tables for low-VOC UV ink rheology. German printers consolidate around suppliers with integrated ink-RIP validation programs.
- Packaging Design:CDSCO pharmaceutical serialization mandates in India create demand for track-and-trace RIP modules integrating variable-data printing with anti-counterfeiting layers.
- Large Format Printing:Water-based latex systems require reformulated color-limiting algorithms as wide-format operators abandon solvent chemistries.
- Proofing:GPU-accelerated screening absorbs premium service revenue from independent profiling consultancies through compressed color-matching iteration cycles.
Digital Printing retains the largest operational footprint; Packaging Design is gaining share fastest.
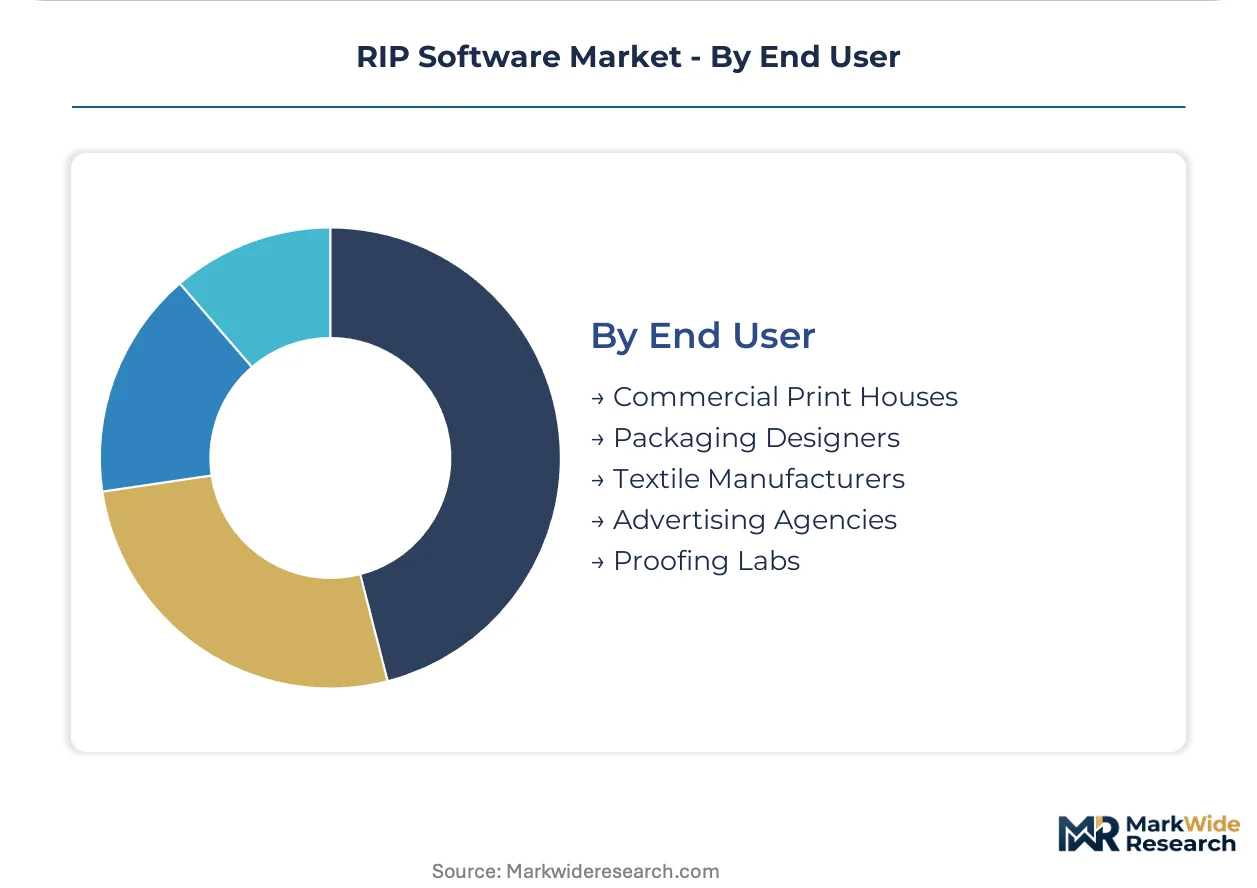
End User:
Technical sophistication and compliance burden stratify purchasing authority and implementation complexity.
- Commercial Print Houses:EPA emissions thresholds on US facilities drive compliance demand for ink-usage tracking embedded in RIP dashboards. VOC reporting requirements influence vendor selection.
- Packaging Designers:Brand owner enforcement of tighter Delta-E tolerances across proofing applications prioritizes premium color management modules.
- Textile Manufacturers:Dye-sublimation and direct-to-garment presses require specialized RIP kernels optimized for fabric-specific ink penetration and fixation profiles.
- Advertising Agencies:Web-to-print integration demands API-embedded RIP nodes with rapid turnaround for campaign-driven production schedules.
- Proofing Labs:Spectrophotometer feedback loops and closed-loop calibration development anchor service differentiation in high-end color verification.
Commercial Print Houses dominate current deployment; Packaging Designers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg anchors commercial print demand in Germany's Rhine-Neckar metropolitan region, where UV-curable inkjet displacement concentrates among high-volume commercial installations.
Germany
Heidelberg and Koenig & Bauer anchor high-volume print clusters in the Rhine-Neckar and Bavaria regions. The EU F-Gas Regulation restricts fluorinated greenhouse gases, pushing wide-format operators toward water-based latex systems requiring reformulated color-limiting algorithms. German textile printers in Baden-Württemberg consolidate vendor relationships around suppliers with integrated ink-RIP validation programs.
United States
Commercial print houses in California and the Northeast face EPA emissions thresholds on commercial print facilities. The EPA enforces facility-wide VOC reporting thresholds, creating compliance demand for ink-usage tracking embedded in RIP dashboards. GPU-accelerated neural-network halftoning pilots in California absorb premium service revenue from independent profiling consultancies.
Japan
Commercial print houses in Tokyo and Osaka retire solvent-based flexo lines, requiring RIP kernels with multi-pass UV optimization and LED-curing curve calibration. METI industrial policy supports inkjet technology transitions through equipment depreciation incentives. Nagoya-area packaging converters embed JDF-compliant RIP nodes into automated production lines.
India
Domestic pharmaceutical serialization mandates under CDSCO create demand for track-and-trace RIP modules integrating variable-data printing with anti-counterfeiting layers. Maharashtra-based packaging converters prioritize web-to-print integration for rapid turnaround on pharmaceutical contract manufacturing. Bengaluru print service bureaus pilot containerized RIP kernels for multi-tenant GPU resource sharing.
Netherlands
Packaging converters in the Randstad region pilot hybrid RIP architectures preserving sensitive color profiles on-premises while offloading routine rasterization to elastic cloud nodes. ECHA REACH restrictions on N-methyl-2-pyrrolidone force viscosity-temperature compensation tables for low-VOC UV ink rheology. Amsterdam-area proofing labs deploy spectrophotometer feedback loops for sub-1.0 Delta-E tolerance compression.
RIP Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the RIP software landscape, where integrated hardware-software stacks face pressure from modular, API-first entrants. The vendor base stratifies into three tiers: premium color-managed suites commanding six-figure perpetual licenses, mid-market subscription offerings, and commodity rasterization tools competing on seat price. Dominant competitive moves include cloud-native architecture rebuilds to capture recurring revenue and strategic partnerships with independent profiling houses to accelerate substrate validation.
Within the premium integrated-stack tier, Electronics for Imaging and Caldera occupy positions defined by captive hardware ecosystems and specialized workflow kernels respectively. SA International exemplifies the signage-specialist archetype, where nesting and cutting-path algorithms anchor differentiated value in CNC-adjacent segments. Among hardware-captive Japanese developers, Mimaki Engineering and Roland DG represent RIP distribution strategies tied to proprietary print engine architectures.
| Leading Market Players |
|---|
| Electronics for Imaging |
| Caldera |
| Onyx Graphics |
| Ergosoft AG |
| Mimaki Engineering |
| Seiko Epson Corporation |
| Roland DG |
| GMG Color |
| SA International |
| Others |
Pricing and Supply Chain Analysis
GPU memory pricing volatility cascades through RIP software supply chains, compressing margins on hardware-captive bundles while pushing standalone vendors toward subscription metering to isolate cost shocks from end-user pricing tiers.
Pricing Analysis
Throughput-based pricing anchors premium RIP suites, where vendors meter charges against monthly square-meter output or job queue depth rather than perpetual seat licenses. Three-tier pricing structure across premium, standard, and economy levels separates color-managed proofing installations from mid-market web-to-print nodes and commodity rasterization tools. Price differentiation hinges on ICC certification tier and bundled spectrophotometer integration. Cost compression in the economy tier is intensifying because cloud-native entrants are undercutting perpetual-license incumbents on entry-level signage workflows. Mid-tier packaging converters show highest price sensitivity, while luxury brand proofing labs absorb premium pricing for sub-1.0 Delta-E guarantees.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke fulfillment for RIP hardware-software bundles, with Heidelberg and Electronics for Imaging operating captive logistics nodes near Rhine-Neckar and Silicon Valley print clusters. Supply concentration draws from Taiwan for GPU accelerators, South Korea for industrial inkjet printheads, and Germany for spectrophotometer subassemblies. Single-source vulnerability around NVIDIA GPU allocations for neural-network halftoning creates procurement bottlenecks during semiconductor cycle tightness. Distribution runs through authorized dealer networks with embedded field engineering, though direct-to-manufacturer cloud provisioning is eroding channel leverage in mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
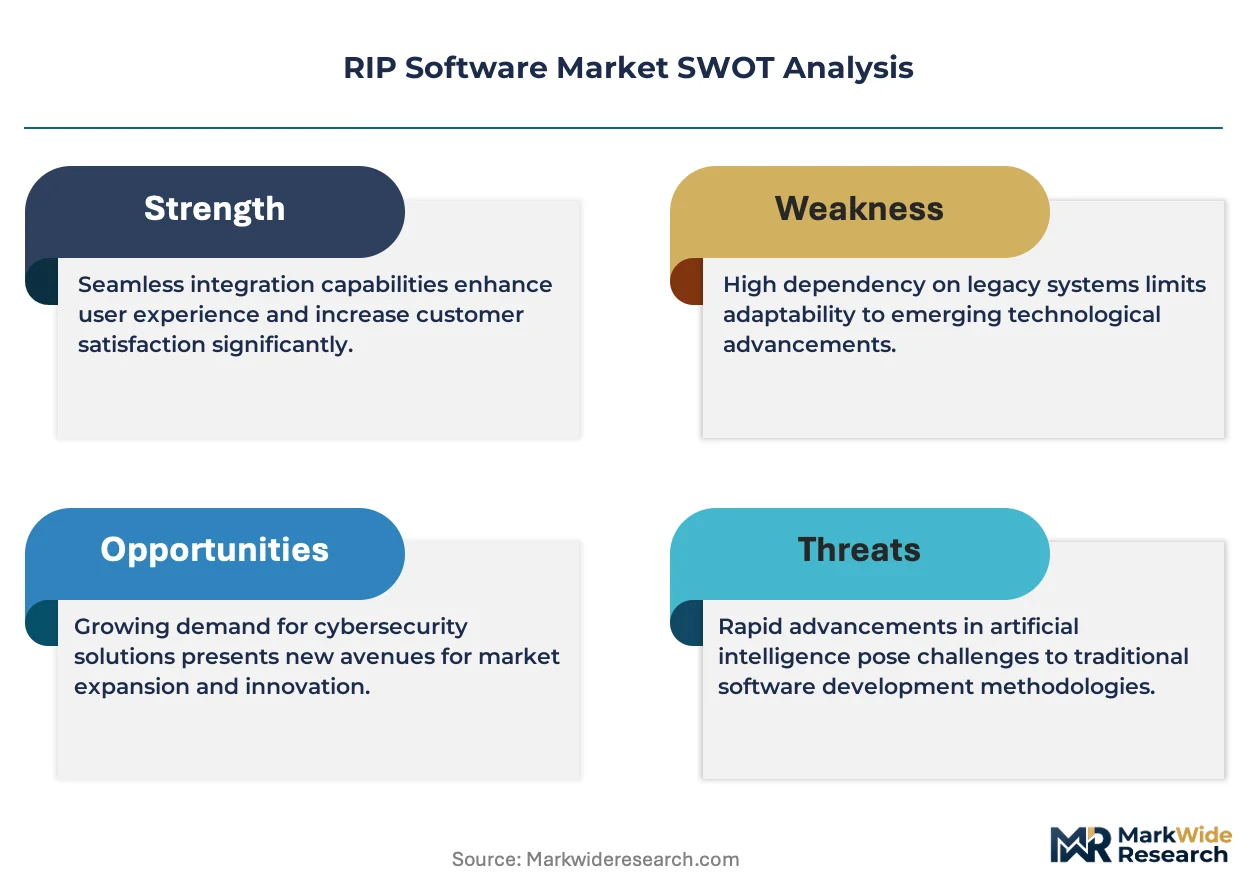
Specialized color science talent scarcity props pricing power for vendors with captive ICC profiling labs, constraining supply expansion faster than demand absorption across packaging and textile verticals.
For Market Incumbents: Hedge against cloud-native displacement by embedding consumption-based metering into legacy installed bases before subscription economics fully commoditize rasterization kernels. Acquire independent profiling houses in the Netherlands and California to consolidate substrate validation capabilities that emerging entrants cannot replicate without multi-year color science investment. Defensive patent filings around GPU-accelerated neural halftoning will raise barriers for AI-first challengers targeting proofing workflows.
For New Entrants and Emerging Players: Regional print service bureaus in India and Southeast Asia offer the most penetrable channel partner type for API-first RIP modules, as these operators lack legacy MIS integration debt and prioritize web-to-print connectivity over color fidelity. White-space targets include CDSCO-compliant pharmaceutical serialization workflows and containerized multi-tenant architectures for GPU resource pooling. Go-to-market execution should anchor on consumption-based trials that bypass capital-commitment friction among private-equity-owned print houses.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market SaaS RIP vendors with recurring revenue above sixty percent and vertical integration into textile-specific ink-RIP validation programs in Germany. Long-term viability hinges on defensible color science IP and API ecosystem lock-in rather than hardware-captive distribution. Monitor EPA enforcement patterns on commercial print facility VOC thresholds as the inflection signal for compliance-embedded RIP dashboard demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Subscription metering captures recurring revenue from mid-tier French and UK signage shops prioritizing operational expenditure predictability. |
| AI-Driven Halftoning Acquisition | GPU-accelerated neural networks compress color-matching cycles and absorb premium service revenue from independent Dutch profiling consultancies. |
| Regulatory Compliance Module Development | EPA emissions tracking dashboards capture compliance budgets from US commercial print facilities facing facility-wide VOC reporting thresholds. |
| Textile Ink-RIP Validation Integration | REACH restrictions on N-methyl-2-pyrrolidone force German printers to consolidate around suppliers with captive low-VOC UV rheology modeling. |
| Hybrid Deployment Architecture Launch | Split on-premises and cloud configurations balance IP protection with burst capacity for Randstad packaging converters. |
Research Methodology
SEC 10-K filings, ECHA REACH substance restriction databases, and EPA enforcement action records formed the secondary backbone, cross-referenced against primary interviews with RIP software product managers, commercial print house operations directors, and color science laboratory technical leads. Triangulation across bottom-up vendor revenue assessments and top-down print industry expenditure models validated segmentation splits across deployment architecture, solution type, and end-user vertical. Stakeholder input captured cloud migration timelines, substrate validation bottlenecks, and regulatory compliance budgeting practices.
Historical trendline analysis of perpetual-license revenue erosion and subscription adoption curves informed projection frameworks across the analysis window. Segmentation dimensions modeled include deployment mode, solution type, application vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to vendor-reported seat expansions and print industry capital expenditure surveys. Industry-specific inputs incorporate EU F-Gas Regulation phase-out schedules and CDSCO pharmaceutical serialization mandate compliance deadlines.
Caveats apply where GPU semiconductor cycle volatility, REACH chemical restriction expansions, or abrupt cloud vendor pricing changes could materially shift the outlook. Forecasts reflect documented assumptions around regulatory enforcement intensity and print house technology refresh cadence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.