
 Background Removal Software Market | 2026-2036
Background Removal Software Market Size, Share, and Industry Trends Forecast 2026-2036
Background Removal Software Market Insights
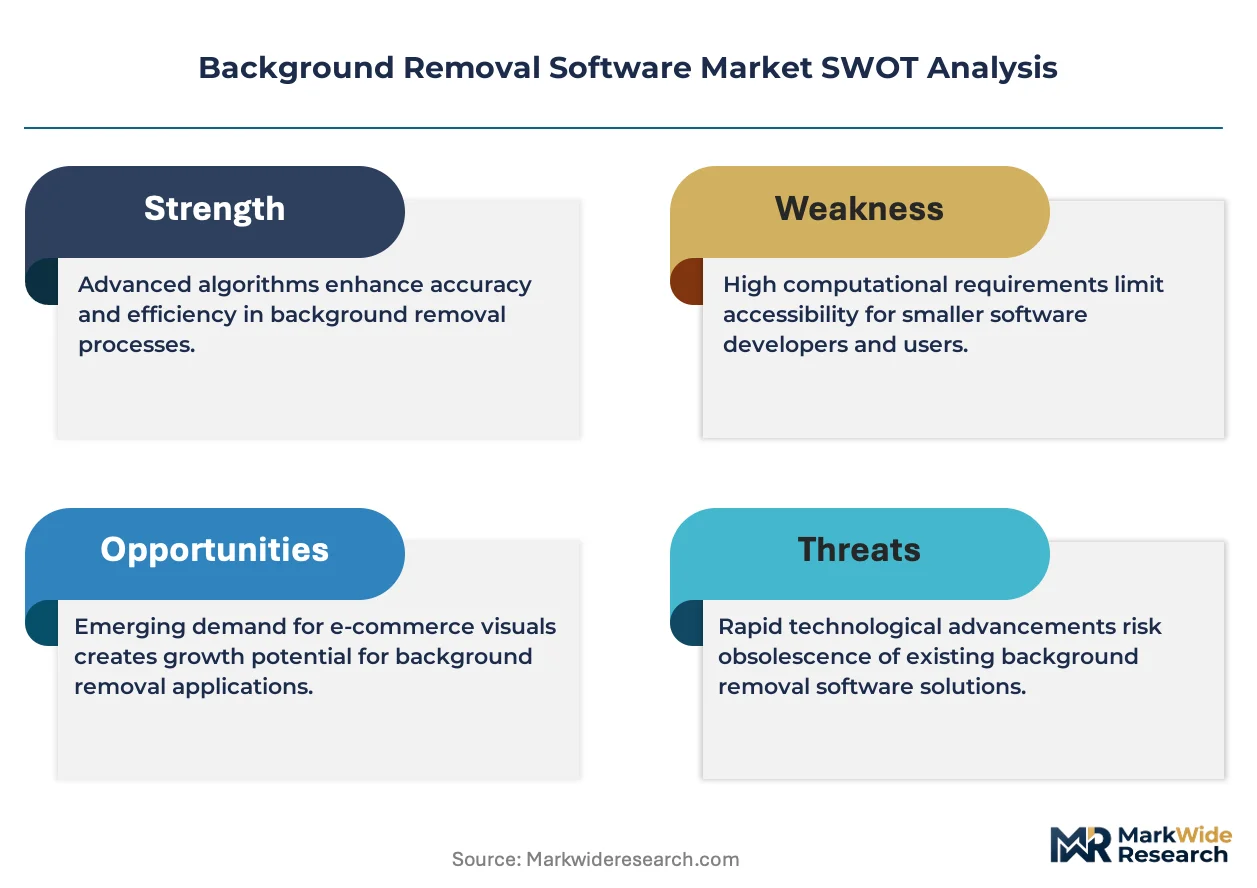
Diffusion-based generative AI is reshaping how background removal tools handle edge detection around hair, fur, and translucent materials. Remove.bg leverages proprietary convolutional neural networks to sustain sub-second processing speeds for high-volume e-commerce catalogs. Photoroom anchors its position through mobile-first architecture optimized for social commerce sellers. Clipdrop competes via API-first distribution that embeds directly into creative software pipelines.
Background removal software isolates foreground subjects from digital imagery through alpha matting, chroma keying, or machine-learned segmentation masks operating at pixel-level precision. The technology serves commercial photography, automated catalog production, and video compositing workflows where clean subject isolation determines visual output quality. SaaS deployment leads among small businesses seeking pay-per-image economics without infrastructure overhead, while AI-Powered processing displaces manual editing across high-volume e-commerce use cases where batch throughput governs operational cost. Plugin integrations into Adobe Creative Cloud and Figma concentrate margin pools among professional graphic design workflows.
The EU AI Act mandates algorithmic transparency for automated image processing services deployed to European consumers, compelling vendors to document training data provenance and inference decision logic. The US Federal Trade Commission scrutinizes subscription billing practices and output ownership claims in generative AI tools under Section 5 unfair competition authority. ISO/IEC 42001 emerging AI management standards will likely shape enterprise procurement criteria for background removal vendors serving corporate marketing departments. Stakeholders must weigh on-device processing investments against cloud latency trade-offs as privacy regulations fragment across jurisdictions.
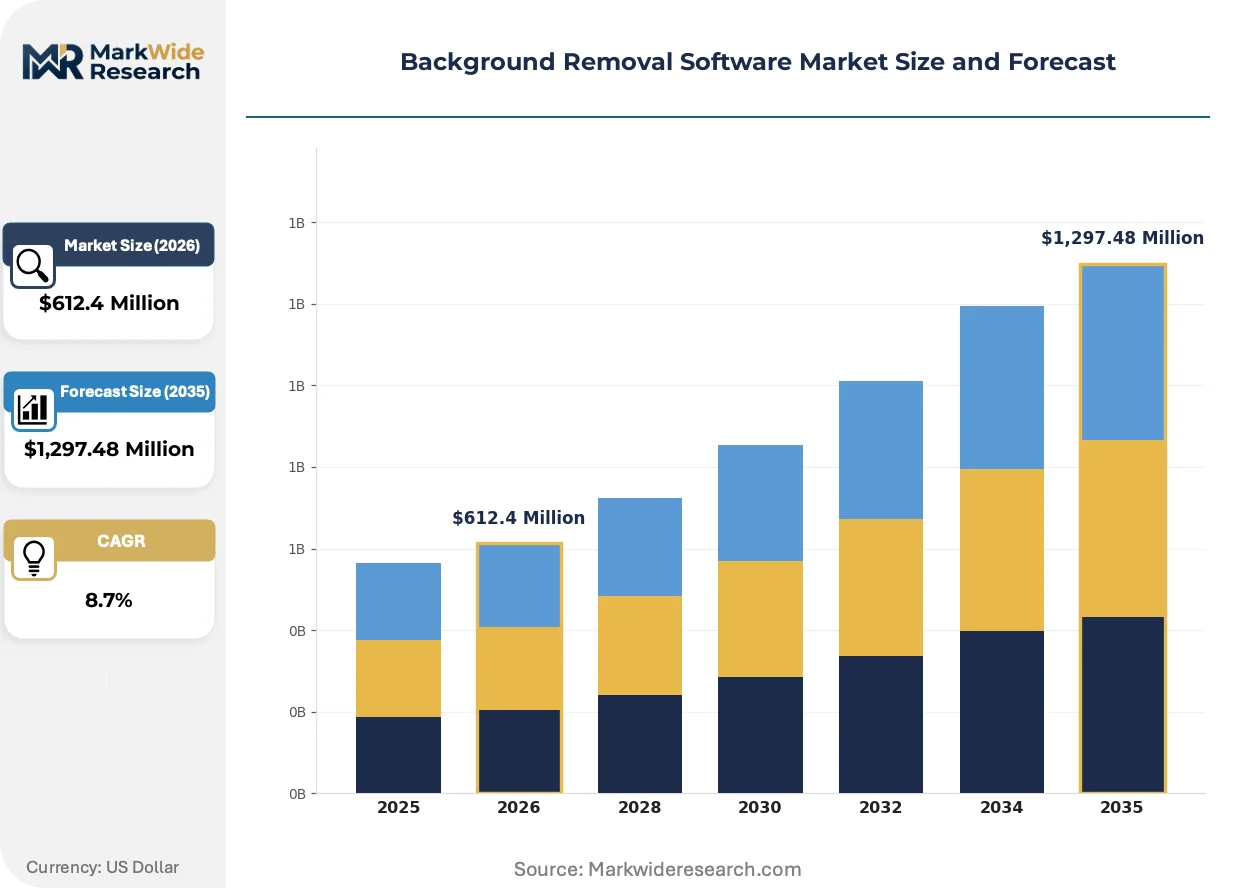
Market Dynamics
Diffusion-based generative models are compressing processing latency while elevating edge precision around hair, fur, and translucent materials, forcing vendors to re-architect inference pipelines for sub-second throughput at enterprise scale.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic documentation requirements are accelerating investment in explainable segmentation architectures that European marketing departments now specify in procurement criteria.
- Social commerce seller ecosystems:Mobile-first background removal workflows are displacing desktop editing for influencer-driven product photography across Instagram and TikTok commerce integrations.
- On-device processing architectures:Edge AI chipsets from Qualcomm and Apple are enabling local inference that satisfies GDPR data residency requirements without cloud round-trips.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for diffusion models remain exposed to NVIDIA data center pricing cycles and cloud provider capacity constraints.
- Training data provenance risk:Unlicensed stock photography in foundation model datasets creates litigation exposure under US copyright doctrine and emerging right-of-publicity statutes.
- Manual masking substitution:Offshore retouching studios in Bangladesh and Vietnam continue to undercut AI tools on complex editorial imagery where edge precision failures require human rework.
Strategic Opportunities
- Live video commerce in India:Real-time background replacement for influencer streaming remains underpenetrated despite Reliance Jio's 5G infrastructure rollout and government PLI scheme support for domestic AI development.
- ISO/IEC 42001 certification:Enterprise procurement departments are beginning to require AI management system certification, creating a compliance-based segmentation wedge for certified vendors.
- API-embedded creative workflows:Direct integration into Figma and Canva design environments is displacing standalone SaaS subscriptions among mid-market creative teams.
Industry Challenges
- Matting algorithm talent scarcity:Deep expertise in alpha channel estimation and color spill suppression concentrates among computer vision PhDs at a handful of academic labs and frontier AI research groups.
- Legacy Adobe workflow integration:Enterprise creative departments with entrenched Creative Cloud contracts resist API migration due to retraining costs and plugin certification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Background Removal Software Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, SaaS, Plugin, Mobile App Use Case: E-commerce, Photography, Graphic Design, Video Production Technology: AI-Powered, Manual Editing, Cloud-Based, Batch Processing End User: Professionals, Small Businesses, Corporates, Individual Consumers |
| Companies Covered | Pixelcut, Pixelbin.io, Remove.bg, Slazzer, Cutout.pro, Photoroom, Clipdrop, Removal.AI, Claid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Background Removal Software Market Trends and Innovations
Generative AI architectures are redefining competitive differentiation around inference speed, edge case handling, and privacy-preserving deployment modes. Three forces are compressing vendor margins while expanding addressable use cases.
Transformer-based segmentation models with attention mechanisms are rendering obsolete traditional encoder-decoder CNNs that struggle with fine-grained detail around hair strands and glass reflections. High-volume e-commerce catalog operations are adopting these architectures for batch processing pipelines where failure rates on complex product categories previously required manual quality control. The structural consequence is a compression in acceptable error rates from percentage points to basis points, raising baseline performance floors for market entry.
The EU AI Act's risk classification system for automated image processing services is forcing vendors to document training data provenance and inference decision logic for deployment to European consumers. Marketing technology procurement teams in Germany and France are now requiring algorithmic impact assessments as standard contract terms. Mid-tier SaaS providers without compliance infrastructure are ceding enterprise accounts to certified competitors or exiting the European market entirely.
Consumption patterns among creative professionals are fragmenting from subscription bundles toward usage-based API pricing tied to specific output volumes. Design teams at direct-to-consumer brands are unbundling background removal from comprehensive creative suites, procuring point solutions through marketplace integrations rather than enterprise licensing. This shift is most visible in the United States, where Shopify merchant ecosystems drive pay-per-image economics that prioritize throughput over feature depth.
Background Removal Software Market Segmentation
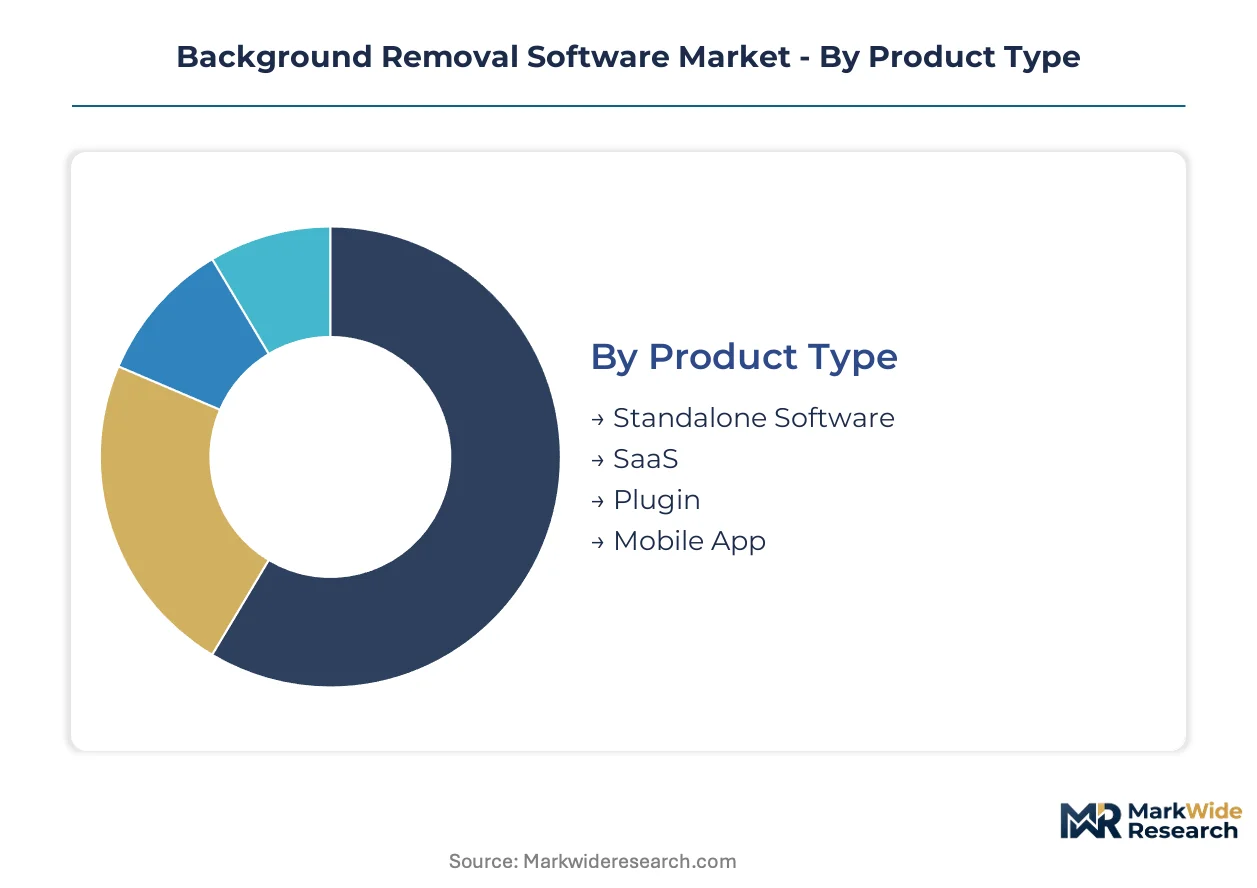
Segmentation in background removal software reveals divergent technology stacks and procurement economics across customer tiers. Product architecture choices determine whether vendors capture enterprise licensing revenue or consumer subscription volumes.
Product Type:
Mature deployment models now coexist with emerging distribution formats as buyer preferences fragment across technical sophistication levels.
- SaaS:Browser-based inference pipelines eliminate local GPU requirements and enable pay-per-image economics for high-volume e-commerce catalogs. Shopify and Amazon Marketplace merchants in the United States drive enterprise licensing at scale for this segment.
- Plugin:Direct integration into Adobe Creative Cloud and Figma design environments captures professional graphic design workflows where plugin certification delays create switching costs. Adobe's entrenched enterprise contracts concentrate margin pools among certified developers.
- Standalone Software:Desktop applications with local processing satisfy GDPR data residency requirements for European marketing departments.
- Mobile App:On-device inference leveraging Qualcomm and Apple edge AI chipsets serves influencer-driven product photography across Instagram and TikTok commerce integrations.
SaaS handles the majority of throughput; Mobile App is gaining share fastest among social commerce sellers.
Use Case:
Application intensity varies sharply by output quality requirements and batch processing scale across commercial workflows.
- E-commerce:Automated catalog production pipelines demand sub-second processing speeds for thousands of product images with standardized white backgrounds. Amazon Marketplace and Shopify merchant ecosystems in the United States anchor procurement volume for this segment.
- Graphic Design:Pixel-level precision requirements around hair, fur, and translucent materials sustain premium pricing for diffusion-based generative architectures with attention mechanisms.
- Photography:Portrait studios and wedding photographers prioritize edge precision over throughput, resisting full automation for complex editorial imagery.
- Video Production:Real-time chroma keying for live streaming and post-production compositing requires frame-consistent matting across temporal sequences.
E-commerce commands the largest addressable base; Video Production is expanding most quickly as live commerce formats proliferate.
Technology:
Processing architecture choices determine compliance posture, latency profiles, and capital intensity for vendors and buyers alike.
- AI-Powered:Transformer-based segmentation models with attention mechanisms render traditional encoder-decoder CNNs obsolete for fine-grained detail around hair strands and glass reflections. EU AI Act algorithmic transparency mandates accelerate investment in explainable segmentation architectures.
- Cloud-Based:Centralized inference exposes users to data residency risks under GDPR and emerging ISO/IEC 42001 procurement criteria.
- Batch Processing:Pipeline automation for high-volume catalog operations compresses acceptable error rates from percentage points to basis points.
- Manual Editing:Offshore retouching studios in Bangladesh and Vietnam continue undercutting AI tools on complex editorial imagery where edge precision failures require human rework.
AI-Powered dominates new procurement; Cloud-Based faces displacement from on-device alternatives.
End User:
Customer tier determines pricing model tolerance, feature depth requirements, and integration complexity.
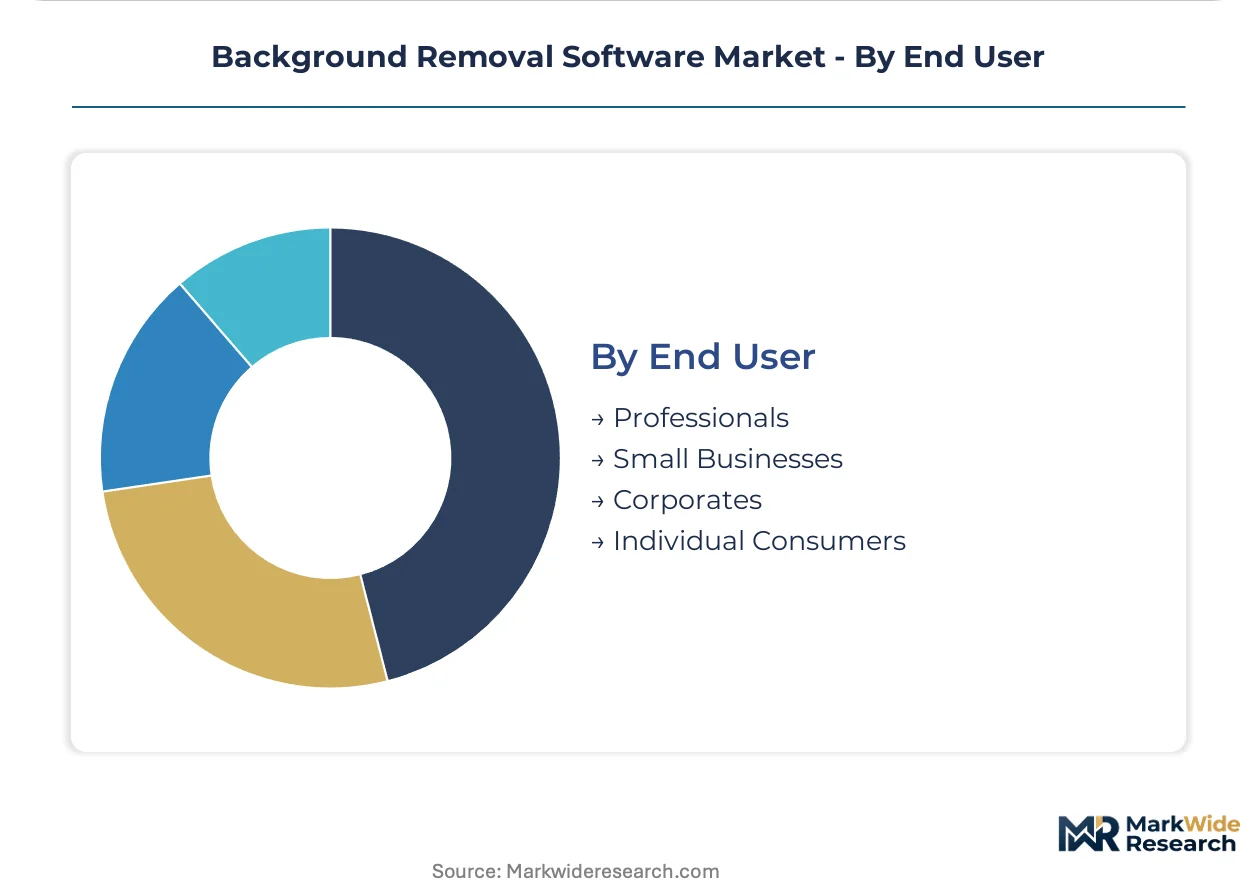
- Corporates:Enterprise marketing departments require ISO/IEC 42001 certification, algorithmic impact assessments, and API-embedded creative workflows. Procurement teams in Germany and France mandate these specifications as standard contract terms.
- Small Businesses:Pay-per-image economics without infrastructure overhead align with variable marketing budgets and seasonal campaign cycles.
- Professionals:Graphic designers and photographers resist API migration due to retraining costs and entrenched Creative Cloud contracts.
- Individual Consumers:Mobile-first workflows optimized for social commerce displace desktop editing among influencer-driven sellers.
Corporates generate the highest contract values; Individual Consumers represent the steepest expansion trajectory as mobile penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software licensing flows concentrate in jurisdictions with dense e-commerce merchant ecosystems and stringent data governance frameworks. The United States exports SaaS architectures while importing specialized mobile-first tools from European and Asian developers. Cross-border API traffic now dominates value exchange in this category.
United States
Amazon Marketplace and Shopify merchant ecosystems anchor enterprise procurement at scale, with direct-to-consumer brands driving pay-per-image economics through embedded workflow integrations. The Federal Trade Commission scrutinizes subscription billing practices and output ownership claims under Section 5 unfair competition authority. Seattle and San Francisco Bay Area clusters host the dominant API-first distribution platforms serving creative software pipelines.
Germany
Industrial marketing departments and automotive catalog operations demand ISO/IEC 42001 certification and algorithmic impact assessments as standard contract terms. The EU AI Act mandates algorithmic transparency for automated image processing services deployed to European consumers. Munich and Berlin concentration of enterprise SaaS procurement teams is accelerating investment in explainable segmentation architectures.
United Kingdom
Creative agency networks and publishing houses sustain premium pricing for diffusion-based generative architectures with attention mechanisms around complex editorial imagery. The UK Information Commissioner's Office enforces GDPR-aligned data residency requirements that favor on-device processing alternatives. London's Shoreditch and Soho districts concentrate influencer-driven social commerce sellers adopting mobile-first background removal workflows.
India
Reliance Jio's 5G infrastructure rollout and government PLI scheme support for domestic AI development are expanding real-time background replacement for live video commerce. The Telecom Regulatory Authority of India governs data localization expectations for cloud-based image processing services. Bangalore and Hyderabad clusters of computer vision engineering talent are matting algorithm development centers for export-oriented SaaS providers.
Japan
Luxury fashion e-commerce and portrait studio workflows prioritize edge precision over throughput, resisting full automation for complex editorial imagery. The Ministry of Economy, Trade and Industry promotes edge AI chipset adoption through domestic semiconductor manufacturing incentives. Tokyo's Shibuya and Harajuku districts anchor influencer-driven product photography demand for mobile-optimized background removal tools.
Background Removal Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Frontier AI research groups and computer vision PhD concentrations at academic labs control deep expertise in alpha channel estimation. Mid-tier SaaS providers without compliance infrastructure are ceding European enterprise accounts to certified competitors. Dominant competitive moves include API-embedded creative workflow partnerships and on-device processing architecture investments.
Within the API-first distribution tier, Remove.bg and Clipdrop exemplify sub-second inference pipeline architectures serving high-volume e-commerce catalogs. Photoroom occupies a position in the mobile-native segment optimized for social commerce seller ecosystems across Instagram and TikTok integrations. Pixelcut anchors the standalone software archetype with desktop applications satisfying GDPR data residency requirements for European marketing departments.
| Leading Market Players |
|---|
| Pixelcut |
| Pixelbin.io |
| Remove.bg |
| Slazzer |
| Cutout.pro |
| Photoroom |
| Clipdrop |
| Removal.AI |
| Claid |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific fiber optic cable latency costs between Singapore and Los Angeles govern cloud inference economics for background removal vendors, concentrating margin pressure on SaaS providers serving United States e-commerce merchants while enabling price differentiation between edge-based and centralized processing tiers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing stratified across premium API tiers, standard SaaS bundles, and economy pay-per-image models. Price differentiation separates ISO/IEC 42001-certified enterprise licenses from uncertified mid-tier offerings, with GDPR compliance premiums widening spreads. Pricing pressure stems from GPU compute cost volatility under NVIDIA data center pricing cycles. Small business merchants exhibit highest price sensitivity, while corporate marketing departments tolerate premium tiers for algorithmic transparency documentation.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk for edge AI chipset procurement, with Qualcomm and Apple silicon sourcing concentrated in Taiwan and South Korea. Training infrastructure draws from NVIDIA GPU fabrication anchored in Taiwan, cloud server assembly in Mexico, and data center energy feeds from Texas and Virginia grids. Single-source vulnerability concentrates in TSMC's advanced node capacity. Distribution runs through API-first embedding into Shopify and Adobe Creative Cloud marketplaces rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as Figma and Canva marketplace integrations displace standalone SaaS subscriptions, with interoperability becoming the primary value capture mechanism.
For Market Incumbents: Insulate enterprise relationships through ISO/IEC 42001 certification investments and API-embedded creative workflow partnerships that raise switching costs against emerging diffusion-model entrants. Deepen backward integration into proprietary training data pipelines to reduce provenance litigation exposure. Prioritize on-device processing architecture R&D to preempt GDPR-driven procurement shifts away from cloud inference. For New Entrants and Emerging Players: Pursue live video commerce infrastructure in India, where Reliance Jio's 5G rollout and government PLI scheme support create white-space conditions for real-time background replacement tools. Target influencer-driven social commerce sellers across Instagram and TikTok integrations with mobile-first architectures. Deploy usage-based API pricing to unbundle from incumbent subscription bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier SaaS providers lacking EU AI Act compliance infrastructure, as these vendors cede European enterprise accounts to certified competitors. Long-term viability favors vendors with transformer-based segmentation expertise and edge AI deployment capabilities. Monitor algorithmic impact assessment procurement requirements in Germany and France as inflection indicators for compliance-based market segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Direct embedding into Figma and Canva displaces standalone subscriptions among mid-market creative teams. |
| Certification Investment | ISO/IEC 42001 compliance opens procurement channels with German automotive and industrial marketing departments. |
| On-Device Architecture | Qualcomm and Apple edge AI chipsets enable GDPR-compliant processing without cloud round-trips. |
| API-First Distribution | Sub-second inference pipelines capture high-volume Shopify and Amazon Marketplace merchant workflows. |
| Acquisition of Specialist Firm | Computer vision PhD talent concentrations at academic labs anchor alpha matting algorithm differentiation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, App Annie mobile usage data, and EU regulatory registers. Conversations with CTOs at direct-to-consumer brands, IT procurement officers at enterprise marketing departments, platform engineers at creative software vendors, and integration specialists at e-commerce marketplaces informed demand-side dynamics. Bottom-up triangulation across merchant volume estimates and top-down validation against SaaS revenue disclosures anchored market sizing.
Forecast inputs span deployment model, organization size, vertical application, integration complexity, and regional adoption pattern across the projection horizon. Segmentation modeling incorporated e-commerce catalog throughput requirements, video production frame-consistency specifications, and graphic design pixel-precision thresholds. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns and enterprise procurement cycle analysis.
Macroeconomic conditions sit as an overlay; deviation in cloud compute pricing cycles, GPU supply constraints, or EU AI Act enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on merchant ecosystem expansion rates and edge AI chipset penetration curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Continuous Integration Tools Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Driver Updater Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Home Fitness App Market
Software & Services
Broadcast Scheduling Software Market
Software & Services
Server Software Market
Software & Services
3D Animation Software Market
Software & Services
Codeless Testing Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
3D Animation Production Software Market
Software & Services
Meditation Management Apps Market
Software & Services
B2B Price Optimization and Management Software Market