
 Drug Screening Laboratory Service Market | 2026-2036
Drug Screening Laboratory Service Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Screening Laboratory Service Market Insights
North American reference laboratory capacity is rebalancing as specialized toxicology operations scale to meet post-pandemic workplace testing normalization. Quest Diagnostics leverages its national collection site network to sustain volume leadership in employer-mandated programs. LabCorp anchors its position through integrated clinical and forensic toxicology workflows. Thermo Fisher Scientific differentiates via analytical instrument supply and companion method-development services for third-party labs.
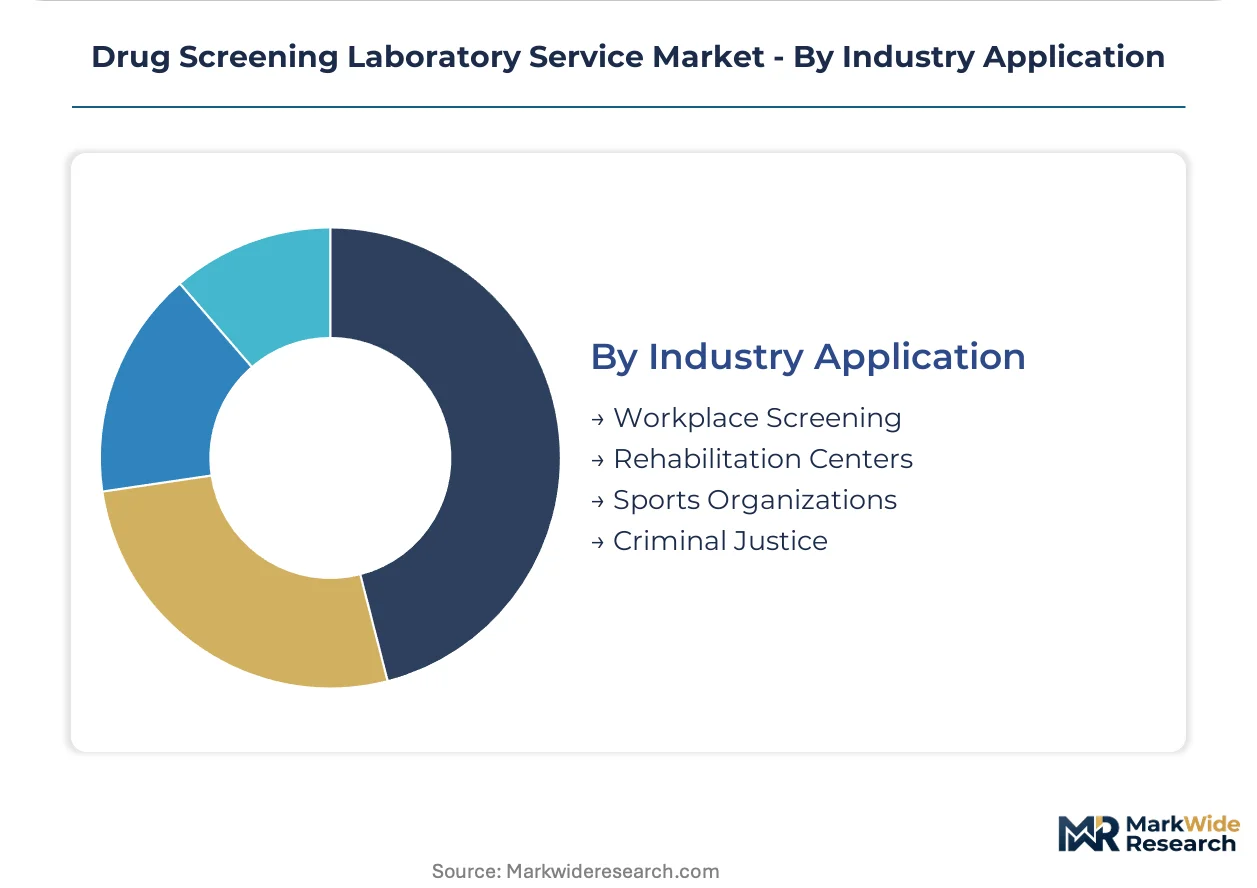
Drug screening laboratory service encompasses the collection, analysis, and certified reporting of biological specimens to detect controlled substances, prescription medications, and illicit drugs using validated cutoff concentrations and chain-of-custody protocols. These services serve employers, legal systems, and treatment providers requiring defensible, legally admissible results for hiring decisions, compliance monitoring, and clinical interventions. Urine testing occupies the largest service-type share due to established federal guidelines and cost efficiency, though hair testing captures growing share among employers seeking longer detection windows. Workplace screening dominates industry application revenue, while rehabilitation centers represent the fastest-expanding client segment as value-based addiction treatment models proliferate.
FDA regulates in vitro diagnostic devices and laboratory-developed tests used in screening panels, while SAMHSA certifies laboratories under the National Laboratory Certification Program for federal workplace testing. State-level variations in marijuana legalization create compliance fragmentation that laboratories must navigate through jurisdiction-specific testing menus and reporting thresholds. Stakeholders should monitor evolving state employment law precedents on cannabis testing to anticipate structural shifts in corporate screening demand.
Market Dynamics
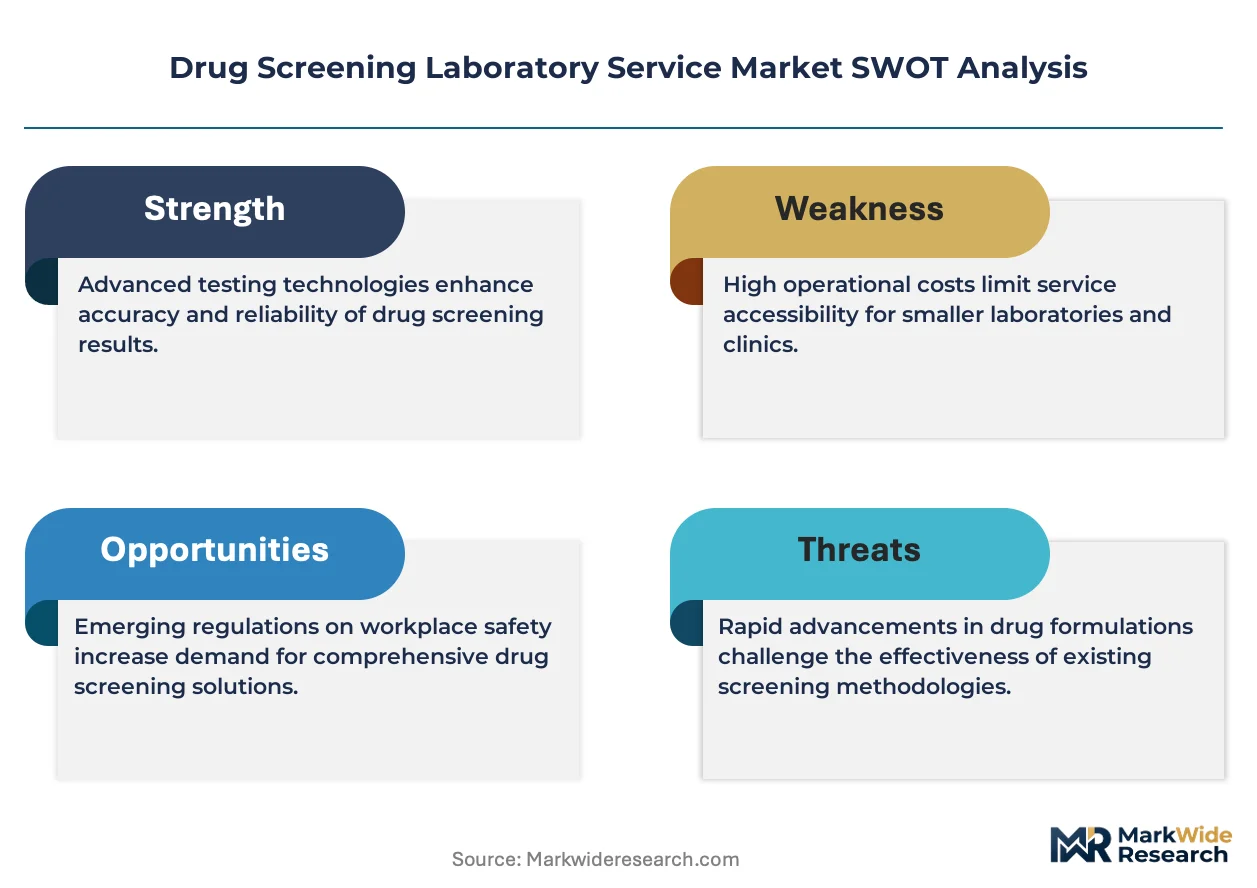
Federal workplace testing mandates and state-level cannabis legalization create divergent compliance obligations that laboratories must simultaneously satisfy, forcing investments in dual-track protocols and jurisdiction-specific reporting systems.
Growth Catalysts
- 49 CFR Part 40:The U.S. Department of Transportation's updated guidelines expand testing panels and lower cutoff thresholds for safety-sensitive positions, directly increasing certified laboratory workload volumes.
- Construction and transportation sectors:These injury-liability-exposed industries are implementing random drug testing programs beyond federal minimums to reduce workers compensation claims and litigation exposure.
- Oral fluid testing:This specimen type is gaining regulatory acceptance for federal workplace programs, offering collection efficiency advantages that reduce site visit costs for employers.
Market Restraints
- Reference standard costs:Certified reference materials for synthetic cannabinoids and novel psychoactive substances command premium pricing, compressing margins on expanded panels.
- Mass spectrometer supply concentration:Analytical instrument manufacturing concentrates among German and Japanese suppliers, creating procurement bottlenecks for laboratories scaling LC-MS/MS capacity.
- Cross-reactivity limitations:Immunoassay screening methods generate false positives for common medications including proton pump inhibitors and antidepressants, necessitating costly confirmatory testing.
Strategic Opportunities
- Rehabilitation center outsourcing:Value-based addiction treatment models are driving clinical laboratories to contract toxicology services rather than maintain in-house mass spectrometry capabilities.
- Hair testing for pre-employment:Employers in states with recreational cannabis access are adopting 90-day detection window protocols to identify chronic use patterns unaffected by temporary abstinence.
- ISO 15189 accreditation:International quality standards enable certified laboratories to access forensic and clinical markets across European and Asia-Pacific jurisdictions without redundant audits.
Industry Challenges
- Forensic toxicologist recruitment:The specialized combination of analytical chemistry training and chain-of-custody protocol expertise faces persistent supply constraints in regional labor markets.
- SAMHSA certification timelines:National Laboratory Certification Program inspections and proficiency testing requirements create 12-18 month delays for new laboratory market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Screening Laboratory Service Market |
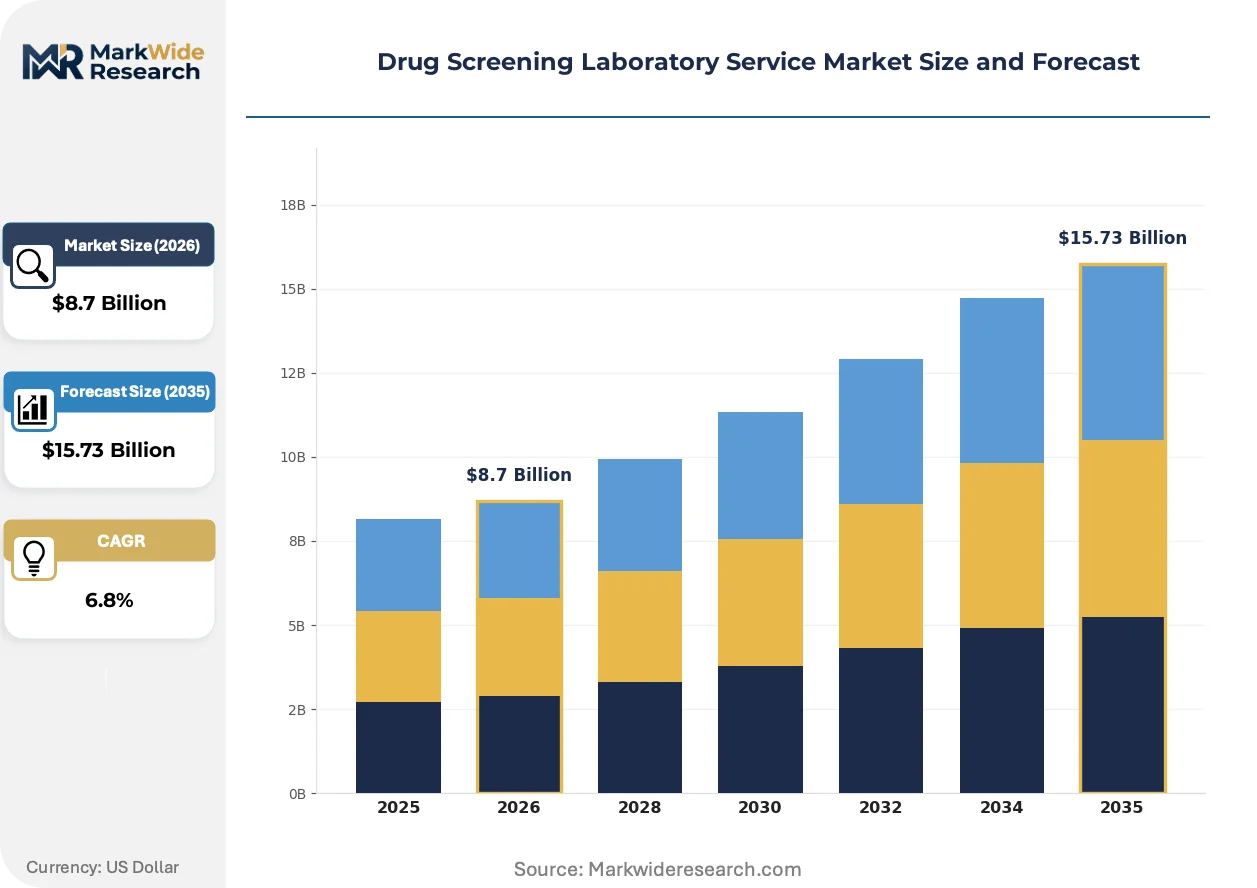
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Urine Testing, Hair Testing, Saliva Testing, Blood Testing Client Type: Corporate, Educational Institutions, Healthcare Providers, Government Agencies Testing Method: Immunoassay, Gas Chromatography, Liquid Chromatography, Mass Spectrometry Industry Application: Workplace Screening, Rehabilitation Centers, Sports Organizations, Criminal Justice |
| Companies Covered | Quest Diagnostics, LabCorp, Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche, Siemens Healthineers, OraSure Technologies, Bio-Rad Laboratories, Cordant Health Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Screening Laboratory Service Market Trends and Innovations
Specimen collection logistics and analytical detection capabilities are converging to reshape how employers verify workforce substance use, with automation and extended detection windows displacing traditional urine-based protocols.
Liquid chromatography-tandem mass spectrometry is integrating into high-throughput screening workflows as the definitive analytical platform for confirmatory testing. Mid-sized regional laboratories are adopting this technology to compete with national reference laboratories on panel breadth and turnaround time. The shift is integrating defensible quantitative results into employment decisions previously based on qualitative screening alone.
State employment law precedents on cannabis testing are fragmenting corporate screening policies across jurisdictions. Courts in California and New York have limited pre-employment marijuana testing for non-safety-sensitive positions. Employers operating across multiple states are responding with location-specific testing menus rather than uniform national programs.
Third-party administrator consolidation is compressing the buyer landscape for laboratory services. Large occupational health management platforms are aggregating employer demand and negotiating exclusive panel pricing with single-source laboratory partners. This concentration is most visible in the United States, where national logistics networks enable centralized specimen routing to high-volume testing hubs.
Drug Screening Laboratory Service Market Segmentation
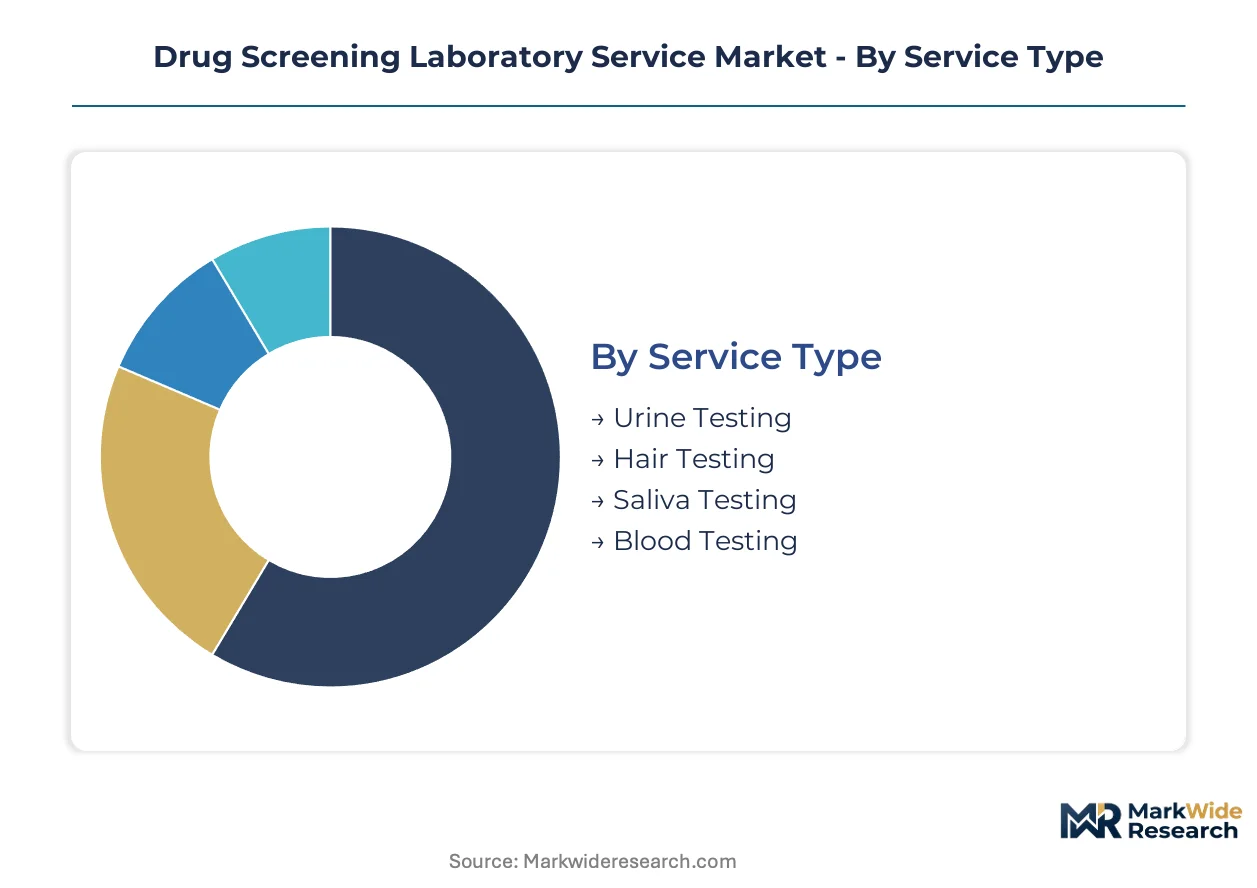
Specimen matrix and analytical platform selection directly determine laboratory throughput economics, regulatory compliance posture, and client retention rates across this fragmented service market. Segmentation reveals how federal certification requirements and employer liability preferences partition demand across distinct operational models.
Service Type:
Detection window length and collection invasiveness define the technology axis for specimen selection.
- Urine Testing:Enzymatic hydrolysis and immunoassay screening of creatinine-normalized samples dominate federal workplace compliance programs. United States transportation sector employers sustain volume concentration due to 49 CFR Part 40 mandates and established collection site infrastructure.
- Hair Testing:Keratin-incorporated metabolite detection via ELISA extraction and LC-MS/MS confirmation captures 90-day use histories. Post-legalization state employers in California and New York deploy this matrix to identify chronic patterns unaffected by temporary abstinence.
- Saliva Testing:Oral fluid collection offers point-of-care efficiency with recent-use detection windows.
- Blood Testing:Direct plasma quantification serves forensic and clinical overdose investigations.
Mature deployment sits with Urine Testing. Newer deployment is concentrated in Hair Testing.
Client Type:
Purchasing sophistication and compliance urgency separate institutional buyers across risk tolerance tiers.
- Corporate:Human resource departments and occupational health managers procure defensible testing for pre-employment screening and random monitoring. Construction and logistics firms in Texas and Florida sustain highest per-employer spend due to workers compensation liability exposure.
- Government Agencies:Federal and state procurement offices mandate SAMHSA-certified laboratory participation through competitive bidding vehicles.
- Healthcare Providers:Addiction medicine clinics and pain management practices require quantitative confirmation for treatment monitoring.
- Educational Institutions:University athletic departments and secondary school districts implement policy-driven screening with limited panel breadth.
Volume concentration resides with Corporate clients. Procurement complexity peaks with Government Agencies.
Testing Method:
Analytical specificity and capital intensity stratify laboratory competitive positioning.
- Immunoassay:Competitive binding assays on automated platforms deliver qualitative screening results within minutes. High-throughput reference laboratories deploy this method for initial negative reporting and cost containment in United States workplace programs.
- Liquid Chromatography:Reverse-phase separation enables quantitative metabolite identification for expanded synthetic panels.
- Mass Spectrometry:Tandem quadrupole detection provides definitive confirmation with forensic defensibility.
- Gas Chromatography:Volatile compound separation serves specialized alcohol and solvent detection.
Immunoassay anchors routine screening workflows. Mass Spectrometry commands confirmatory premium positioning.
Industry Application:
Legal admissibility standards and turnaround requirements fragment end-use specifications.
- Workplace Screening:Chain-of-custody protocols and Medical Review Officer oversight satisfy employment action defensibility. United States Department of Transportation safety-sensitive positions sustain highest certified laboratory utilization.
- Rehabilitation Centers:Value-based addiction treatment models drive toxicology outsourcing as clinical laboratories shed capital-intensive mass spectrometry assets.
- Criminal Justice:Probation monitoring and court-ordered testing require forensic-grade documentation.
- Sports Organizations:Anti-doping panels for collegiate and professional athletic leagues demand WADA-aligned substance detection.
Workplace Screening retains volume leadership. Rehabilitation Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical specimen collection networks anchor geographic demand concentration, with federal certification requirements and employer liability statutes creating distinct national market architectures.
United States
Department of Transportation safety-sensitive mandates and construction sector workers compensation exposure sustain the highest certified laboratory utilization worldwide. SAMHSA's National Laboratory Certification Program creates 12-18 month entry barriers that protect incumbent volume positions. Texas and Florida injury-liability markets concentrate random testing program procurement.
Germany
Industrial employers in chemical manufacturing and logistics sectors deploy pre-employment screening under Betriebsverfassungsgesetz works council frameworks. REACH compliance documentation requirements for hazardous substance exposure monitoring intersect with workplace testing protocols. Bavaria's automotive supplier clusters anchor regional toxicology service demand.
United Kingdom
Railway and Transport Safety Act mandates drive safety-critical sector compliance testing alongside financial services pre-employment screening. Health and Safety Executive guidelines on substance misuse management create employer duty-of-care obligations. London's occupational health provider networks consolidate specimen routing to accredited Midlands laboratories.
Australia
Mining sector fly-in-fly-out operations sustain remote collection site logistics demand under Coal Mining Safety and Health Act requirements. Fair Work Commission precedents on dismissal-for-cause testing create defensibility standards for resource employers. Western Australia's Pilbara region concentrates FIFO workforce screening volumes.
Canada
Canadian Model for Providing a Safe Workplace guidelines harmonize federal contractor testing standards across provincial jurisdictions. Cannabis legalization in 2018 fragmented employer policy responses between safety-sensitive and general workforce categories. Alberta's oil sands operations maintain rigorous substance monitoring protocols.
Drug Screening Laboratory Service Market Competitive Landscape
Global majors compete with regional champions across certification breadth and collection network density. The vendor base stratifies into three tiers: integrated reference laboratories with national logistics infrastructure, specialized toxicology operators focused on forensic defensibility, and analytical instrument suppliers extending into method-development services. Consolidation pressures concentrate among mid-sized regional players seeking SAMHSA certification scale. Strategic moves center on third-party administrator exclusivity contracts and ISO 15189 accreditation expansion.
Within the integrated reference laboratory tier, Quest Diagnostics and LabCorp exemplify volume-leadership archetypes through national collection site networks. Thermo Fisher Scientific occupies the analytical platform supplier position, extending instrument supply relationships into companion validation services for certified laboratories. These three anchors represent distinct competitive vectors: logistics scale, clinical-forensic workflow integration, and analytical technology enablement.
| Leading Market Players |
|---|
| Quest Diagnostics |
| LabCorp |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Siemens Healthineers |
| OraSure Technologies |
| Bio-Rad Laboratories |
| Cordant Health Solutions |
| Others |
Pricing and Supply Chain Analysis
Backward integration into specimen collection site networks anchors both supply position and pricing power for national reference laboratories competing against regional toxicology specialists. Captive logistics infrastructure insulates high-volume operators from third-party routing fees while enabling bundled service pricing that compresses margins for unintegrated competitors.
Pricing Analysis
Certified reporting bundled with Medical Review Officer oversight anchors premium pricing tiers, while unbundled analytical-only services compete on transactional per-test rates. SAMHSA certification grade and panel breadth drive price differentiation between federal-compliant and workplace-only laboratories. Cost compression in expanded synthetic cannabinoid panels is intensifying because certified reference materials command scarcity premiums. Corporate HR departments exhibit highest price sensitivity, whereas government procurement offices prioritize defensibility over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Florida, and California coordinate hub-and-spoke specimen routing from employer collection sites to high-throughput testing hubs. Analytical instrument manufacturing concentrates in Germany and Japan, while reference standard production centers on United States and European specialty chemical suppliers. Single-source vulnerability in tandem mass spectrometer procurement creates equipment delivery bottlenecks for laboratories scaling LC-MS/MS capacity. Distribution runs through third-party administrator networks that aggregate employer demand and negotiate exclusive panel pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over collection site networks to defend margin positions against aggregator intermediaries.
For Market Incumbents: Cement SAMHSA certification scale through proficiency testing investment and expand oral fluid testing capabilities before regulatory acceptance finalizes. Third-party administrator consolidation threatens direct employer relationships, making channel control through exclusive logistics partnerships essential for volume retention. For New Entrants and Emerging Players: Capture rehabilitation center outsourcing contracts as value-based addiction treatment models proliferate and clinical laboratories shed capital-intensive mass spectrometry assets. Rehabilitation centers represent the most penetrable segment, with ISO 15189 accreditation serving as the critical go-to-market credential for forensic-defensible positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated reference laboratories seeking regional toxicology capabilities. Mid-sized SAMHSA-certified operators with established government contracts offer viable five-to-ten-year holds. State employment law precedents on cannabis testing serve as the primary inflection signal for structural demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SAMHSA Certification Investment | Federal workplace compliance access under 49 CFR Part 40 mandates sustains high-volume utilization. |
| Oral Fluid Testing Capability Expansion | Regulatory acceptance for DOT programs reduces employer site visit costs and accelerates turnaround. |
| ISO 15189 Accreditation Expansion | International quality standards enable forensic and clinical market access without redundant audits. |
| Third-Party Administrator Exclusivity | Aggregator consolidation compresses buyer landscape and locks in volume commitments. |
| Hair Testing Method Development | Ninety-day detection windows attract post-legalization state employers seeking chronic use identification. |
Research Methodology
Trade association filings, SAMHSA laboratory certification records, and Department of Transportation regulatory guidance formed the secondary backbone of this analysis. Primary interviews with laboratory operations directors, toxicology service procurement managers at Fortune 500 employers, Medical Review Officers, and rehabilitation center clinical directors validated demand assumptions. Bottom-up laboratory capacity modeling and top-down employer testing program expenditure analysis enabled triangulation across independent estimation approaches.
Historical certified laboratory workload trends and employer testing policy adoption curves informed projection framework construction across the analysis window. Segmentation modeling incorporated specimen matrix type, analytical platform, client purchasing sophistication, and federal versus non-federal compliance tier. CAGRs derived from volume trajectory analysis and pricing elasticity assumptions. Forecast inputs included state cannabis legalization progression and DOT panel expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state employment law precedents on cannabis testing and synthetic cannabinoid regulatory scheduling. Outputs reflect documented assumptions regarding federal mandate continuity and reference standard supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Adiponectin Testing Market
Testing Services
Allergy Tester Market
Testing Services
Adenovirus Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Global Coagulation Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Blood Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Global Virology Testing Market
Testing Services
Tuberculosis Testing Market