
 Counter-UAS Market | 2026-2036
Counter-UAS Market Size, Share, and Industry Trends Forecast 2026-2036
Counter-UAS Market Analysis
Gallium nitride is expanding its footprint in radio-frequency amplification stages, displacing legacy gallium arsenide substrates in high-power jamming and detection arrays. RTX leverages captive semiconductor foundries to secure GaN supply chains for phased-array radars. Lockheed Martin anchors long-range kinetic interception programs with directed-energy adjuncts. Israel Aerospace Industries specializes in compact, vehicle-mounted systems tailored for maneuver force protection.
Counter-UAS systems encompass layered detection, tracking, identification, and neutralization architectures designed to defeat unmanned aerial vehicles across Group 1 through Group 3 classifications, typically employing RF spectrum analyzers operating across 400 MHz to 6 GHz alongside electro-optical/infrared sensors with sub-milliradian tracking precision. Detection Systems occupy the largest installed base as perimeter security mandates multiply across airports and energy facilities, while Cyber Solutions represent the fastest-expanding margin pool as non-kinetic defeat protocols gain legal preference in civilian airspace. Kinetic Systems retain dominant share in military theaters where rules of engagement permit hard-kill responses.
The U.S. FAA coordinates with DHS and DoD on counter-drone test ranges under Section 2206 of the FAA Extension Act, while EU member states implement the European Drone Regulation framework through EASA-designated national authorities. The U.S. SEC and CFIUS review foreign investment in RF semiconductor firms, constraining technology transfer pathways. Stakeholders must monitor evolving legal frameworks governing civilian airspace interdiction authority and electromagnetic spectrum licensing to align product roadmaps with operable jurisdictions.
Market Dynamics
Gallium nitride substrate shortages are compressing RF component lead times and forcing defense primes to requalify alternative semiconductor architectures for phased-array implementations.
Growth Catalysts
- Layered Defense Mandates:U.S. Department of Defense procurement directives require integrated detection-interdiction stacks for forward operating bases, accelerating multi-sensor fusion deployments.
- Remote ID Compliance:The FAA's Remote ID mandate for commercial drones creates standardized electronic signatures that RF spectrum analyzers exploit for rapid threat classification.
- Energy Infrastructure Hardening:Saudi Aramco and UAE ADNOC facilities are deploying perimeter counter-drone systems following attacks on Abqaiq processing complexes.
Market Restraints
- GaN Wafer Bottlenecks:Six-inch gallium nitride substrate production concentrates at Wolfspeed and Coherent facilities, creating single-source vulnerability for high-power amplifier arrays.
- Civilian Airspace Interdiction Limits:FCC electromagnetic spectrum licensing restricts jamming power outputs in U.S. urban corridors below thresholds effective against encrypted datalinks.
- Kinetic Collateral Risk:Falling drone debris and errant projectiles limit hard-kill authorization near airports, stadiums, and dense population centers.
Strategic Opportunities
- Cyber-Defeat Protocols:Protocol injection and GPS spoofing techniques bypass physical interdiction limits where FCC jamming restrictions apply.
- Vehicle-Mounted Mobility:Light armored vehicle integration for maneuver force protection remains underpenetrated outside Israeli and U.S. expeditionary units.
- EU Drone Regulation Tailwinds:EASA's European Drone Regulation framework mandates detect-and-avoid capabilities for certified operations, creating retrofit demand for commercial fleet operators.
Industry Challenges
- RF Engineer Scarcity:Phased-array radar and microwave circuit design talent pools concentrate at legacy defense primes, constraining startup scaling.
- Cross-Domain Integration Complexity:Merging electro-optical, radar, and cyber-defeat streams into unified fire-control loops demands systems engineering capabilities rare outside tier-one contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Counter-UAS Market |
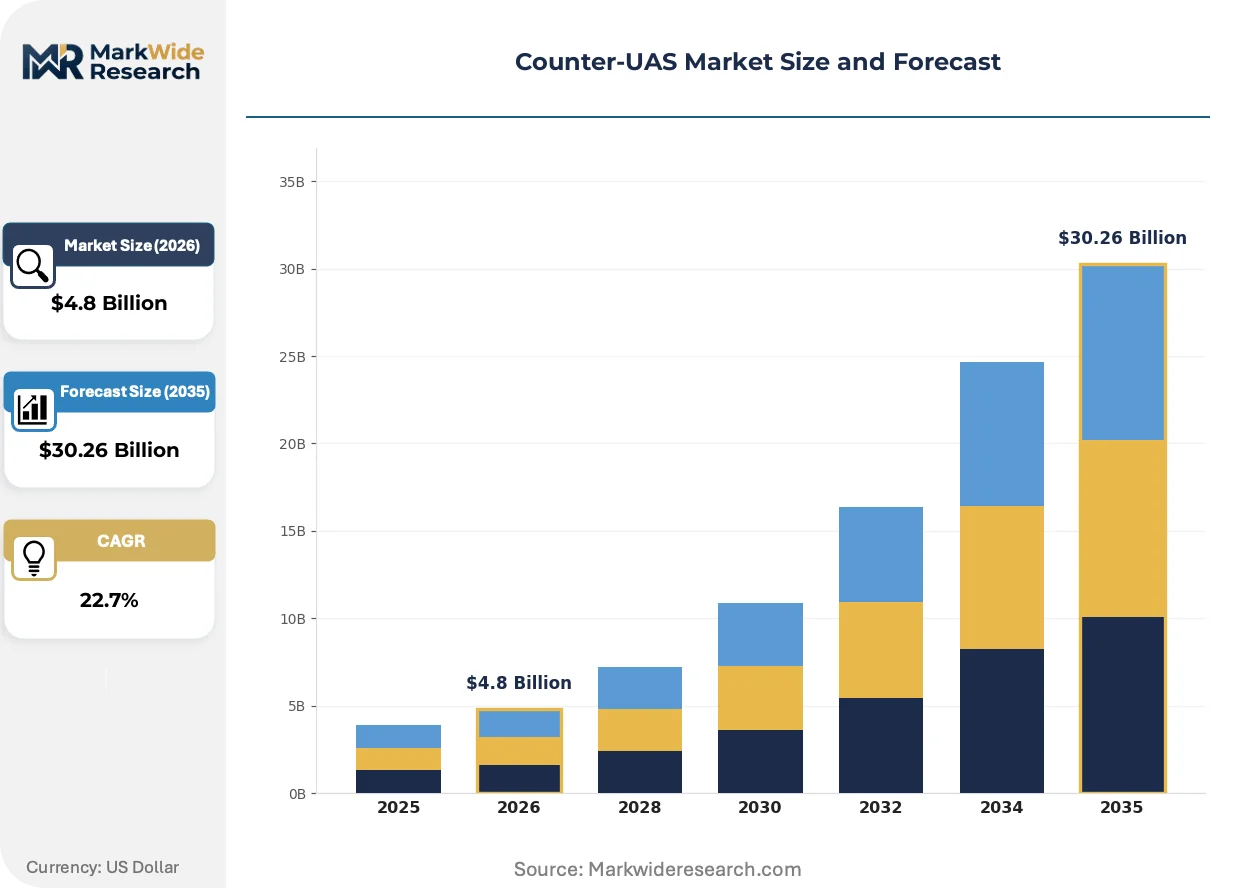
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Detection Systems, Jamming Systems, Kinetic Systems, Cyber Solutions End User: Defense Entities, Critical Infrastructure, Law Enforcement, Commercial Operators Deployment: Onsite, Remote, Mobile, Fixed Installation Technology: Radio Frequency, Electro-Optical, Infrared, Laser Systems |
| Companies Covered | RTX, Lockheed Martin Corporation, Northrop Grumman, Thales Group, BAE Systems, Israel Aerospace Industries, RAFAEL Advanced Defense Systems, Elbit Systems, Saab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Counter-UAS Market Emerging Trajectories
Artificial intelligence inference at the sensor edge is collapsing detection-to-engagement timelines and enabling autonomous neutralization decisions without human-in-the-loop authorization delays.
Software-defined radio architectures are unifying previously discrete jamming, detection, and communications functions into reprogrammable hardware platforms. U.S. Army maneuver units are fielding these systems at brigade scale for expeditionary counter-drone coverage. This consolidation is compressing vendor count in the RF subsystem tier as multi-function platforms displace single-purpose boxes.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on autonomous targeting algorithms deployed in civilian-accessible airspace. Manufacturers must now document decision audit trails for kinetic interdiction systems sold to European law enforcement agencies. Israeli and U.S. exporters are establishing Brussels-based regulatory affairs functions to navigate EASA-EU AI Act overlap.
Defense procurement officers are consolidating vendor relationships around full-spectrum service contracts that bundle hardware, software updates, and threat library subscriptions. Systems integrators are absorbing previously independent detection and defeat specialists to offer single-point accountability. This concentration is most visible in U.S. SOCOM and UK Strategic Command acquisition streams where operational readiness metrics override unit cost minimization.
Counter-UAS Market Segmentation
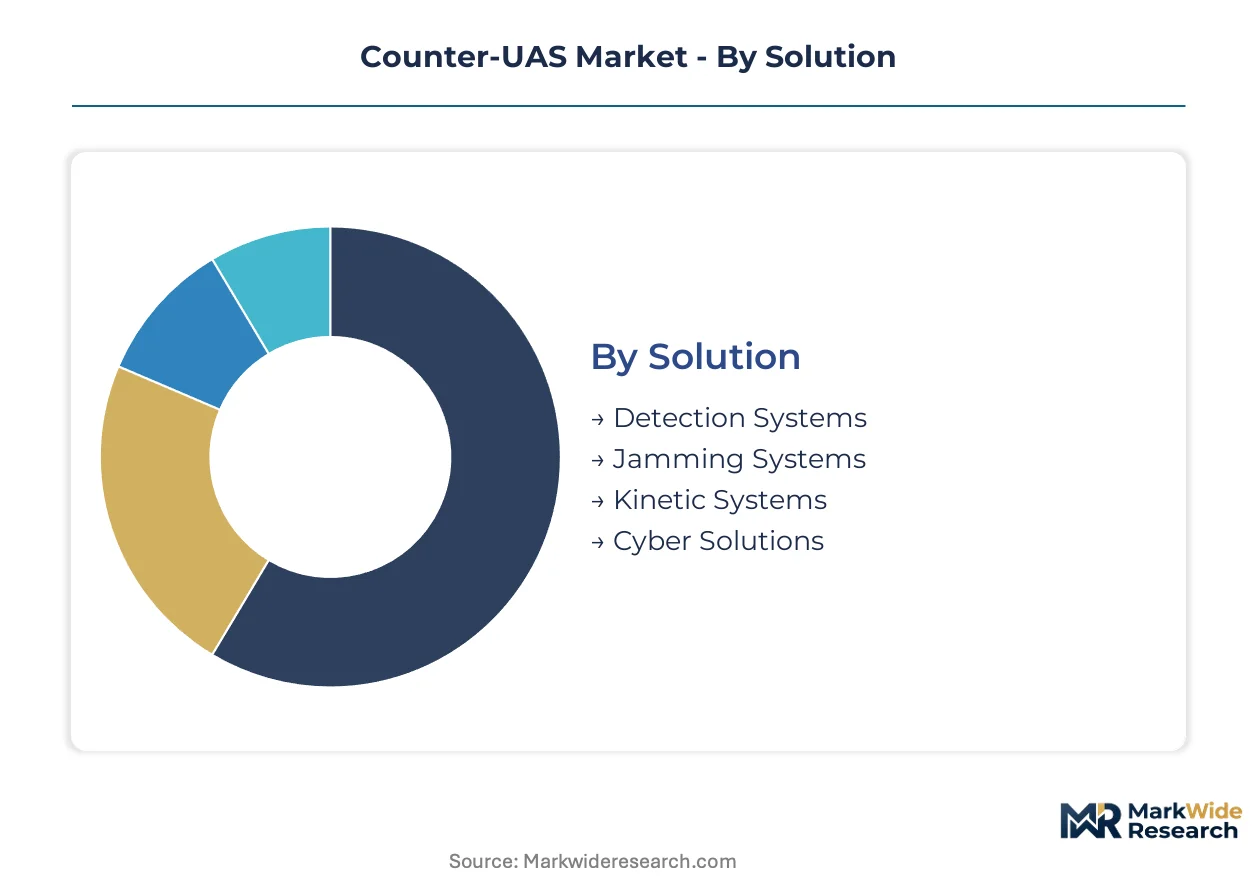
Counter-UAS procurement decisions split across operational requirements, regulatory constraints, and infrastructure maturity. Buyers evaluate detection range against interference rules, mobility against power budgets, and kinetic authorization against liability exposure. Segmentation reveals where defense primes concentrate versus where specialized vendors retain edge.
Solution:
FAA Remote ID mandates and FCC electromagnetic licensing create divergent certification burdens across solution types, with civilian-airspace systems facing stricter conformity assessment than military-only configurations.
- Detection Systems:Multi-sensor fusion architectures combining RF spectrum analyzers with electro-optical/infrared trackers dominate perimeter security at U.S. airports and Saudi Aramco facilities. Demand concentrates where early warning timelines outweigh neutralization authority constraints.
- Jamming Systems:High-power gallium nitride amplifier arrays face FCC output restrictions in urban corridors, limiting effective range against encrypted datalinks. Military procurement bypasses these limits through DoD spectrum allocations.
- Kinetic Systems:Hard-kill interceptors require rules-of-engagement authorization rarely granted near civilian infrastructure.
- Cyber Solutions:Protocol injection and GPS spoofing techniques circumvent jamming restrictions where FCC limits apply.
Leading the category by volume: Detection Systems. Growing fastest: Cyber Solutions.
End User:
Procurement scale and contracting velocity vary sharply across buyer types, with defense entities locking in multi-year programs while commercial operators favor subscription threat-intelligence models.
- Defense Entities:U.S. SOCOM and UK Strategic Command drive integrated detection-interdiction stacks through full-spectrum service contracts bundling hardware, software, and threat library subscriptions.
- Critical Infrastructure:Energy operators in Saudi Arabia and the UAE deploy perimeter hardening following Abqaiq-style attacks, prioritizing detection-to-response timelines over neutralization method.
- Law Enforcement:European agencies navigate EU AI Act conformity assessment for autonomous targeting algorithms, forcing documentation of decision audit trails.
- Commercial Operators:EASA-certified drone fleets retrofit detect-and-avoid capabilities under European Drone Regulation mandates, creating retrofit demand concentrated in Germany and France.
Highest procurement velocity: Defense Entities. Steepest regulatory headwind: Law Enforcement.
Deployment:
Power infrastructure availability and spectrum licensing jurisdiction determine feasible deployment modes, with mobile systems requiring vehicle-integrated power and fixed installations leveraging grid-connected amplifier arrays.
- Onsite:Temporary event security at stadiums and political summits favors rapid-deploy kits with battery-limited endurance.
- Remote:Centralized monitoring hubs serve distributed critical infrastructure with networked sensor feeds and delegated neutralization authority.
- Mobile:Light armored vehicle integration for maneuver force protection remains underpenetrated outside Israeli and U.S. expeditionary brigades, with RTX and Lockheed Martin anchoring platform development.
- Fixed Installation:Airport perimeter systems in the United States and United Kingdom anchor the installed base, with multi-year amortization against operational continuity requirements.
Dominant by installed base: Fixed Installation. Most constrained by supply chain: Mobile.
Technology:
Component sourcing concentration and engineer scarcity shape technology selection, with RF subsystem vendors consolidating around software-defined radio platforms while electro-optical specialists retain independent positioning.
- Radio Frequency:Phased-array radars and spectrum analyzers operating across 400 MHz to 6 GHz form the detection backbone, with GaN substrate shortages compressing lead times at Wolfspeed-dependent suppliers.
- Electro-Optical:Sub-milliradian tracking precision enables visual confirmation and collateral damage assessment where kinetic interdiction is authorized.
- Infrared:Thermal signature tracking maintains detection continuity in low-visibility conditions, complementing RF methods against stealth-coated platforms.
- Laser Systems:Directed-energy adjuncts to kinetic interceptors face power scaling challenges and atmospheric attenuation limits, retaining niche status in long-range naval applications.
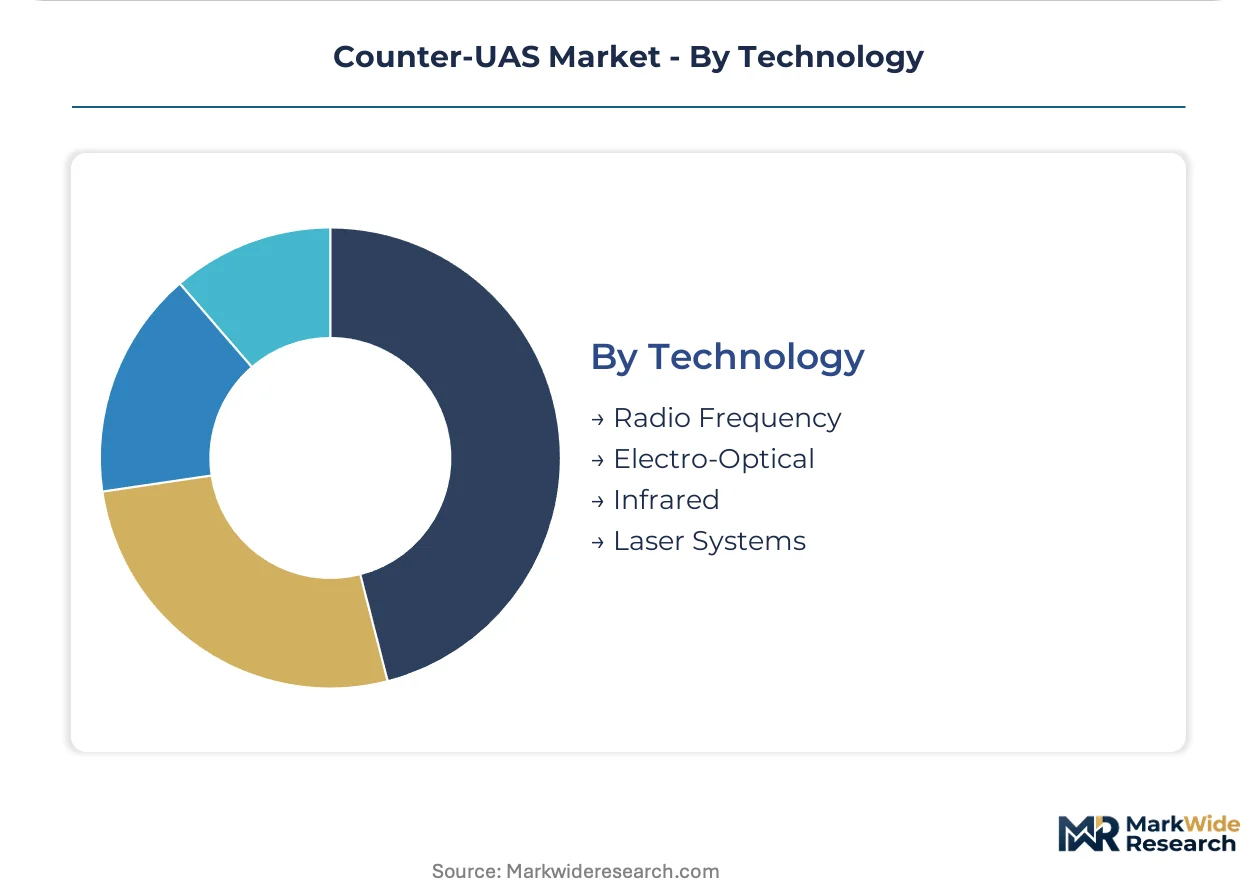
Widest supplier base: Electro-Optical. Tightest component constraint: Radio Frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in the United States, Israel, and the United Kingdom, where layered detection-interdiction systems anchor national security infrastructure. Energy operators in Saudi Arabia and the UAE accelerate perimeter hardening investments following attacks on critical processing facilities. Regulatory divergence across FAA, EASA, and national defense authorities fragments certification pathways for civilian-airspace deployments.
United States
The Department of Defense drives integrated detection-interdiction stacks through full-spectrum service contracts bundling hardware, software, and threat library subscriptions. FAA Section 2206 coordinates counter-drone test ranges with DHS and DoD, establishing standardized evaluation protocols. RTX and Lockheed Martin anchor development clusters in Arizona and Texas, leveraging captive semiconductor foundries for phased-array radar production.
Israel
Vehicle-mounted systems for maneuver force protection dominate procurement, with compact architectures tailored to expeditionary brigade requirements. The national defense establishment maintains classified rules of engagement for hard-kill authorization in contested airspace. Israel Aerospace Industries and RAFAEL Advanced Defense Systems concentrate engineering talent in Tel Aviv and Haifa, specializing in RF spectrum analyzers and cyber-defeat protocols.
United Kingdom
UK Strategic Command acquisition streams prioritize operational readiness metrics over unit cost minimization, consolidating vendor relationships around single-point accountability. The Civil Aviation Authority implements EASA-aligned detect-and-avoid mandates for commercial drone fleets, creating retrofit demand. BAE Systems anchors development in Lancashire and Hampshire, integrating electro-optical tracking with military-grade jamming arrays.
Saudi Arabia
Saudi Aramco facilities deploy perimeter counter-drone systems following Abqaiq-style attacks, prioritizing detection-to-response timelines over neutralization method. The national oil company mandates multi-sensor fusion architectures across processing complexes and export terminals. Engineering procurement concentrates in Dhahran and Jubail, with systems integration contracts awarded to international defense primes under localized partnership requirements.
Germany
EASA's European Drone Regulation framework drives detect-and-avoid retrofit demand among certified commercial operators, particularly in cargo and inspection services. The Federal Office for Information Security evaluates cyber-defeat protocols for civilian airspace deployment under EU AI Act conformity assessment. Industrial clusters in Bavaria and Baden-Württemberg host RF subsystem vendors consolidating around software-defined radio platforms.
Counter-UAS Market Vendor Landscape
Systems integration dominates the current landscape as tier-one contractors absorb previously independent detection and defeat specialists to offer single-point accountability. The vendor base concentrates around defense primes with captive semiconductor supply chains and specialized technology firms with RF engineering depth. Three archetypes define competitive positioning: full-spectrum integrators bundling hardware and subscription services, RF subsystem specialists leveraging GaN amplifier expertise, and cyber-defeat vendors exploiting protocol injection capabilities. M&A consolidation and strategic partnerships represent the dominant competitive moves, compressing vendor count in the RF subsystem tier.
Within the full-spectrum integrator tier, RTX and Lockheed Martin exemplify scale-driven consolidation around layered defense mandates. Israel Aerospace Industries occupies a position within the mobility-specialist archetype, representing compact vehicle-mounted system development. These three anchors reflect the market's bifurcation between semiconductor-integrated primes and maneuver-force protection specialists.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin Corporation |
| Northrop Grumman |
| Thales Group |
| BAE Systems |
| Israel Aerospace Industries |
| RAFAEL Advanced Defense Systems |
| Elbit Systems |
| Saab |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's conformity assessment mandate for autonomous targeting algorithms gates qualified supply for European law enforcement procurement, restricting premium-tier pricing access to vendors with documented decision audit trails and Brussels-based regulatory affairs functions.
Pricing Analysis
Volume concentrates in fixed-installation detection systems at airports and energy facilities, while margins expand fastest in cyber-defeat subscriptions bundling protocol injection capabilities with threat intelligence updates. Three-tier pricing structure across military-grade, dual-use certified, and commercial-limited configurations differentiates on FCC spectrum licensing and kinetic authorization thresholds. Pricing pressure stems from GaN substrate shortages compressing RF component lead times and forcing requalification costs onto buyers. Defense entities show lowest price sensitivity under full-spectrum service contracts, while commercial operators in EASA-certified fleets prioritize per-unit acquisition cost over after-sales subscription bundles.
Supply Chain Analysis
Saudi Aramco's localized partnership requirements and U.S. CFIUS reviews of foreign investment in RF semiconductor firms are reshaping sourcing geography for defense primes seeking compliant component flows. Six-inch gallium nitride substrate production concentrates at Wolfspeed and Coherent facilities in the United States, with epitaxial wafer processing anchored in Japan and Germany. High-power amplifier arrays, electro-optical sensors, and software-defined radio chipsets constitute critical input dependencies. Single-source vulnerability at Wolfspeed-dependent suppliers creates structural risk for phased-array radar production timelines. Distribution runs through systems integrators absorbing previously independent detection and defeat specialists to offer single-point accountability under multi-year service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Counter-UAS market is becoming a vertical-integration race where captive semiconductor foundries and in-house GaN supply chains determine pricing power and delivery reliability against substrate-constrained competitors.
For Market Incumbents: Anchor long-term contracting relationships around full-spectrum service bundles that hardware-lock customers through threat library subscriptions and firmware update dependencies. Absorb RF subsystem specialists to close the engineer scarcity gap in phased-array design, while securing alternative semiconductor architectures to mitigate Wolfspeed single-source exposure. Cyber-defeat protocol vendors represent the most vulnerable specialist tier to consolidation. For New Entrants and Emerging Players: Enter via vehicle-mounted mobility segments for maneuver force protection, where Israeli and U.S. expeditionary brigades remain the only penetrated buyers and light armored vehicle integration contracts sit undercontested. Target European commercial drone fleet operators facing EASA detect-and-avoid retrofit mandates, offering software-only cyber-defeat solutions that bypass GaN hardware constraints and FCC jamming restrictions. Position as regulatory-native vendors with pre-built EU AI Act documentation. For Investors and Strategic Acquirers: Lockheed Martin's directed-energy adjunct program acceleration is the leading indicator that long-range kinetic interception is shifting toward energy-weapon hybrids, signaling obsolescence risk for pure projectile-based hard-kill vendors. Acquirers should target RF subsystem specialists with GaN amplifier expertise and existing DoD spectrum allocations, avoiding cyber-defeat pure-plays facing protocol-hardening countermeasures. Watch for FAA Remote ID mandate enforcement intensity as the inflection signal for civilian-airspace cyber-defeat demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Foundry Investment | RTX's vertical control over phased-array radar supply secures allocation priority during Wolfspeed substrate shortages. |
| Cyber-Defeat Protocol Acquisition | Systems integrators absorb protocol injection specialists to bundle non-kinetic defeat under single-point accountability contracts. |
| EU Regulatory Affairs Localization | Israeli and U.S. exporters establish Brussels functions to navigate EASA-EU AI Act overlap for law enforcement sales. |
| Vehicle-Mounted Platform Integration | Light armored vehicle counter-drone contracts at brigade scale compress vendor count around RTX and Lockheed Martin development clusters. |
| Threat Intelligence Subscription Bundling | Defense procurement officers consolidate vendor relationships around operational readiness metrics overriding unit cost minimization. |
Methodological Framework
Independent corroboration across defense procurement officers at U.S. SOCOM and UK Strategic Command, RF subsystem engineering leads at tier-one contractors, and regulatory affairs directors navigating FAA-EASA overlap underwrites the qualitative findings in this study. Primary interviews with phased-array radar designers, electro-optical tracking specialists, and cyber-defeat protocol engineers combined with secondary validation from SEC filings of defense primes, FAA Section 2206 test range documentation, and EASA European Drone Regulation implementation notices. Bottom-up segment sizing across detection, jamming, kinetic, and cyber solution types triangulated against top-down defense budget allocation analysis.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by solution type, end-user procurement velocity, deployment mode infrastructure requirements, and technology component constraints. Modeled dimensions include military versus civilian airspace regulatory clusters, fixed versus mobile power infrastructure availability, and GaN-dependent versus GaN-alternative RF architectures. CAGRs derive from procurement pipeline visibility at forward operating base programs, energy facility perimeter hardening mandates, and commercial fleet retrofit compliance deadlines. Industry-specific inputs incorporate classified rules-of-engagement evolution for hard-kill authorization and FCC electromagnetic spectrum licensing enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion via CFIUS or sudden GaN substrate supply disruption. Forecasts reflect documented assumptions regarding FAA Remote ID compliance timelines, EASA detect-and-avoid mandate enforcement, and DoD layered defense procurement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Small UAV Market
UAV
UAV Simulator Market
UAV
Drone Inspection Service Market
UAV
Global Drone Autopilots Market
UAV
Solar Powered Drones Market
UAV
North America Drones Market
UAV
Aerial Smart Weapons Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Drones Market
UAV
Drone Camera Market
UAV
Solar-Powered UAV Market
UAV
Tactical UAV Market
UAV
Delivery Drones Market
UAV
Industrial Drones Market
UAV
UAV Lidar Market