
 Home Security Drone Market | 2026-2036
Home Security Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Home Security Drone Market Foresight
Aftermarket service revenue is reconfiguring margin capture across the home security drone value chain. Skydio leverages proprietary autonomous navigation stacks to sustain premium positioning in law enforcement channels. Ring LLC anchors consumer mindshare through tight integration with existing smart-home ecosystems. Parrot competes on open-architecture software that appeals to European system integrators seeking customization.
Home security drones are unmanned aerial systems purpose-built for residential and commercial property monitoring, typically incorporating infrared sensors, GPS-based navigation, and real-time video streaming with flight endurance between twenty and forty minutes per sortie. Their primary commercial purpose centers on autonomous perimeter patrol, intrusion detection, and situational awareness relay for security operations centers. Outdoor drones dominate current shipment volumes due to broader use cases in estate and facility protection, while AI-based analytics represents the fastest-expanding technology layer as computer vision enables threat classification without human-in-the-loop review. Residential users still occupy the largest end-user segment by unit count, though commercial properties command substantially higher average selling prices per deployment.
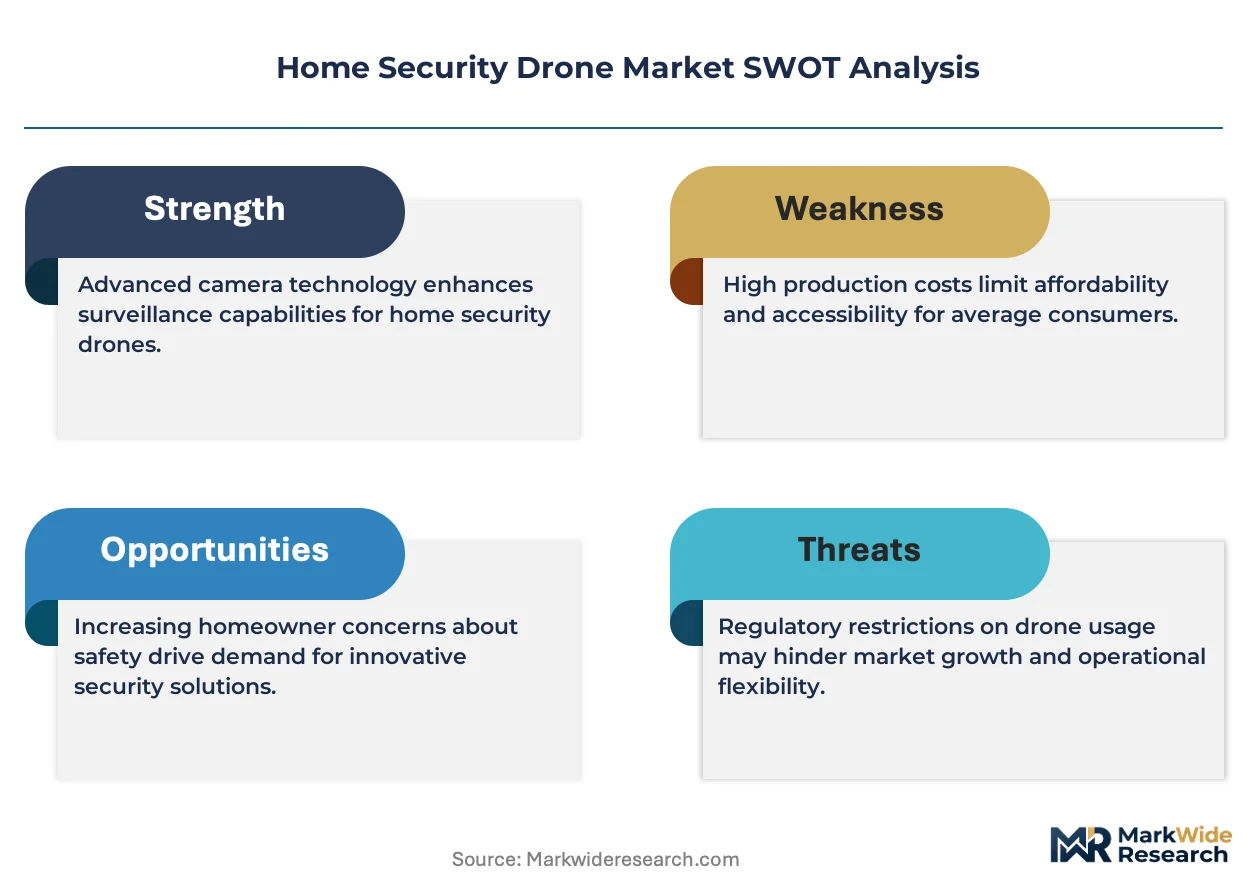
The FAA governs commercial drone operations in the United States through Part 107 and emerging beyond-visual-line-of-sight rulemakings that directly dictate where security drones can legally patrol. EASA's CE marking requirements under the EU Drone Regulation and specific category operational authorizations shape product certification burdens for manufacturers serving European buyers. Australia's Civil Aviation Safety Authority enforces standard operating conditions that limit altitude and proximity to populated areas, constraining urban deployment architectures. Stakeholders must monitor regulatory divergence on autonomous flight permissions as this determines which technology investments will unlock addressable demand in each jurisdiction.
Market Dynamics
Autonomous navigation software stacks are compressing the operational labor cost structure for perimeter security operations, while FAA beyond-visual-line-of-sight waivers are unlocking contiguous estate coverage that manual piloting cannot economically serve.
Growth Catalysts
- Part 107 waiver expansion:FAA regulatory accommodations for extended-range operations enable single-operator control of multi-drone fleets across sprawling residential developments in Florida and Texas.
- AI-based threat classification:Computer vision algorithms trained on intrusion pattern datasets now execute real-time anomaly flagging without human-in-the-loop verification, compressing response latency.
- Gated community procurement concentration:Homeowners associations in suburban United States markets are consolidating vendor contracts for autonomous patrol services, creating anchor demand for fleet deployments.
Market Restraints
- Lithium-polymer battery cost volatility:Cell-grade cathode material pricing fluctuations directly compress hardware margins for flight systems with 20-40 minute endurance requirements.
- Sensor module supply concentration:Infrared imaging component fabrication concentrates in East Asian foundries, exposing integrators to single-source risk for thermal detection capabilities.
- EASA operational authorization friction:CE marking under EU Drone Regulation mandates extensive conformity assessment for autonomous flight systems, extending European market entry timelines.
Strategic Opportunities
- Suburban Australian developments:CASA standard operating conditions accommodate altitude-capped autonomous patrol architectures across low-density residential corridors in Queensland and Western Australia.
- Smart-home ecosystem integration:API-level interoperability with existing alarm and access control systems creates stickier vendor relationships in the residential segment.
- 5G network slicing for command-and-control:Ultra-reliable low-latency communication channels enable real-time video relay without proprietary radio infrastructure investment.
Industry Challenges
- Autonomous systems engineering talent scarcity:Flight control algorithm development and sensor fusion expertise command premium compensation, constraining vendor scaling velocity.
- Legacy security infrastructure interoperability:Physical security information management platforms deployed in commercial estates require custom middleware development for drone telemetry ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Security Drone Market |
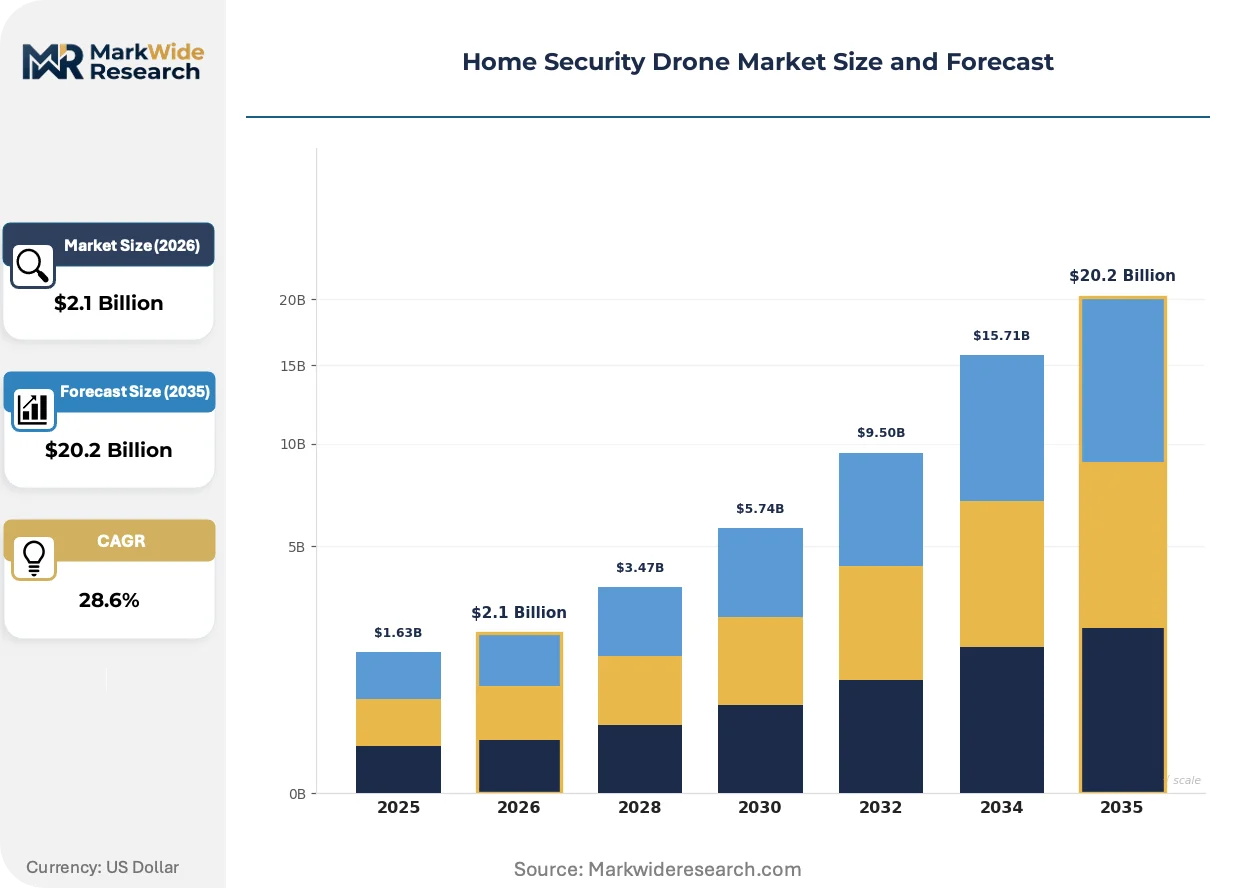
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $20.2 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Drones, Outdoor Drones, Surveillance Drones, Tactical Drones Technology: GPS-based Navigation, Infrared Sensors, Real-time Video Streaming, AI-based Analytics End User: Residential Users, Commercial Properties, Government Facilities, Law Enforcement Delivery Mode: Online Sales, Retail Stores, Distributors, B2B Sales |
| Companies Covered | Parrot, Azur Drones, Sunflower Labs Inc., Draganfly, Percepto, Ring LLC, Autel Robotics, Sony, Skydio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Security Drone Market Shifts & Advancements
Edge-based processing architectures are displacing cloud-dependent analytics, while regulatory frameworks for autonomous flight mature across multiple jurisdictions. These shifts compress latency and expand addressable patrol geometries.
Swarming coordination protocols are migrating from research demonstrations to production security deployments. Large estate operators in the United Arab Emirates now pilot multi-drone perimeter coverage with single-operator oversight. This migration from manual piloting to autonomous fleet management compresses labor cost per acre monitored and enables continuous patrol cycles impossible under human endurance constraints.
EASA's specific category operational authorization pathway under EU Drone Regulation is forcing manufacturers to restructure type certification documentation for European market access. Hardware vendors serving French and German system integrators now embed redundant navigation sensors and geofencing logic at the firmware layer. Commercial property deployments in European metropolitan peripheries face extended procurement cycles as buyers await regulatory clarity on autonomous flight permissions.
Buyers in residential gated communities are unbundling hardware acquisition from recurring patrol service subscriptions. Homeowners associations in Texas and Florida now favor operational expenditure models where drone fleet ownership remains with the security service provider. This consumption pattern shift concentrates vendor working capital requirements and rewards established operators with balance sheet capacity for fleet depreciation.
Home Security Drone Market Segmentation
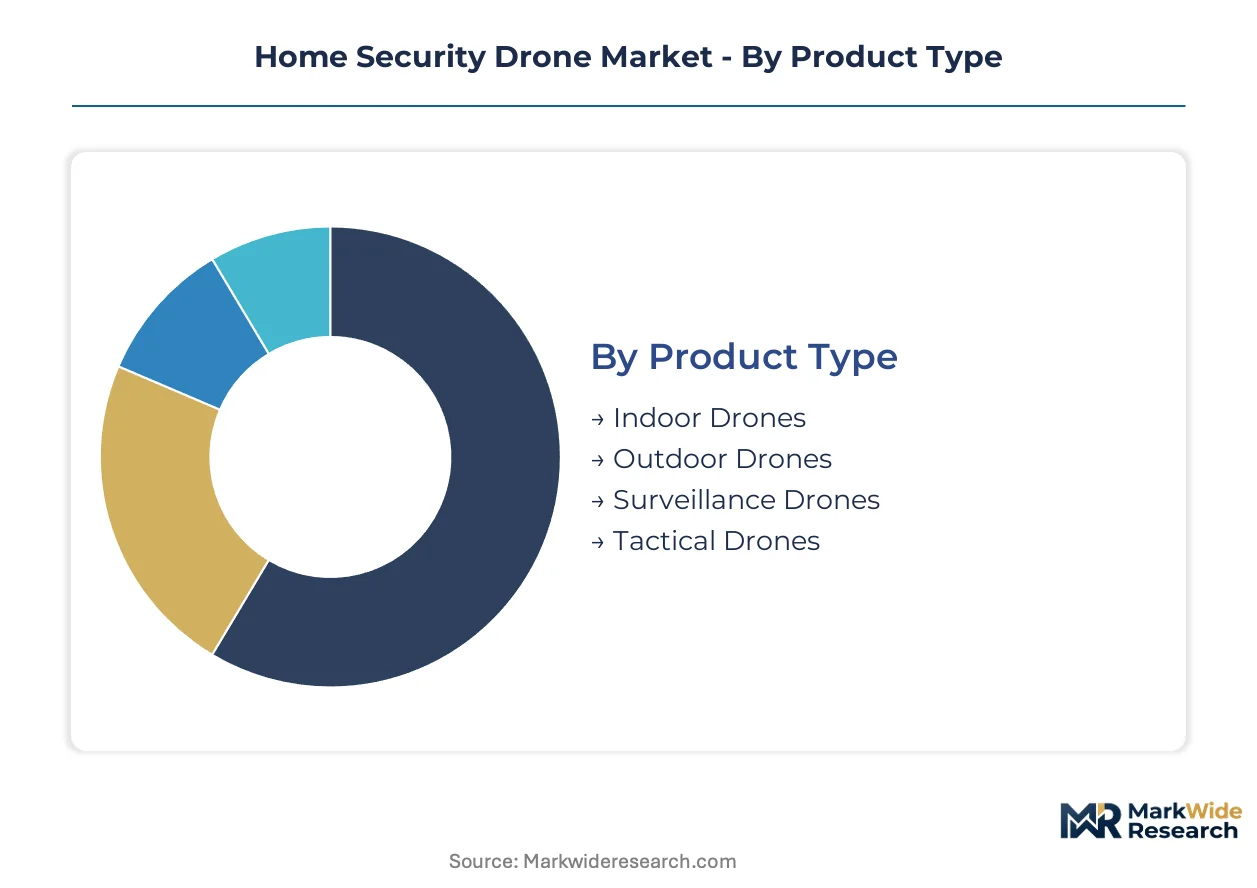
Segmentation in the home security drone market reveals divergent procurement cycles and technology refresh rates across product architectures. Understanding these temporal patterns enables vendors to align inventory planning with segment-specific replacement cadences and service contract durations.
Product Type:
Outdoor drones turn over fastest due to environmental exposure and battery degradation, while tactical systems endure longest through modular upgrade paths.
- Outdoor Drones:Weather-sealed airframes with IP-rated enclosures withstand rain, dust, and temperature cycling across Florida and Texas gated communities. Residential estate operators in suburban United States markets favor these units for perimeter patrol, driving fleet refresh every 18-24 months due to rotor wear and sensor calibration drift.
- Surveillance Drones:Purpose-built platforms integrate stabilized gimbals and optical zoom modules for continuous monitoring operations. Demand concentrates in commercial property portfolios across the United Arab Emirates, where estate operators prioritize persistent aerial coverage over rapid maneuverability.
- Indoor Drones:Compact form factors with obstacle-avoidance arrays navigate confined residential interiors and warehouse environments.
- Tactical Drones:Ruggedized builds with encrypted command links serve law enforcement rapid-response units requiring hardened communications.
Outdoor drones dominate installed base. Surveillance drones are where expansion concentrates.
Technology:
Cost tiering separates commoditized positioning systems from premium AI layers commanding recurring software revenue.
- AI-based Analytics:Edge-deployed computer vision models execute real-time threat classification without cloud latency, enabling sub-second anomaly flagging. Commercial deployments in Australian suburban corridors under CASA altitude caps increasingly specify onboard inference chips to minimize transmission bandwidth.
- Infrared Sensors:Thermal imaging modules detect heat signatures through darkness and foliage, extending effective patrol hours beyond daylight constraints. Texas homeowners associations specify these for nighttime perimeter coverage where visible-light cameras fail.
- GPS-based Navigation:Standard positioning stacks enable waypoint programming and return-to-home failsafes across entry-level product tiers.
- Real-time Video Streaming:Low-latency transmission protocols relay footage to security operations centers for human verification.
GPS-based Navigation saturates unit volume. AI-based Analytics is climbing the fastest.
End User:
Customer type dictates procurement sophistication, from residential subscription models to government compliance mandates.
- Residential Users:Homeowners associations and individual estate owners acquire patrol services through operational expenditure contracts rather than capital purchases. Florida gated communities now standardize drone coverage in association fee structures, creating predictable recurring revenue streams for service providers.
- Commercial Properties:Corporate campuses and industrial facilities command higher per-deployment values through integration with access control and video management systems. Australian mining estate operators in Queensland specify autonomous patrol for vast perimeter distances impractical with ground personnel.
- Law Enforcement:Police departments procure through federal grant programs with specific chain-of-custody requirements for evidentiary footage.
- Government Facilities:Critical infrastructure sites mandate encrypted communications and air-gapped operational networks.
Residential Users anchor unit shipments. Commercial Properties concentrate margin expansion.
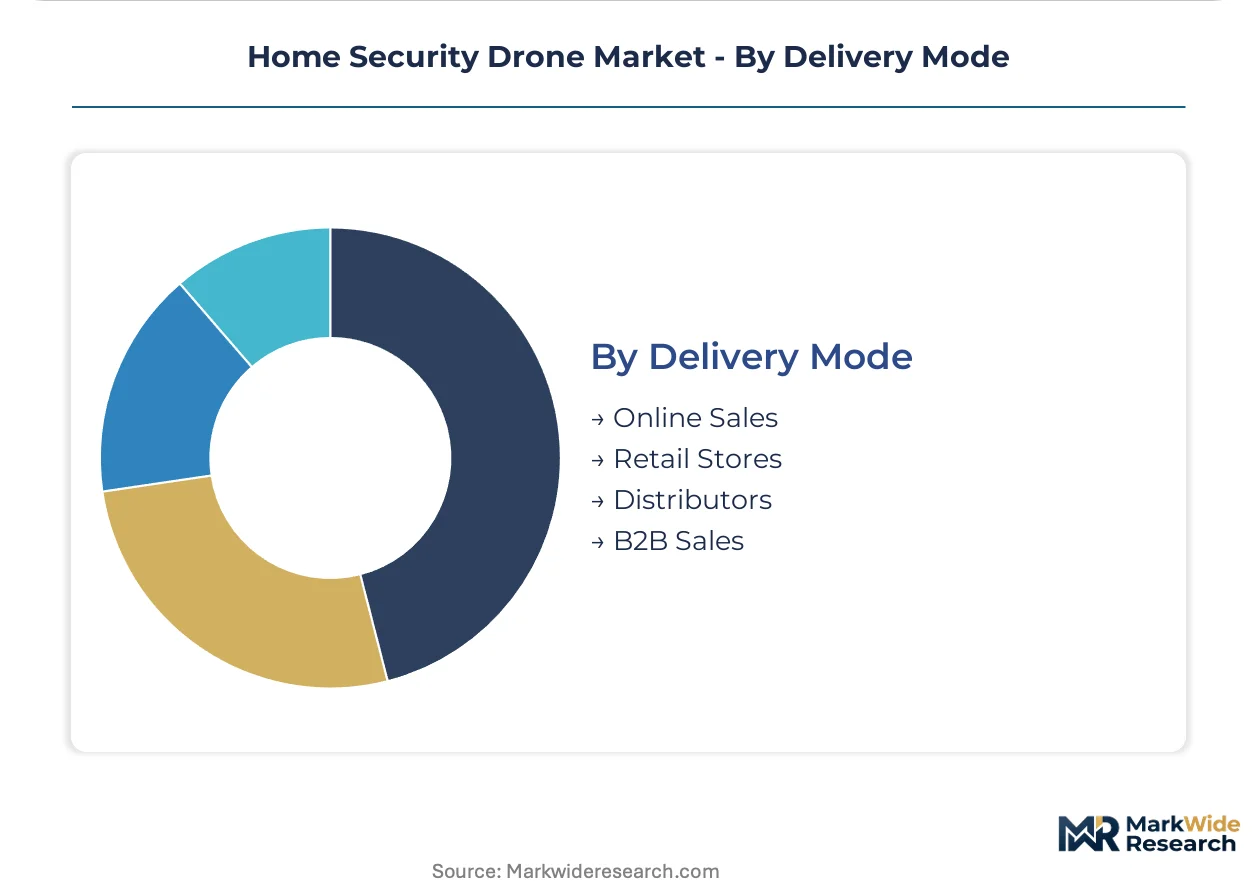
Delivery Mode:
Channel selection correlates with buyer technical sophistication and fleet scale requirements.
- B2B Sales:Direct enterprise engagements enable customization of fleet management software and maintenance service level agreements. Large estate operators in the United Arab Emirates negotiate multi-year patrol contracts with dedicated technical account support.
- Distributors:Regional security integrators stock inventory for rapid deployment to mid-size commercial clients requiring localized service response.
- Online Sales:E-commerce channels serve prosumers and small residential buyers with standardized configurations.
- Retail Stores:Big-box electronics retailers move entry-tier units to DIY home security adopters.
B2B Sales capture the highest contract values. Distributors mediate the broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in the United States demonstrate the lowest price elasticity, absorbing premium autonomous patrol services through homeowners association fees, while price-sensitive adopters in emerging markets gravitate toward entry-tier hardware with minimal recurring software commitments.
United States
Gated communities in Florida and Texas are consolidating multi-year drone patrol contracts with security service providers. FAA Part 107 waiver expansions for beyond-visual-line-of-sight operations now enable single-operator control of fleet deployments across sprawling suburban developments. The Dallas-Fort Worth metroplex anchors the highest concentration of active autonomous patrol deployments among residential estate operators.
Australia
Queensland mining estate operators specify autonomous perimeter patrol for vast distances impractical with ground personnel. CASA standard operating conditions accommodate altitude-capped autonomous architectures across low-density residential corridors. Suburban developments in Western Australia are piloting edge-based analytics to minimize transmission bandwidth under regulatory constraints.
United Arab Emirates
Large estate operators in Dubai negotiate multi-year patrol contracts with dedicated technical account support. MOHAP coordination with aviation authorities streamlines operational authorization for security applications. Multi-drone swarming demonstrations have migrated from research to production deployments across Abu Dhabi commercial property portfolios.
Germany
System integrators serving French and German commercial properties demand open-architecture software for customization flexibility. EASA specific category operational authorization under EU Drone Regulation mandates redundant navigation sensors and geofencing logic at the firmware layer. The Rhine-Ruhr metropolitan periphery faces extended procurement cycles as buyers await regulatory clarity on autonomous flight permissions.
Japan
Corporate campus security departments prioritize integration with existing physical security information management platforms. METI guidance on autonomous system deployment shapes vendor compliance documentation for commercial property tenders. The Kanto region around Tokyo concentrates demand for persistent aerial coverage with encrypted command links.
Home Security Drone Market Competitive Landscape
Capability concentration sits with autonomous navigation specialists; scale advantage sits with consumer electronics incumbents with established distribution infrastructure. The vendor base stratifies across three tiers: premium autonomous stack providers, ecosystem-integrated consumer brands, and open-architecture European system integrators. Dominant competitive moves include strategic partnerships with smart-home platform operators and backward integration into proprietary sensor module sourcing.
Within the premium autonomous tier, Skydio and Parrot exemplify divergent architectural philosophies. Skydio leverages proprietary navigation stacks to sustain positioning in law enforcement channels. Parrot competes through open-software approaches that appeal to European integrators seeking customization flexibility. Ring LLC anchors consumer mindshare through tight integration with existing smart-home ecosystems, occupying a scale-driven position that rewards ecosystem lock-in over pure flight performance.
| Leading Market Players |
|---|
| Parrot |
| Azur Drones |
| Sunflower Labs Inc. |
| Draganfly |
| Percepto |
| Ring LLC |
| Autel Robotics |
| Sony |
| Skydio |
| Others |
Supply & Pricing Matrix
Lithium-polymer battery cost volatility functions as the dominant risk vector determining both pricing tier spreads and supply chain configuration across home security drone manufacturing. Cell-grade cathode material price swings compress hardware margins at the economy tier while forcing premium vendors toward captive sourcing agreements to stabilize input costs.
Pricing Analysis
Aftermarket service revenue tiers now drive lifetime value capture more than initial hardware sales. Three-tier pricing structure across premium autonomous stacks, standard GPS-navigated units, and economy camera-drones separates vendors by AI capability depth and sensor redundancy. Price differentiation hinges on FAA Part 107 waiver compatibility and onboard inference chip specification. Cost compression in entry-tier hardware is intensifying because Chinese component suppliers are absorbing margin erosion to maintain volume share. Residential homeowners associations in Florida demonstrate lowest price sensitivity, absorbing patrol subscriptions through association fees, while Australian mining estate operators negotiate aggressively on per-acre pricing.
Supply Chain Analysis
Contract manufacturing concentration for flight control boards and gimbal assemblies rests with Taiwanese EMS providers and Shenzhen-based CMs serving tier-one drone brands. Geographic supply concentration centers on China for lithium-polymer cells and carbon fiber airframes, Taiwan for semiconductor packaging, and South Korea for high-density memory modules. Raw material dependencies span cobalt and nickel cathode formulations, rare earth magnets for brushless motors, and germanium substrates for infrared sensors. Single-source vulnerability concentrates in East Asian foundries fabricating thermal imaging modules. Distribution runs through regional security integrators in the United States and Australia, direct enterprise sales in the United Arab Emirates, and e-commerce channels for residential prosumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home security drone markets function fundamentally as service-attach opportunities where recurring patrol subscriptions and predictive maintenance contracts expand faster than hardware replacement cycles. Vendors capturing aftermarket revenue streams outperform pure equipment sellers on customer lifetime value metrics.
For Market Incumbents: Pre-empt margin erosion in entry-tier hardware by backward integration into proprietary battery pack assembly and sensor calibration services. Consolidate vendor relationships with Florida and Texas homeowners associations through multi-year patrol service contracts that bundle hardware refresh cycles. Counter emerging open-architecture software competitors by embedding API-level smart-home ecosystem integration at the firmware layer.
For New Entrants and Emerging Players: Build out specialized swarming coordination software for large estate operators in the United Arab Emirates and Queensland mining corridors where multi-drone fleet management remains undersupplied. Target suburban Australian developments under CASA altitude-capped operating conditions as the most penetrable geography for autonomous patrol services. Pursue white-label partnerships with established physical security integrators lacking in-house drone engineering capability.
For Investors and Strategic Acquirers: Autonomous navigation software specialists with proven FAA waiver support documentation represent priority acquisition targets for defense and security conglomerates seeking differentiated positioning. Long-term viability in this market hinges on regulatory compliance infrastructure and recurring revenue attachment rates rather than hardware shipment scale alone. Watch EASA specific category operational authorization approval timelines as the critical inflection signal for European market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 107 Waiver Portfolio Expansion | Beyond-visual-line-of-sight permissions unlock contiguous estate coverage in Texas and Florida gated communities. |
| Edge AI Inference Chip Integration | Onboard computer vision reduces cloud latency for Australian deployments under CASA bandwidth constraints. |
| Smart-Home Platform API Partnerships | Ring and Alexa ecosystem integration creates sticky vendor relationships in residential subscription segments. |
| Redundant Navigation Sensor Certification | EASA specific category compliance enables European market access for French and German system integrators. |
| Predictive Maintenance Service Contracts | Rotor wear and battery degradation monitoring extends fleet refresh cycles and locks in recurring revenue. |
Research Methodology
Desk research of FAA waiver filing databases, EASA type certification registries, and CASA operational authorization records preceded structured interviews with autonomous systems engineering directors, security operations center managers, and homeowners association procurement chairs. Primary fieldwork with drone fleet operators in Florida, Texas, and Queensland validated deployment cost structures and patrol service pricing benchmarks. Secondary sources encompassed customs import records for lithium-polymer cells, SEC filings from consumer electronics incumbents, and smart-home platform partnership announcements. Bottom-up unit shipment estimates by product tier and top-down service revenue projections by geography were triangulated to constrain forecast variance.
Assumptions regarding FAA beyond-visual-line-of-sight rulemaking progression, EASA specific category authorization timelines, and lithium-polymer cell pricing trajectories were held fixed across baseline scenarios while autonomous flight permission divergence and smart-home platform consolidation were modeled as sensitivity variables. Segmentation dimensions spanned product architecture, technology layer, end-user type, and delivery mode. CAGRs were derived from logistic adoption curve fitting calibrated against historical security technology diffusion patterns. Inputs included gated community expansion permits in target geographies and mining estate perimeter distances requiring patrol coverage.
Stress conditions across battery material cost spikes, regulatory authorization delays, and competitive entry from consumer electronics brands were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that autonomous systems engineering talent scarcity or geopolitical disruption to East Asian sensor supply chains could materially revise trajectory projections. Cross-checking against FAA annual waiver issuance statistics and Australian mining capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Middle-East and Africa Small UAV Market
UAV
Global Drone Software Market
UAV
Global Electric Drone Market
UAV
Global Drone Data Services Market
UAV
Ultra-Long Endurance Drone Market
UAV
Commercial Drone-Enabled Services Market
UAV
Fixed Wing Military Drones Market
UAV
Global Drone Services Market
UAV
Drone Camera Market
UAV
Enterprise Drone Management Solutions Market
UAV
Autonomous Aircraft Cameras Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Europe Drones Market
UAV
Counter Drone System Market
UAV
Drone Defense System Market
UAV
UAV Lidar Market