
 Nano Drones Market | 2026-2036
Nano Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Drones Market Outlook
Military-grade endurance specifications above twenty-five minutes is bifurcating the competitive landscape into premium defense suppliers and cost-optimized commercial vendors. DJI Technology Co. Ltd. leverages its Shenzhen manufacturing base to dominate consumer and prosumer tiers with integrated flight controllers. AeroVironment Inc. anchors its position through captive production of propulsion systems for U.S. Department of Defense contracts. Lockheed Martin Corporation specializes in encrypted datalinks and thermal payloads for denied-area operations.
Nano drones denote unmanned aerial vehicles with maximum dimensions below two hundred millimeters and gross takeoff weights under twenty-five grams, typically employing brushless DC motors and lithium-polymer cells to achieve thrust-to-weight ratios exceeding two-to-one for indoor navigation and close-range reconnaissance. Multirotor configurations, particularly nano quadcopters, occupy the largest production volume due to mechanical simplicity and hovering precision in GPS-denied environments. Autonomous and AI-Enhanced technology segments represent the fastest-expanding capability layer as obstacle-avoidance algorithms and swarm coordination protocols migrate from research laboratories to fielded systems.
The FAA enforces Part 107 operational limitations and remote identification requirements for commercial nano drone flights below four hundred feet, while EASA's open and specific category frameworks mandate CE marking and conformity assessments for European market access. Military procurement channels operate under ITAR and EU dual-use export controls, creating segmented certification pathways that vendors must navigate separately. Stakeholders should monitor evolving counter-drone regulations and electromagnetic spectrum allocation decisions that could restrict flight zones or command-link frequencies without warning.
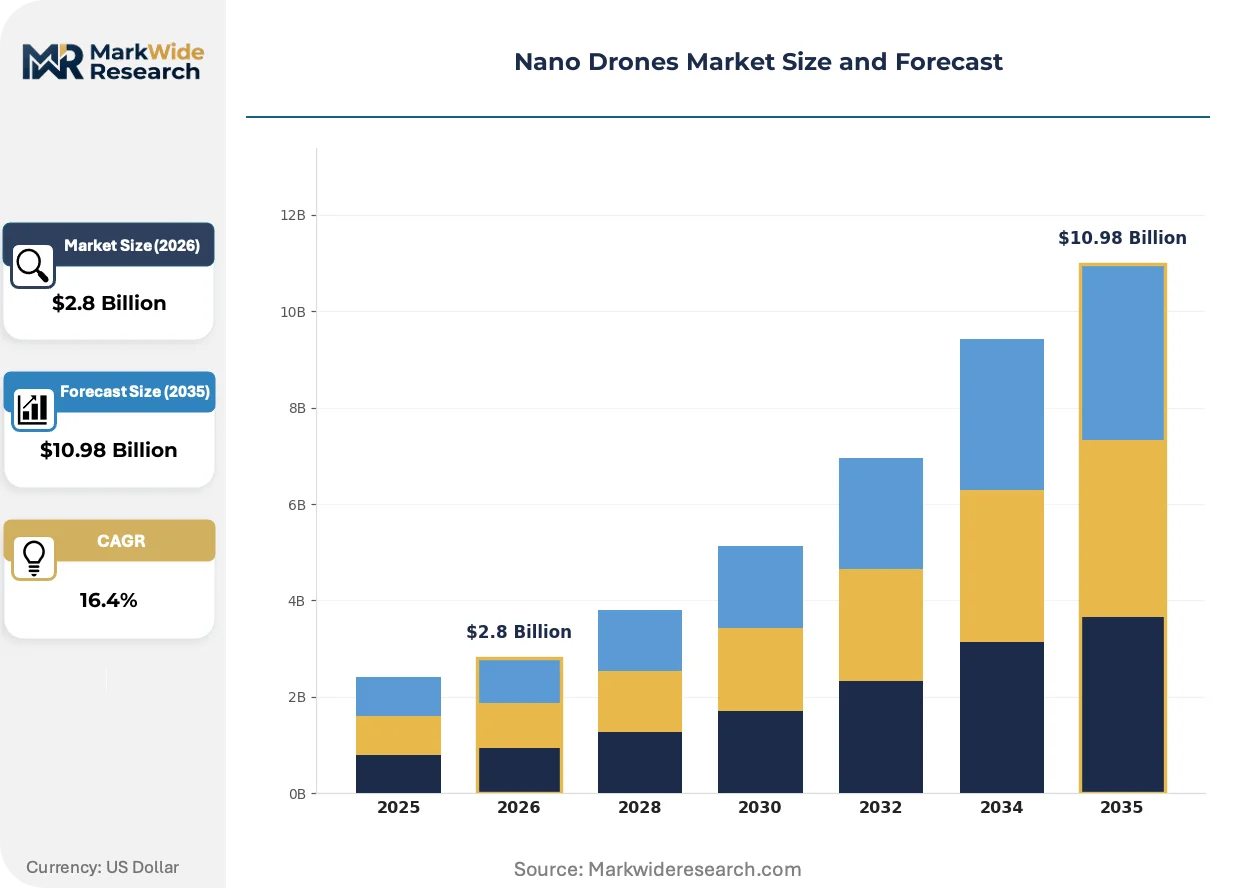
Market Dynamics
Military procurement specifications for extended flight endurance and encrypted datalinks are compressing supplier margins while elevating technical entry barriers, forcing commercial vendors toward modular payload architectures and defense contractors toward captive manufacturing.
Growth Catalysts
- Special Operations Command procurement:U.S. defense budgets prioritize palm-sized ISR platforms for urban reconnaissance, creating sustained demand for miniaturized thermal and electro-optical payloads.
- EASA open-category frameworks:CE marking pathways for sub-250-gram platforms accelerate commercial operator certification across European member states, expanding addressable operator bases.
- Brushless DC motor efficiency gains:Thrust-to-weight ratios exceeding two-to-one enable GPS-denied indoor navigation, opening facility security and infrastructure inspection applications previously unreachable by larger systems.
Market Restraints
- Lithium-polymer cell supply concentration:Battery chemistry production clusters in East Asian manufacturing zones expose vendors to raw material price volatility and export control friction.
- ITAR and EU dual-use export controls:Segmented certification pathways for military versus commercial channels force redundant engineering and compliance investments.
- Radio frequency spectrum allocation uncertainty:Command-link frequency restrictions in densely populated airspaces threaten operational continuity without warning.
Strategic Opportunities
- Swarm coordination protocols:Autonomous multi-agent algorithms migrating from research laboratories enable coordinated area coverage for search-and-rescue and agricultural monitoring.
- FAA Part 107 remote identification mandates:Compliance requirements for commercial flights below four hundred feet create aftermarket service opportunities for identification module integration and fleet management software.
- India's PLI scheme for drone manufacturing:Production-linked incentives for domestic assembly attract component suppliers seeking tariff-advantaged access to South Asian defense and civil markets.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time obstacle avoidance and sensor fusion outpaces available talent pools, extending product development cycles.
- Counter-drone electromagnetic interference: Detection and neutralization systems deployed at critical infrastructure sites degrade command links and GPS signals, forcing redundant navigation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Drones Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed Wing, Hybrid, Nano Quadcopter Application: Agriculture, Surveillance, Delivery, Photography End User: Military, Commercial, Research, Recreational Technology: Remote Control, Autonomous, GPS, AI-Enhanced |
| Companies Covered | DJI Technology Co. Ltd., AeroVironment Inc., Parrot SA, Lockheed Martin Corporation, Northrop Grumman Corporation, Teledyne FLIR, Yuneec International Co. Ltd., Skydio Inc., Draganfly Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Drones Market Strategic Shifts
Autonomous flight algorithms and miniaturized sensor payloads are redistributing competitive advantage from airframe manufacturers to software and semiconductor specialists, compressing hardware margins while expanding recurring revenue streams.
Swarm intelligence architectures is fragmenting the competitive landscape as obstacle-avoidance algorithms and decentralized coordination protocols migrate from university laboratories to fielded military and commercial systems. Defense procurement offices now evaluate platforms on network scalability rather than individual unit specifications. This capability compression favors vendors with captive software development over pure hardware assemblers.
EASA's specific category operational authorization requirements impose conformity assessments for beyond-visual-line-of-sight flights, forcing commercial operators to invest in detect-and-avoid systems and redundant communications links. Agricultural spraying and linear infrastructure inspection segments face the steepest compliance cost escalation. German and French regulators are accelerating parallel frameworks, creating fragmented European compliance timelines.
Buyer concentration among defense primes and large-scale agricultural enterprises is compressing distributor margins and accelerating direct manufacturer-to-operator sales channels. Volume procurement agreements now bundle hardware, software licenses, and maintenance into multi-year contracts. This shift is most visible in U.S. federal procurement and Brazilian agribusiness operations, where fleet standardization reduces training and logistics overhead.
Nano Drones Market Segmentation
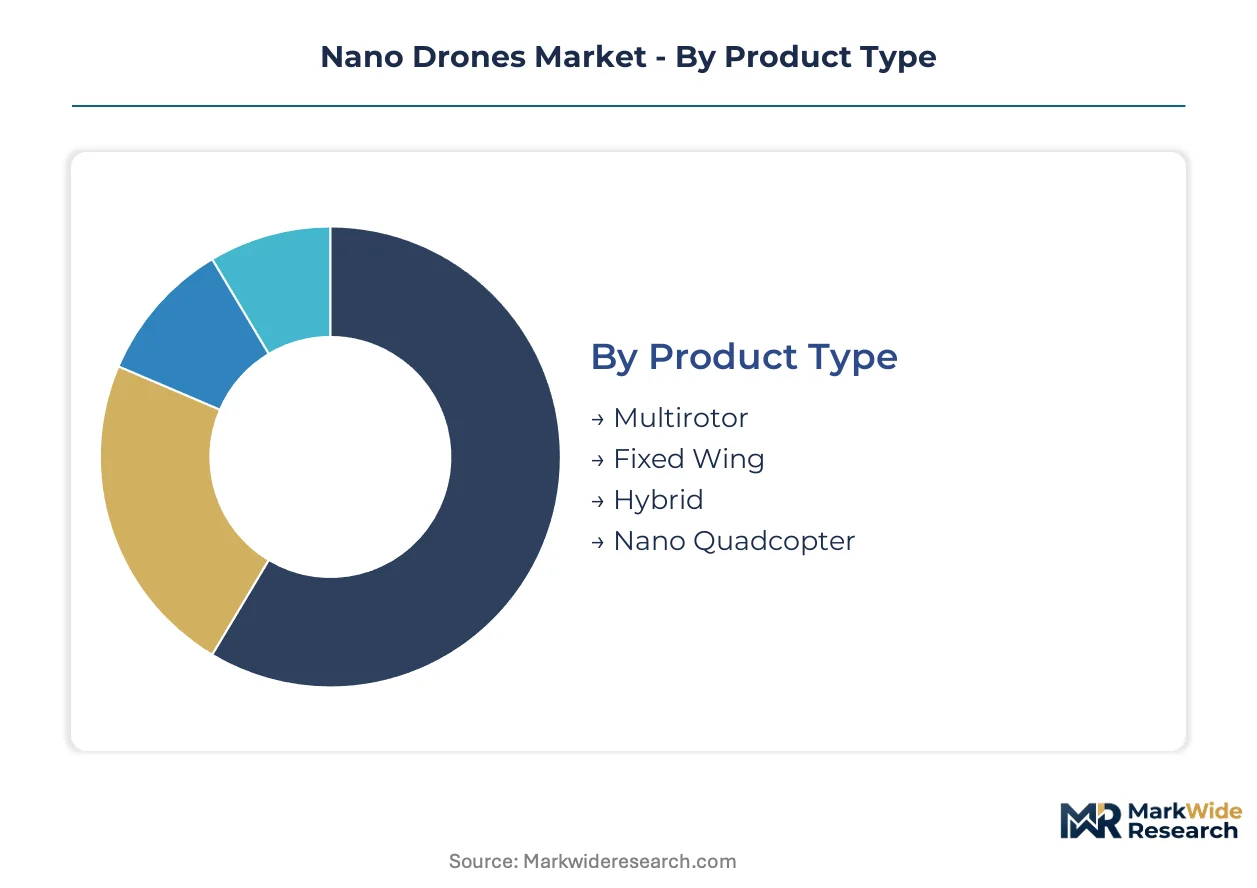
Segmentation in nano drones reveals how procurement channels fragment across defense certification requirements and commercial operator economics. Vendors navigate divergent technical specifications, compliance pathways, and pricing architectures depending on which slice they target.
Product Type:
Multirotor platforms dominate domestic defense procurement, while fixed-wing variants concentrate in export-led agricultural monitoring contracts.
- Multirotor:Mechanical simplicity enables hovering precision in GPS-denied environments. U.S. Special Operations Command specifications prioritize these configurations for urban intelligence gathering, driving demand for encrypted datalinks and thermal payloads.
- Nano Quadcopter:Brushless DC motors and lithium-polymer cells deliver thrust-to-weight ratios exceeding two-to-one. German facility security operators and Japanese infrastructure inspectors deploy these for indoor navigation where larger systems cannot operate.
- Fixed Wing:Extended endurance suits linear crop monitoring across Brazilian soybean belts and Australian pastoral stations.
- Hybrid:Combines vertical takeoff with fixed-wing efficiency for last-mile delivery trials in Singapore and Dubai.
Multirotor configurations command the established base. The steepest expansion runs through nano quadcopters.
Application:
Surveillance applications absorb the highest unit economics, while agriculture spreads volume across price-sensitive emerging markets.
- Surveillance:Military reconnaissance and critical infrastructure protection demand miniaturized electro-optical and thermal sensors. NATO urban operations and Saudi border security programs specify palm-sized platforms with encrypted command links.
- Agriculture:Precision spraying and crop health monitoring spread across Indian cotton belts and Vietnamese rice paddies. India's PLI scheme for domestic drone assembly accelerates fleet deployment among agritech cooperatives.
- Delivery:Medical supply transport trials operate under FAA Part 107 waivers in North Carolina and EASA specific-category authorizations in Ireland.
- Photography:Content creation and real estate marketing concentrate in UAE luxury property sectors and South Korean influencer economies.
Surveillance retains the premium pricing tier. Agricultural deployment scales fastest by unit volume.
End User:
Military procurement channels operate under ITAR and EU dual-use controls, while recreational demand concentrates in consumer electronics retail.
- Military:Encrypted datalinks, thermal payloads, and swarm coordination protocols define procurement specifications. U.S. Department of Defense budgets prioritize miniaturized ISR platforms, with AeroVironment and Lockheed Martin anchoring supplier relationships through captive manufacturing.
- Commercial:FAA Part 107 remote pilot certification and EASA open-category frameworks reshape operator compliance. German agricultural enterprises and Brazilian agribusiness operations standardize fleets to reduce training overhead.
- Research:University laboratories in Switzerland and South Korea advance obstacle-avoidance algorithms and decentralized coordination protocols.
- Recreational:Sub-250-gram platforms bypass registration requirements in FAA and EASA jurisdictions, concentrating sales through Shenzhen-based supply chains.
Military end users anchor the technology frontier. Commercial operators drive manufacturing scale.
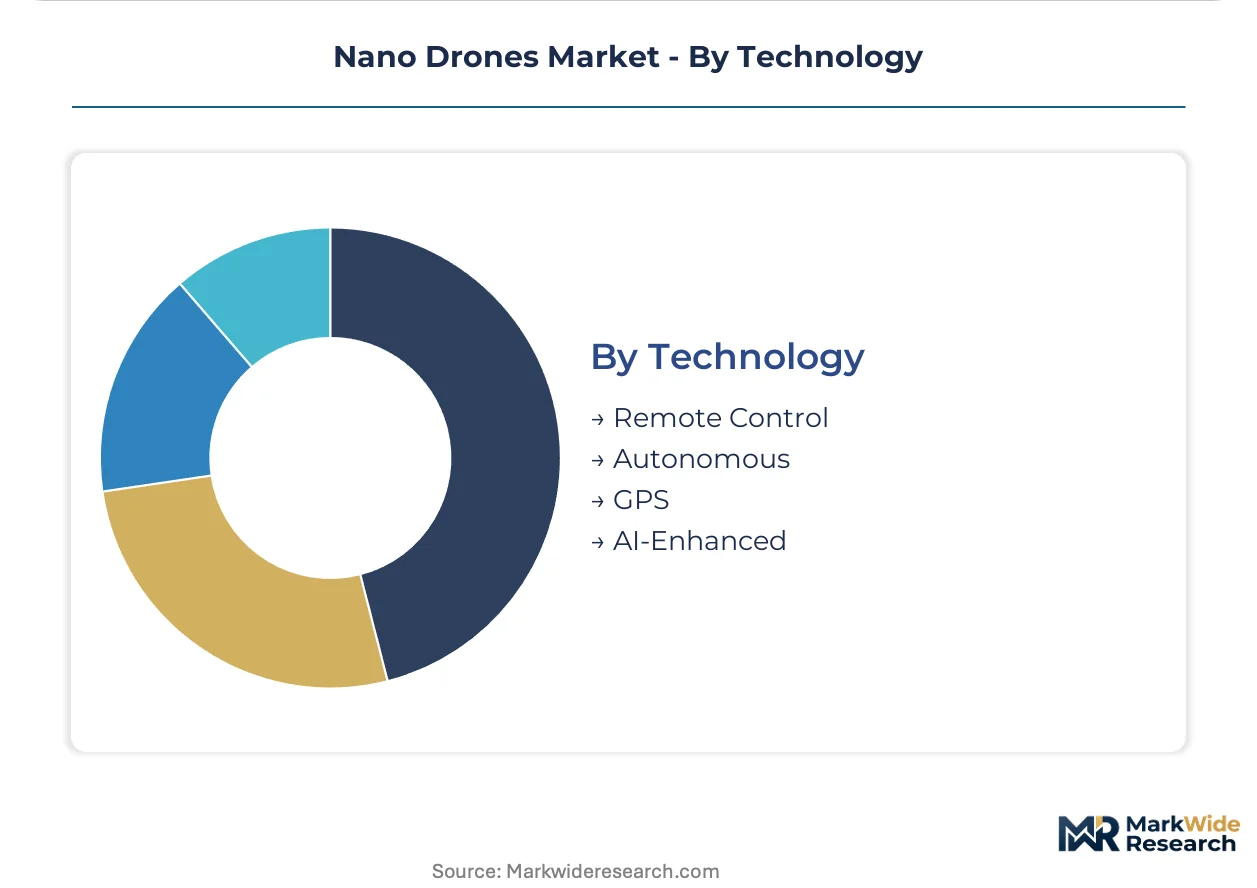
Technology:
Autonomous capabilities concentrate R&D investment, while remote control retains cost-sensitive consumer segments.
- Autonomous:Real-time obstacle avoidance and sensor fusion algorithms migrate from research laboratories to fielded systems. Swarm coordination protocols enable coordinated area coverage for search-and-rescue operations in Alpine regions and agricultural monitoring across French vineyards.
- AI-Enhanced:Machine vision for target recognition and predictive maintenance spreads through defense primes and large-scale commercial fleets. Embedded systems engineering scarcity extends product development cycles for these tiers.
- Remote Control:Line-of-sight operation dominates recreational and entry-level commercial segments under FAA and EASA basic frameworks.
- GPS:Satellite navigation supports waypoint programming for infrastructure inspection, though counter-drone electromagnetic interference forces redundant navigation architectures.
Autonomous systems absorb the steepest R&D escalation. AI-Enhanced platforms are gaining share fastest among defense and enterprise adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Shenzhen, Shenzhen-based supply chains, and U.S. defense procurement offices concentrate nano drone production capacity. Military specifications from NATO members and commercial certification frameworks from EASA and FAA create divergent demand poles across three continents.
United States
Special Operations Command budgets prioritize palm-sized ISR platforms for urban reconnaissance missions. FAA Part 107 remote pilot certification and remote identification requirements reshape commercial operator compliance. Defense procurement concentrates in Virginia and California corridors where AeroVironment and Lockheed Martin maintain captive manufacturing relationships.
China
Shenzhen manufacturing bases dominate consumer and prosumer tier production through integrated flight controller supply chains. MIIT standards and export control frameworks govern dual-use technology shipments. Guangdong Province hosts the densest cluster of brushless DC motor and lithium-polymer cell suppliers.
Germany
Facility security operators deploy nano quadcopters for indoor navigation in GPS-denied industrial environments. EASA open-category frameworks mandate CE marking for sub-250-gram platforms. Bavaria and Baden-Württemberg host precision engineering suppliers serving both defense and commercial channels.
India
Agritech cooperatives accelerate fleet deployment for precision spraying across cotton belts and rice paddies. PLI scheme production-linked incentives attract component suppliers for domestic assembly. Telangana and Karnataka emerge as drone manufacturing hubs under central government subsidy programs.
France
Vineyard agricultural monitoring adopts swarm coordination protocols for coordinated area coverage. EASA specific category operational authorizations impose conformity assessments for beyond-visual-line-of-sight flights. Toulouse and Paris-Saclay clusters advance autonomous flight algorithm research from university laboratories.
Nano Drones Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Premium defense suppliers anchor encrypted datalink and thermal payload specifications through captive manufacturing investments. Cost-optimized commercial vendors leverage modular payload architectures and Shenzhen supply chain proximity. Consolidation pressure intensifies as procurement offices evaluate platforms on network scalability rather than individual unit specifications.
Within the defense-contractor archetype, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions tied to U.S. Department of Defense procurement channels. DJI Technology Co. Ltd. exemplifies the scale-driven commercial tier with Shenzhen manufacturing integration. AeroVironment Inc. sits within the mid-tier specialist category serving dual defense and commercial applications.
| Leading Market Players |
|---|
| DJI Technology Co. Ltd. |
| AeroVironment Inc. |
| Parrot SA |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Teledyne FLIR |
| Yuneec International Co. Ltd. |
| Skydio Inc. |
| Draganfly Innovations |
| Others |
Value Chain & Pricing Dynamics
Brushless DC motor substitution for brushed alternatives simultaneously concentrates Guangdong Province supply geography and compresses unit economics across consumer tiers. Lithium-polymer cell chemistry migration from cobalt-heavy formulations toward lithium-iron-phosphate variants redraws raw material sourcing maps while flattening price curves for entry-level platforms.
Pricing Analysis
FAA Part 107 and EASA open-category frameworks dictate the pricing tier structure across defense, commercial, and recreational segments. Three-tier pricing structure across premium defense, standard commercial, and economy consumer levels separates ITAR-certified platforms with encrypted datalinks from CE-marked inspection systems and sub-250-gram unregistered units. Cost compression in the commercial tier intensifies because Shenzhen manufacturing integration enables modular payload architectures. Recreational buyers exhibit highest price sensitivity, while Special Operations Command procurement demonstrates lowest elasticity for mission-specified endurance and thermal capabilities.
Supply Chain Analysis
Strategic stockpiling of lithium-polymer cells and brushless DC motors dominates inventory strategy as vendors hedge against East Asian export control friction. Component manufacturing concentrates in China, South Korea, and Japan, drawing from rare earth magnet supplies and semiconductor foundry outputs. Single-source vulnerability in battery chemistry production clusters exposes downstream assemblers to raw material price volatility. Distribution runs through direct manufacturer-to-operator channels for defense primes and agribusiness fleets, while consumer tiers rely on Shenzhen-based electronics retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swarm coordination protocol maturation represents a high-growth disruption as autonomous multi-agent algorithms migrate from research laboratories to fielded military and commercial systems. FAA remote identification mandates and EASA specific-category frameworks accelerate compliance service opportunities across the analysis window.
For Market Incumbents: Shield encrypted datalink capabilities through captive semiconductor fabrication investments as DJI Technology Co. Ltd. and emerging Shenzhen competitors erode hardware margins. Deepen backward integration into brushless DC motor production to defend against Guangdong Province supply concentration risks. Prioritize software licensing architectures that monetize swarm coordination protocols on recurring revenue streams rather than unit sales.
For New Entrants and Emerging Players: EASA CE marking fast-track pathways for sub-250-gram platforms open immediate addressable market expansion among German facility security operators and French vineyard agricultural monitors. Target Indian agritech cooperatives under PLI scheme subsidies where domestic assembly incentives reduce tariff exposure. Pursue direct-to-operator sales models that bundle hardware with fleet management software subscriptions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial drone assemblers lacking autonomous software development capabilities. Long-term viability hinges on migration from hardware margins toward recurring software revenue across the projection horizon. Acquisition targets should demonstrate embedded systems engineering depth in obstacle-avoidance firmware. Monitor FAA electromagnetic spectrum allocation decisions as the inflection signal for command-link architecture obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Swarm Coordination Protocol Development | Autonomous multi-agent algorithms enable coordinated area coverage for NATO urban reconnaissance and Alpine search-and-rescue operations. |
| Remote Identification Module Integration | FAA Part 107 compliance services create aftermarket revenue streams for commercial fleet operators below four hundred feet. |
| Domestic Manufacturing Footprint Expansion | India's PLI scheme attracts component suppliers seeking tariff-advantaged access to South Asian defense and civil procurement channels. |
| Encrypted Datalink Captive Production | In-house semiconductor fabrication shields defense contractors from ITAR-controlled technology transfer restrictions. |
| AI-Enhanced Sensor Fusion R&D Investment | Machine vision for target recognition spreads through U.S. Department of Defense primes and Brazilian agribusiness fleet operators. |
Study Parameters
Initial hypotheses were tested against primary input from Special Operations Command procurement officers, FAA certification specialists, EASA conformity assessment bodies, and Shenzhen manufacturing supply chain managers, then refined through secondary validation. Defense budget appropriations documents, ITAR-controlled technology export filings, EASA open-category regulatory frameworks, and Guangdong Province customs records anchored quantitative baselines. Bottom-up triangulation across component supplier interviews and top-down reconciliation against NATO member state procurement databases ensured segmentation integrity.
Variance decomposition across product type, application, end user, and technology dimensions structured the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth trajectory reconciliation against macroeconomic defense spending and commercial operator certification expansion. Modeled inputs included lithium-polymer cell price indices, brushless DC motor efficiency curves, and swarm coordination protocol adoption rates from university laboratory transfer timelines.
Decision-makers should treat outputs as directional under assumptions of sustained Special Operations Command ISR platform prioritization and stable EASA regulatory frameworks; material deviation would warrant model refresh. Revision becomes warranted when FAA electromagnetic spectrum allocation decisions or India's PLI scheme subsidy modifications cross thresholds that alter component sourcing economics or certification pathway viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Multirotor Drones Market
UAV
Drone Delivery Services Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Solar Powered Drones Market
UAV
Global Inspection Drones Market
UAV
Global Smart Commercial Drones Market
UAV
Small UAV Market
UAV
UAV Battery Market
UAV
Europe Commercial Drones Market
UAV
North America Small UAV Market
UAV
Drone Powered Business Solutions Market
UAV
GCC Drones Market
UAV
Drone Data Management Market
UAV
Drone-Based Consulting Services Market
UAV
Home Security Drone Market
UAV
North America Drone Software Market