
 Global Tag Management System Market | 2026-2036
Global Tag Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tag Management System Market Foresight
Enterprise software procurement channels are rewriting how tag management vendors reach decision-makers. Google leverages its embedded position within marketing technology stacks to sustain dominance in client-side deployments. Adobe competes through deep integration with its creative cloud and analytics suites, while Tealium differentiates via specialized customer data platform adjacencies.
A tag management system is a software platform that centralizes the deployment, maintenance, and governance of tracking pixels and data collection scripts across digital properties, typically supporting JavaScript container injection, API-based server-side forwarding, and consent-state orchestration. Its primary commercial purpose is to ensure accurate marketing attribution while reducing page-load latency and technical debt. Cloud deployment leads solution delivery due to elasticity requirements for traffic spikes during retail promotional cycles, yet server-side tagging represents the fastest-expanding solution category as organizations seek to bypass browser-level cookie restrictions. Data compliance applications command premium pricing as enterprises face escalating regulatory exposure.
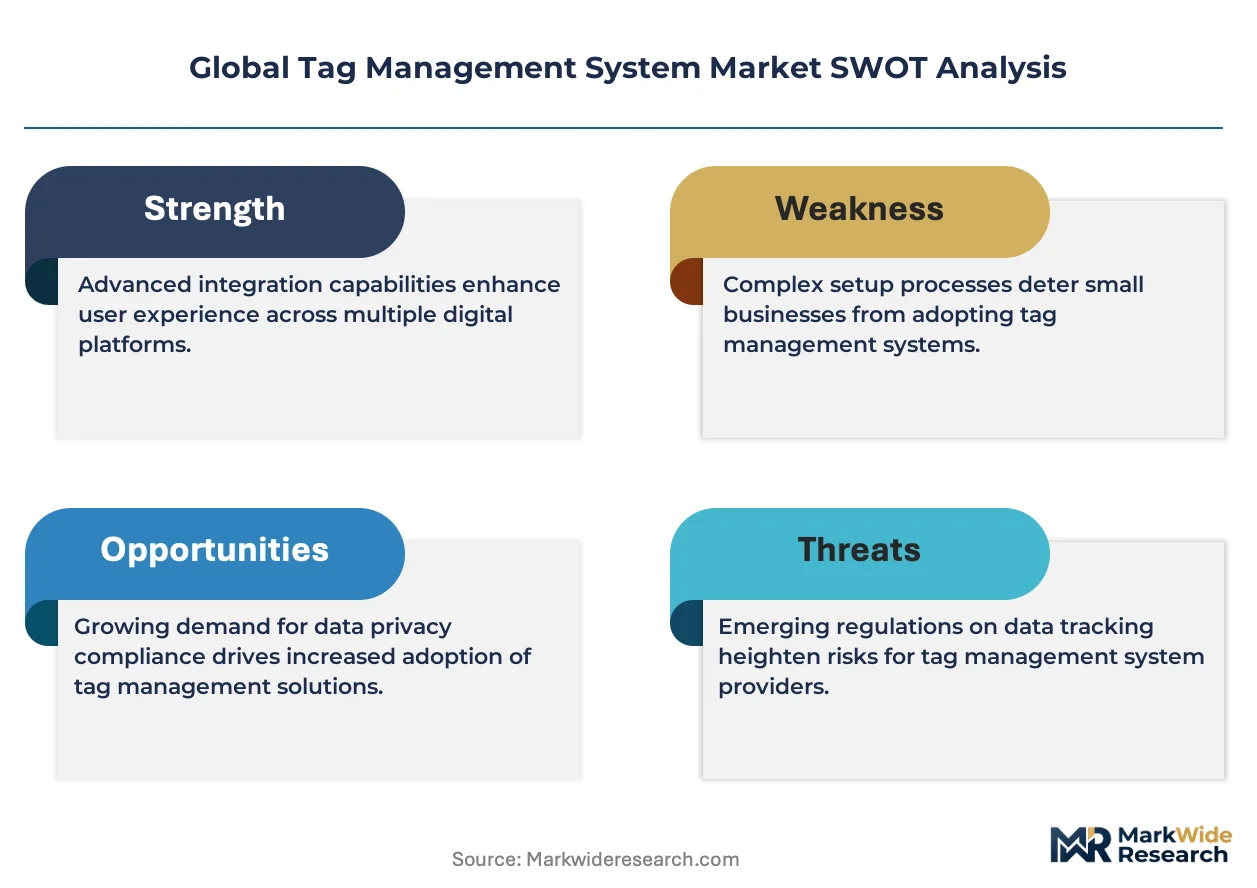
The EU's GDPR, the California Consumer Privacy Act enforced by the California Attorney General, and Brazil's LGPD administered by ANPD collectively mandate granular consent logging and data minimization, directly elevating demand for governance-centric tag management features. ISO 27001 and SOC 2 Type II certifications have become table stakes for vendor selection in financial services and healthcare-adjacent deployments. Stakeholders must monitor the divergence between browser-native privacy APIs and regulatory enforcement timelines to calibrate infrastructure migration strategies.
Market Dynamics
Server-side tagging architectures are displacing legacy client-side deployments as browser-level cookie deprecation and consent-string fragmentation force enterprises to re-architect data collection infrastructure at the network edge.
Growth Catalysts
- GDPR enforcement escalation:EU data protection authorities impose multi-million euro penalties for consent-logging failures, compelling financial institutions in Germany and telecommunications providers in the United Kingdom to upgrade governance capabilities.
- California privacy law cascade:The California Privacy Rights Act and emerging state-level statutes in Virginia and Colorado mandate granular opt-out mechanisms, driving demand for real-time consent-state orchestration.
- First-party data strategies:Retailers facing Safari Intelligent Tracking Prevention and Chrome Privacy Sandbox limitations deploy server-side containers to preserve attribution accuracy without third-party cookies.
Market Restraints
- Cloud infrastructure cost volatility:Server-side tagging architectures require sustained compute and egress expenditure during traffic spikes, compressing margins for mid-market SaaS vendors.
- Engineering talent scarcity:Deployment of API-based forwarding and edge computing configurations demands specialized DevOps and data engineering expertise concentrated in technology hubs.
- ISO 27001 certification timelines:Financial services procurement mandates extend vendor onboarding cycles by six to eighteen months, delaying revenue recognition for emerging providers.
Strategic Opportunities
- Healthcare-adjacent deployments:HIPAA-covered entities in the United States require audit-ready tag governance for patient journey analytics, creating a compliance-premium segment.
- Brazil LGPD maturation:ANPD enforcement actions against ad-tech intermediaries elevate demand for localized consent-management infrastructure among multinational consumer brands.
- Edge computing convergence:Integration of server-side tagging with CDN edge functions enables sub-50-millisecond consent resolution, opening real-time personalization use cases.
Industry Challenges
- Legacy CMS integration friction:Enterprises running decade-old content management systems face protracted migration timelines to support modern tag container injection methods.
- Cross-functional alignment gaps:Marketing operations, legal privacy offices, and engineering teams maintain conflicting KPIs for data collection granularity, slowing deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tag Management System Market |
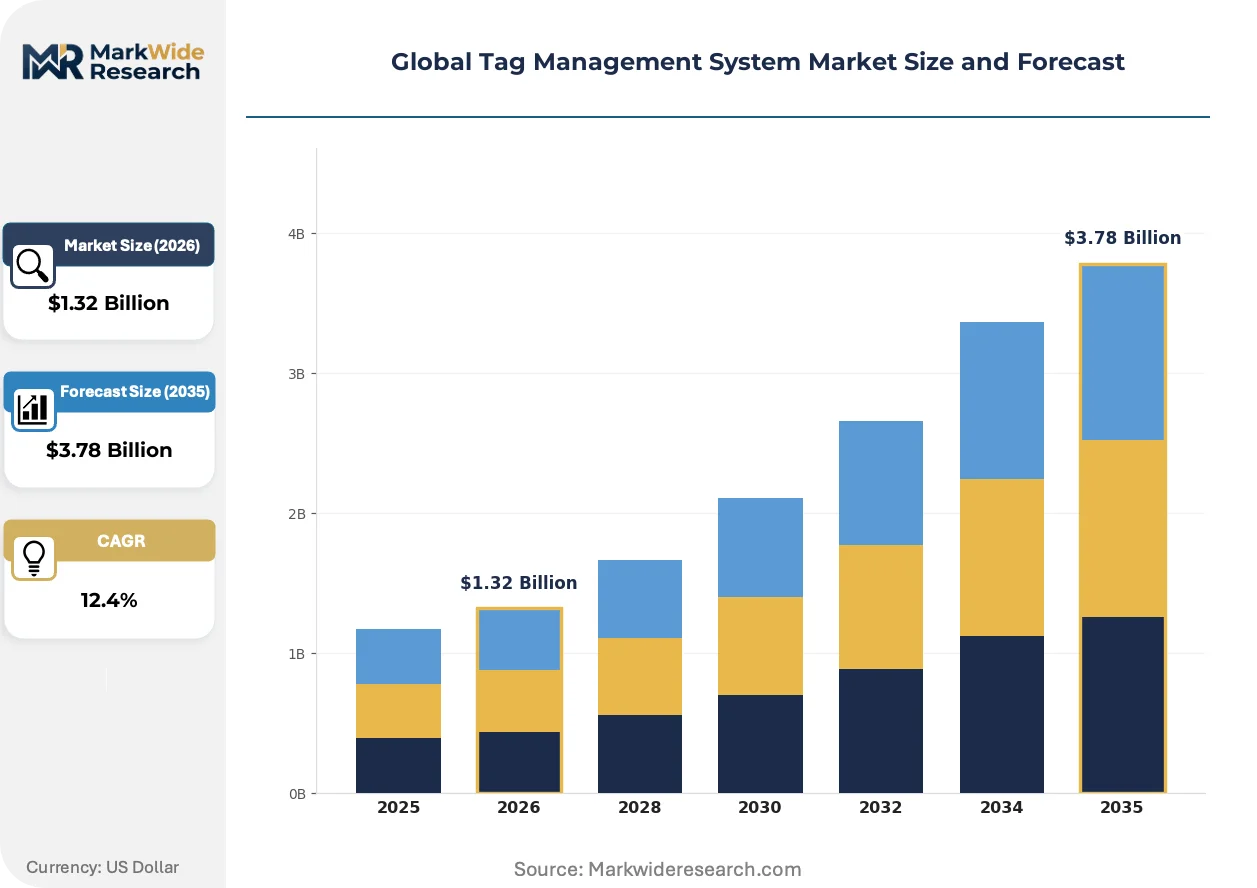
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premise, Hybrid, Private Cloud Solution: Server-Side Tagging, Client-Side Tagging, Multi-Channel Tagging, Mobile Tag Management Application: Web Analytics, Marketing Automation, Customer Experience, Conversion Optimization, Data Compliance End User: Retailers, Online Publishers, Travel Agencies, Telecommunications, Financial Institutions |
| Companies Covered | Google, Adobe, Tealium, IBM Corporation, Oracle, Ensighten, Adform, Piwik PRO, Commanders Act, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tag Management System Market Shifts & Advancements
Browser-native privacy APIs and regulatory enforcement divergence are compressing technology refresh cycles while elevating governance automation from cost center to competitive differentiator.
Server-side tagging infrastructure is migrating from experimental pilot programs to standard enterprise architecture. Retailers operating high-velocity promotional calendars in the United States and Germany adopt edge-deployed containers to maintain page-load performance during traffic surges. This migration from client-side injection is compressing vendor selection timelines as procurement teams prioritize ISO 27001-certified providers with demonstrated consent-orchestration capabilities.
GDPR Article 82 liability rulings by the Court of Justice of the European Union expose enterprises to direct damages claims for unlawful data transfers. Financial institutions in France and the Netherlands now mandate contractual audit rights over sub-processor tag configurations. Telecommunications providers respond by consolidating vendor relationships with platforms offering automated data-mapping documentation.
Chief Marketing Officers increasingly require outcome-based pricing for tag management services, displacing seat-based SaaS contracts. Enterprise buyers in the United Kingdom and Australia negotiate value metrics tied to consent opt-in rate improvements and data quality scores. This procurement evolution favors vendors with transparent API telemetry and customizable SLA frameworks over bundled analytics suites.
Global Tag Management System Market Segmentation
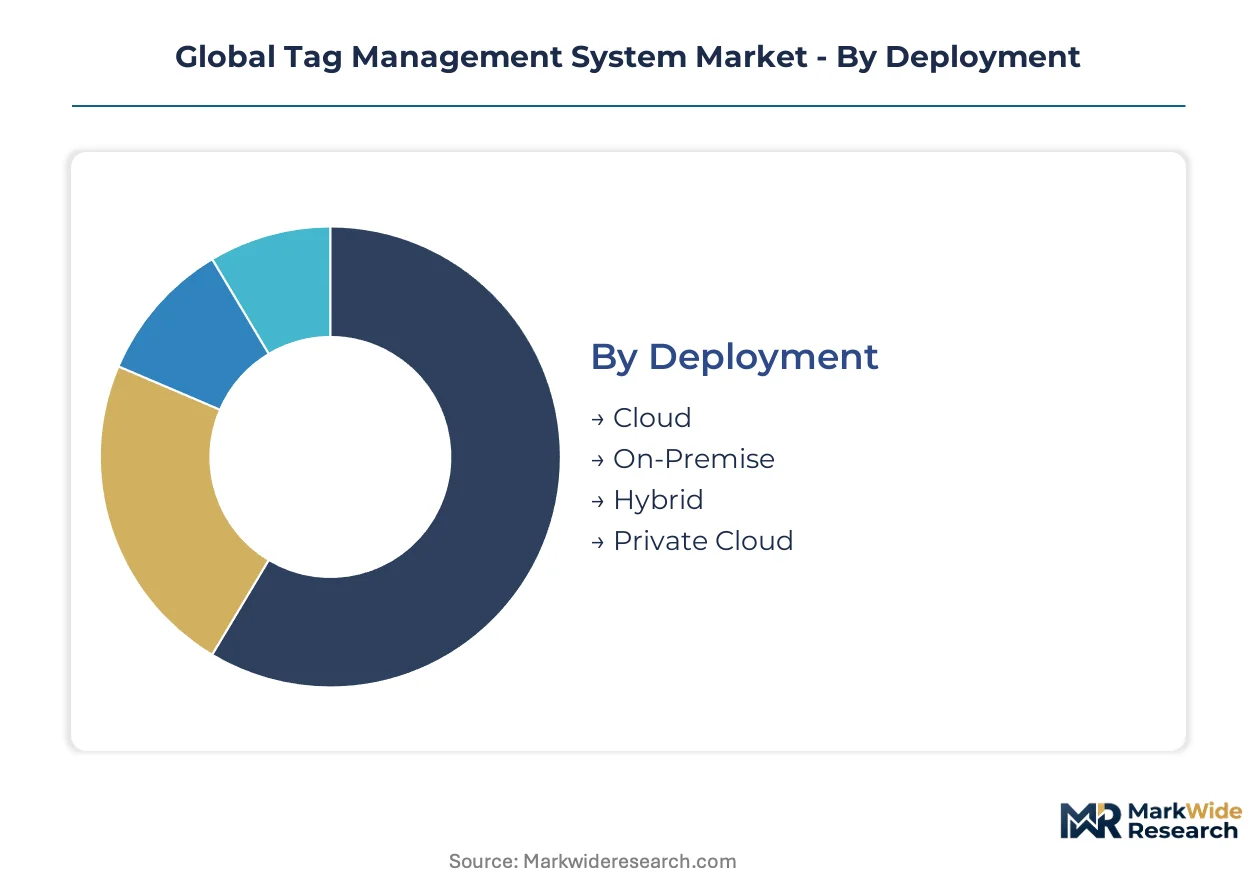
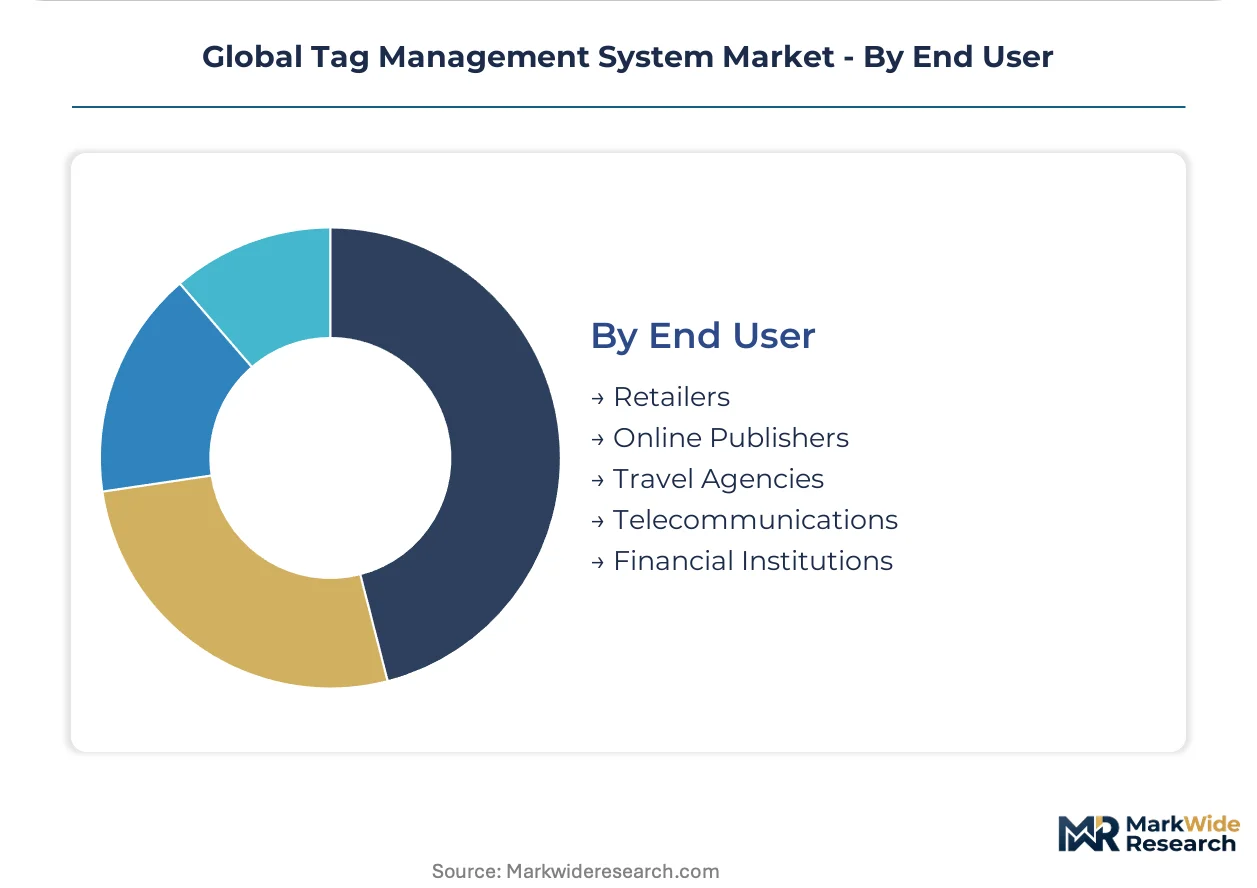
Tag management systems fragment across deployment architectures, solution types, application purposes, and end-user verticals. Each dimension carries distinct procurement criteria, compliance obligations, and technical integration requirements that reshape vendor selection workflows.
Deployment:
Cost tier structures separate elastic consumption models from fixed-capital alternatives across enterprise scale bands.
- Cloud:Elastic compute provisioning supports traffic spikes during retail promotional cycles without infrastructure over-provisioning. Demand concentrates among mid-market retailers in Germany and the United States seeking ISO 27001-certified providers with consumption-based billing.
- On-Premise:Dedicated hardware installations within enterprise data centers provide complete data sovereignty for sensitive customer records. Financial institutions in France and Switzerland mandate on-premise deployments to satisfy national banking regulator audit requirements.
- Hybrid:Split architectures route consent-sensitive data through on-premise nodes while offloading analytics workloads to public cloud infrastructure.
- Private Cloud:Single-tenant virtualized environments deliver cloud elasticity with dedicated resource isolation for healthcare-adjacent deployments.
The dominant share belongs to Cloud, while Private Cloud is closing the gap fastest.
Solution:
Application maturity separates experimental pilots from standardized enterprise architecture across data collection methodologies.
- Server-Side Tagging:Network-edge container deployment bypasses browser-level cookie restrictions and consent-string fragmentation. Telecommunications providers in the United Kingdom and retailers in the United States adopt server-side architectures to preserve attribution accuracy under Safari Intelligent Tracking Prevention.
- Client-Side Tagging:Traditional JavaScript container injection remains prevalent in legacy web estates with decade-old content management system integrations. Online publishers in India and Brazil maintain client-side deployments due to limited DevOps engineering capacity for API-based re-architecture.
- Multi-Channel Tagging:Unified container governance across web, mobile application, and connected device endpoints.
- Mobile Tag Management:Native SDK-based data collection for iOS and Android application environments.
Server-Side Tagging commands the largest revenue pool, while Mobile Tag Management is expanding most quickly.
Application:
Customer type differentiation separates compliance-driven procurement from performance-optimized deployments across organizational maturity levels.
- Data Compliance:Granular consent-state orchestration and automated data-mapping documentation satisfy GDPR Article 82 liability exposure. Financial institutions in Germany and the Netherlands mandate compliance-centric deployments following Court of Justice of the European Union damages rulings.
- Web Analytics:Accurate marketing attribution and traffic source identification through centralized pixel deployment.
- Marketing Automation:Real-time audience segmentation and trigger-based campaign execution.
- Customer Experience:Journey analytics and personalization engine fueling.
- Conversion Optimization:A/B testing instrumentation and funnel analysis.
Data Compliance captures the steepest expansion trajectory, while Web Analytics retains the deepest installed base.
End User:
Supply concentration clusters around regulated verticals with the strictest audit and certification mandates.
- Financial Institutions:Banks, insurers, and payment processors require SOC 2 Type II attestation and contractual sub-processor audit rights. German and UK financial services procurement teams extend vendor onboarding cycles to verify automated consent-logging capabilities.
- Telecommunications:Mobile network operators and broadband providers face intensified GDPR enforcement for location data processing. French and Dutch telecommunications providers consolidate vendor relationships to reduce Article 82 liability exposure.
- Retailers:High-velocity promotional calendars demand edge-deployed containers for traffic surge resilience.
- Online Publishers:Advertising-dependent media properties balance revenue optimization against consent opt-out rate pressures.
- Travel Agencies:Cross-border booking platforms navigate fragmented consent requirements across departure and destination jurisdictions.
Financial Institutions anchor category revenue, while Telecommunications is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber-optic cable systems landing at Cork, Ireland, and Bilbao, Spain, underwrite Europe's data sovereignty infrastructure for tag management deployments. Frankfurt's internet exchange anchors continental traffic routing for financial services compliance workloads.
United States
California's Attorney General enforces the California Privacy Rights Act with escalating penalties for consent-logging failures. Retailers in Los Angeles and San Francisco deploy edge-computing containers to maintain attribution accuracy under Safari Intelligent Tracking Prevention. The state's technology procurement offices mandate SOC 2 Type II certification for SaaS tag management vendors serving state agencies.
Germany
BaFin-regulated financial institutions in Frankfurt and Munich require automated data-mapping documentation for GDPR Article 82 liability mitigation. The KBA enforces strict consent-state orchestration for automotive customer journey analytics. Bavaria's insurance technology clusters concentrate server-side tagging adoption for audit-ready governance.
United Kingdom
The Information Commissioner's Office intensifies enforcement against telecommunications providers processing location data without granular consent. London's financial services procurement teams extend vendor onboarding cycles to verify sub-processor audit rights. Manchester's retail technology hubs adopt hybrid cloud architectures for traffic surge resilience during promotional cycles.
France
CNIL enforcement actions expose enterprises to direct damages claims for unlawful data transfers under Court of Justice rulings. Paris-based banking groups mandate contractual audit rights over tag configurations. The Île-de-France region concentrates demand for automated consent-orchestration platforms among luxury goods marketers.
Brazil
ANPD enforcement against ad-tech intermediaries elevates demand for localized consent-management infrastructure. São Paulo's multinational consumer brands re-architect data collection to satisfy LGPD data minimization mandates. The city's retail technology procurement teams prioritize Portuguese-language governance dashboards for legal team accessibility.
Global Tag Management System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the governance and analytics adjacencies. The vendor base stratifies across three tiers: hyperscale cloud platforms with embedded marketing stacks, independent specialists with customer data platform adjacencies, and regional compliance-focused providers. Two strategic archetypes dominate: full-stack marketing cloud vendors leveraging creative suite integration, and pure-play tag management platforms differentiating through consent-orchestration depth. Competitive moves concentrate on M&A for consent-management capabilities and strategic partnerships with CDN edge-function providers.
Within the independent specialist tier, Tealium exemplifies the customer data platform convergence archetype, while Ensighten occupies a position emphasizing enterprise security certifications. Google anchors the hyperscale platform category through embedded distribution within advertising technology stacks.
| Leading Market Players |
|---|
| Adobe |
| Tealium |
| IBM Corporation |
| Oracle |
| Ensighten |
| Adform |
| Piwik PRO |
| Commanders Act |
| Others |
Supply & Pricing Matrix
Transatlantic fiber-optic cable systems landing at Cork, Ireland, and Bilbao, Spain, impose bandwidth cost dynamics that concentrate server-side tagging infrastructure investment in Frankfurt and London data centers, amplifying price differentiation between ISO 27001-certified providers and uncertified alternatives while compressing margins for mid-market SaaS vendors unable to negotiate enterprise-scale egress discounts.
Pricing Analysis
Volume-discount tiering structures dominate SaaS contracts, with consumption-based billing scaling from mid-market retailers to hyperscale financial institutions. Pricing stratifies across premium compliance tiers with SOC 2 Type II attestation, standard cloud-elastic tiers, and economy client-side tiers lacking consent-orchestration depth. Cost compression in the economy tier intensifies because browser cookie deprecation forces legacy clients toward unplanned server-side migrations. Financial institutions in Germany exhibit lowest price sensitivity due to Article 82 liability exposure, while online publishers in Brazil face acute budget constraints.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become critical for CDN edge-function providers serving traffic-spike retail calendars. Infrastructure concentration rests on Ireland, Germany, and the United Kingdom for EU data sovereignty compliance, with secondary compute clusters in Virginia and California serving North American workloads. Raw material dependencies span silicon photonics for transatlantic cables, specialized GPUs for edge inference, and lithium-ion storage for data center continuity. Single-source vulnerability runs through submarine cable landing stations. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server-side tagging architectures sit in early-cycle expansion as GDPR enforcement escalation and Safari Intelligent Tracking Prevention collectively force infrastructure re-architecture across retail and financial verticals.
For Market Incumbents: Entrench governance-automation capabilities through deeper consent-orchestration APIs that neutralize emerging pure-play specialists. Prioritize SOC 2 Type II certification maintenance to defend against ISO 27001-compliant challengers in financial services procurement. Extend sub-processor audit rights contractually to match Court of Justice liability rulings. For New Entrants and Emerging Players: Establish a beachhead in Brazil's LGPD-mandating consumer brand segment where localized Portuguese-language dashboards remain underserved. Target healthcare-adjacent HIPAA deployments in the United States where audit-ready tag governance commands compliance premiums. Pursue CDN edge-function partnerships as the primary go-to-market angle for sub-50-millisecond consent resolution. For Investors and Strategic Acquirers: Customer data platform convergence specialists with pre-built consent-management modules represent the most defensible acquisition archetype. Long-term viability hinges on differentiation depth in governance automation rather than bundled analytics bundling. Monitor ANPD enforcement action frequency as the inflection indicator for Latin American market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Consent-Orchestration Platform Launch | GDPR Article 82 rulings in France and the Netherlands mandate automated data-mapping documentation for liability mitigation. |
| CDN Edge-Function Partnership | Integration with Cloudflare or Fastly enables sub-50-millisecond consent resolution for Manchester retail technology hubs. |
| ISO 27001 Certification Investment | BaFin-regulated Frankfurt institutions require attestation for vendor onboarding, extending procurement cycles without it. |
| Healthcare-Adjacent Market Entry | HIPAA-covered entities in California need audit-ready tag governance for patient journey analytics. |
| Portuguese-Language Localization | São Paulo legal teams demand accessible governance dashboards under ANPD's escalating LGPD enforcement. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. Conversations with CTOs, IT procurement officers, platform engineers, and channel partners across Germany, the United Kingdom, and the United States were triangulated against SEC 10-K disclosures, hyperscaler capex reports, and ANPD enforcement databases. Bottom-up deployment estimates and top-down market sizing were reconciled through iterative calibration.
Calibration against historical adoption curves and regulatory enforcement timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, application purpose, end-user vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating server-side migration velocity and consent-management feature premiums.
Stress conditions across bandwidth cost volatility, GDPR penalty escalation, and engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about browser privacy API evolution and enforcement consistency. Macroeconomic contraction, regulatory fragmentation, or breakthrough privacy-preserving attribution technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Ediscovery Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
P2P Rental Apps Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
G2P Systems Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Data Governance Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Europe API Management Market
Digital Solutions
Canada ICT Market