
 Integrated Systems Market | 2026-2036
Integrated Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Systems Market Outlook
ISO/IEC 27001 certification is collapsing as a baseline market-access filter for enterprise integration contracts. Cisco Systems leverages its networking hardware dominance to anchor bundled security-automation offerings. Siemens differentiates through deep manufacturing domain expertise married to proprietary industrial IoT stacks.
Integrated systems combine heterogeneous hardware, software, and communication protocols into unified operational architectures governed by real-time data exchange standards such as OPC UA and MQTT. These architectures orchestrate physical infrastructure with digital control layers to optimize throughput, safety, and energy efficiency across facilities. Control systems and automation systems retain the largest installed base, though security systems command premium pricing as cyber-physical convergence deepens. Cloud computing and AI technology segments are expanding fastest where edge-to-cloud orchestration replaces siloed on-premise deployments.
FDA 21 CFR Part 820 quality system requirements shape healthcare integration timelines, while EU Cybersecurity Act baseline certification gates European critical infrastructure access. NIST SP 800-82 revision demands now drive utility-sector control system hardening in the United States. Stakeholders must weigh sovereign data residency mandates against cloud-native architecture investments when selecting integration partners.
Market Dynamics
Cyber-physical convergence is forcing control system vendors to embed security architectures directly into operational technology stacks, collapsing the traditional IT/OT boundary that once separated plant floor systems from enterprise networks.
Growth Catalysts
- EU Cybersecurity Act baseline certification:European critical infrastructure operators now face mandatory resilience requirements, accelerating procurement of pre-certified integrated platforms that bundle control and security functions.
- India's industrial corridor buildout:The Gujarat-Tamil Nadu corridor is generating concentrated demand for unified control platforms spanning power distribution, logistics, and manufacturing coordination.
- Edge-to-cloud orchestration:Manufacturing facilities are replacing siloed on-premise deployments with hybrid architectures that enable real-time analytics without abandoning deterministic control requirements.
Market Restraints
- Semiconductor supply concentration:Industrial-grade processors and networking chipsets face sourcing constraints from Taiwan and South Korea foundries, extending lead times for control system integrators.
- ISO/IEC 27001 certification collapse:The baseline security standard has lost discriminating power as a market-access filter, forcing vendors to absorb additional compliance costs without pricing power.
- Legacy protocol entrenchment:Proprietary fieldbus systems in installed industrial bases create technical friction for OPC UA migration, limiting retrofit market velocity.
Strategic Opportunities
- Smart city deployments in Southeast Asia:Vietnam, Indonesia, and Thailand are accelerating unified control platform procurement for traffic, energy, and water management coordination.
- AI-driven predictive maintenance convergence:Machine learning inference at the edge is creating new integration service revenue streams for systems integrators with manufacturing domain expertise.
- FDA 21 CFR Part 820 healthcare pathway:Quality system requirements for medical device manufacturing are opening specialized integration contracts for validated control environments.
Industry Challenges
- OT cybersecurity skill scarcity:Systems integrators face recruitment constraints for engineers fluent in both IEC 62443 standards and legacy PLC programming environments.
- NIST SP 800-82 compliance timelines:Utility-sector control system hardening requirements in the United States are extending project delivery cycles and tying up engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Systems Market |
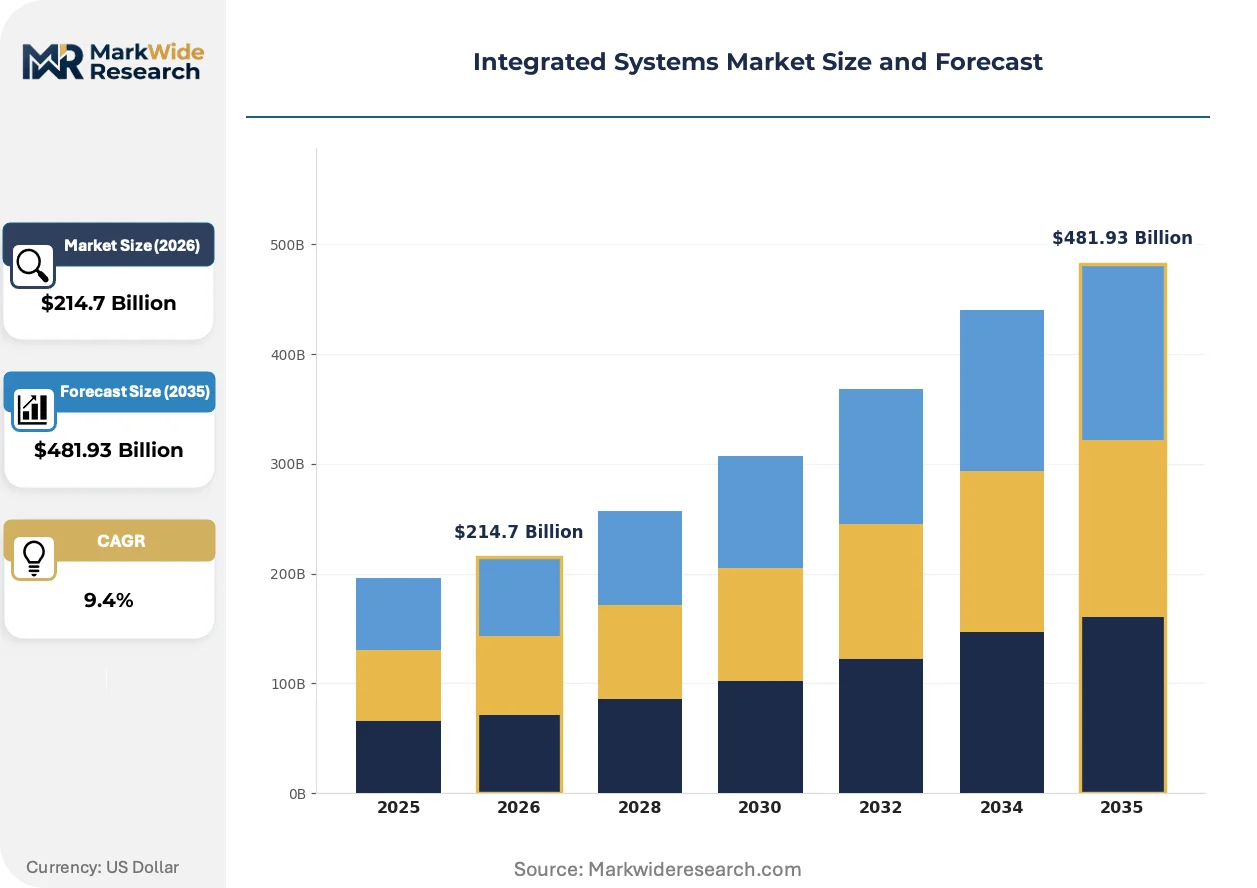
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $481.93 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Automation Systems, Security Systems, Display Systems Technology: IoT, AI, Machine Learning, Cloud Computing End User: Manufacturing, Transportation, Healthcare, Retail Application: Smart Buildings, Industrial Automation, Supply Chain Management, Smart Cities |
| Companies Covered | Accenture, Cisco Systems, IBM Corporation, Siemens, Honeywell International, Capgemini, Deloitte, Fujitsu, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Systems Market Strategic Shifts
MQTT-based lightweight messaging is displacing heavier industrial protocols in distributed sensor networks, enabling architectures that span geographically dispersed assets without dedicated leased lines.
Containerized edge runtime environments are displacing monolithic SCADA installations at manufacturing sites. Discrete and process industries are piloting Kubernetes-orchestrated control workloads that separate application logic from hardware dependencies. This approach is compressing capital requirements for multi-site standardization while complicating deterministic latency guarantees.
The EU AI Act risk classification framework is reshaping procurement specifications for autonomous control systems in European critical infrastructure. High-risk applications now require documented conformity assessment procedures that extend vendor liability upstream into algorithm training data provenance. Water treatment and energy distribution operators are responding by bifurcating procurement between certified AI-enabled platforms and deterministic rule-based alternatives.
Buyers are unbundling long-term service contracts from initial system deployment, compressing vendor revenue recognition timelines. Industrial end-users in Germany and Japan are adopting modular subscription models for security updates and remote monitoring that separate operational expenditure from capital budgets. This pattern is most pronounced in pharmaceutical manufacturing where FDA validation requirements create switching friction that vendors attempt to monetize through recurring compliance services.
Integrated Systems Market Segmentation
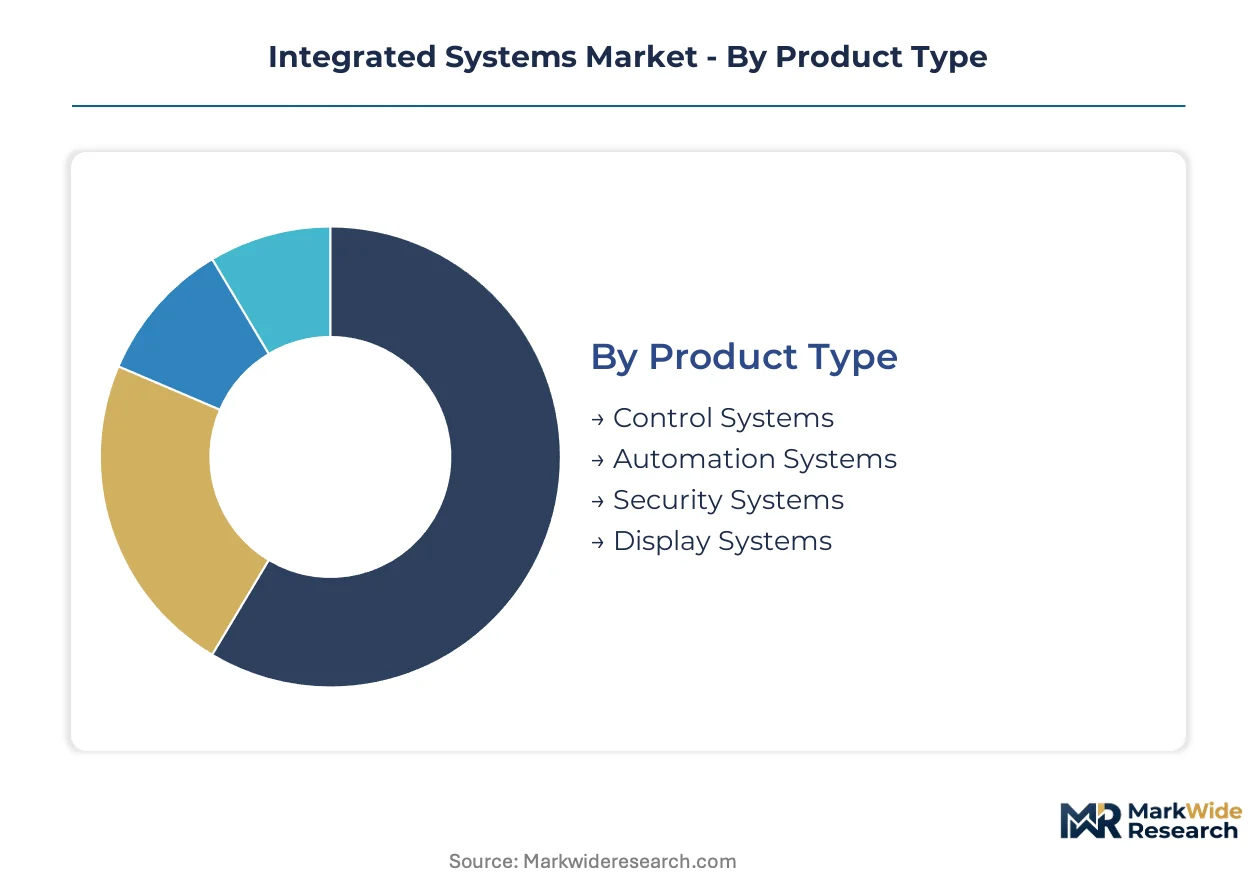
Integrated systems span heterogeneous technology stacks and deployment contexts, making granular segmentation essential for procurement strategy. Buyers face distinct integration complexity, certification requirements, and lifecycle cost profiles across product architectures and end-use environments.
Product Type:
Control systems face the strongest substitution pressure from cloud-native orchestration platforms that collapse traditional SCADA hierarchies into containerized workloads.
- Control Systems:These architectures govern deterministic process loops through PLCs, DCS platforms, and RTU networks, maintaining hard real-time constraints. Demand concentrates in India's Gujarat-Tamil Nadu industrial corridor where power distribution and manufacturing coordination require unified command layers. Semiconductor sourcing constraints from Taiwan and South Korea foundries extend lead times for industrial-grade processors.
- Automation Systems:Robotic work cells, motion control networks, and material handling orchestration define this segment, bridging mechanical execution with digital scheduling. German and Japanese pharmaceutical manufacturers are unbundling long-term service contracts into modular subscription models for security updates and remote monitoring. FDA 21 CFR Part 820 validation requirements create switching friction that vendors monetize through recurring compliance services.
- Security Systems:Cyber-physical defense layers embed IEC 62443 standards directly into OT stacks as the IT/OT boundary dissolves.
- Display Systems:Human-machine interface panels and centralized visualization consoles aggregate multi-source data streams for operator decision support.
Control systems anchor the volume base while automation systems gain share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive edge hardware from opex-weighted cloud subscriptions, reshaping vendor pricing power and customer budget allocation.
- IoT:Sensor networks, edge gateways, and protocol translation layers connect physical assets to digital control planes through MQTT and OPC UA standards. Smart city deployments across Vietnam, Indonesia, and Thailand are accelerating procurement of unified traffic, energy, and water management platforms.
- AI:Machine learning inference engines enable predictive maintenance and autonomous optimization, though EU AI Act risk classification now mandates documented conformity assessment for high-risk critical infrastructure applications.
- Machine Learning:Pattern recognition algorithms trained on operational telemetry generate anomaly detection and quality prediction capabilities.
- Cloud Computing:Distributed compute and storage resources support hybrid edge-to-cloud orchestration that replaces siloed on-premise deployments.
IoT retains the largest installed base while cloud computing expands most quickly where manufacturing facilities adopt hybrid architectures.
End User:
Application maturity varies sharply across verticals, with regulated environments imposing validation burdens that slow deployment velocity relative to commercial settings.
- Manufacturing:Discrete and process industries deploy integrated systems for throughput optimization, quality assurance, and energy efficiency across production lines. Containerized edge runtime environments are displacing monolithic SCADA installations as Kubernetes-orchestrated control workloads separate application logic from hardware dependencies.
- Healthcare:Medical device manufacturing and hospital infrastructure require validated control environments meeting FDA 21 CFR Part 820 quality system requirements. EU Cybersecurity Act baseline certification gates access for European critical infrastructure operators.
- Transportation:Logistics coordination, fleet management, and traffic control systems demand real-time data exchange across geographically dispersed assets.
- Retail:Supply chain visibility, inventory optimization, and customer experience orchestration drive adoption of lightweight messaging architectures.
Manufacturing dominates current deployment value while healthcare exhibits the steepest expansion trajectory as cyber-physical convergence deepens regulatory compliance spending.
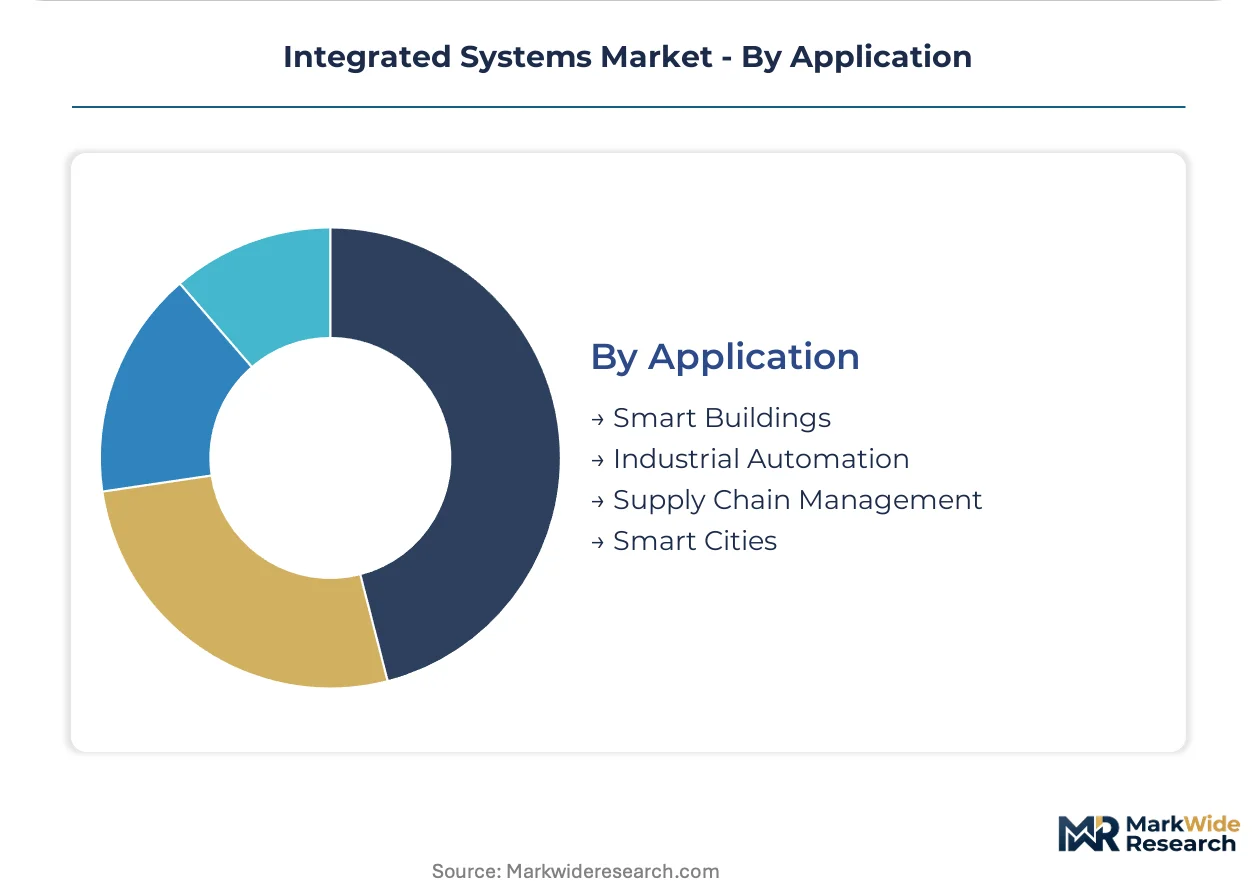
Application:
Customer procurement patterns bifurcate between greenfield smart city projects with consolidated vendor relationships and brownfield industrial sites grappling with legacy protocol entrenchment.
- Industrial Automation:Factory-floor integration of robotics, process control, and quality systems demands deterministic latency guarantees that complicate cloud-native migration. NIST SP 800-82 revision requirements drive utility-sector control system hardening in the United States, extending project delivery cycles.
- Smart Cities:Unified control platforms coordinate urban infrastructure spanning traffic management, energy distribution, and public safety networks. Southeast Asian governments in Vietnam, Indonesia, and Thailand are accelerating procurement ahead of infrastructure investment cycles.
- Smart Buildings:HVAC, lighting, and access control integration optimizes energy consumption and occupant experience in commercial and residential properties.
- Supply Chain Management:End-to-end visibility platforms track inventory, condition, and location across multi-modal logistics networks.
Industrial automation commands the largest current investment while smart cities climb the fastest as urbanization and infrastructure modernization converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Cybersecurity Act baseline certification accelerates procurement of pre-certified integrated platforms across European critical infrastructure operators. India's industrial corridor buildout generates concentrated demand for unified control systems spanning power distribution and manufacturing coordination. Smart city deployments in Vietnam, Indonesia, and Thailand accelerate unified control platform procurement for traffic, energy, and water management.
United States
NIST SP 800-82 revision requirements drive utility-sector control system hardening, extending project delivery cycles and tying up engineering resources. The FDA 21 CFR Part 820 quality system requirements shape healthcare integration timelines for medical device manufacturing. The Greater Boston corridor hosts specialized integration contracts for validated control environments in pharmaceutical manufacturing.
Germany
Industrial end-users in Bavaria and Baden-Württemberg adopt modular subscription models for security updates and remote monitoring that separate operational expenditure from capital budgets. The EU AI Act risk classification framework reshapes procurement specifications for autonomous control systems in critical infrastructure. The Rhine-Ruhr industrial cluster concentrates demand for Kubernetes-orchestrated control workloads that separate application logic from hardware dependencies.
India
The Gujarat-Tamil Nadu industrial corridor generates concentrated demand for unified control platforms spanning power distribution, logistics, and manufacturing coordination. The country's national industrial policy framework supports domestic manufacturing capabilities for control system components. The Delhi-Mumbai Industrial Corridor hosts integrated systems deployment for smart city infrastructure and logistics coordination.
Japan
Pharmaceutical manufacturers in the Kanto and Kansai regions unbundle long-term service contracts into modular subscription models for security updates and remote monitoring. METI standards guide industrial IoT stack development for manufacturing domain expertise applications. The Nagoya-Toyota industrial corridor concentrates demand for robotic work cells and motion control network integration.
Vietnam
Smart city deployments in Ho Chi Minh City and Hanoi accelerate procurement of unified control platforms for traffic management, energy distribution, and water management coordination. National infrastructure investment cycles prioritize integrated systems for urban modernization. The northern economic region concentrates manufacturing facility adoption of hybrid edge-to-cloud architectures.
Integrated Systems Market Competitive Environment
Player mix skews toward diversified technology conglomerates with networking hardware and industrial automation foundations. The vendor base clusters around three strategic archetypes: networking hardware specialists bundling security-automation offerings, industrial automation incumbents with proprietary IoT stacks, and systems integrators with manufacturing domain expertise. Dominant competitive moves include strategic partnerships for edge-to-cloud orchestration capabilities and portfolio diversification into AI-driven predictive maintenance services.
Within the networking-hardware-anchored tier, Cisco Systems exemplifies bundled security-automation offerings leveraging infrastructure dominance. Siemens occupies a position representing deep manufacturing domain expertise married to proprietary industrial IoT stacks. IBM Corporation sits within the systems integrator archetype, anchoring service-oriented positioning for enterprise integration contracts.
| Leading Market Players |
|---|
| Accenture |
| Cisco Systems |
| IBM Corporation |
| Siemens |
| Honeywell International |
| Capgemini |
| Deloitte |
| Fujitsu |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Cybersecurity Act baseline certification gates both supplier qualification and price differentiation simultaneously, forcing vendors to absorb compliance costs while buyers sort platforms by resilience tier. This regulatory filter compresses margins for uncertified players while concentrating pricing power among pre-certified integrators serving European critical infrastructure.
Pricing Analysis
Certification level (ISO/IEC 27001, EU Cybersecurity Act, FDA 21 CFR Part 820) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling security-automation modules and validated compliance documentation. Cost compression in standard tiers is intensifying because ISO/IEC 27001 has lost discriminating power as a market-access filter. Healthcare and pharmaceutical manufacturers exhibit the least price sensitivity due to FDA validation switching friction, while commercial smart building deployments show the highest elasticity.
Supply Chain Analysis
Taiwan and South Korea anchor industrial-grade processor and networking chipset fabrication for control system integrators. These components draw from specialty silicon wafers, advanced packaging substrates, and precision analog semiconductors. Single-source vulnerability concentrates in Taiwan foundry capacity, exposing lead time volatility for PLC and DCS hardware. Distribution runs through authorized systems integrator channels rather than direct OEM sales, with project-based procurement dominating brownfield industrial sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The integrated systems market is recovering from semiconductor supply constraints as foundry capacity normalizes and India's industrial corridor buildout sustains capital deployment. This cyclical driver supports margin restoration for vendors with qualified supplier networks.
For Market Incumbents: Shield installed base relationships by embedding IEC 62443 security architectures directly into OT stacks before cloud-native orchestration platforms collapse traditional SCADA hierarchies. Deepen backward integration into edge hardware manufacturing to offset Taiwan foundry concentration risk. Prioritize certification investment for EU Cybersecurity Act baseline compliance to maintain pricing power in European critical infrastructure.
For New Entrants and Emerging Players: Lead with AI-driven predictive maintenance convergence as the entry wedge, targeting Vietnam and Indonesia smart city deployments where unified control platform procurement is accelerating ahead of infrastructure investment cycles. Build go-to-market around Kubernetes-orchestrated containerized edge runtime environments that separate application logic from hardware dependencies, appealing to manufacturing facilities seeking multi-site standardization without deterministic latency trade-offs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native orchestration sub-segments as containerized workloads displace monolithic SCADA installations. Long-term viability favors systems integrators with manufacturing domain expertise and validated healthcare control environments over pure networking hardware plays. Watch for inflection in OPC UA migration velocity as the signal for retrofit market acceleration versus legacy protocol entrenchment.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Edge-to-cloud orchestration collapses siloed on-premise deployments for manufacturing coordination. |
| Strategic Partnership | Systems integrators ally with semiconductor distributors to secure Taiwan and South Korea foundry allocation. |
| Acquisition of Specialist Firm | Industrial automation incumbents purchase AI inference startups for predictive maintenance service expansion. |
| Geographic Expansion | Vendors establish integration centers along India's Gujarat-Tamil Nadu industrial corridor for localized deployment. |
| Product Launch | Pre-certified integrated platforms bundle control and security functions for EU Cybersecurity Act compliance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and industrial automation trade data. Control systems engineers, plant managers at discrete manufacturing facilities, procurement leads for power distribution utilities, and OT cybersecurity specialists provided structured input. Bottom-up sizing of installed base volumes triangulates against top-down expenditure analysis from national infrastructure investment frameworks.
Segmentation dimensions modeled span product architecture (control systems, automation systems, security systems, display systems), technology stack (IoT, AI, machine learning, cloud computing), end-use vertical (manufacturing, healthcare, transportation, retail), and application context (industrial automation, smart cities, smart buildings, supply chain management). CAGRs were derived from elasticity-adjusted demand curves across the projection horizon, incorporating edge-to-cloud migration velocity and regulatory compliance spending trajectories as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Cybersecurity Act implementation and FDA 21 CFR Part 820 quality system requirements; material policy shifts would require re-modeling. Semiconductor supply concentration, NIST SP 800-82 compliance timeline extensions, and EU AI Act risk classification enforcement present specific revision risks. Recalibration cycles align with material shifts in foundry capacity allocation and smart city procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
IT As a Service Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
AQI App Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Enterprise Manufacturing Intelligence Market