
 Engineering Information Management Solutions Market | 2026-2036
Engineering Information Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Information Management Solutions Market Intelligence
North American software vendors is consolidating around specialized engineering data platforms. Autodesk leverages cloud-native architecture to sustain R&D intensity across building and infrastructure workflows. Bentley Systems anchors its position through deep integration with civil engineering design standards. Oracle competes by extending enterprise database capabilities into asset lifecycle management for energy and utilities clients.
Engineering Information Management Solutions comprise software systems that capture, organize, version-control, and distribute technical documents, CAD files, and project data across distributed engineering teams. These platforms enforce metadata schemas, audit trails, and role-based access to ensure data integrity across multi-year capital projects. Document Management occupies the largest revenue pool as owner-operators mandate centralized repositories for regulatory submissions and handover packages. AI-driven segments represent the fastest-expanding category as machine learning automates document classification and extracts specifications from unstructured engineering drawings. Cloud-based delivery is displacing on-premises installations among mid-market construction firms seeking reduced IT overhead.
FDA 21 CFR Part 11 requirements shape validation protocols for life sciences engineering data, while ISO 19650 standards mandate structured information management across built-asset projects in Europe and Asia-Pacific. The EU AI Act introduces conformity obligations for automated decision-making in engineering workflows, compelling vendors to embed explainability features. Stakeholders must evaluate how emerging sustainability disclosure rules, including the EU CSRD, will expand documentation scope to encompass embodied carbon tracking and circular material passports within engineering information repositories.
Market Dynamics
Cloud migration is compressing deployment cycles for engineering information platforms as construction firms abandon multi-year on-premises implementations. The EU AI Act's conformity requirements are forcing vendors to rebuild algorithmic transparency into automated document classification workflows.
Growth Catalysts
- ISO 19650 Mandates:Structured information management requirements across built-asset projects in Germany, France, and the United Kingdom are compelling owner-operators to upgrade legacy document repositories.
- AI-Enabled Classification:Machine learning algorithms now extract specifications from unstructured engineering drawings, reducing manual indexing labor for infrastructure documentation teams.
- Industrial Digitization Programs:German automotive and manufacturing supply chains are driving platform upgrades through stringent documentation standards and cross-border collaboration requirements.
Market Restraints
- GDPR Data Localization:Cross-border engineering collaboration faces friction as EU member states enforce divergent interpretations of personal data handling in technical documentation systems.
- Legacy System Entrenchment:Decades of customized on-premises deployments create switching costs that delay cloud adoption among established industrial operators.
- Specialized Talent Scarcity:Shortage of professionals combining engineering domain knowledge with information architecture expertise constrains implementation velocity.
Strategic Opportunities
- EU CSRD Alignment:Sustainability disclosure rules expand documentation scope to encompass embodied carbon tracking and circular material passports within engineering repositories.
- Mid-Market Cloud Displacement:Construction firms with 500-2,000 employees represent an underserved segment seeking reduced IT overhead through SaaS delivery models.
- AI-Explainability Integration:Convergence of natural language processing with audit-trail engineering creates new product categories for regulatory-heavy verticals.
Industry Challenges
- FDA 21 CFR Part 11 Validation:Life sciences engineering data requires extensive protocol documentation that extends sales cycles and demands specialized compliance expertise.
- Multi-System Integration Complexity:Synchronizing metadata schemas across CAD, ERP, and asset management platforms creates implementation risk and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Information Management Solutions Market |
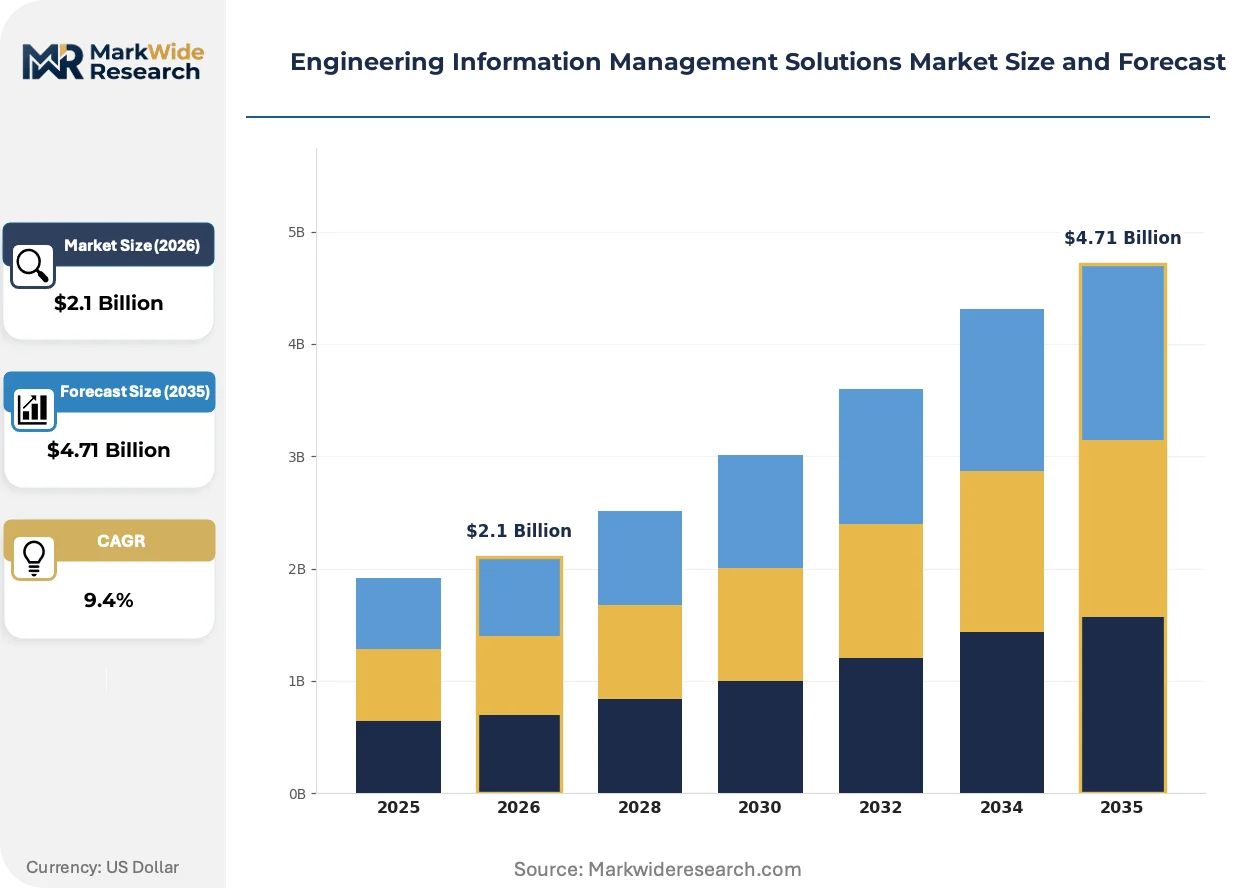
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Management, Project Management, Data Analytics, Workflow Automation Technology: Cloud-based, On-premises, Hybrid, AI-driven End User: Aerospace, Construction, Automotive, Manufacturing Application: Research & Development, Compliance Management, Risk Assessment, Quality Control |
| Companies Covered | Bentley Systems, Autodesk, Oracle, Aveva Group, Idox, Accruent, Asite, Newforma, Deltek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Information Management Solutions Market Strategic Shifts & Innovations
Generative AI is rewriting how engineering teams interact with technical documentation, shifting from keyword search to conversational query interfaces. This transformation is compressing information retrieval timelines and altering user training requirements.
Natural language processing engines are absorbing unstructured content from decades of scanned engineering drawings and specifications. Mid-market construction firms in Germany and the Netherlands are adopting these tools fastest, driven by ISO 19650 compliance deadlines. The technology is absorbing previously unsearchable document archives into queryable knowledge bases.
The EU AI Act introduces conformity obligations for automated decision-making in engineering workflows, compelling vendors to embed explainability features. Industrial software providers must now document algorithmic logic for regulators and clients. Document classification systems in life sciences and energy infrastructure face the steepest retrofit requirements.
Subscription pricing models are displacing perpetual licenses as the dominant procurement structure for engineering information platforms. EPC contractors and owner-operators in France and Spain are consolidating vendor relationships around integrated SaaS suites. This shift concentrates purchasing power with platform vendors while reducing customization flexibility for specialized engineering disciplines.
Engineering Information Management Solutions Market Segmentation
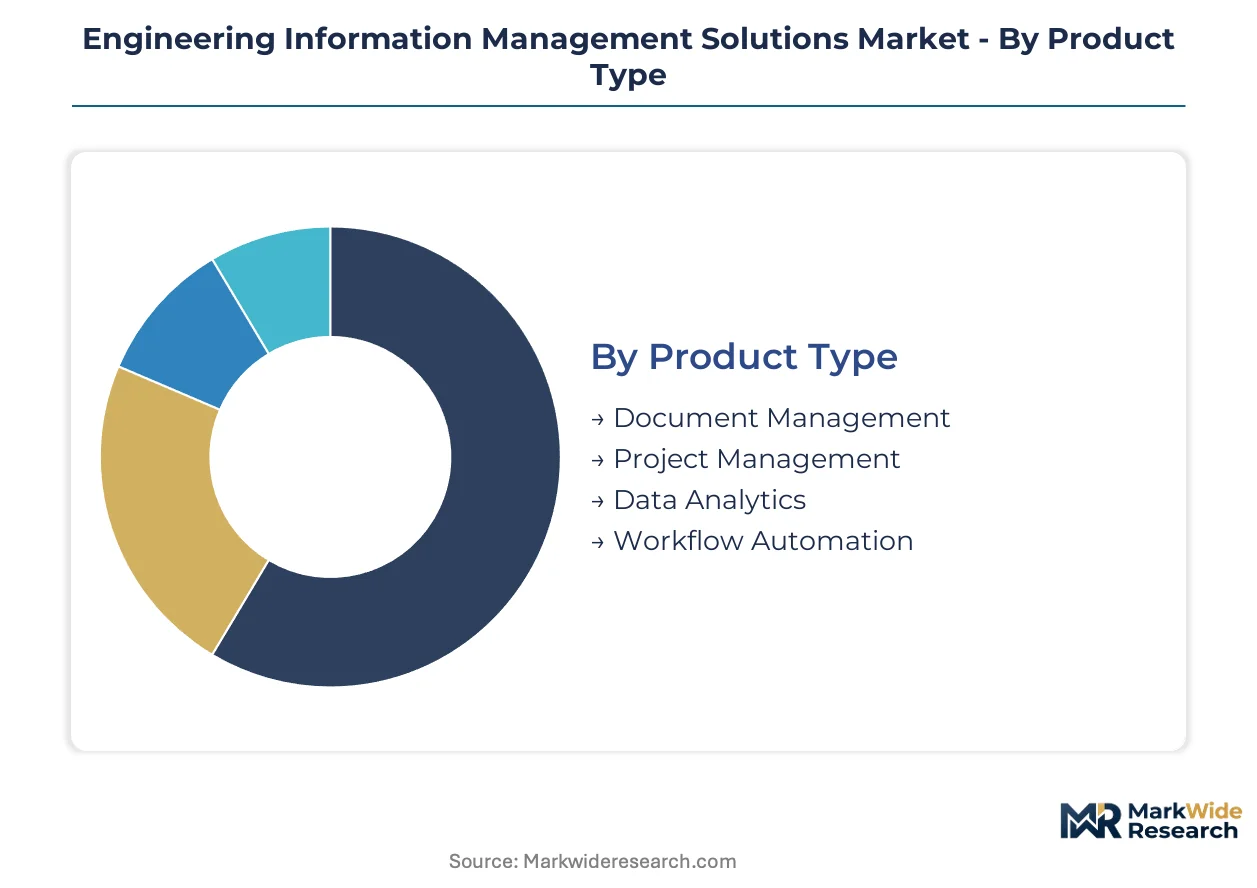
Engineering Information Management Solutions serve heterogeneous compliance regimes across product architectures, deployment modes, and industrial verticals. Segmentation reveals how certification burdens concentrate in specific technology tiers and end-use applications. Procurement patterns diverge sharply between regulated life sciences workflows and asset-heavy infrastructure operators.
Product Type:
FDA 21 CFR Part 11 validation protocols fall most heavily on document repositories handling electronic signatures and audit trails, while ISO 19650 compliance shapes project coordination platforms in European built-asset markets.
- Document Management:Centralized repositories enforce metadata schemas and version control across multi-year capital projects. Demand concentrates among German automotive OEMs and their tiered supply chains, where regulatory handover packages require immutable audit trails for homologation submissions. FDA and EU MDR documentation standards drive platform upgrades in life sciences manufacturing.
- Project Management:Coordination platforms synchronize distributed engineering teams across design, procurement, and construction phases. French and Spanish EPC contractors are consolidating vendor relationships around integrated SaaS suites that compress deployment cycles. ISO 19650 mandates in the United Kingdom and Netherlands accelerate displacement of legacy spreadsheet-based workflows.
- Data Analytics:Performance dashboards aggregate asset telemetry and project KPIs for executive decision-making. Embodied carbon tracking requirements under EU CSRD expand addressable scope for sustainability-focused deployments.
- Workflow Automation:Rule-based engines route approvals and notifications across organizational hierarchies. Mid-market construction firms in Germany adopt these tools to reduce administrative overhead without dedicated IT staff.
Leading the category by volume: Document Management. Growing fastest: Data Analytics.
Technology:
Deployment architecture determines cost structure, customization flexibility, and regulatory exposure for engineering data governance.
- Cloud-based:Multi-tenant SaaS delivery eliminates infrastructure capital expenditure and accelerates implementation timelines. Mid-market construction firms with 500-2,000 employees across France and Spain favor this model for reduced IT overhead. GDPR data localization requirements create friction as EU member states enforce divergent interpretations of cross-border technical documentation handling.
- On-premises:Installed software behind corporate firewalls satisfies air-gapped security requirements in defense and classified infrastructure projects. Legacy system entrenchment among established industrial operators delays displacement despite higher total cost of ownership.
- Hybrid:Mixed deployments synchronize sensitive design data locally while pushing collaboration layers to hosted environments. German automotive supply chains leverage this architecture to balance intellectual property protection with cross-border partner access.
- AI-driven:Machine learning engines automate document classification and extract specifications from unstructured engineering drawings. EU AI Act conformity obligations compel vendors to embed explainability features for automated decision-making workflows in energy infrastructure and life sciences verticals.
Volume leadership: Cloud-based. Steepest expansion trajectory: AI-driven.
End User:
Industry verticals impose distinct documentation standards, collaboration patterns, and technology maturity thresholds on platform selection.
- Aerospace:Long product lifecycles and stringent configuration management requirements dominate procurement criteria. FAA certification protocols and AS9100 quality standards mandate granular traceability across design evolution chains.
- Construction:Project-based delivery with fragmented subcontractor ecosystems drives demand for accessible, rapidly deployable coordination tools. German and Dutch mid-market firms adopt cloud platforms fastest under ISO 19650 compliance deadlines.
- Automotive:German OEMs and their tiered supply chains anchor regional demand through stringent documentation standards and cross-border collaboration requirements. KBA homologation processes require structured information handovers for type approval.
- Manufacturing:Discrete production environments prioritize integration with ERP and MES systems for closed-loop quality management. Industrial digitization programs across German federal states accelerate platform upgrade cycles.
Construction leads by deployment volume. Automotive shows the fastest technology refresh cycles.
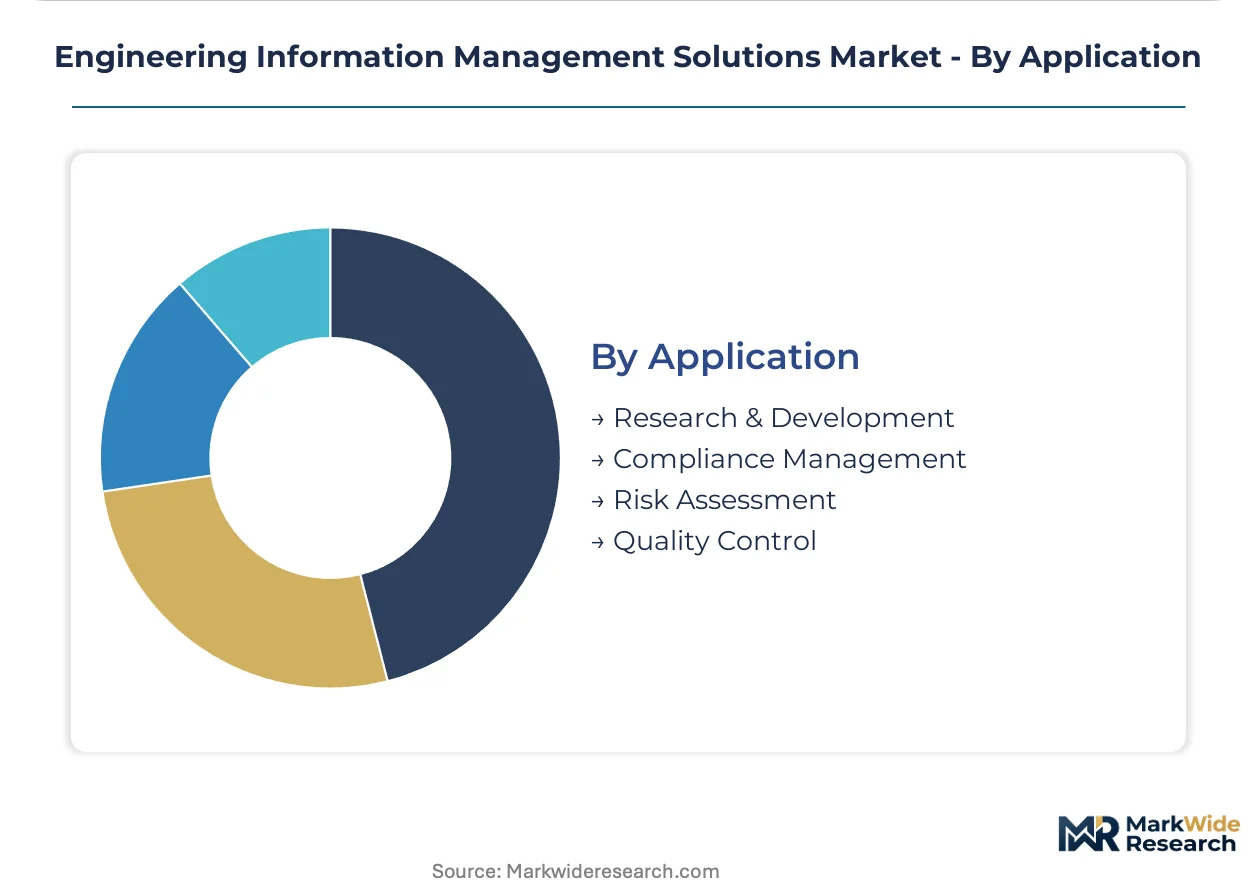
Application:
Functional use case determines integration depth, user training requirements, and regulatory validation burden for engineering information platforms.
- Research & Development:Iterative design environments require flexible versioning and rapid branching for experimental configurations. IP protection concerns favor hybrid or on-premises deployments in competitive technology sectors.
- Compliance Management:Structured information repositories support regulatory submission preparation and audit response. FDA 21 CFR Part 11 and EU MDR documentation standards shape validation protocols for life sciences engineering data.
- Risk Assessment:Hazard analysis documentation and mitigation tracking align with functional safety standards including IEC 61508 and ISO 26262 for automotive applications.
- Quality Control:Inspection records and non-conformance tracking integrate with statistical process control systems. Manufacturing execution system connectivity dominates procurement specifications.
Compliance Management leads by revenue concentration. Research & Development is climbing fastest as generative AI compresses information retrieval timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and their tiered supply chains anchor continental demand for structured documentation platforms. Industrial digitization programs across German federal states accelerate platform refresh cycles as KBA homologation processes mandate immutable audit trails for type approval submissions.
Germany
Automotive OEMs and their tiered supply chains drive platform upgrades through stringent documentation standards. KBA homologation processes require structured information handovers for type approval. Industrial digitization programs across Bavaria and Baden-Württemberg accelerate cloud migration among mid-market component suppliers.
United States
Defense contractors and energy infrastructure operators sustain demand for air-gapped security architectures. FAA certification protocols and AS9100 quality standards mandate granular traceability across design evolution chains. Aerospace clusters in Washington State and Texas prioritize configuration management for long product lifecycles.
United Kingdom
EPC contractors and owner-operators consolidate vendor relationships around integrated SaaS suites. ISO 19650 mandates accelerate displacement of legacy spreadsheet-based workflows. London-based engineering consultancies drive adoption of cloud-native coordination platforms for cross-border infrastructure projects.
France
Nuclear energy operators and pharmaceutical manufacturers impose stringent validation protocols on document repositories. ANSM documentation standards shape compliance management specifications for life sciences engineering data. EPC contractors in the Île-de-France region compress deployment cycles through SaaS procurement.
Netherlands
Mid-market construction firms adopt cloud platforms fastest under ISO 19650 compliance deadlines. Maritime engineering clusters in Rotterdam require hybrid deployments balancing intellectual property protection with partner collaboration. Dutch engineering consultancies pioneer generative AI integration for document classification workflows.
Engineering Information Management Solutions Market Key Industry Players
Global majors compete with regional champions across deployment architecture and vertical specialization. The vendor base organizes into three tiers: cloud-native platform builders, legacy system modernizers, and vertical-specific compliance specialists. Autodesk and Oracle anchor the top tier through enterprise database extensions and building workflow dominance. Bentley Systems occupies a distinct position in civil engineering design standards integration. Competitive moves concentrate on M&A for AI capabilities and strategic partnerships for mid-market channel access.
Within the cloud-native tier, Autodesk exemplifies platform breadth across building and infrastructure workflows. Oracle represents enterprise database extension into asset lifecycle management. Bentley Systems anchors specialized positioning through deep civil engineering standards integration. These three occupy positions that illustrate how competitive differentiation fragments across technical architecture, vertical depth, and compliance certification breadth.
| Leading Market Players |
|---|
| Bentley Systems |
| Autodesk |
| Oracle |
| Aveva Group |
| Idox |
| Accruent |
| Asite |
| Newforma |
| Deltek |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between FDA-validated repositories and standard document management platforms manifests in both pricing premiums and supply chain sourcing strategies, with German automotive OEMs paying substantial uplifts for KBA-homologation-ready systems while mid-market construction firms in France and Spain absorb compressed margins through SaaS procurement.
Pricing Analysis
Warranty and implementation service bundling separates premium-tier deployments from unbundled SaaS offerings, with validated systems for life sciences commanding substantial upfront professional services commitments. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden differentiation, with FDA 21 CFR Part 11 and EU AI Act conformity driving tier separation. Pricing pressure stems from subscription normalization as perpetual license revenue pools shrink. Mid-market construction firms exhibit highest price sensitivity, while defense contractors and pharmaceutical manufacturers demonstrate lowest elasticity due to validation protocol rigidity.
Supply Chain Analysis
EU data localization mandates under GDPR are reshaping sourcing patterns for cloud infrastructure and professional services delivery. Software development concentrates in the United States, Germany, and India, with implementation services drawing from regional engineering consultancies in France, the Netherlands, and the United Kingdom. Cloud compute dependencies rest on hyperscaler infrastructure with regional data residency requirements. Single-source vulnerability runs through specialized compliance certification bodies for FDA and EU MDR validation. Distribution runs through direct enterprise sales teams and systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing decades of customized on-premises deployments, compressing implementation timelines and altering vendor competitive dynamics across engineering information management.
For Market Incumbents: Deepen vertical integration into AI explainability tooling to preempt EU AI Act retrofit requirements. Consolidate channel partnerships with German automotive supply chain integrators to defend against emerging cloud-native entrants. Certification investment in ISO 19650 and FDA validation protocols remains the critical defensive lever.
For New Entrants and Emerging Players: The mid-market price-point gap between premium validated systems and basic document repositories offers substantial white-space opportunity. Target 500-2,000 employee construction firms in France and Spain seeking reduced IT overhead without enterprise-grade compliance burdens. Pursue generative AI-native positioning with conversational query interfaces as primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-enabled workflow automation specialists given EU regulatory catalysts mandating explainability features. Long-term viability favors platforms with embedded compliance certification breadth across FDA, EU MDR, and ISO 19650 standards. Watch for consolidation signals among mid-market SaaS vendors as subscription pricing normalization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Explainability Integration | EU AI Act conformity obligations compel algorithmic transparency retrofit across automated document classification workflows. |
| Mid-Market SaaS Expansion | Construction firms with 500-2,000 employees seek reduced IT overhead through subscription delivery models. |
| Compliance Certification Investment | FDA 21 CFR Part 11 and EU MDR validation protocols extend competitive moats in life sciences verticals. |
| Strategic Partnership with Systems Integrators | German automotive supply chains demand localized implementation expertise for KBA homologation support. |
| Generative AI Platform Development | Natural language processing engines transform decades of scanned engineering drawings into queryable knowledge bases. |
Research Approach
SEC filings, EU regulatory databases, and hyperscaler capex disclosures formed the secondary backbone, supplemented by primary interviews with engineering information management vendors, CTOs at EPC contractors, and IT procurement officers at German automotive OEMs. Bottom-up and top-down triangulation validated segment-level estimates against enterprise deployment disclosures and channel partner feedback.
Bottom-up modeling aggregated individual customer archetype adoption curves while top-down analysis cross-referenced total addressable market boundaries against infrastructure investment patterns. Deployment model, organization size, vertical specialization, and regional regulatory cluster dimensions structured the segmentation framework. CAGRs derived from fitted growth curves incorporating cloud displacement velocity and compliance mandate timelines. AI adoption rates and ISO 19650 implementation deadlines served as industry-specific forecast inputs throughout the projection horizon.
Inputs from vendor financial disclosures and regulatory filing databases were available through the study window; gaps in privately held mid-market firm deployment data introduce uncertainty bands around SaaS penetration estimates. Forecasts reflect documented assumptions regarding cloud migration velocity and compliance deadline adherence. Regulatory enforcement variability and macroeconomic IT budget compression represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Workflow Management System Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
System Integrator Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Digital Shelf Market
Digital Solutions
OTA Transmission Platform Market