
 Global Remote Monitoring and Management (RMM) Tools Market | 2026-2036
Global Remote Monitoring and Management (RMM) Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Remote Monitoring and Management (RMM) Tools Market Foresight
India is tilting toward cloud-native infrastructure build-outs as its IT outsourcing corridors scale distributed workforce management. Kaseya VSA leverages extensive channel partnerships across North American mid-market IT services. NinjaOne anchors its position through a unified platform architecture that collapses endpoint monitoring and ticketing into single-pane workflows. Datto RMM sustains competitive relevance with deep backup continuity integration alongside core monitoring functions.
Remote Monitoring and Management tools constitute software platforms that continuously collect telemetry from endpoints, networks, and servers through lightweight agent deployments, then centralize alerting, patch orchestration, and remote remediation through policy-driven automation engines. Their primary commercial purpose is to reduce mean time to resolution for IT incidents while enabling proactive maintenance across geographically dispersed infrastructure. Cloud-based deployment dominates new procurement as organizations abandon on-premise server dependencies for elastic SaaS delivery models. Endpoint Management captures concentrated margin pools where patch compliance and device hardening intersect with cyber insurance requirements. Automation Tools represent the fastest-expanding solution category as IT labor scarcity drives scripted remediation and self-healing workflow adoption.
FCC guidelines on communications infrastructure reliability shape network monitoring requirements for telecommunications deployments in the United States. GDPR data residency provisions in Europe constrain cloud-based RMM architectures, compelling vendors to offer regional data segregation and encryption standards. ISO 27001 certification has become a baseline procurement filter for financial services buyers evaluating vendor security postures. Stakeholders must weigh the trade-off between centralized platform consolidation and modular best-of-breed specialization as buyer sophistication fragments across MSP tiers and enterprise IT operations.
Market Dynamics
The EU AI Act is forcing algorithmic transparency requirements into automated endpoint management workflows, compelling vendors to rearchitect policy engines and audit trails across distributed infrastructure deployments.
Growth Catalysts
- GDPR Data Residency Mandates:European financial services buyers now require regional data segregation, expanding demand for EU-sovereign cloud RMM architectures with localized encryption standards.
- IT Labor Scarcity:North American MSPs are accelerating scripted remediation adoption as technician hiring gaps widen, driving self-healing workflow procurement across mid-market service desks.
- India's IT Outsourcing Corridors:Hyderabad and Bangalore hubs are scaling hybrid deployment RMM suites to manage distributed workforce endpoints across global client environments.
Market Restraints
- Input Cost Volatility:Cloud infrastructure pricing from hyperscale providers creates margin pressure on SaaS-native RMM vendors operating thin subscription models.
- Supply Concentration Risk:Endpoint agent telemetry processing relies heavily on US-West and EU-Central data center clusters, creating geographic resilience vulnerabilities.
- Technical Limitation:Legacy Windows Server environments resist cloud-native agent deployment, fragmenting management coverage in industrial control and healthcare IT settings.
Strategic Opportunities
- Underpenetrated Manufacturing Vertical:German and Japanese industrial automation clusters show minimal RMM adoption for operational technology convergence, presenting greenfield endpoint monitoring demand.
- Zero Trust Architecture Convergence:Integration of continuous device posture verification with access policy enforcement is hybridizing RMM platforms into identity-security stacks.
- India's PLI Scheme:Electronics manufacturing incentives are spawning domestic IT hardware production, creating localized endpoint fleets requiring indigenous RMM support infrastructure.
Industry Challenges
- Certification Timeline Compression:ISO 27001 and SOC 2 Type II audit cycles now exceed 12 months, delaying vendor qualification for financial services procurement pipelines.
- Multi-Tenant Architecture Complexity:MSPs struggle to isolate client data streams while maintaining unified policy orchestration across thousands of heterogeneous endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Remote Monitoring and Management (RMM) Tools Market |
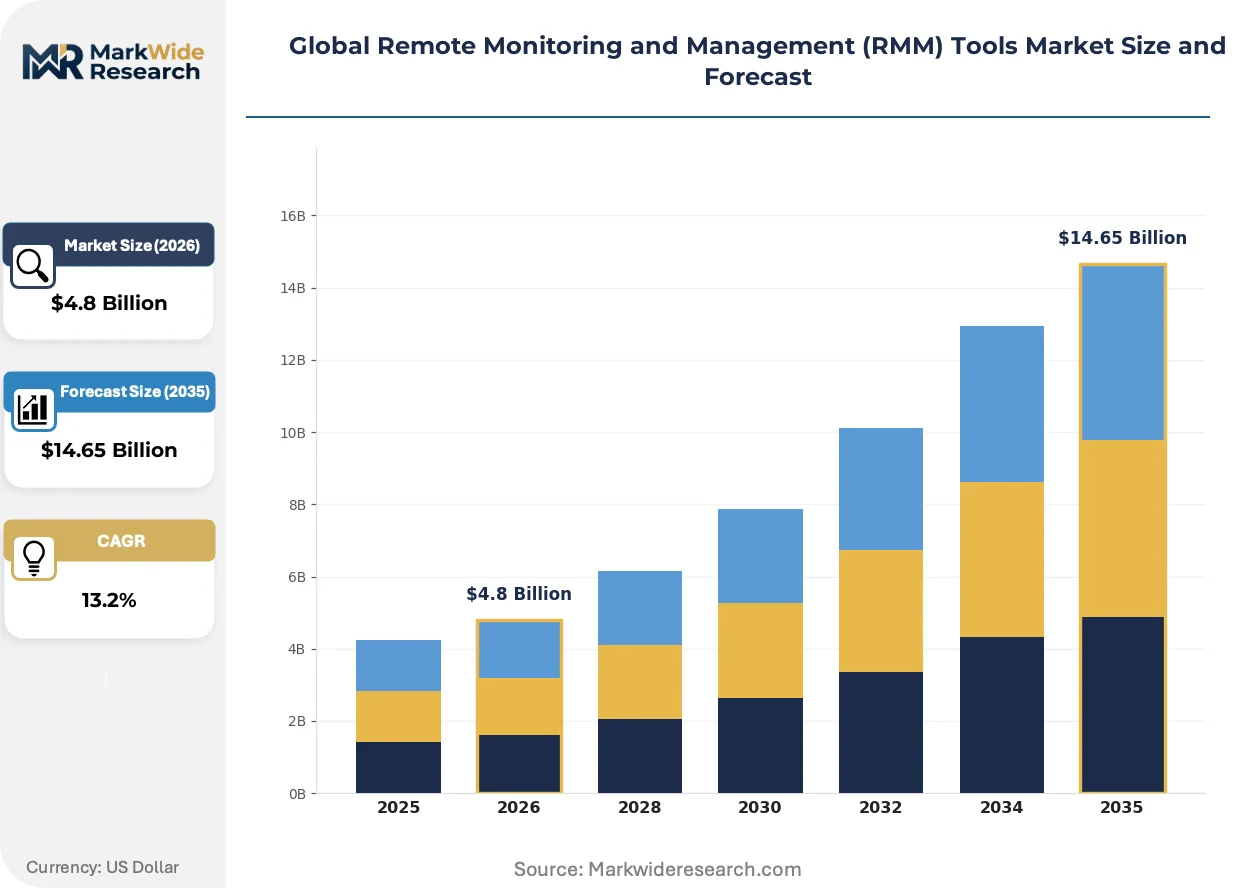
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $14.65 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Mode: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Type: Network Monitoring, Endpoint Management, Patch Management, Automation Tools End User Type: Managed Service Providers, IT Operations Teams, System Administrators, Technology Consultancies Industry Application: Telecommunications, Financial Services, Education Institutions, Government Agencies |
| Companies Covered | Atera, Datto RMM, NinjaOne, Auvik, ITarian, Kaseya VSA, N-able RMM, Syncro, ConnectWise Automate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Remote Monitoring and Management (RMM) Tools Market Shifts & Advancements
Automation engines are embedding predictive capabilities that compress incident response from hours to minutes. Vendors are racing to unify telemetry pipelines across cloud, on-premise, and edge infrastructure. The competitive frontier now centers on policy orchestration depth rather than monitoring breadth alone.
Agentless telemetry collection is hybridizing with lightweight endpoint agents to reduce deployment friction in regulated healthcare and financial environments. US hospital systems and EU banking IT departments are piloting these blended architectures to satisfy HIPAA and GDPR audit requirements simultaneously. This convergence is collapsing the traditional boundary between network monitoring and endpoint management product categories.
The EU AI Act's algorithmic transparency mandates are reshaping automated remediation workflows across European MSP operations. Vendors must now document decision pathways for patch prioritization and alert escalation, adding compliance overhead to previously opaque policy engines. German and French IT service providers are responding by demanding vendor-supplied audit trails as standard procurement terms.
Subscription bundling is displacing per-endpoint pricing as the dominant commercial structure among North American mid-market buyers. MSPs now negotiate platform-wide licenses covering monitoring, ticketing, and backup continuity as consolidated monthly fees. This preference shift is most visible in US healthcare and professional services verticals, where procurement teams prioritize predictable operational expenditure over granular usage-based billing.
Global Remote Monitoring and Management (RMM) Tools Market Segmentation
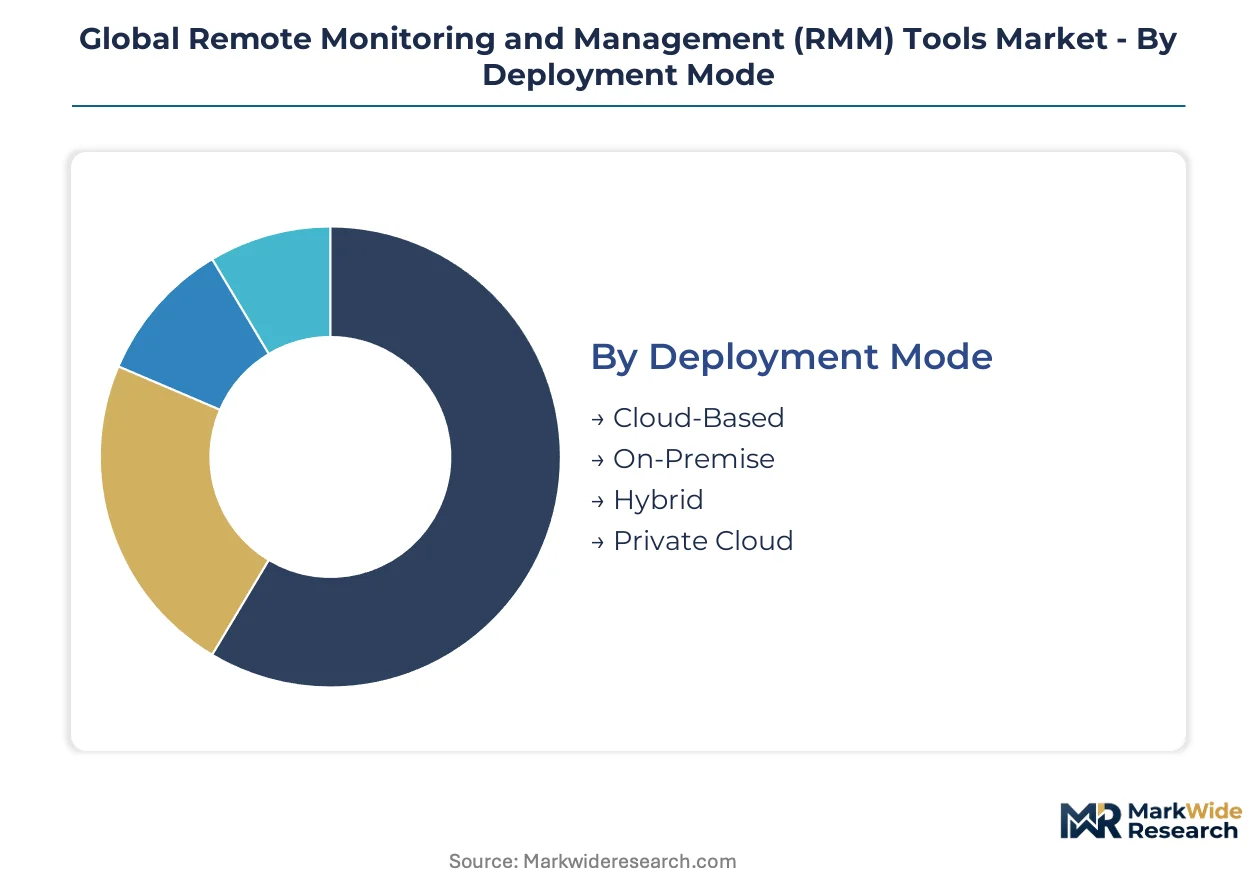
RMM tool procurement patterns fragment sharply across deployment architectures and buyer sophistication tiers. Vendor product roadmaps must reconcile elastic cloud delivery with hardened on-premise requirements that persist in regulated verticals. Understanding segment velocity reveals where platform investments concentrate versus where modular point solutions still capture margin.
Deployment Mode:
Cloud-based deployments turn over fastest as SaaS-native buyers cycle through quarterly platform evaluations, while on-premise commitments extend across multi-year capital depreciation schedules. Hybrid architectures exhibit intermediate replacement cycles driven by infrastructure refresh timelines.
- Cloud-Based:Elastic SaaS delivery eliminates server maintenance overhead while enabling automatic feature updates through continuous deployment pipelines. North American MSPs are consolidating procurement around cloud-native platforms to reduce data center footprint and accelerate endpoint onboarding. GDPR Article 44 cross-border transfer restrictions are forcing European buyers to demand EU-sovereign cloud instances with localized encryption key management.
- On-Premise:Dedicated server installations within customer-controlled facilities preserve complete data sovereignty and enable deep customization of policy orchestration engines. German automotive manufacturers and Japanese precision engineering firms maintain on-premise RMM stacks to satisfy operational technology network segmentation requirements. Capital expenditure approval cycles and hardware procurement lead times extend deployment timelines substantially.
- Hybrid:Split architectures route sensitive telemetry through on-premise collectors while leveraging cloud analytics for capacity-intensive processing workloads. Financial services buyers in Singapore and Switzerland deploy hybrid models to satisfy data residency mandates without sacrificing machine-learning-driven anomaly detection.
- Private Cloud:Single-tenant cloud infrastructure dedicated to individual organizations combines SaaS operational simplicity with isolated resource pools. Australian healthcare networks and Canadian provincial government IT departments favor private cloud RMM to maintain HIPAA and PIPEDA compliance without managing physical server estates.
Cloud-based deployment anchors the volume base while hybrid configurations gain share at the steepest rate as regulated industries seek architectural compromise.
Solution Type:
Automation tools command premium pricing tiers due to scarce engineering talent, while network monitoring functions commoditize fastest under open-source telemetry standard pressure. Patch management occupies a mid-tier cost position tied to cyber insurance compliance mandates.
- Network Monitoring:Continuous packet inspection and flow analysis across routers, switches, and wireless access points with threshold-based alerting for bandwidth saturation. Telecommunications carriers in India and Brazil deploy network-centric RMM modules to satisfy infrastructure reliability regulations while managing distributed cell tower fleets. FCC network reliability guidelines in the United States shape feature requirements for carrier-grade deployments.
- Endpoint Management:Unified device inventory, configuration enforcement, and security posture verification across heterogeneous workstation and mobile fleets. Endpoint Management captures concentrated margin pools where patch compliance and device hardening intersect with cyber insurance requirements. K-12 school districts and higher education institutions prioritize endpoint-centric platforms to manage bring-your-own-device chaos.
- Patch Management:Automated vulnerability scanning, patch availability correlation, and staged deployment orchestration with rollback capabilities. Healthcare IT departments in the United Kingdom and France prioritize patch management modules to satisfy NHS Digital and ANSSI security baseline requirements.
- Automation Tools:Scripted remediation, self-healing workflow engines, and predictive incident response that compress mean time to resolution without human intervention. Automation Tools represent the fastest-expanding solution category as IT labor scarcity drives scripted remediation adoption across North American mid-market service desks.
Network Monitoring anchors the volume base while Automation Tools climb the fastest as technician hiring gaps widen across MSP operations.
End User Type:
Managed Service Providers exhibit the shortest procurement cycles as competitive pressure forces quarterly platform evaluations, while government agencies extend vendor relationships across multi-year framework agreements. Technology consultancies occupy a middle position with project-driven purchasing patterns.
- Managed Service Providers:Multi-tenant platform operators managing thousands of heterogeneous client endpoints through centralized policy orchestration and white-labeled service delivery. MSPs in Hyderabad and Bangalore are scaling hybrid deployment RMM suites to manage distributed workforce endpoints across global client environments.
- IT Operations Teams:Internal enterprise technology groups responsible for infrastructure reliability within single-organization contexts with dedicated budget authority. IT Operations Teams in German automotive and Japanese industrial conglomerates favor on-premise deployments to maintain operational technology network isolation.
- System Administrators:Individual technical practitioners managing smaller endpoint fleets with limited procurement authority and preference for lightweight, rapidly deployable tools. System Administrators in educational institutions and nonprofit organizations prioritize open-source-integrated RMM platforms with minimal licensing friction.
- Technology Consultancies:Project-based advisory firms deploying temporary monitoring infrastructure during digital transformation engagements or post-merger integration programs. Technology Consultancies in London and New York bundle RMM platforms into broader managed services offerings for private equity portfolio companies.
Managed Service Providers anchor the volume base while Technology Consultancies expand most quickly as advisory firms deepen operational technology service lines.
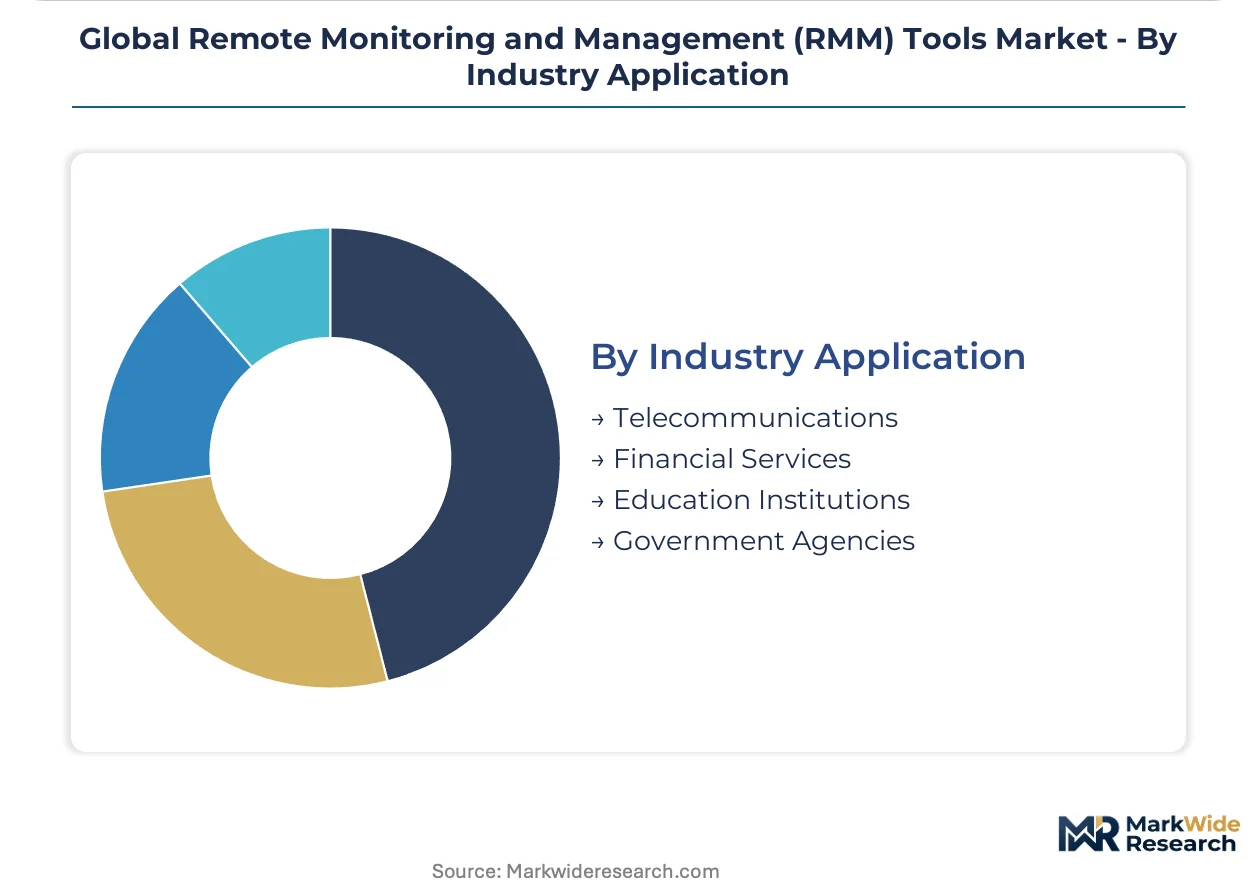
Industry Application:
Financial Services procurement cycles compress under regulatory examination pressure, while Education Institutions extend replacement timelines across annual budget cycles. Government Agencies exhibit the longest sales cycles due to security clearance and framework compliance requirements.
- Telecommunications:Carrier-grade infrastructure monitoring for cell towers, fiber backhaul, and customer premise equipment with five-nines reliability requirements. Telecommunications deployments in the United States face FCC guidelines on communications infrastructure reliability that shape network monitoring feature specifications.
- Financial Services:Hardened endpoint monitoring for trading floors, branch networks, and mobile banking infrastructure with real-time fraud correlation. European financial services buyers now require regional data segregation, expanding demand for EU-sovereign cloud RMM architectures with localized encryption standards. ISO 27001 certification has become a baseline procurement filter for financial services buyers evaluating vendor security postures.
- Education Institutions:Heterogeneous device management across student, faculty, and administrative fleets with limited cybersecurity staffing and constrained capital budgets. Education Institutions in Australia and Canada prioritize cloud-based RMM to eliminate server maintenance overhead while supporting hybrid learning models.
- Government Agencies:Classified and unclassified network segmentation with mandatory FedRAMP or equivalent national certification and domestic data residency. Government Agencies in France and Germany demand vendor-supplied audit trails as standard procurement terms under EU AI Act algorithmic transparency mandates.
Financial Services anchors the volume base while Telecommunications shows the steepest expansion trajectory as 5G infrastructure build-outs accelerate endpoint monitoring requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure build-outs concentrate RMM procurement in three distinct geographies. The United States anchors SaaS-native platform adoption. Germany and India emerge as high-velocity secondary markets with divergent regulatory drivers.
United States
FCC guidelines on communications infrastructure reliability mandate network monitoring capabilities for telecommunications carriers. Mid-market MSPs consolidate procurement around cloud-native platforms to eliminate data center overhead. Dallas and Austin technology corridors host dense concentrations of service providers scaling automated endpoint management.
Germany
Automotive manufacturers and precision engineering firms demand on-premise deployments for operational technology isolation. The EU AI Act compels algorithmic transparency in automated remediation workflows. Stuttgart and Munich industrial clusters maintain hardened RMM stacks for production line network segmentation.
India
Hyderabad and Bangalore outsourcing hubs scale hybrid deployment suites to manage distributed workforce endpoints across global client environments. The PLI scheme for electronics manufacturing spawns domestic hardware production requiring indigenous support infrastructure. TRAI regulations on data localization shape vendor selection criteria.
United Kingdom
Financial services buyers in London prioritize ISO 27001 certification as a baseline procurement filter. GDPR Article 44 cross-border transfer restrictions force EU-sovereign cloud instance demands. Technology consultancies bundle RMM platforms into private equity portfolio services.
Japan
METI industrial policy promotes operational technology convergence in manufacturing automation clusters. Healthcare IT departments pilot agentless telemetry architectures to satisfy audit requirements. Nagoya and Osaka precision engineering firms resist cloud-native agent deployment in legacy Windows Server environments.
Global Remote Monitoring and Management (RMM) Tools Market Competitive Landscape
Platform consolidators and modular specialists split the market into distinct competitive spheres. Consolidated platform vendors capture multi-tenant MSP relationships through unified workflow architectures. Modular point-solution providers defend margin in specialized endpoint security and network telemetry niches. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and geographic expansion through channel partner ecosystems.
Within the unified-platform tier, Kaseya VSA and NinjaOne exemplify consolidation strategies that collapse monitoring, ticketing, and automation into single-pane workflows. Datto RMM occupies a position emphasizing backup continuity integration alongside core monitoring functions. These three vendors represent divergent approaches to the same fundamental buyer demand for reduced operational complexity.
| Leading Market Players |
|---|
| Atera |
| Datto RMM |
| NinjaOne |
| Auvik |
| ITarian |
| Kaseya VSA |
| N-able RMM |
| Syncro |
| ConnectWise Automate |
| Others |
Supply & Pricing Matrix
Overcapacity in US-West hyperscale data centers is compressing cloud infrastructure margins and forcing SaaS-native RMM vendors toward aggressive subscription bundling to preserve customer lifetime value against churn pressure.
Pricing Analysis
GDPR Article 44 cross-border transfer restrictions dictate the pricing tier structure across European procurement. Three-tier pricing separates EU-sovereign cloud instances with localized encryption from standard global deployments and entry-level on-premise licensing. ISO 27001 certification commands premium positioning in financial services verticals. Pricing pressure stems from hyperscale infrastructure cost volatility squeezing SaaS margins. Mid-market MSPs exhibit highest price sensitivity while enterprise IT operations prioritize compliance-grade tiers regardless of cost.
Supply Chain Analysis
Cloud compute capacity feeds from hyperscale providers concentrated in the United States, Ireland, and Singapore. Endpoint agent telemetry processing draws from proprietary data center clusters and third-party colocation facilities. Single-source vulnerability in US-West infrastructure creates geographic resilience risk for global MSP operations. Distribution runs through direct vendor sales teams, channel partner ecosystems, and technology consultancies bundling platforms into broader service offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American mid-market MSPs consolidating vendor relationships around unified platforms, fragmenting pricing leverage across modular point-solution providers.
For Market Incumbents: Pre-empt cloud-native challenger encroachment by hardening multi-tenant data isolation architectures and accelerating EU-sovereign instance deployment ahead of GDPR enforcement tightening. Channel partner exclusivity agreements in Hyderabad and Bangalore outsourcing corridors defend against regional specialist emergence. Certification investment in FedRAMP and ISO 27001 maintains procurement gatekeeping in government and financial services verticals. For New Entrants and Emerging Players: German and Japanese manufacturing automation clusters present minimal incumbent penetration for operational technology convergence solutions. Agentless telemetry architectures bypass legacy Windows Server deployment friction in healthcare and industrial control settings. Go-to-market through technology consultancies bundling RMM into private equity portfolio services sidesteps direct MSP channel conflict. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native automation tool development as open-source telemetry standards commoditize network monitoring functions. Acquisition targets should demonstrate sticky multi-tenant MSP relationships with annual contract value expansion above category median. The signal to watch is hyperscale provider vertical integration into endpoint management adjacent services.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Sovereign Cloud Instance Deployment | GDPR Article 44 compliance unlocks financial services procurement pipelines in Frankfurt and Paris. |
| Agentless Telemetry Architecture Development | HIPAA audit satisfaction expands addressable market in US hospital systems resisting agent deployment. |
| Channel Partner Ecosystem Expansion | Hyderabad and Bangalore density captures India's IT outsourcing corridor procurement concentration. |
| ISO 27001 Certification Acceleration | Baseline procurement filter satisfaction opens London financial services buyer segments. |
| Automation Engine Predictive Capability Investment | IT labor scarcity compression drives self-healing workflow premium pricing in North American MSPs. |
Research Methodology
Operator-level perspectives from MSP platform engineers, IT procurement officers, channel partnership directors, and endpoint security architects anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie platform adoption metrics, and GPO contract databases. Bottom-up endpoint deployment estimates and top-down SaaS revenue aggregation triangulated market sizing across deployment modes and solution types.
Scenario-bracketing framed demand projections across the analysis window, modeling cloud adoption velocity, hybrid architecture persistence in regulated verticals, and automation tool penetration by organization size. Segmentation dimensions included deployment architecture, solution category, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from historical platform subscription growth rates, endpoint fleet expansion trajectories, and labor scarcity-driven automation substitution elasticities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale providers into adjacent endpoint management services would shift outcomes. Cross-checking against hyperscaler partnership disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
File Sharing Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Utility Cases Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Europe ICT Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Online Dating Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Device As a Service (Daas) Market
Digital Solutions
Contactless Ticketing Solutions Market