
 G2P Systems Market | 2026-2036
G2P Systems Market Size, Share, and Industry Trends Forecast 2026-2036
G2P Systems Market Analytics
The convergence of AI-driven orchestration software with modular robotic hardware is rewriting how fulfillment centers architect their material flow. Symbotic leverages its proprietary software stack to control end-to-end warehouse automation for mass retail clients. Daifuku anchors its position through deep manufacturing scale in automated storage and retrieval systems across Asia-Pacific installations. AutoStore differentiates via its ultra-dense cube-based storage topology that minimizes warehouse footprint.
Goods-to-person (G2P) systems comprise automated material handling technologies that retrieve inventory from storage and deliver it to stationary human or robotic pick stations, typically achieving throughput rates of 300–1,000 picks per hour depending on robot density and software optimization. These systems eliminate unproductive worker travel time in distribution centers and manufacturing facilities. Integrated platforms currently command the strongest margin pools as buyers prioritize unified control over disparate hardware fleets. Cloud-based deployment models are expanding fastest among mid-market enterprises seeking to avoid capital-intensive infrastructure commitments.
The EU AI Act classifies certain autonomous warehouse robots as high-risk AI systems, imposing conformity assessments that directly shape product development roadmaps for vendors serving European customers. OSHA in the United States enforces machine guarding and collaborative robot safety standards that influence G2P system design and site certification timelines. Stakeholders must monitor how evolving liability frameworks for autonomous systems reshape procurement criteria and vendor qualification processes across major deployment geographies.
Market Dynamics
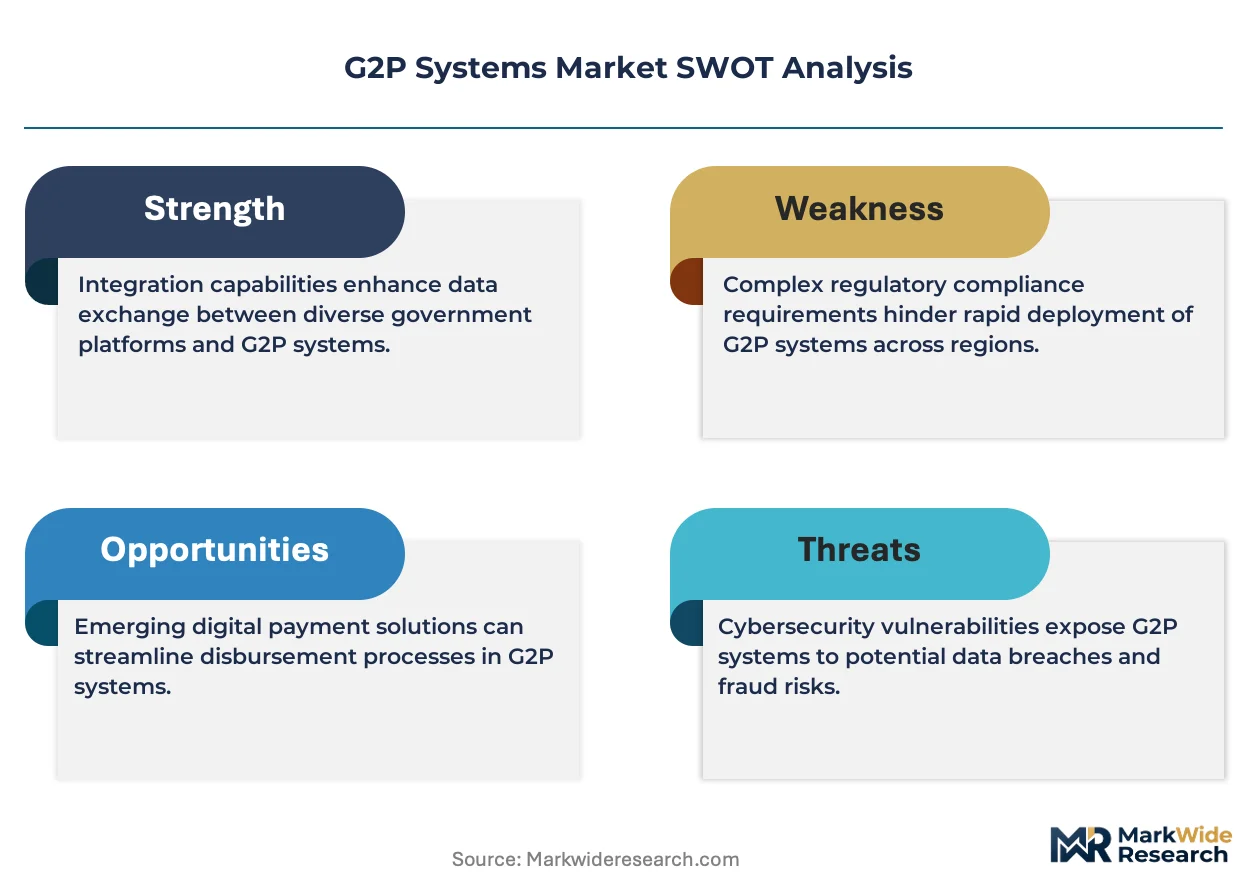
AI-driven orchestration layers are compressing integration timelines for fulfillment centers while regulatory pressure from the EU AI Act and OSHA forces hardware-software co-certification, reshaping vendor qualification and procurement cycles.
Growth Catalysts
- E-commerce Fulfillment Density:Third-party logistics clusters in Germany are deploying large-scale autonomous mobile robot fleets to eliminate worker travel time in high-SKU environments.
- EU AI Act Conformity Pathways:High-risk classification of autonomous warehouse robots is accelerating vendor investment in unified control platforms that streamline safety assessments.
- Cloud Deployment Models:Mid-market enterprises are adopting subscription-based orchestration software to bypass capital-intensive infrastructure commitments.
Market Restraints
- Steel and Lithium-Ion Input Volatility:Battery cell costs for mobile robots fluctuate with raw material spot markets, compressing hardware margins.
- Concentrated ASRS Manufacturing:Automated storage and retrieval system production centers on Japan and South Korea, creating single-source vulnerability.
- Collaborative Robot Safety Certification:OSHA machine guarding standards extend site certification timelines by months in US deployments.
Strategic Opportunities
- India Warehouse Modernization:PLI scheme incentives for manufacturing automation are opening greenfield G2P deployments in automotive and pharma clusters.
- Pharma Cold Chain Integration:Temperature-controlled G2P modules for biologics distribution represent an underpenetrated application segment.
- 5G Private Networks:Ultra-reliable low-latency connectivity is hybridizing with edge AI to enable real-time robot coordination in dense installations.
Industry Challenges
- Multi-Vendor Fleet Integration:Orchestrating disparate robot brands through proprietary software stacks creates API fragmentation and commissioning delays.
- Mechatronics Talent Scarcity:Shortages of technicians qualified in both robotic maintenance and warehouse management systems slow deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | G2P Systems Market |
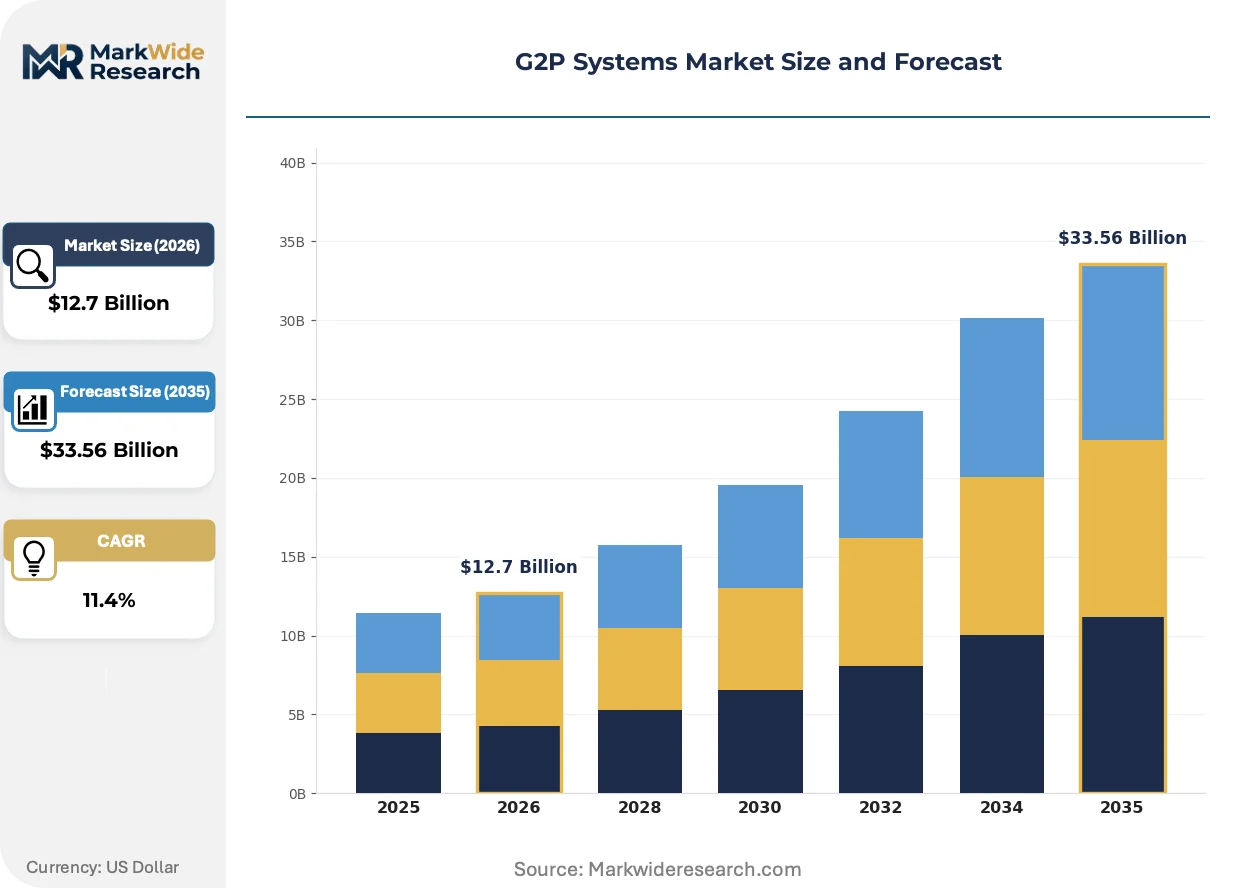
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Middleware, Hardware Components, Integrated Platforms Deployment Model: On-Premise, Cloud-Based, Hybrid, Distributed Industry Vertical: Financial Services, Healthcare, Telecommunications, Retail End User: Enterprises, Government Agencies, Nonprofits, Educational Institutions |
| Companies Covered | Honeywell Intelligrated, Symbotic, Dematic Group, SSI Schaefer, Vanderlande, Daifuku, Jungheinrich, AutoStore, Swisslog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
G2P Systems Market Evolving Landscape
Convergence between modular robotic hardware and cloud-native control architectures is dissolving traditional boundaries between fixed automation and flexible fulfillment systems, compressing payback periods for mid-scale operations.
Swarm robotics architectures are hybridizing fixed-grid storage with free-roaming autonomous mobile robots to optimize both density and throughput simultaneously. Mass retail fulfillment centers are piloting these configurations to handle seasonal demand spikes without infrastructure reconfiguration. This hybrid approach is compressing the traditional trade-off between cube utilization and retrieval speed that constrained earlier G2P generations.
The EU AI Act's high-risk system classification is mandating conformity assessments for autonomous warehouse robots with decision-making capabilities beyond pre-programmed paths. European fulfillment operators must now document risk management systems and human oversight protocols before deployment. German automotive logistics clusters are responding by consolidating vendor relationships to reduce compliance duplication across multiple robot suppliers.
Buying patterns are fragmenting as mid-market 3PLs reject bundled hardware-software contracts in favor of modular procurement. These operators are unbundling after-sales service and selecting best-of-breed orchestration layers separately from robot hardware. The shift is most visible in Netherlands and Belgium distribution corridors, where multi-tenant facilities require rapid reconfiguration between client profiles.
G2P Systems Market Segmentation
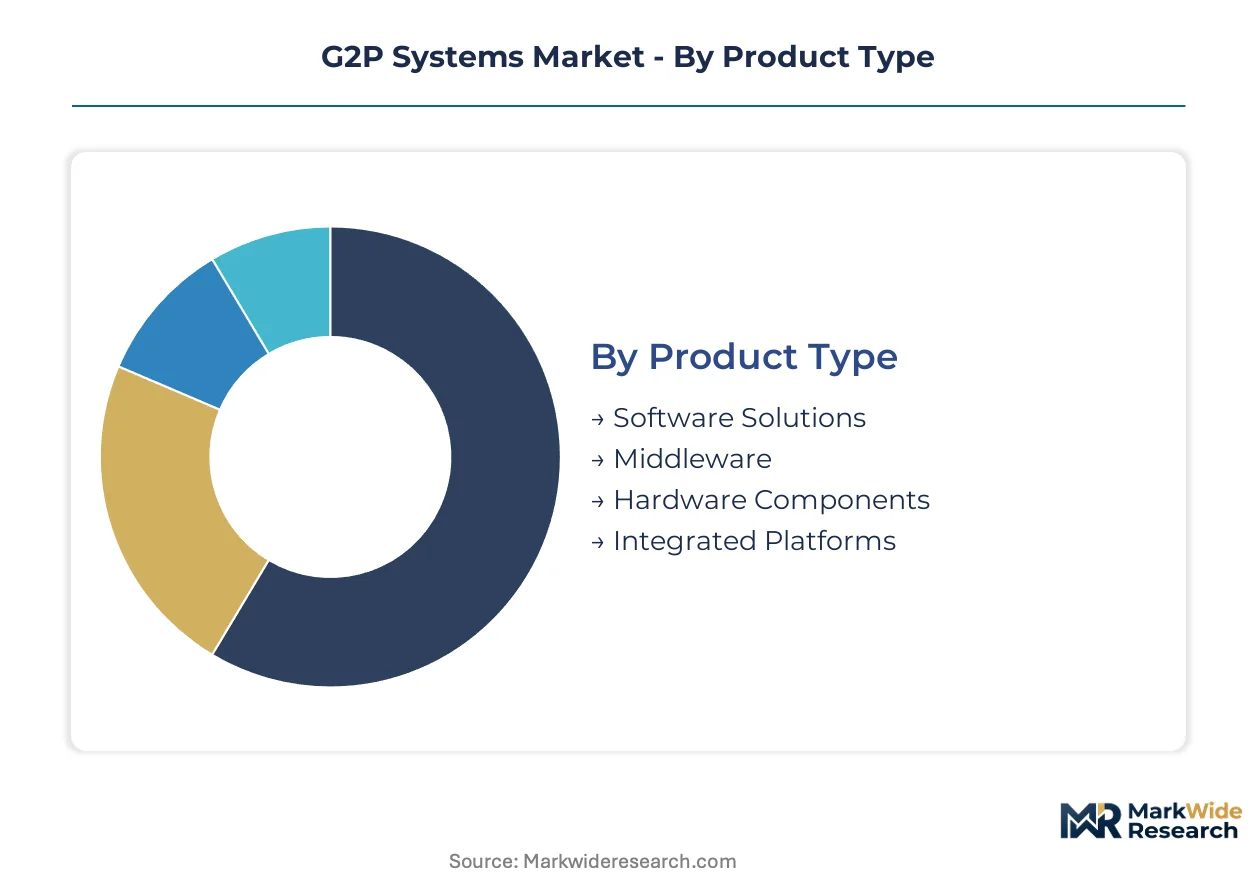
G2P systems segment across hardware-software boundaries, deployment architectures, and customer scale tiers. Buyers navigate trade-offs between capital intensity, integration complexity, and operational flexibility when selecting across these dimensions.
Product Type:
Mature hardware categories anchor installed base revenue while software layers capture expanding margin pools as orchestration becomes the primary differentiation lever.
- Integrated Platforms:Unified hardware-software stacks deliver end-to-end warehouse automation with centralized control architectures. German automotive logistics clusters prioritize these systems to streamline EU AI Act conformity assessments and reduce vendor management overhead.
- Software Solutions:Cloud-native orchestration layers manage heterogeneous robot fleets through API-driven coordination. Netherlands-based 3PLs are unbundling procurement to select best-of-breed software separately from robot hardware, accelerating adoption among multi-tenant facilities.
- Hardware Components:Individual robotic units, storage racks, and conveyor modules for custom integration projects.
- Middleware:Interoperability bridges connecting legacy warehouse management systems with modern autonomous fleets.
Integrated platforms handle the majority of throughput; software solutions are expanding most quickly on share.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from subscription-based alternatives that lower entry barriers for mid-market operators.
- Cloud-Based:Subscription orchestration software eliminates upfront infrastructure commitments while enabling elastic capacity scaling. Mid-market enterprises across Belgium distribution corridors favor this model to preserve balance sheet flexibility.
- Hybrid:Edge computing nodes process time-critical robot coordination locally while cloud layers handle analytics and fleet optimization. Mass retail fulfillment centers pilot these configurations to balance latency requirements with centralized visibility.
- On-Premise:Fully localized control systems for facilities with stringent data sovereignty or connectivity constraints.
- Distributed:Federated architectures coordinating multiple warehouse nodes as unified logical systems.
Cloud-based deployments are climbing the fastest on share; on-premise retains the largest installed base.
Industry Vertical:
Application-specific requirements drive divergent specifications around throughput velocity, SKU complexity, and environmental conditions.
- Retail:High-SKU e-commerce fulfillment centers demand modular systems reconfigurable for seasonal demand spikes. Swarm robotics hybridizing fixed-grid storage with free-roaming AMRs is gaining traction here.
- Healthcare:Temperature-controlled G2P modules for pharmaceutical distribution require validated cold chain integrity.
- Financial Services:Secure document handling and high-value asset vault automation with audit trail requirements.
- Telecommunications:Spare parts logistics for network infrastructure maintenance with rapid response SLAs.
Retail commands the dominant deployment volume; healthcare is gaining share fastest on specialized cold chain integration.
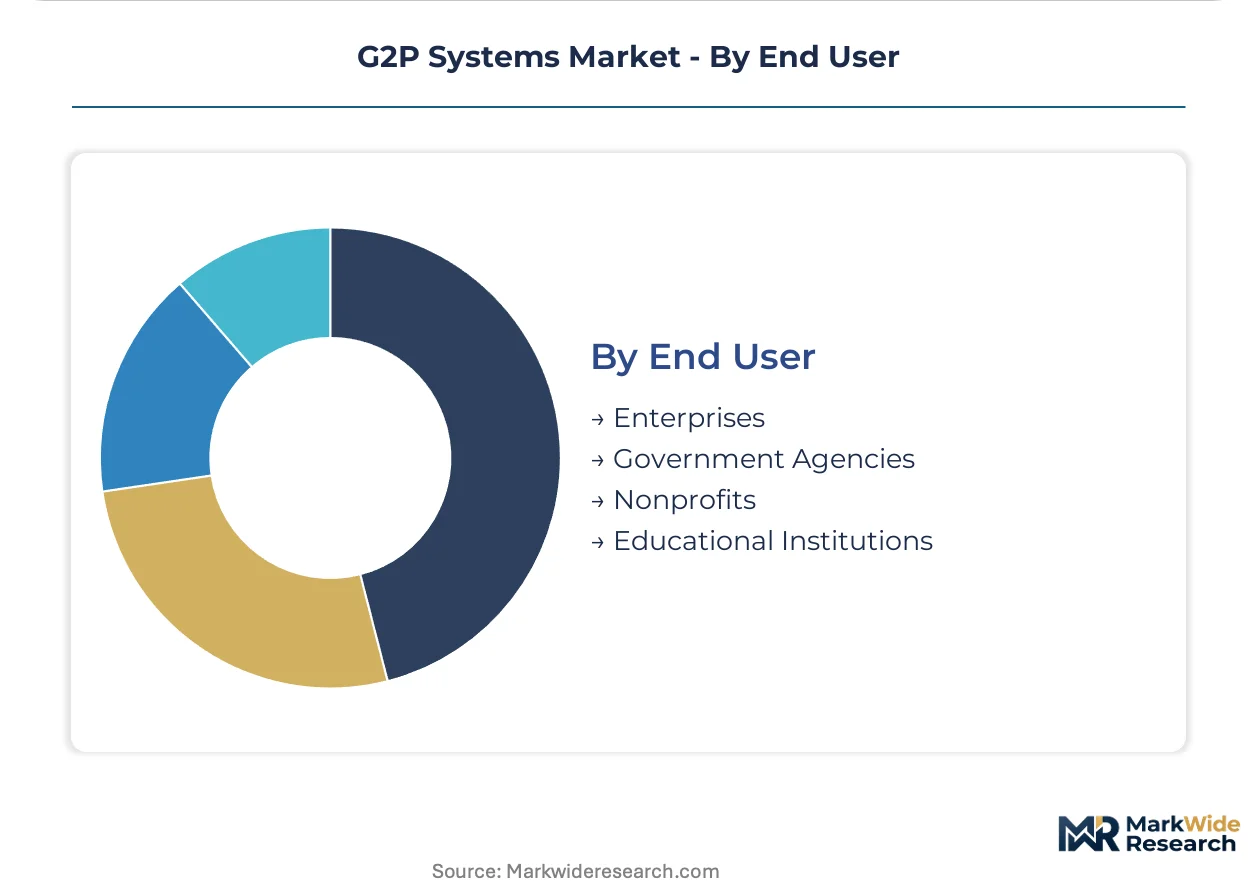
End User:
Customer type determines procurement sophistication, with enterprises driving standardization and government agencies imposing certification rigor.
- Enterprises:Large-scale operators with dedicated automation engineering teams and multi-site standardization mandates. These buyers consolidate vendor relationships to reduce compliance duplication across facilities.
- Government Agencies:Public sector procurement with extended certification timelines and preference for domestic manufacturing content under PLI-type incentives.
- Nonprofits:Cost-constrained operations prioritizing refurbished hardware and open-source orchestration alternatives.
- Educational Institutions:Research and training deployments with emphasis on interoperability standards and workforce development.
Enterprises account for the dominant share of deployment value; government agencies show the steepest expansion trajectory on infrastructure modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in warehouse automation systems, exporting integrated G2P platforms to automotive logistics clusters across Europe while importing specialized battery cells and precision sensors from Asia-Pacific suppliers. The United States and China both exhibit import dependency in high-density storage robotics, though domestic assembly capacity is expanding rapidly. Japan maintains export dominance in automated storage and retrieval subsystems.
Germany
Automotive logistics clusters in Stuttgart and Munich drive dense G2P deployments for just-in-sequence parts delivery. The EU AI Act mandates conformity assessments for autonomous warehouse robots, accelerating vendor consolidation among third-party logistics operators. Baden-Württemberg hosts the continent's highest concentration of swarm robotics pilot installations.
United States
E-commerce fulfillment centers in California and Texas are deploying autonomous mobile robot fleets at scale to compress order cycle times. OSHA machine guarding standards extend site certification timelines, favoring vendors with pre-validated safety architectures. The Inland Empire logistics corridor anchors the nation's largest concentration of cloud-orchestrated G2P operations.
China
Domestic e-commerce platforms are retrofitting legacy distribution centers with modular robotic systems to manage extreme SKU proliferation. MIIT industrial upgrading directives subsidize smart logistics equipment procurement for qualified facilities. The Yangtze River Delta manufacturing belt generates the strongest demand for hybrid cloud-edge deployment architectures.
Japan
Precision manufacturing supply chains require ultra-reliable material handling with sub-second retrieval latency. METI's Society 5.0 roadmap prioritizes warehouse automation as a productivity multiplier for shrinking workforces. The Chubu region around Nagoya concentrates domestic ASRS production capacity serving export markets.
India
PLI scheme incentives for manufacturing automation are unlocking greenfield G2P investments in automotive and pharmaceutical clusters. BIS certification requirements for industrial robotics create qualification barriers for unproven vendors. Maharashtra's Pune-Nashik industrial corridor hosts the fastest-growing deployment pipeline for temperature-controlled pharmaceutical distribution modules.
G2P Systems Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated platform vendors with end-to-end control architectures, modular hardware specialists optimizing for density or throughput, and pure-play orchestration software providers. Strategic archetypes include manufacturing-scale incumbents leveraging vertical integration, venture-backed robotics firms pursuing land-and-expand cloud models, and industrial conglomerates cross-selling from adjacent automation portfolios. Dominant competitive moves span M&A to acquire mechatronics talent and strategic partnerships to embed orchestration layers within third-party logistics operator workflows.
Within the integrated platform tier, Symbotic represents the vertically consolidated archetype with proprietary software-hardware stacks, while Daifuku exemplifies manufacturing-scale depth in automated storage and retrieval systems. AutoStore occupies a position in the ultra-dense storage specialization segment, anchoring the modular hardware vector that minimizes warehouse footprint. These three companies collectively illustrate how competitive positioning stratifies across control architecture ownership, manufacturing scale, and storage topology optimization.
| Leading Market Players |
|---|
| Honeywell Intelligrated |
| Symbotic |
| Dematic Group |
| SSI Schaefer |
| Vanderlande |
| Daifuku |
| Jungheinrich |
| AutoStore |
| Swisslog |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's spot-rate volatility feeds directly into landed costs for German automotive logistics clusters, compressing margins on integrated platform deliveries while amplifying price differentiation between EU AI Act-certified and uncertified system tiers.
Pricing Analysis
Next-generation swarm robotics configurations command substantial premiums over fixed-grid ASRS installations, while prior-generation conveyor-based systems face accelerated depreciation. Three-tier pricing structure across premium orchestration-integrated, standard hardware-bundled, and economy component-only levels dominates procurement. Cost compression in the economy tier is intensifying because mid-market 3PLs unbundle software from hardware. Government agencies show the least price sensitivity due to PLI scheme subsidies, whereas educational institutions prioritize refurbished units.
Supply Chain Analysis
Foxconn and Jabil Electronics hold concentrated contract manufacturing capacity for robotic drive assemblies and sensor modules. Component sourcing draws from Japan for precision servo motors, South Korea for lithium-ion cells, and Germany for steel rack fabrication. Steel and battery input volatility creates margin exposure for hardware vendors. Distribution runs through direct vendor-to-operator channels for large enterprises, with systems integrators serving mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
G2P system demand tracks e-commerce fulfillment capex cycles, with German automotive logistics clusters signaling early-stage recovery through accelerated AMR pilot commitments.
For Market Incumbents: Pre-empt modular software unbundling by embedding orchestration layers deeper into warehouse management system workflows. Consolidate vendor relationships among EU-based 3PLs to reduce conformity assessment duplication under the EU AI Act. Prioritize in-house production of battery management systems to offset lithium-ion cost volatility. For New Entrants and Emerging Players: Temperature-controlled pharmaceutical distribution modules for Indian cold chain modernization represent the most penetrable entry point, given PLI scheme incentives and limited incumbent specialization. Cloud-native orchestration for multi-tenant facilities in Belgium and Netherlands distribution corridors offers secondary white-space. Lead with API-first integration messaging to bypass hardware certification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play orchestration software providers with established API ecosystems and recurring revenue bases. Five-to-ten-year viability hinges on regulatory compliance automation capabilities rather than hardware manufacturing scale. Monitor EU AI Act enforcement intensity across German logistics clusters as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Automation | Pre-validated safety architectures compress site certification timelines for OSHA and EU regulators. |
| Cloud Orchestration Platform Launch | Subscription models unlock mid-market 3PLs in Belgium and Netherlands distribution corridors. |
| Pharma Cold Chain Module Development | Temperature-controlled G2P systems address underpenetrated biologics distribution requirements. |
| Strategic Partnership with 5G Network Providers | Ultra-reliable connectivity enables real-time swarm coordination in dense warehouse installations. |
| Acquisition of Mechatronics Talent Pools | Technical workforce scarcity constrains deployment velocity across German automotive clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from publicly listed automation vendors, EU AI Act implementation guidance, and OSHA technical standards documentation. Primary interviews covered warehouse operations directors at third-party logistics operators, procurement leads at German automotive manufacturers, robotics integration specialists, and regulatory compliance officers. Bottom-up unit deployment estimates triangulate against top-down capex flow analysis across e-commerce fulfillment and automotive logistics verticals.
Forecast inputs span robot density per facility, software attach rates by deployment model, and regulatory compliance cost burdens across geographies. Segmentation dimensions include hardware-software product type, cloud-hybrid-on-premise deployment architecture, and customer scale tier from enterprise to government agency. CAGRs derive from elasticity modeling against e-commerce fulfillment volume growth and manufacturing automation incentive programs. Battery cell cost trajectories and steel price indices feed hardware margin projections throughout the analysis window.
Practitioners should monitor EU AI Act enforcement patterns, lithium-ion spot market movements, and German automotive production schedules for early signals of forecast revision. Assumptions reflect current regulatory frameworks and commodity price baselines. Quarterly review of AMR deployment announcements from Stuttgart and Munich logistics clusters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart Card Reader Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
Core Graphics Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Precision Agriculture Software Market