
 Tag Management Software Market | 2026-2036
Tag Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Tag Management Software Market Outlook
Modular unbundling of tag containers is restructuring how marketing teams evaluate vendor relationships. Google Tag Manager leverages its native integration with the Google Marketing Platform to dominate mid-market adoption. Tealium anchors enterprise deployments through its customer data infrastructure specialization. Adobe Experience Platform Launch competes by extending creative-cloud workflows into tag orchestration.
Tag management software constitutes a rules-based execution layer that deploys, updates, and governs JavaScript tags and tracking pixels across web properties and mobile applications without direct code modification. The platform operates through asynchronous container loading, typically achieving sub-100-millisecond latency for tag firing sequences to prevent page-render blocking. Cloud-based deployment leads segment adoption as organizations migrate martech stacks away from on-premises maintenance overhead. Real-time updates functionality commands premium positioning within the functionality dimension, reflecting operational necessity for campaign agility. Web analytics integration level retains the largest installed base, though CRM-connected configurations demonstrate the fastest expansion as identity resolution requirements intensify.
FCC guidelines on broadband privacy and the EU's GDPR shape product development trajectories, with vendors embedding consent-state propagation as a default architecture requirement. ISO 27001 certification has become a baseline procurement filter for enterprise RFP processes, particularly in healthcare and financial services verticals. Stakeholders must monitor emerging state-level privacy statutes in the United States, as fragmented compliance obligations will determine which vendors can sustain multi-jurisdictional deployment scalability without custom engineering overhead.
Market Dynamics
Consent-state propagation architecture is restructuring vendor procurement criteria as privacy regulations harden across multiple jurisdictions, forcing enterprises to re-engineer data collection infrastructure around real-time permission management rather than retrospective compliance patching.
Growth Catalysts
- GDPR enforcement escalation:The EU's Digital Services Act mandates auditable consent chains, compelling enterprises to replace legacy tag deployments with governance-native platforms.
- Retail media networks:Walmart and Target's advertising platforms require granular attribution tracking, driving demand for server-side tag configurations that bypass browser cookie deprecation.
- Edge computing migration:Content delivery networks now embed tag execution at the edge, reducing latency for e-commerce checkout flows and mobile application events.
Market Restraints
- Cloud infrastructure concentration:AWS, Google Cloud, and Microsoft Azure control server-side tagging compute costs, creating margin pressure for independent software vendors.
- JavaScript execution blocking:Safari's Intelligent Tracking Prevention and Firefox's Enhanced Tracking Protection limit pixel firing reliability, degrading attribution accuracy.
- ISO 27001 certification costs:Healthcare and financial services procurement mandates impose six-figure annual compliance investments that exclude mid-market vendors.
Strategic Opportunities
- India's data localization mandate:The Digital Personal Data Protection Act requires in-country data processing, creating demand for sovereign tag management deployments.
- Connected TV advertising:Streaming platforms lack standardized measurement protocols, opening white space for tag vendors to establish OTT-specific container schemas.
- First-party data clean rooms:Integration with Snowflake and Databricks environments enables privacy-preserving audience activation without third-party cookie dependency.
Industry Challenges
- MarTech engineering talent scarcity:Organizations struggle to hire specialists who bridge JavaScript execution optimization with consent management platform configuration.
- Legacy website architecture retrofitting:Enterprises running decade-old content management systems face six-to-twelve-month migration timelines to implement asynchronous container loading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tag Management Software Market |
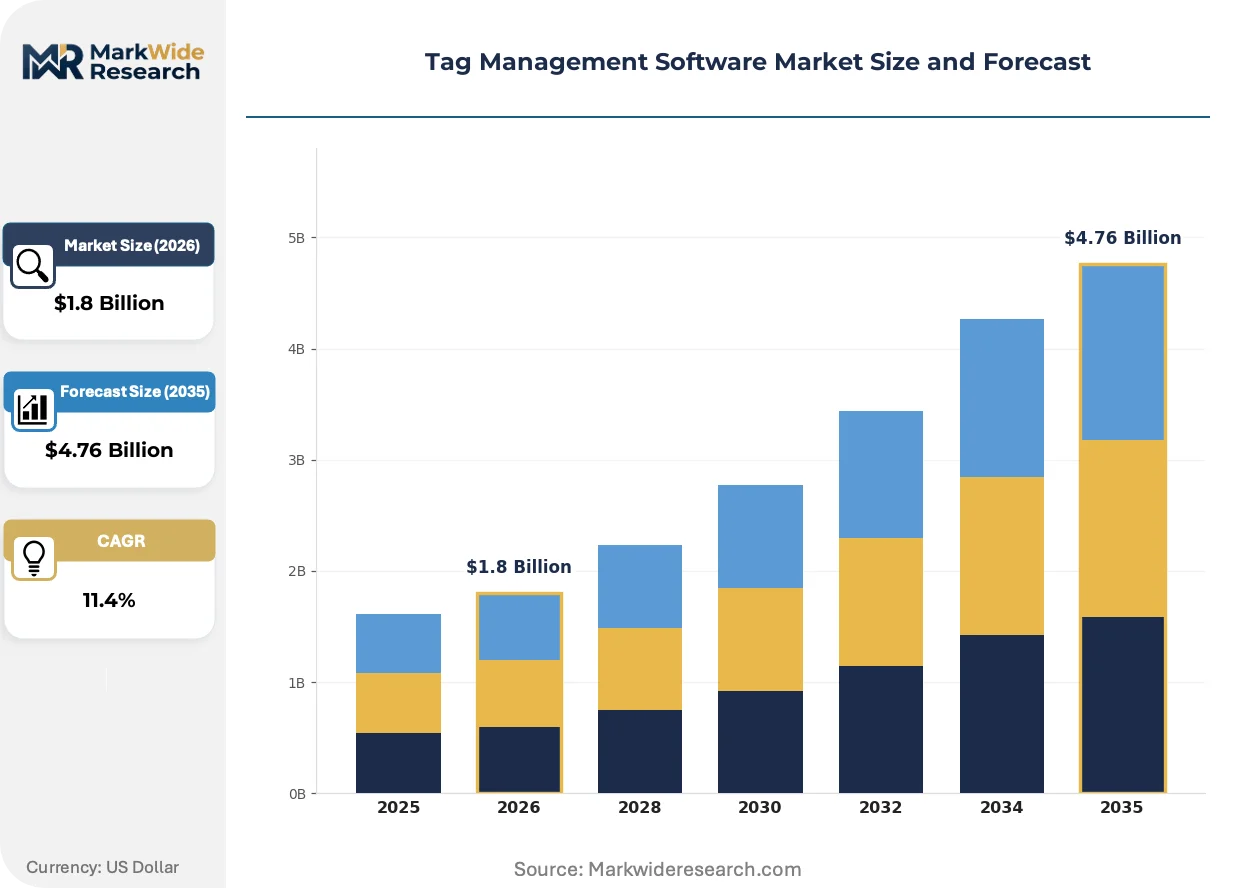
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Small Businesses, Enterprises, Marketing Agencies, E-commerce Functionality: Real-time Updates, Version Control, User Management, A/B Testing Integration Level: Web Analytics, CRM, E-mail Marketing, Others |
| Companies Covered | Google Tag Manager, Tealium, Adobe Experience Platform Launch, Piwik PRO, ObservePoint, Ensighten, Qubit, Commanders Act, Segment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tag Management Software Market Strategic Shifts
Server-side tagging infrastructure is displacing client-side execution as the default architecture, compressing the competitive window for vendors who lack hybrid deployment capabilities and forcing product roadmaps toward unified data collection layers.
Customer data platforms are unifying tag management with identity resolution and audience segmentation into single-stack offerings. Retail and healthcare buyers favor these consolidated deployments to reduce vendor count and simplify GDPR Article 30 record-keeping. This unification is compressing standalone tag management pricing power and favoring vendors with native data warehouse connectivity.
The EU AI Act's risk classification framework is reshaping how automated decisioning tags are deployed. High-risk use cases in credit and insurance now require human-in-the-loop audit trails, forcing vendors to embed explainability logging directly into tag firing sequences. Financial services deployments in Germany and France are accelerating compliance-first procurement cycles.
Buyer committees now mandate proof-of-concept pilots before enterprise commitments, extending sales cycles but reducing implementation failure rates. Procurement teams evaluate tag vendors against synthetic data testing environments rather than production references alone. This pattern is most pronounced in United States healthcare systems navigating HIPAA Business Associate Agreement complexity.
Tag Management Software Market Segmentation
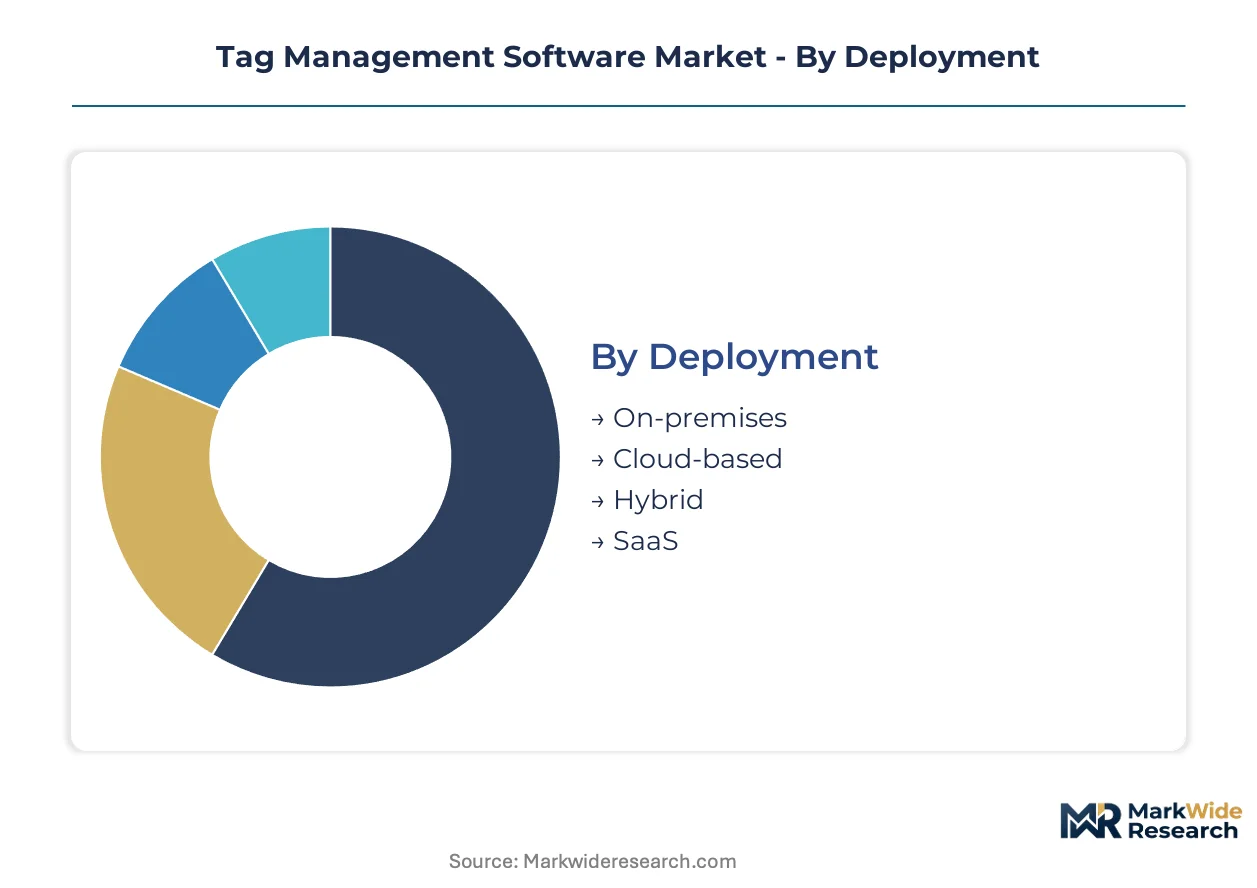
Tag management software buyers prioritize fundamentally different capabilities based on their data governance maturity and technical infrastructure. Deployment architecture determines latency performance and compliance posture, while end-user scale dictates whether organizations need enterprise-grade consent propagation or lightweight campaign agility.
Deployment:
Cost tier separates buyers in this category, with infrastructure ownership preferences correlating directly to regulatory exposure and IT headcount.
- Cloud-based:Asynchronous container loading executes through distributed edge nodes, eliminating on-premises maintenance overhead. Healthcare systems in the United States and retail media networks drive procurement, compelled by HIPAA Business Associate Agreement complexity and sub-100-millisecond latency requirements for checkout attribution.
- SaaS:Multi-tenant architectures deliver automatic security patching and elastic scaling without DevOps investment. Marketing agencies and e-commerce platforms favor this tier for campaign agility, though data residency clauses in India's Digital Personal Data Protection Act are forcing vendors to establish sovereign instances.
- On-premises:Single-tenant installations retain full data sovereignty for air-gapped environments. Financial services institutions in Germany deploy these configurations to satisfy BaFin audit requirements for transaction data flows.
- Hybrid:Split execution routes sensitive events through private infrastructure while pushing anonymized analytics to public cloud. Enterprises navigating EU-U.S. data transfer uncertainty adopt this architecture to maintain GDPR Article 44 compliance.
Volume sits with Cloud-based deployments; growth tilts toward Hybrid configurations as data localization mandates multiply.
End User:
Application context determines whether buyers need standalone tag containers or unified customer data infrastructure.
- E-commerce:Server-side tagging configurations bypass Safari Intelligent Tracking Prevention and Firefox Enhanced Tracking Protection to preserve checkout funnel attribution. Walmart and Target's retail media networks require granular event tracking that client-side pixels cannot reliably deliver.
- Enterprises:Procurement committees mandate ISO 27001 certification, six-figure annual compliance investments, and proof-of-concept pilots before commitment. These buyers favor vendors with native Snowflake and Databricks connectivity for first-party data clean room integration.
- Marketing Agencies:Multi-client container management demands rapid deployment templates and role-based access controls. GDPR Article 30 record-keeping obligations push these buyers toward platforms with automated consent-state audit trails.
- Small Businesses:Limited martech engineering headcount drives preference for pre-built tag templates and managed service overlays. These buyers prioritize Google Marketing Platform native integration over specialized governance features.
Revenue concentrates with Enterprises; the steepest expansion trajectory belongs to E-commerce as privacy regulations harden.
Functionality:
Customer maturity separates buyers, with sophisticated organizations demanding programmable execution layers beyond basic tag deployment.
- Real-time Updates:Container modifications propagate to production environments without code deployment cycles, enabling intraday campaign adjustments. Retail media networks and flash-sale e-commerce operators treat this as non-negotiable operational infrastructure.
- A/B Testing:Tag firing sequences integrate with experimentation platforms to measure variant performance without duplicate instrumentation. Digital-native enterprises in France and Germany embed EU AI Act explainability logging into these workflows for high-risk automated decisioning use cases.
- Version Control:Immutable configuration histories enable rollback to known-good states when tag errors corrupt analytics pipelines. Healthcare systems navigating HIPAA complexity require this for Business Associate Agreement audit defense.
- User Management:Role-based permissions restrict tag publishing authority to reduce rogue pixel deployment. Marketing agencies serving regulated financial services clients deploy these controls for client data segregation.
Adoption depth is greatest for Real-time Updates; A/B Testing is climbing the fastest as experimentation discipline matures.
Integration Level:
Supply concentration in adjacent martech categories determines which integration pathways vendors must prioritize.
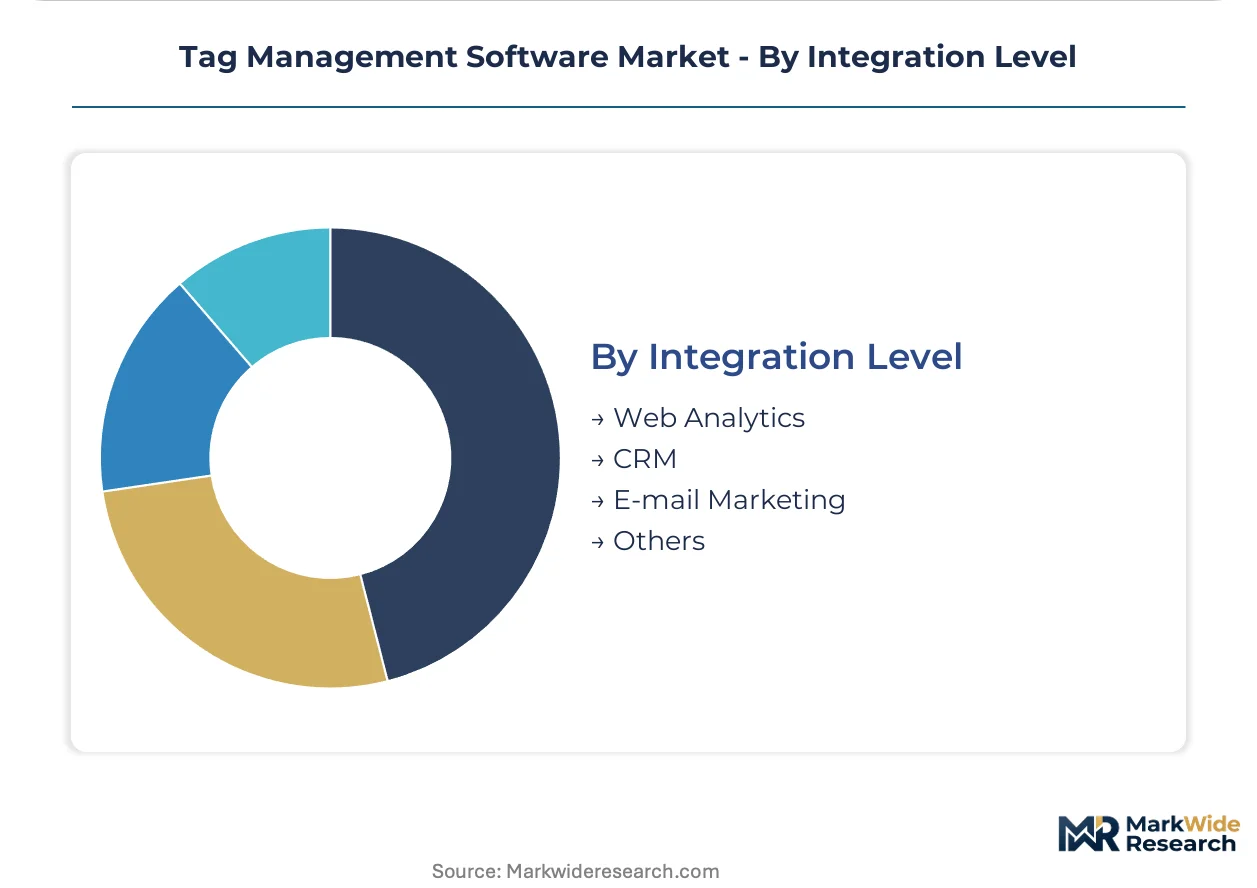
- Web Analytics:Direct data layer standardization with Google Analytics 4 and Adobe Analytics retains the largest installed base. These configurations remain default for mid-market buyers without specialized identity resolution requirements.
- CRM:Server-side event forwarding into Salesforce, HubSpot, and Microsoft Dynamics enables unified customer profiles without third-party cookie dependency. Enterprise healthcare and financial services deployments demonstrate the fastest expansion as identity resolution intensifies.
- E-mail Marketing:Tag-triggered audience segments activate through Mailchimp, Klaviyo, and Braze for behavioral retargeting workflows. E-commerce platforms leverage these integrations for abandoned-cart recovery automation.
- Others:Connected TV measurement protocols, data clean room environments, and proprietary retail media APIs constitute emerging integration categories. Streaming platforms lack standardized container schemas, creating vendor opportunity to establish OTT-specific definitions.
Deployment scale favors Web Analytics; CRM-connected configurations are gaining share fastest as first-party data strategies displace cookie-dependent attribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tag management software consumption concentrates in the United States, while development talent pools and data center infrastructure distribute across Western Europe and South Asia. Production of core platform technology remains anchored in American cloud computing clusters, though regulatory fragmentation is forcing vendors to establish sovereign hosting footprints.
United States
Retail media networks at Walmart and Target drive enterprise procurement, requiring server-side tagging configurations that bypass browser-level tracking restrictions. FCC broadband privacy guidelines and HIPAA Business Associate Agreement complexity compel healthcare systems toward ISO 27001-certified deployments. Silicon Valley and Seattle host the dominant engineering clusters for cloud-native tag infrastructure development.
Germany
BaFin audit requirements for financial services transaction data push institutions toward on-premises and hybrid deployment architectures. The EU AI Act's risk classification framework mandates explainability logging for automated decisioning tags in credit and insurance use cases. Frankfurt's financial technology corridor concentrates compliance-first procurement committees evaluating sovereign data processing options.
United Kingdom
London's advertising technology ecosystem sustains demand for multi-client container management among marketing agencies serving pan-European accounts. The Information Commissioner's Office enforcement of GDPR consent-chain audibility drives replacement of legacy tag deployments. The city's retail banking headquarters accelerate CRM-connected configurations for unified customer profiles.
India
The Digital Personal Data Protection Act's data localization mandate forces vendors to establish in-country processing infrastructure for e-commerce platform deployments. Bangalore and Hyderabad's software engineering hubs supply MarTech implementation talent for asynchronous container migration projects. Domestic e-commerce operators prioritize real-time update functionality for flash-sale campaign agility.
France
CNIL regulatory guidance on consent-state propagation shapes product requirements for vendors serving the French market. High-risk automated decisioning use cases in insurance and credit trigger EU AI Act compliance investments in explainability logging. Paris-based luxury retail headquarters demand granular attribution tracking for omnichannel customer journey mapping.
Tag Management Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across deployment architecture categories. Google and Adobe leverage creative-cloud and marketing-platform integration to dominate mid-market adoption, while independent vendors anchor enterprise deployments through customer data infrastructure specialization. Three strategic archetypes have emerged: cloud-native container platforms, consent-management-integrated suites, and server-side execution specialists. Competitive moves concentrate on hybrid deployment capability expansion and first-party data clean room integration partnerships.
Within the cloud-native tier, Google Tag Manager and Adobe Experience Platform Launch exemplify platform-ecosystem anchoring strategies that reduce procurement friction for existing marketing technology customers. Tealium occupies a position representing enterprise-grade customer data infrastructure unification, where tag management converges with identity resolution and audience segmentation. Among European-based specialists, Piwik PRO exemplifies the sovereign-deployment archetype, addressing data residency requirements through regional hosting infrastructure. These three company patterns illustrate how vendor selection increasingly correlates with organizational data governance maturity and regulatory exposure rather than standalone tag deployment functionality.
| Leading Market Players |
|---|
| Google Tag Manager |
| Tealium |
| Adobe Experience Platform Launch |
| Piwik PRO |
| ObservePoint |
| Ensighten |
| Qubit |
| Commanders Act |
| Segment |
| Others |
Value Chain & Pricing Dynamics
MarTech engineering talent concentration in Bangalore and Hyderabad drives labor-cost differentials that widen pricing-tier spreads between premium enterprise deployments and lightweight SaaS configurations.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects hyperscaler cloud infrastructure concentration, as AWS, Google Cloud, and Microsoft Azure control server-side tagging compute costs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified enterprise deployments from rapid-deployment agency configurations. Price differentiation hinges on consent-state propagation complexity and real-time update functionality. Healthcare systems demonstrate lowest price sensitivity given HIPAA Business Associate Agreement mandates, while small businesses prioritize Google Marketing Platform native integration over specialized governance features.
Supply Chain Analysis
Refurbishment flows for legacy on-premises tag management instances create secondary supply channels as enterprises migrate toward cloud-native architectures. Core platform development concentrates in the United States, with engineering clusters anchored in Silicon Valley and Seattle. Cloud infrastructure draws from hyperscaler data centers across the United States, Western Europe, and India. Single-source vulnerability in cloud compute provisioning creates margin pressure for independent software vendors. Distribution runs through direct enterprise sales, agency channel partners, and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tag management software procurement has become a cost-of-compliance story, with GDPR and the EU AI Act erecting barrier-to-entry moats that favor vendors with embedded consent-state propagation and explainability logging architectures.
For Market Incumbents: Extend hybrid deployment capabilities to capture EU-U.S. data transfer uncertainty demand, while deepening first-party data clean room integration partnerships with Snowflake and Databricks. Server-side tagging specialization from emerging entrants threatens premium positioning, making ISO 27001 certification maintenance and sovereign hosting footprint expansion critical defensive levers.
For New Entrants and Emerging Players: Begin with India's data localization mandate opportunity, where the Digital Personal Data Protection Act forces vendors to establish in-country processing infrastructure for e-commerce platform deployments. Connected TV advertising measurement protocols offer unstandardized white space for OTT-specific container schema development. Go-to-market should emphasize real-time update functionality for flash-sale retail operators.
For Investors and Strategic Acquirers: Re-rating potential sits with consent-management-integrated suite providers given EU AI Act enforcement escalation as a catalyst. Long-term viability favors vendors bridging JavaScript execution optimization with customer data platform unification. Monitor state-level privacy statute fragmentation in the United States as an inflection indicator for multi-jurisdictional deployment scalability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Tagging Migration | Bypasses Safari Intelligent Tracking Prevention and Firefox Enhanced Tracking Protection for reliable attribution. |
| Consent-State Propagation Architecture | Addresses GDPR Article 30 record-keeping and EU Digital Services Act audit requirements. |
| First-Party Data Clean Room Integration | Enables privacy-preserving audience activation through Snowflake and Databricks connectivity. |
| Sovereign Hosting Footprint Expansion | Satisfies India's Digital Personal Data Protection Act data localization mandates. |
| EU AI Act Explainability Logging | Supports high-risk automated decisioning compliance in German and French financial services. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across retail media networks, healthcare systems, and marketing agencies. SEC filings, hyperscaler capex disclosures, and App Annie mobile analytics provided technology deployment validation. Bottom-up vendor revenue triangulation against top-down addressable market sizing ensured cross-verification.
Deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern were modeled at granular level across the analysis window. CAGRs derived from segment-level growth trajectory analysis incorporating privacy regulation enforcement timelines and cloud migration pace. Server-side tagging penetration rates and consent management platform adoption curves informed technology transition assumptions.
Underlying measurement precision varies by segment; cloud-based and SaaS deployments carry tighter precision than on-premises configurations given vendor disclosure transparency. Forecasts reflect assumptions on regulatory enforcement intensity and browser-level tracking restriction evolution. Practitioners should monitor FCC broadband privacy guideline developments and emerging state-level privacy statutes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Transient Analysis Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Website Translation Software Market
Software & Services
Global Permit Management Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Office Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Global Reference Check Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Mobile Application Development Platform (MADP) Market