

P2P Rental Apps Market Size, Share, and Industry Trends Forecast 2026-2036
P2P Rental Apps Market Insights
Multi-source marketplace sourcing is expanding as platform operators diversify beyond single-asset categories to capture cross-vertical network effects. Airbnb leverages its global host infrastructure to sustain property rental dominance while extending into experience-based offerings. Turo anchors vehicle sharing liquidity through proprietary insurance partnerships and dynamic pricing algorithms. Fat Llama specializes in equipment leasing density across London and Los Angeles, competing on localized inventory depth rather than geographic breadth.
Peer-to-peer rental applications constitute digital marketplace infrastructure connecting idle asset owners with temporary users through verified identity protocols, integrated payment escrow, and algorithmic trust scoring. These platforms orchestrate commercial purpose by monetizing underutilized capacity in vehicles, residential space, and specialized equipment without transferring ownership. Mobile apps command the platform type hierarchy due to persistent location services and push-notification engagement loops that web interfaces cannot replicate. Property rental and vehicle sharing concentrate the service offering margin pools, while transaction fee monetization dominates revenue architecture because it scales with gross booking value rather than fixed subscription ceilings.
The US Federal Trade Commission scrutinizes platform fee transparency and host earnings disclosures, while the EU Digital Services Act imposes liability frameworks for illegal content and algorithmic recommendation accountability. Insurance regulators in multiple states now mandate supplemental coverage disclosures before peer-to-peer vehicle transactions finalize. Stakeholders must monitor evolving classification battles over whether hosts constitute employees or independent contractors, as this determination cascades through tax obligations, benefit requirements, and platform operating costs.
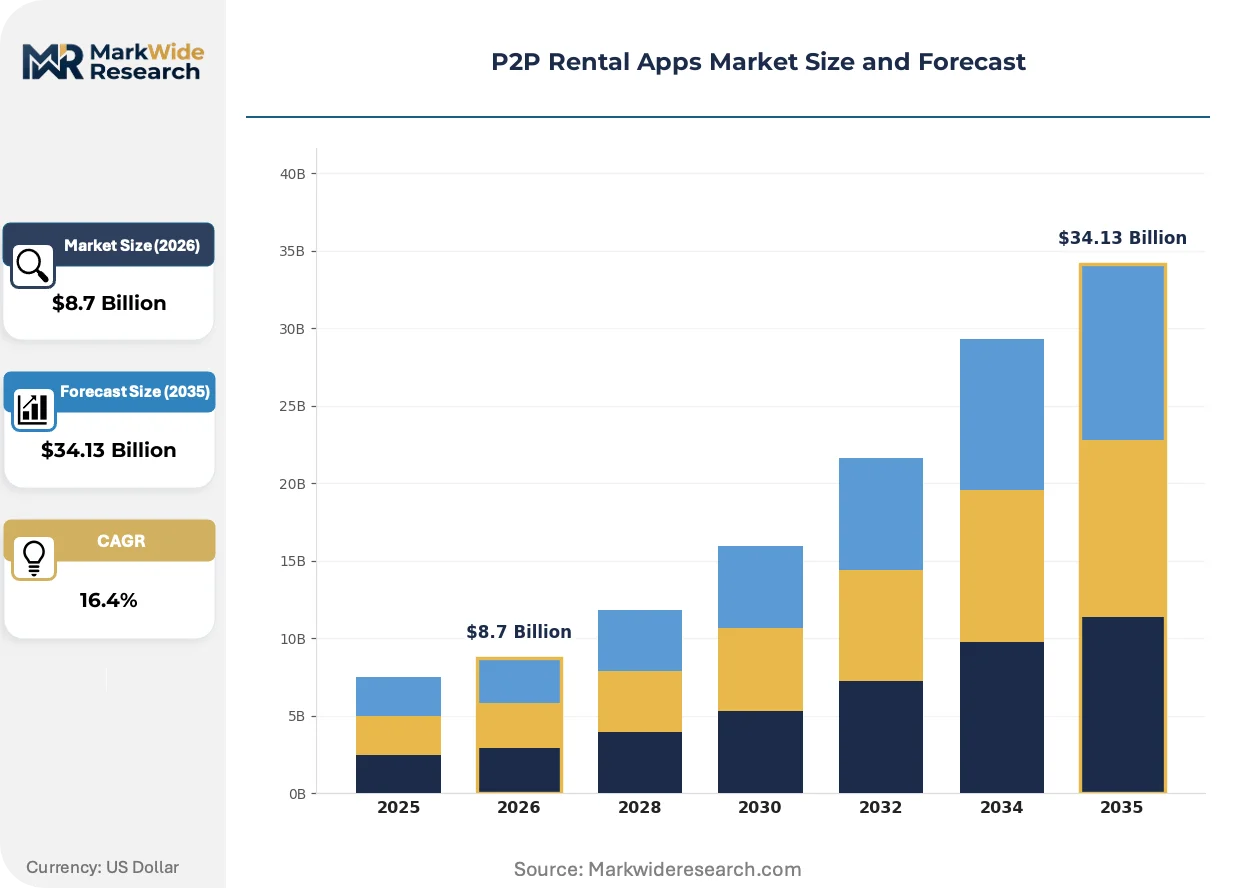
Market Dynamics
Algorithmic trust scoring and embedded insurance APIs are compressing transaction friction, enabling asset owners to monetize idle capacity without traditional broker intermediation. Mobile-first identity verification protocols now authenticate users in under 90 seconds, collapsing the onboarding barrier that previously constrained marketplace liquidity.
Growth Catalysts
- EU Digital Services Act:Standardized liability frameworks for illegal content and algorithmic transparency create compliance clarity that accelerates platform expansion across member states.
- Embedded payment escrow:Real-time fund settlement through licensed money transmitter partnerships eliminates chargeback risk and reduces host payment delays from days to hours.
- Urban millennial density:Concentrated demand in metropolitan cores like New York, London, and Berlin generates network effects that attract supply-side inventory faster than dispersed suburban markets.
Market Restraints
- Host classification ambiguity:Ongoing disputes over independent contractor versus employee status in California, New York, and Illinois create payroll tax and benefit liability uncertainty.
- Supplemental insurance gaps:Personal auto policies in most US states exclude commercial peer-to-peer usage, forcing platforms to absorb catastrophic loss exposure or mandate costly rider purchases.
- Local zoning preemption:Short-term rental caps in Barcelona, Amsterdam, and Paris restrict inventory growth in high-demand urban cores where platform economics concentrate.
Strategic Opportunities
- Experience-based verticals:Activity and tour marketplaces attached to rental bookings capture incremental spend per trip while differentiating against pure accommodation competitors.
- India's digital payments infrastructure:Unified Payments Interface ubiquity enables escrow-free transactions that reduce platform working capital requirements and merchant discount rates.
- Commercial fleet conversion:Underutilized corporate vehicle pools and dormant hospitality assets represent captive supply that platforms can activate through white-label enterprise partnerships.
Industry Challenges
- Cross-border tax compliance:Hosts operating across multiple jurisdictions face fragmented reporting obligations for occupancy taxes, income withholding, and VAT collection.
- Legacy property management system integration:Hotels and institutional hosts require API connectivity to existing channel managers and revenue management tools before adopting peer-to-peer distribution.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P2P Rental Apps Market Trends and Innovations
Dynamic pricing algorithms and predictive demand modeling are compressing revenue optimization cycles from weekly to hourly adjustments. Platforms now integrate weather data, event calendars, and flight arrival patterns to automate rate recommendations that previously required manual host intervention.
Machine learning-based fraud detection is overtaking rule-based identity verification in transaction security. These neural network systems analyze device fingerprints, behavioral biometrics, and payment velocity patterns to flag suspicious bookings before confirmation. Major platforms deploy this technology across high-value vehicle and luxury property categories where synthetic identity theft concentrates. The shift is overtaking static document checks that fraudsters increasingly circumvent with deepfake submissions.
The EU Digital Services Act mandates algorithmic recommendation transparency and illegal content removal protocols that reshape platform governance. Operators must disclose ranking parameters and provide appeal mechanisms for delisted listings. Property rental marketplaces face particular scrutiny in France and Germany where housing advocates pressure regulators to prioritize long-term tenancy visibility over short-term commercial listings.
Subscription-based access models are fragmenting traditional per-transaction booking behavior. Urban professionals in London, Singapore, and San Francisco purchase monthly vehicle or equipment memberships that guarantee availability without individual reservation friction. This shift displaces sporadic usage patterns and generates predictable recurring revenue that platforms prefer for cash flow stability and reduced customer acquisition costs.
P2P Rental Apps Market Segmentation
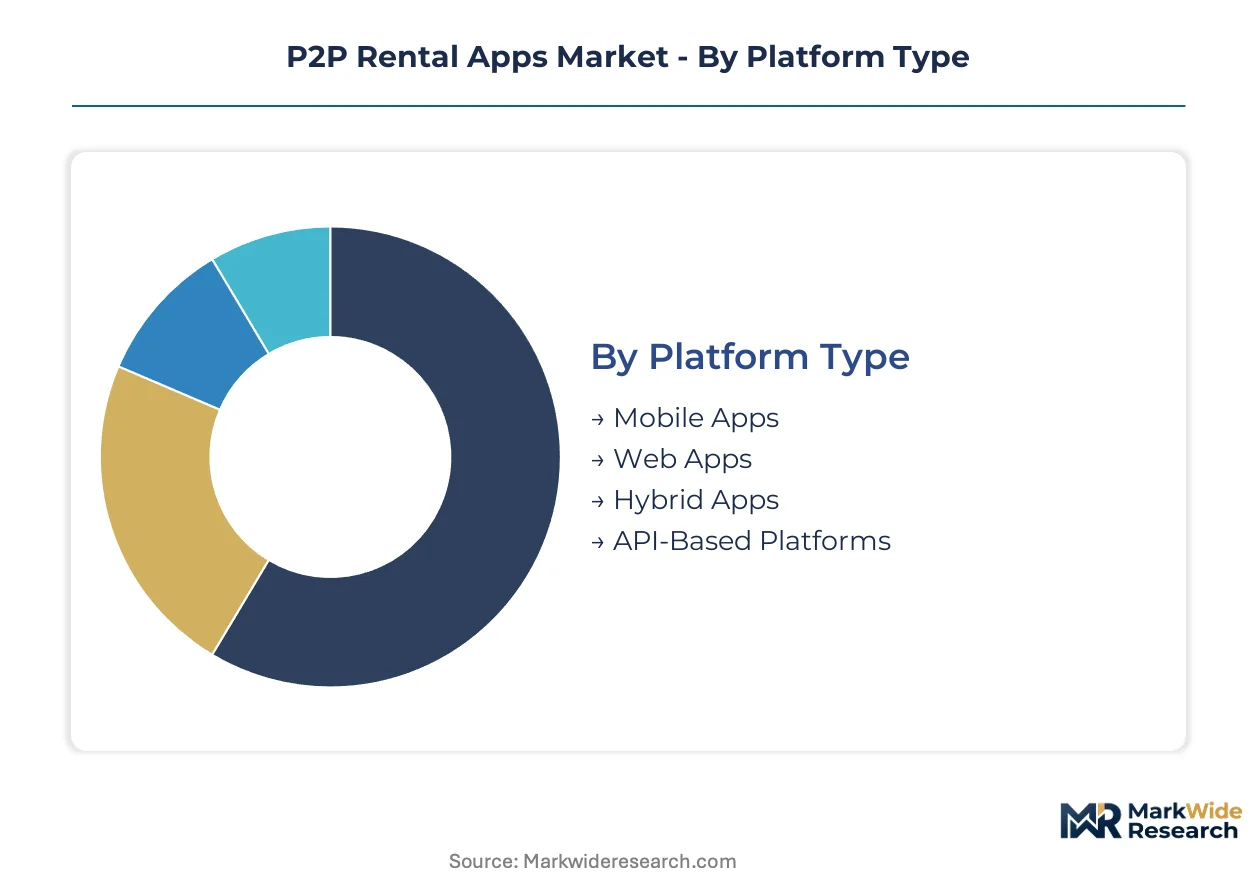
P2P rental apps fragment across four structural dimensions that determine customer acquisition costs, regulatory exposure, and network effect velocity. Platform type dictates identity verification infrastructure requirements. Service offering shapes insurance partnership complexity and host onboarding friction.
Platform Type:
Certification burdens cluster around payment licensing and data protection, with mobile-first architectures facing stricter app store compliance than web-native alternatives.
- Mobile Apps:Native iOS and Android deployments leverage persistent location services and push-notification engagement loops that web interfaces cannot replicate. Demand concentrates in urban millennial corridors across New York, London, and Berlin where smartphone penetration exceeds 95% and instant booking expectations dominate.
- Web Apps:Browser-based platforms reduce app store commission burdens and enable rapid feature iteration without store approval delays. Corporate fleet managers and institutional hosts in Germany and France prefer web dashboards for bulk inventory management and multi-property rate calibration.
- Hybrid Apps:Cross-platform frameworks balance development cost efficiency with native hardware access for camera-based identity verification and GPS-enabled asset tracking.
- API-Based Platforms:Headless infrastructure enables white-label deployments for hospitality groups and automotive dealerships seeking branded rental marketplaces without platform engineering investments.
Mobile Apps sits at the top of the volume ranking, with API-Based Platforms climbing the fastest.
Service Offering:
Margin structures diverge sharply across asset categories, with property rental commanding premium transaction fees and vehicle sharing absorbing elevated insurance overhead.
- Vehicle Sharing:Peer-to-peer automobile and motorcycle rentals require supplemental commercial coverage that personal auto policies exclude. Turo anchors liquidity in the United States through proprietary insurance partnerships and dynamic pricing algorithms that adjust hourly based on local demand signals.
- Property Rental:Residential space monetization generates the highest gross booking values per transaction but faces municipal zoning preemption in Barcelona, Amsterdam, and Paris where short-term rental caps restrict inventory growth.
- Equipment Leasing:Specialized tool and camera rentals concentrate density in London and Los Angeles through Fat Llama's localized inventory depth strategy rather than geographic breadth expansion.
- Event Supplies:Temporary furniture, décor, and catering equipment rentals spike around festival calendars and wedding seasons with pronounced demand clustering in summer months.
- Specialty Items:Niche categories including luxury handbags, musical instruments, and outdoor gear attract hobbyist communities with lower frequency but higher trust requirements per transaction.
Property Rental generates the dominant revenue share, though Equipment Leasing shows the steepest expansion trajectory among secondary categories.
Target Customer:
Customer acquisition economics vary threefold across segments, with small businesses delivering lifetime value premiums against higher initial onboarding friction.
- Individual Renters:Urban consumers seeking one-off vehicle or accommodation access represent the volume base but exhibit churn sensitivity to platform fee increases.
- Small Businesses:Local contractors and event planners generate recurring demand patterns and tolerate subscription pricing for guaranteed equipment availability.
- Freelancers:Independent photographers, videographers, and consultants rent specialized gear for project-based workflows with irregular but high-value transaction profiles.
- Hobbyists:Enthusiast communities for drones, camping equipment, and power tools drive weekend demand spikes and peer-to-peer trust formation through shared interest signals.
- Startups:Early-stage companies leverage P2P platforms for temporary office space and vehicle fleets to preserve capital against equity dilution.
Individual Renters anchor transaction volume, while Small Businesses deliver the most predictable recurring revenue expansion.
Monetization Model:
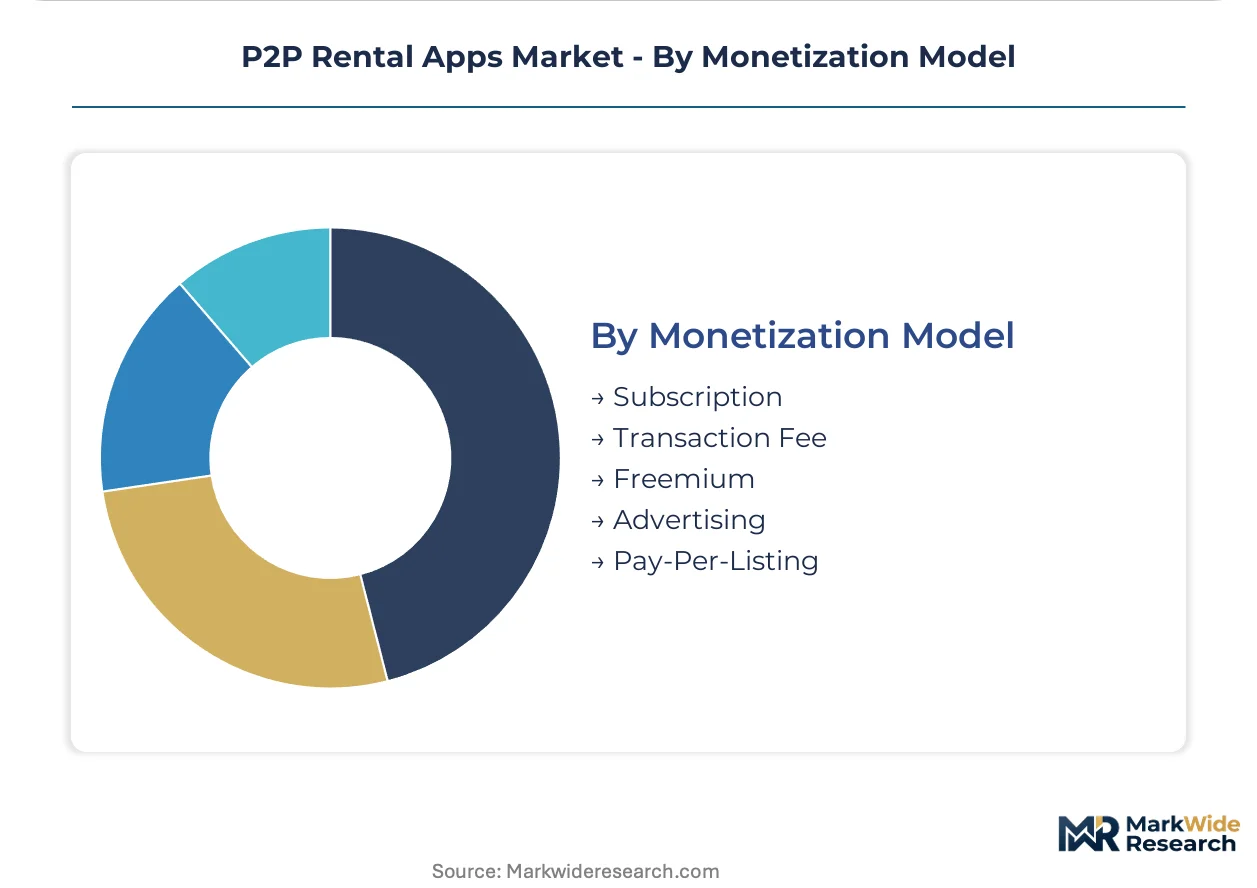
Revenue architecture selection determines working capital intensity and host relationship dynamics, with transaction fees scaling with marketplace liquidity and subscriptions locking in supply-side commitment.
- Subscription:Monthly or annual access fees guarantee availability without per-booking friction, generating predictable cash flows that reduce customer acquisition cost pressure.
- Transaction Fee:Percentage-based commissions on gross booking value align platform incentives with host success and dominate revenue architecture across major marketplaces.
- Freemium:Tiered feature access converts casual listers to paid tiers through enhanced visibility, priority support, and reduced commission rates.
- Advertising:Sponsored placement and host-promoted listings capture incremental revenue from supply-side competition for consumer attention.
- Pay-Per-Listing:Upfront posting fees shift risk to hosts and suit categories with low booking probability or high asset values where commission uncertainty deters participation.
Transaction Fee structures command the dominant position, with Subscription models gaining share fastest among urban professional segments seeking usage predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating platform development in jurisdictions with clearer liability frameworks and lower compliance friction. The United States and select European markets attract operator headquarters while enforcement-heavy municipalities drive host inventory underground.
United States
Urban millennial density in New York, Los Angeles, and Austin sustains property and vehicle sharing liquidity. The FTC scrutinizes platform fee transparency and host earnings disclosures, creating compliance costs that favor scaled operators. Miami and Nashville emerge as host acquisition battlegrounds where inventory growth outpaces regulatory enforcement capacity.
Germany
Corporate fleet managers in Berlin and Munich activate dormant vehicle assets through white-label platform partnerships. The EU Digital Services Act imposes algorithmic transparency requirements that reshape ranking and delisting protocols. Hamburg's hospitality sector experiments with hybrid property management systems integrating peer-to-peer distribution channels.
United Kingdom
Equipment leasing demand concentrates in London's creative industries and Manchester's construction corridors. The Financial Conduct Authority monitors payment escrow licensing for marketplace operators. Bristol and Edinburgh develop localized inventory depth strategies for specialty item categories.
France
Short-term rental caps in Paris and Bordeaux restrict inventory growth in high-demand urban cores. Housing advocates pressure regulators to prioritize long-term tenancy visibility over commercial listings. Lyon and Nice attract platform investment through less restrictive zoning enforcement.
India
Unified Payments Interface ubiquity enables escrow-free transactions reducing platform working capital requirements. The RBI monitors digital lending integrations within rental marketplaces. Bangalore and Hyderabad emerge as mobile-first platform development centers serving domestic and export markets.
P2P Rental Apps Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue experience-based verticals and subscription access models. The market structure concentrates around property rental and vehicle sharing platforms with sufficient liquidity to sustain network effects. Three archetypes dominate: global marketplace operators with cross-vertical expansion, specialized equipment leasing platforms with localized inventory depth, and regional vehicle sharing networks with proprietary insurance partnerships. Competitive moves center on dynamic pricing algorithm deployment and embedded insurance API integration.
Within the global marketplace tier, Airbnb and Booking.com exemplify scale-driven network effects across property and experience categories. Turo anchors the vehicle sharing segment through insurance partnerships and demand-based pricing infrastructure. Fat Llama occupies the specialized equipment position with density-focused strategies in creative industry corridors.
| Leading Market Players |
|---|
| Airbnb |
| Booking.com |
| Turo |
| Getaround |
| Outdoorsy |
| RVshare |
| Fat Llama |
| ShareGrid |
| Vrbo |
| Others |
Pricing and Supply Chain Analysis
Urban millennial demand for instant booking and embedded insurance coverage forces platforms to absorb escalating compliance and verification costs, compressing take rates and pushing operators toward subscription models that lock in predictable revenue streams.
Pricing Analysis
Input-cost pass-through from supplemental commercial insurance and licensed payment escrow partnerships intensifies margin pressure across vehicle-sharing and property-rental tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by verification depth, response time guarantees, and host support access. Cost compression in the standard tier is intensifying because embedded API licensing fees scale with transaction volume. Small businesses exhibit the lowest price sensitivity due to subscription-locked availability guarantees, while individual renters churn rapidly when platform fees exceed perceived value thresholds.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers and proprietary fraud-detection algorithm vendors that dominate platform backend architecture. Supply concentrates in the United States, Ireland, and Singapore for data center hosting and identity-verification API services. Platform operations draw from payment processor networks, commercial insurance underwriters, and mobile device sensor ecosystems. Regulatory restriction risk escalates as the EU Digital Services Act and FTC disclosure mandates fragment compliance requirements across jurisdictions. Distribution runs through app store gatekeepers and enterprise white-label partnerships that control customer acquisition pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where operators headquartered in liability-clarified jurisdictions like the United States capture host inventory from enforcement-heavy European cities where zoning preemption drives supply underground.
For Market Incumbents: Extend dynamic pricing algorithm deployment into experience-based verticals and subscription access models before emerging entrants capture urban professional segments. Consolidate position through proprietary insurance API integration that raises switching costs for multi-homing hosts. Vertical integration into payment licensing reduces escrow dependency and defends margin position against fintech entrants. For New Entrants and Emerging Players: Machine-learning fraud detection with sub-90-second onboarding latency offers a technology-first wedge against incumbent verification bottlenecks. Target India's UPI-enabled escrow-free transaction infrastructure and Germany's corporate fleet conversion white-label partnerships as the most penetrable geographies. Pursue equipment leasing density in secondary creative industry corridors rather than geographic breadth expansion. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized equipment platforms possessing localized inventory depth and regional vehicle-sharing networks with captive insurance partnerships. Long-term viability hinges on regulatory arbitrage sustainability and host classification resolution across California, New York, and Illinois. Monitor FTC enforcement intensity and EU Digital Services Act implementation velocity as inflection indicators for platform operating cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance API Integration | Proprietary partnerships with commercial underwriters reduce host onboarding friction and catastrophic loss exposure. |
| Dynamic Pricing Algorithm Deployment | Hourly rate adjustments using weather and event data compress revenue optimization cycles beyond competitor capabilities. |
| Subscription Access Model Launch | Monthly membership structures lock in urban professional demand and reduce customer acquisition cost pressure. |
| Corporate Fleet White-Label Partnership | Enterprise hospitality and automotive assets activate dormant supply without platform engineering investments. |
| Machine-Learning Fraud Detection Investment | Neural network systems displace static document checks that deepfake submissions increasingly circumvent. |
Research Methodology
Direct dialogue with platform operators, host community managers, regulatory compliance officers, and payment infrastructure providers grounded the qualitative foundation. Secondary validation drew from FTC enforcement actions, EU Digital Services Act implementation guidance, SEC filings of marketplace operators, and app store commission structure disclosures. Bottom-up host inventory modeling and top-down gross booking value estimation triangulated market sizing across the analysis window.
Bottom-up volume projections aggregated host acquisition rates, listing activation ratios, and average transaction values by platform type and service offering. Segmentation dimensions modeled include platform architecture, asset category, target customer archetype, and monetization model. CAGRs derived from historical liquidity growth curves and regulatory scenario weighting. Forecast inputs incorporated urban millennial density clustering, municipal zoning preemption intensity, and embedded payment infrastructure maturity.
The model holds under stable regulatory classification of hosts as independent contractors; deviation in employee-status determinations across California, New York, or Illinois would shift platform operating cost structures materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.