
 Data Analytics in the Smart Home Market | 2026-2036
Data Analytics in the Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Data Analytics in the Smart Home Market Analysis
Residential energy management is decoupling from traditional security-driven smart home adoption as the dominant analytics use case. Amazon.com, Inc. leverages its Alexa ecosystem to anchor voice-activated data pipelines across thermostat and lighting endpoints. Google competes through Nest's machine learning layer that predicts occupancy patterns for HVAC optimization. Schneider Electric specializes in grid-edge analytics that extend its building automation expertise into residential energy dashboards.
Data analytics in the smart home encompasses the collection, processing, and actionable interpretation of sensor-generated behavioral and environmental data from connected residential devices, typically operating across edge-computing nodes and cloud architectures with latency thresholds below 100 milliseconds for real-time automation triggers. Its primary commercial purpose is to transform raw device telemetry into predictive operational commands that reduce energy expenditure, enhance occupant safety, and automate environmental control without continuous human intervention. Machine learning and IoT technology segments are capturing the fastest expansion as on-device inference reduces cloud dependency and enables sub-second response loops for critical health and safety events. Smart thermostats and smart cameras retain the deepest margin pools due to their hardware-software subscription bundling and recurring data services, while smart speakers face commoditization pressure from white-label voice platforms.
The EU AI Act and GDPR impose algorithmic explainability and data minimization obligations on smart home platforms processing biometric or behavioral data in European households. The FCC in the United States governs spectrum allocation for Zigbee, Thread, and Wi-Fi protocols that underpin device mesh networks, while the EPA's ENERGY STAR specifications shape thermostat analytics certification requirements that influence procurement decisions by utilities and builders. Stakeholders must monitor the divergence between EU-mandated transparency frameworks and US sectoral rules as this regulatory gap determines which analytics architectures achieve cross-border deployment scale.
Market Dynamics
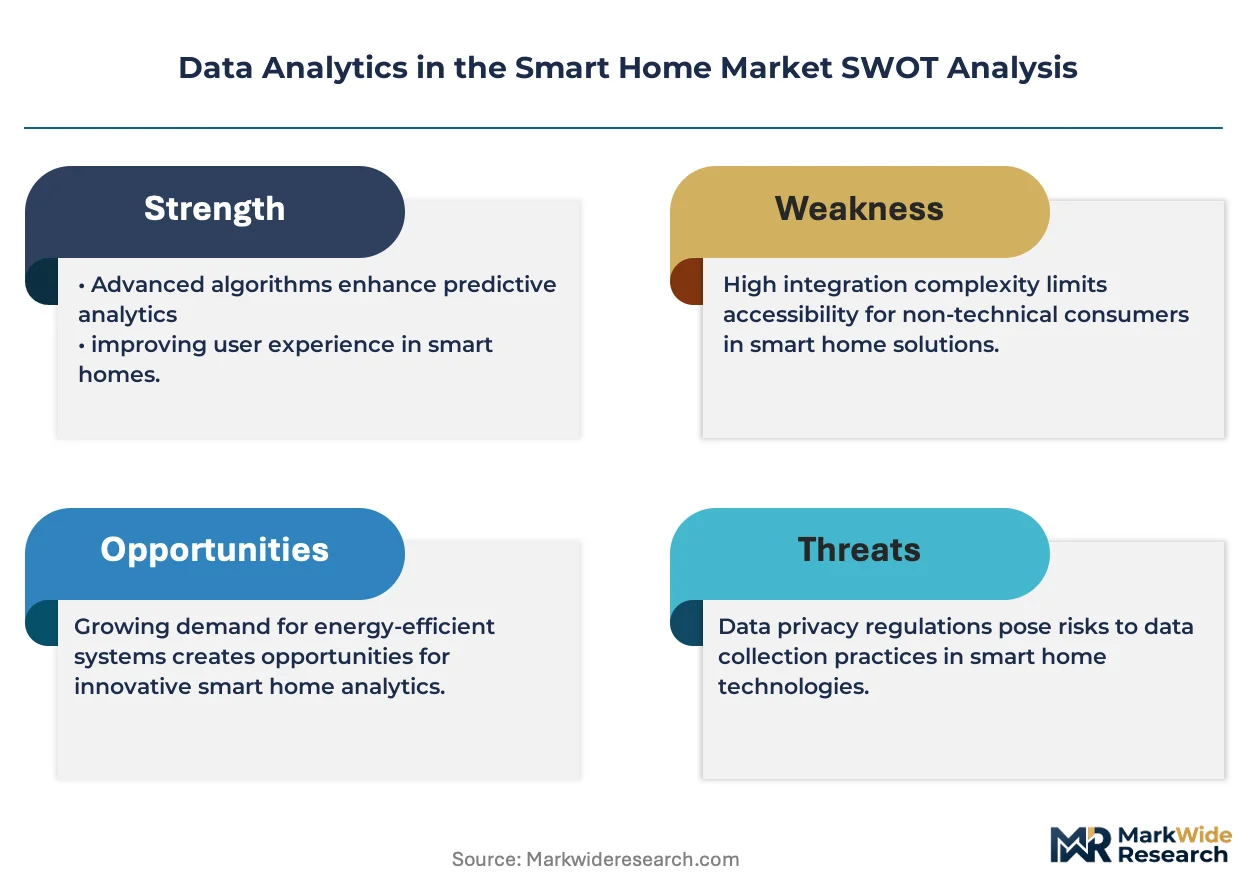
Energy management platforms are displacing security-first deployments as the dominant buyer use case, reshaping vendor R&D priorities and partnership structures across the residential analytics stack.
Growth Catalysts
- Utility-led smart meter rollouts:Germany's accelerated deployment programs are creating immediate demand for homeowner-facing analytics dashboards that visualize consumption patterns and enable demand-response participation.
- EU AI Act transparency mandates:Algorithmic explainability requirements for biometric and behavioral data processing are forcing platform upgrades that improve consumer trust and reduce churn.
- Edge computing latency thresholds:Sub-100 millisecond response requirements for safety-critical automation are driving silicon investment in on-device inference capabilities.
Market Restraints
- GDPR data minimization obligations:Strict retention limits and purpose limitation rules increase compliance overhead and constrain longitudinal behavioral modeling.
- White-label voice platform commoditization:Open-source alternatives to proprietary assistants are eroding hardware margins and subscription attach rates in the smart speaker category.
- Mesh network protocol fragmentation:Incompatibility between Zigbee, Thread, and proprietary stacks forces multi-radio hardware designs that inflate bill-of-materials costs.
Strategic Opportunities
- Grid-edge analytics convergence:Building automation expertise from commercial portfolios is transferring into residential energy dashboards, opening utility partnership channels.
- Occupancy prediction layering:Machine learning models that anticipate HVAC needs based on behavioral patterns enable premium subscription tiers with measurable energy savings.
- Health and safety event detection:Fall detection and anomaly recognition for aging-in-place populations represents an underpenetrated application with strong demographic tailwinds.
Industry Challenges
- Embedded machine learning talent scarcity:Shortage of engineers capable of optimizing neural networks for resource-constrained microcontrollers slows product development cycles.
- Cross-border certification complexity:Divergent FCC spectrum rules and EU cybersecurity labeling requirements force region-specific hardware variants that fragment manufacturing scale.
- Legacy thermostat replacement friction:Installation skill requirements and compatibility checking with existing HVAC infrastructure constrain self-service adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Analytics in the Smart Home Market |
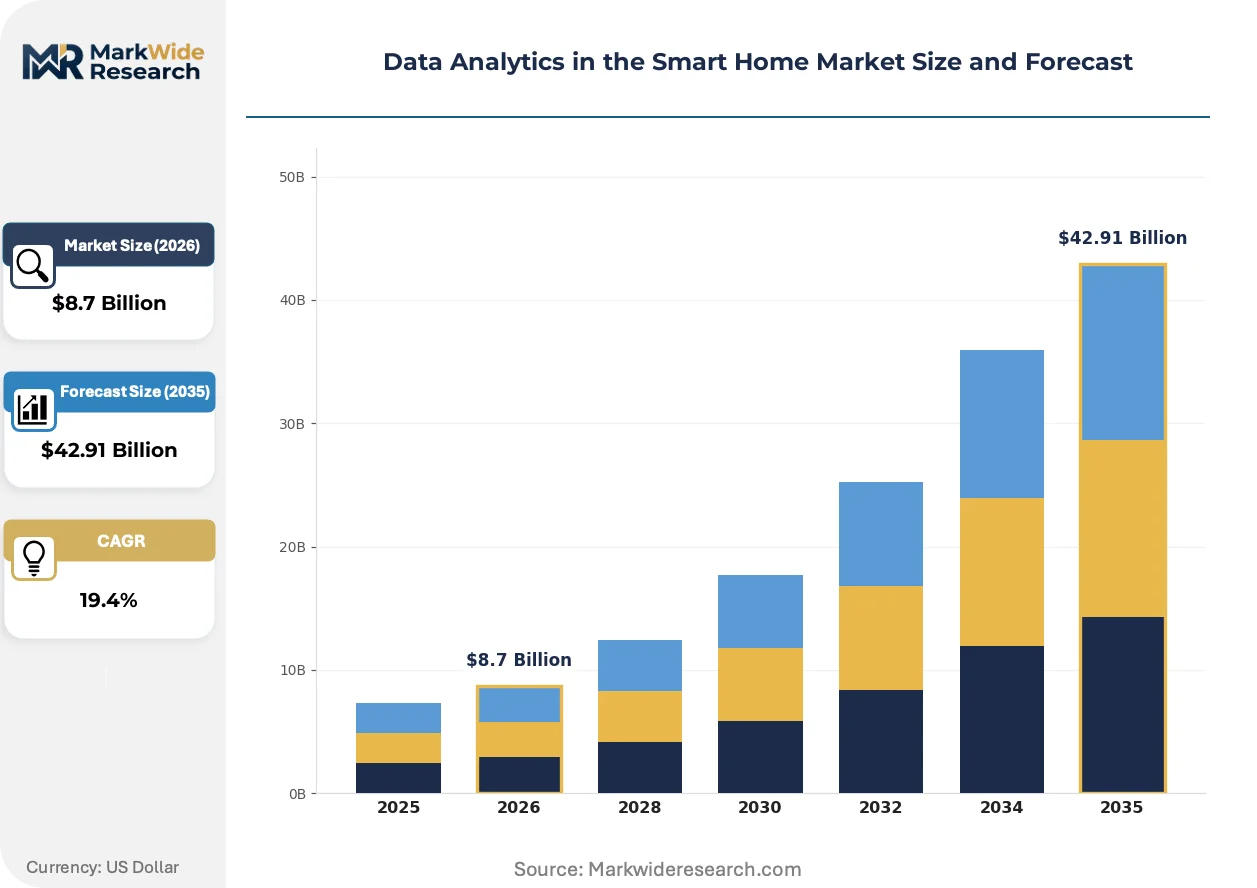
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Smart Cameras, Smart Lights, Smart Speakers Technology: Machine Learning, Big Data, IoT, Cloud Computing End User: Homeowners, Renters, Property Managers, Builders Application: Energy Management, Security Monitoring, Automation Control, Health Monitoring |
| Companies Covered | Amazon.com, Inc., Google, Apple Inc., Samsung Electronics Co. Ltd., Schneider Electric, Honeywell International Inc., Johnson Controls Inc., Siemens, Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Analytics in the Smart Home Market Emerging Trajectories
On-device inference is compressing cloud dependency while regulatory transparency mandates and shifting procurement authority are restructuring competitive positioning across the residential analytics value chain.
Edge AI accelerators are expanding into thermostat and camera endpoints to execute occupancy detection and anomaly recognition without round-trip latency to remote servers. Utilities and security monitoring services are adopting these capabilities fastest, prioritizing reliability over incremental cloud savings. This architecture shift is expanding into premium hardware tiers that command recurring software subscription revenue.
The EU AI Act's risk-based classification system imposes documentation and human oversight obligations on biometric identification and behavioral prediction systems deployed in European households. Platform operators must maintain technical files and conformity assessments that increase compliance costs but create barriers against non-compliant imports. Smart camera and voice assistant categories face the steepest adaptation requirements, with vendors restructuring data pipelines to satisfy algorithmic explainability audits.
Buying authority for residential analytics is migrating from individual homeowners toward utility procurement departments and homebuilder specification committees. Channel influence concentrates in energy efficiency program administrators who bundle hardware subsidies with installation services, displacing retail self-selection. This concentration is most advanced in Germany and California, where decarbonization mandates require new construction to meet strict consumption benchmarks that only integrated analytics platforms can reliably document.
Data Analytics in the Smart Home Market Segmentation
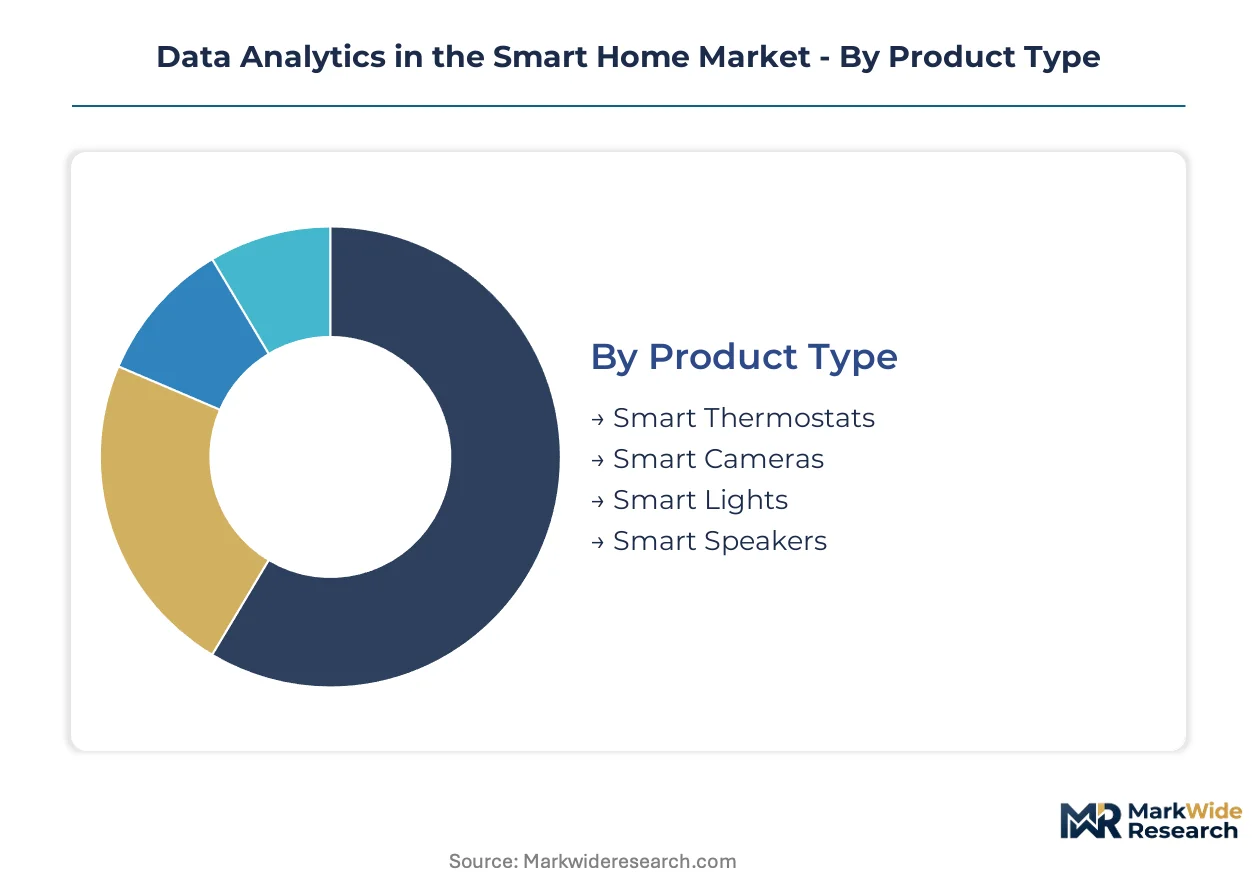
Segmentation in smart home analytics reveals how hardware margins, data pipeline architectures, and procurement authority diverge across buyer types and use cases. Understanding these splits exposes where subscription revenue concentrates and which technology layers face commoditization pressure.
Product Type:
Buyers prioritize devices that bundle recurring data services with hardware, creating tiered margin structures across the residential stack.
- Smart Thermostats:Temperature-sensing endpoints with occupancy detection algorithms and HVAC control integration. Demand concentrates among German homeowners participating in utility-led smart meter programs, where consumption visualization drives demand-response enrollment and hardware subsidy capture.
- Smart Cameras:Vision-based sensors with edge inference for motion detection and biometric identification. Property managers in multi-family housing deploy these fastest, pressured by insurance underwriters requiring documented security coverage and liability reduction.
- Smart Lights:Connected luminaires with color-temperature automation and circadian rhythm programming. Builders specify these in California new construction to meet Title 24 energy compliance with minimal installation complexity.
- Smart Speakers:Voice-activated hubs with natural language processing pipelines. White-label alternatives from Shenzhen manufacturers erode proprietary platform margins, compressing subscription attach rates.
Smart thermostats lead on scale; smart cameras lead on momentum.
Technology:
Processing location determines latency performance, cloud cost structure, and regulatory exposure across residential deployments.
- Machine Learning:Predictive algorithms trained on behavioral patterns to anticipate occupancy, energy demand, and anomaly events. On-device inference in thermostats and cameras reduces round-trip latency below 100 milliseconds for safety-critical automation triggers.
- IoT:Sensor mesh networks operating across Zigbee, Thread, and Wi-Fi protocols. Germany's utility sector adopts these fastest for grid-edge visibility into residential demand patterns.
- Big Data:Cloud-scale aggregation of cross-device telemetry for longitudinal behavioral modeling. GDPR data minimization rules constrain retention periods and purpose limitation in European deployments.
- Cloud Computing:Remote processing infrastructure for model training and cross-home pattern recognition. Energy management platforms favor hybrid architectures that shift non-critical workloads to cloud while preserving edge autonomy for real-time control.
IoT leads on installation volume; machine learning leads on R&D investment intensity.
End User:
Procurement authority is migrating from individual decision-makers toward institutional buyers with scale economics and compliance obligations.
- Homeowners:Individual residents purchasing through retail or utility channels. German homeowners accessing subsidized smart meter analytics represent the most concentrated demand pool.
- Builders:New construction specifiers integrating analytics platforms to meet decarbonization mandates. California builders face Title 24 requirements that only integrated energy dashboards can reliably document.
- Property Managers:Multi-family operators deploying security and energy systems across rental portfolios. Liability reduction and operational efficiency drive bulk procurement of camera and access control systems.
- Renters:Tenants with limited installation authority seeking portable or landlord-approved devices. Subscription-based services with minimal hardware footprint gain traction in this constrained segment.
Builders lead on contract value; homeowners lead on decision volume.
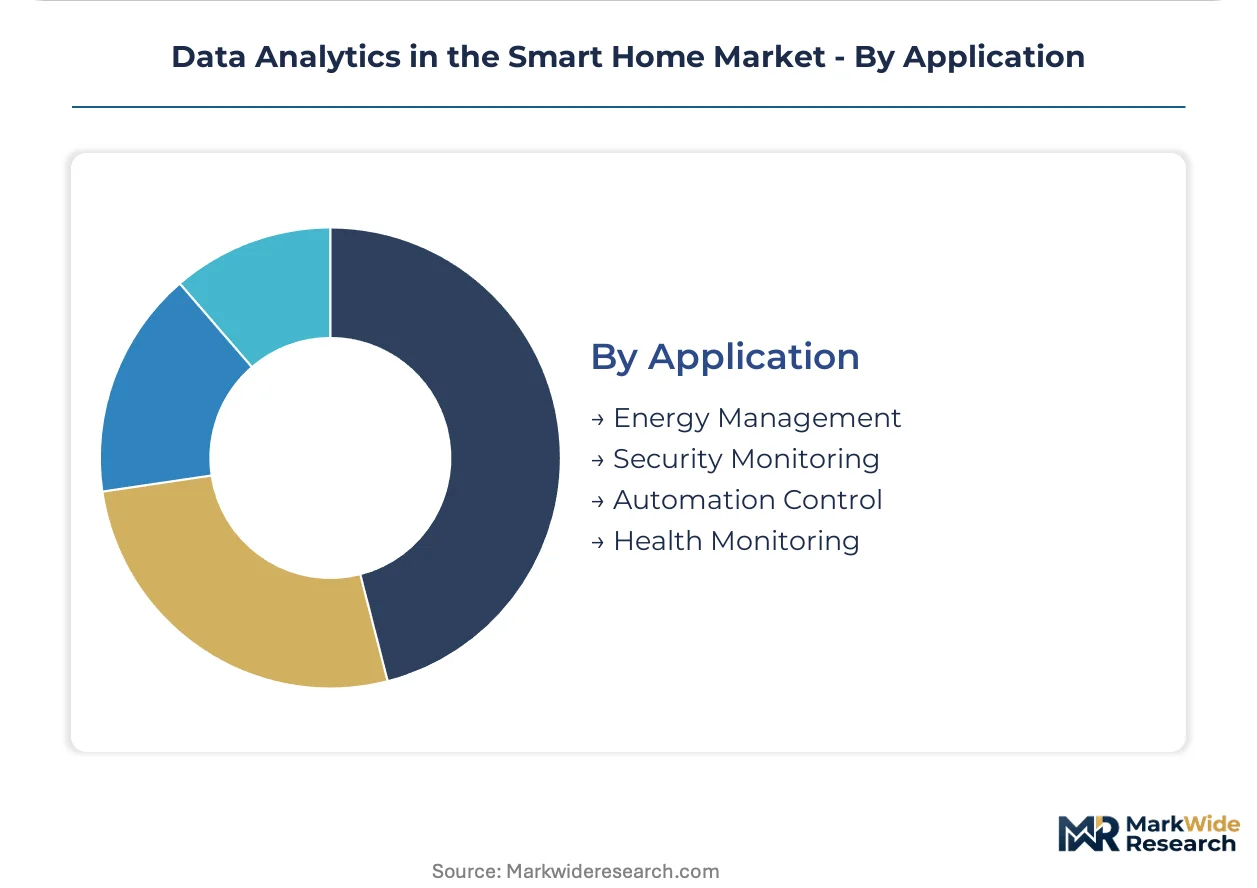
Application:
Use case priority is shifting from security-driven adoption toward energy optimization as decarbonization mandates reshape procurement criteria.
- Energy Management:Consumption monitoring, demand-response participation, and HVAC optimization. EU AI Act transparency requirements apply when behavioral prediction algorithms process usage patterns in European households.
- Security Monitoring:Intrusion detection, video verification, and emergency response triggering. GDPR biometric data rules impose strict purpose limitation and retention caps on camera analytics in EU member states.
- Automation Control:Cross-device orchestration of lighting, climate, and entertainment systems. Voice-activated pipelines face FCC spectrum governance for mesh network protocols in US deployments.
- Health Monitoring:Fall detection, activity pattern recognition, and aging-in-place safety alerts. Demographic tailwinds from aging populations in Germany and Japan expand addressable demand for this underpenetrated category.
Energy management leads on procurement growth; health monitoring leads on expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly and firmware customization to jurisdictions with lighter algorithmic transparency burdens, creating a compliance-cost arbitrage that favors North American and select Asian production bases over EU-facing operations.
United States
Utility procurement departments in California and Texas are bundling subsidized thermostats with demand-response programs. The FCC governs Zigbee and Thread spectrum allocation for mesh networks. Silicon Valley clusters concentrate voice-activated platform development, with Seattle-area operations anchoring cloud-scale behavioral modeling infrastructure.
Germany
Utility-led smart meter rollouts in Bavaria and North Rhine-Westphalia are accelerating homeowner analytics adoption. The EU AI Act imposes algorithmic explainability obligations on biometric identification systems deployed in residential settings. Berlin-Brandenburg hosts compliance-focused engineering centers adapting data pipelines for GDPR data minimization rules.
China
MIIT standards for IoT device interoperability are shaping export-bound hardware specifications. Shenzhen manufacturers dominate white-label voice platform production, eroding proprietary assistant margins. Pearl River Delta clusters specialize in edge AI accelerator silicon for camera and thermostat endpoints.
Japan
METI's carbon neutrality roadmap is driving builder specification of integrated energy dashboards in new construction. Aging-in-place demographics in Kansai and Kyushu are expanding demand for fall detection and health monitoring analytics. Tokyo-based electronics conglomerates anchor machine learning R&D for occupancy prediction algorithms.
United Kingdom
Ofcom spectrum licensing shapes Thread and Wi-Fi protocol deployment in connected home devices. London/Southeast clusters concentrate software development for property manager-facing security and energy platforms. Midlands manufacturing operations assemble hardware for export to EU markets, navigating post-Brexit regulatory divergence on cybersecurity labeling.
Data Analytics in the Smart Home Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem operators capturing recurring software revenue while hardware fabricators compete on cost and customization speed. The market exhibits tiered concentration: voice-activated platforms consolidate around three dominant assistants, while thermostat and camera hardware fragments across dozens of OEM suppliers. Two strategic archetypes dominate: vertically integrated ecosystem operators bundling hardware-software-subscription stacks, and component specialists supplying inference-optimized silicon to multiple brands. Competitive moves center on utility partnership exclusivity and edge AI accelerator co-development with semiconductor foundries.
Within the ecosystem-operator tier, Amazon.com, Inc. and Google exemplify contrasting approaches to voice-activated data pipeline architecture, while Schneider Electric occupies a position translating commercial building automation expertise into residential energy dashboards. These three anchors demonstrate how competitive positioning depends on whether players control the end-user interface, the underlying infrastructure, or the B2B procurement channel.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Schneider Electric |
| Honeywell International Inc. |
| Johnson Controls Inc. |
| Siemens |
| Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Embedded machine learning engineering talent concentrates in Shenzhen and Bangalore, with labor-cost differentials of 40-60% against Berlin or Seattle widening pricing-tier spreads between premium edge-AI thermostats and economy sensor hubs.
Pricing Analysis
Distributor margin layers absorb 15-25 points before retail markup, compressing OEM netbacks on white-label voice platforms while direct-to-utility contracts preserve fuller pricing realization for energy dashboard vendors. Pricing stratifies across premium, standard, and economy tiers keyed to edge inference latency performance and GDPR compliance certification depth. Cost compression in smart speakers intensifies as Shenzhen manufacturers flood channels with sub-$15 voice endpoints. Property managers demonstrate lowest price sensitivity, prioritizing liability reduction and insurance compliance over per-unit hardware cost.
Supply Chain Analysis
Returns and refurbishment flows for thermostat and camera endpoints concentrate in Pearl River Delta facilities, with remanufactured edge AI accelerators feeding secondary markets across Southeast Asia. Silicon fabrication draws from Taiwan and South Korea for inference-optimized microcontrollers, while final assembly rests on China, Vietnam, and Mexico. Single-source vulnerability in ARM-based edge processor supply threatens production continuity for sub-100 millisecond response devices. Distribution runs through utility procurement departments and homebuilder specification committees, displacing traditional retail channels in Germany and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as the EU AI Act's risk-based classification system forces platform upgrades, converting compliance overhead into competitive moats against non-conforming imports.
For Market Incumbents: Anchor ecosystem control through exclusive utility partnership locks in Germany and California, where decarbonization mandates concentrate procurement authority. Deepen backward integration into edge AI accelerator silicon via foundry co-development agreements. White-label voice platform commoditization threatens subscription attach rates; defend through proprietary occupancy prediction algorithms that command premium SaaS tiers. For New Entrants and Emerging Players: Launch via health monitoring specialization targeting Japan's Kansai and Kyushu aging-in-place demographics, the most penetrable white-space segment with demographic tailwinds and minimal incumbent saturation. Grid-edge analytics convergence opens utility partnership channels for building automation specialists without residential track records. Target builder specification committees in California Title 24 compliance-driven new construction. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists supplying inference-optimized silicon to multiple thermostat and camera OEMs, as ecosystem operators trade at subscription-revenue premiums. Long-term viability over the projection horizon hinges on cross-border certification capabilities that navigate FCC-EU regulatory divergence. Monitor ENERGY STAR specification updates and EU AI Act enforcement actions as inflection indicators for hardware subsidy flows and import barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Accelerator Co-Development | Foundry partnerships with TSMC or Samsung secure sub-100 millisecond inference capability for safety-critical automation triggers. |
| Utility Partnership Exclusivity | German utility-led smart meter rollouts concentrate procurement authority behind integrated energy dashboard vendors. |
| GDPR-Compliant Pipeline Restructuring | Algorithmic explainability audits satisfy EU AI Act biometric data obligations, creating import barriers against non-compliant platforms. |
| Health Monitoring Category Expansion | Fall detection specialization addresses Japan's aging-in-place demographics with underpenetrated demand and strong tailwinds. |
| White-Label Voice Platform Deflection | Proprietary natural language processing pipelines preserve subscription attach rates against Shenzhen manufacturer erosion. |
Methodological Framework
Coverage spans Germany, the United States, China, and Japan, with primary inputs from each market cluster combining executive interviews with smart home platform CTOs, utility demand-response program administrators, homebuilder specification directors, and edge AI semiconductor procurement leads. Secondary validation draws from FCC spectrum allocation filings, EU AI Act implementation guidance, ENERGY STAR certification databases, and MIIT IoT interoperability standards. Bottom-up device shipment modeling triangulates against top-down energy management platform revenue aggregation.
Granularity-level modeling disaggregates the market across product type, processing technology, end-user procurement authority, and application use case, with regional regulatory framework clusters as an additional cross-cutting dimension. CAGRs derive from logistic diffusion curves fitted to smart meter deployment schedules and builder mandate compliance timelines. Forecast inputs incorporate utility subsidy program budgets, edge AI silicon foundry capacity expansion announcements, and GDPR enforcement action intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement acceleration or Zigbee-Thread protocol consolidation shocks. Practitioners should monitor German Bundesnetzagentur smart meter rollout pace, California Title 24 amendment cycles, and edge AI accelerator lead time quotations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Pipeline Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
UAE ICT Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Construction Design App Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
In-App Purchase Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Business Information Market