
 Application Modernization Services Market | 2026-2036
Application Modernization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Application Modernization Services Market Intelligence
Asset-light subscription and consumption-based financing is tilting competitive dynamics toward providers with scalable cloud delivery platforms. Accenture leverages its global systems integration footprint to capture enterprise transformation budgets. IBM sustains relevance through deep mainframe modernization expertise and hybrid cloud orchestration. Capgemini competes by embedding sustainability metrics into modernization roadmaps for European clients.
Application modernization services encompass the assessment, migration, refactoring, and re-architecture of legacy software systems to cloud-native, microservices-based, or containerized environments, typically involving code conversion, database replatforming, and API layer reconstruction to improve scalability, security, and interoperability. The primary purpose is to extend functional lifespan of critical business applications while reducing technical debt and operational maintenance burden. Rehosting currently occupies the largest revenue share as enterprises prioritize low-risk lift-and-shift migrations, though refactoring is accelerating fastest as organizations seek to extract cloud-native performance gains from existing codebases. Hybrid cloud deployment models dominate procurement decisions among regulated industries requiring data sovereignty controls.
FDA 21 CFR Part 11 validation requirements shape healthcare sector modernization timelines and documentation standards, while EU GDPR and the EU AI Act impose algorithmic accountability and data residency constraints on cross-border application deployments. NIST cybersecurity frameworks and SEC disclosure rules for material cyber incidents further tighten compliance scope for financial services modernization programs. Stakeholders must weigh the trade-off between speed-to-cloud and regulatory audit trail completeness when selecting service partners and architecture patterns.
Market Dynamics
Cloud-native mandates from the EU AI Act and similar algorithmic accountability frameworks are forcing enterprises to restructure IT estates, compressing multi-year modernization timelines into urgent compliance-driven programs. Federal procurement in the United States is amplifying this pressure through defense contractor requirements.
Growth Catalysts
- FDA 21 CFR Part 11:Healthcare sector validation requirements are extending functional lifespans of critical clinical systems while mandating comprehensive audit trails for electronic records.
- Microservices architecture:Container orchestration platforms are enabling financial services firms to decompose monolithic core banking systems into API-driven service meshes.
- United States federal spending:Defense contractor modernization programs and civilian agency cloud-first directives are concentrating demand in the Washington-Arlington technology corridor.
Market Restraints
- COBOL and assembly language scarcity:The contracting pool of developers proficient in legacy mainframe codebases is inflating specialist labor costs and extending project timelines.
- Cross-border data friction:EU GDPR residency constraints and algorithmic accountability requirements are complicating multi-tenant cloud architectures for US-headquartered service providers.
- Hybrid cloud complexity:Persistent technical debt from on-premise mainframe integrations is constraining seamless workload portability across distributed environments.
Strategic Opportunities
- India's digital public infrastructure:The country's national cloud and API standards are creating localized modernization demand from banking and telecommunications sectors.
- AI-assisted code transformation:Large language model tools paired with automated refactoring engines are compressing assessment-to-migration cycles for Java and .NET workloads.
- Outcome-based consumption models:Subscription financing tied to measurable technical debt reduction is displacing fixed-scope professional services contracts in mid-market manufacturing.
Industry Challenges
- Site reliability engineering talent:Shortages of practitioners skilled in Kubernetes, observability tooling, and chaos engineering are throttling delivery capacity across service providers.
- NIST cybersecurity framework alignment:Documentation and control mapping for zero-trust architecture implementations is extending compliance timelines for financial services clients.
- API layer reconstruction complexity:Reconciling disparate authentication protocols and data schemas across acquired legacy systems is consuming disproportionate integration resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Modernization Services Market |
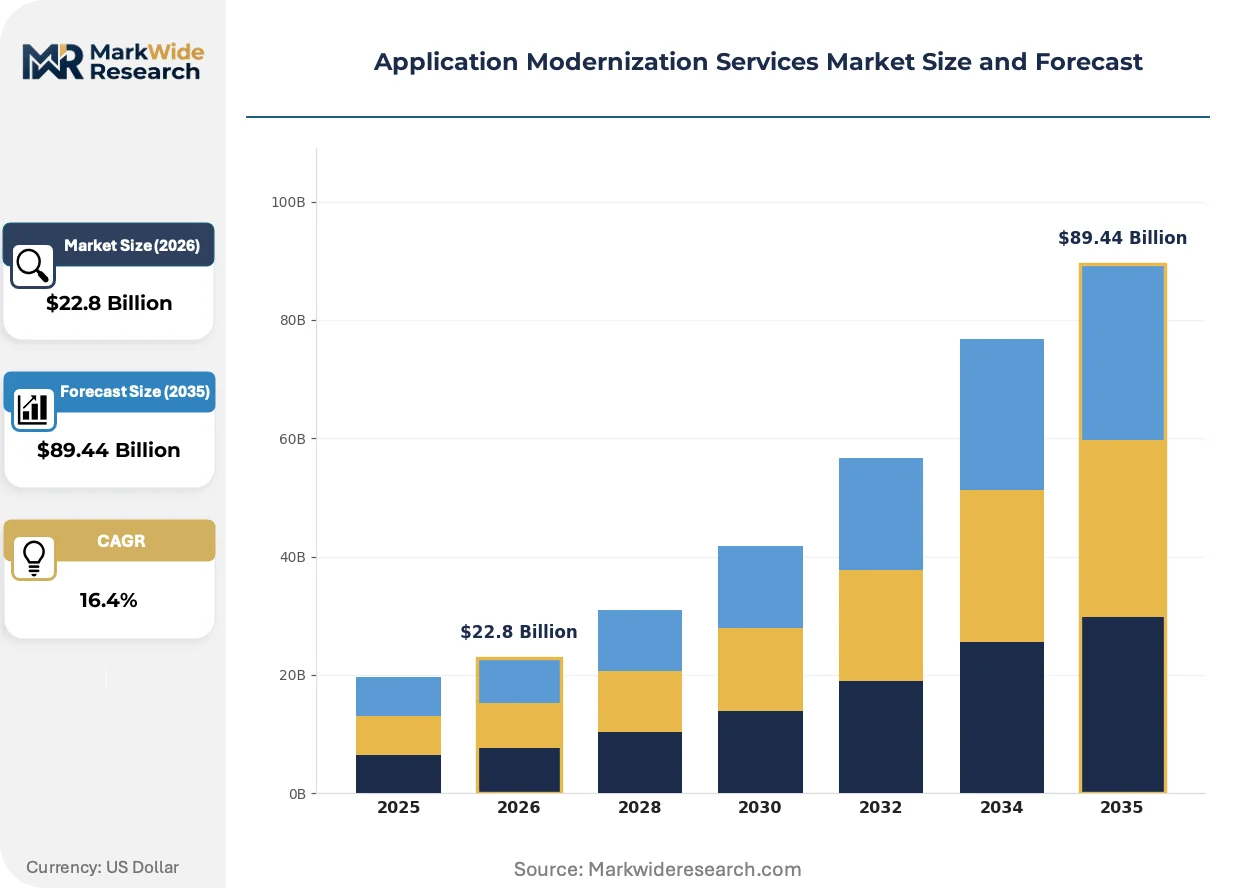
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $89.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rehosting, Refactoring, Rebuilding, Replacing Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Healthcare, Financial Services, Retail, Telecommunications Technology: Microservices, Containers, Serverless, API Management |
| Companies Covered | Infosys, Rocket Software, Accenture, Intellectsoft, ScienceSoft, Capgemini, Cognizant, 10Pearls, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Modernization Services Market Strategic Shifts & Innovations
Generative AI tools are penetrating code assessment and transformation workflows, while regulatory pressure on algorithmic systems is reshaping architecture requirements. Service delivery models are pivoting toward continuous modernization rather than discrete project engagements.
Container orchestration is hybridizing enterprise infrastructure by enabling portable workloads across on-premise data centers, sovereign cloud regions, and hyperscaler environments. Financial services institutions in Germany and Singapore are deploying this pattern to satisfy data residency requirements while accessing elastic compute. The technology is hybridizing procurement decisions by collapsing distinctions between private and public cloud capital allocation.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk automated decision-making systems deployed in credit scoring and insurance underwriting. Enterprises must reconstruct audit trails and explainability layers within existing application stacks. Healthcare providers in France and the Netherlands are prioritizing MDR-aligned quality management systems to preempt algorithmic accountability enforcement.
Continuous modernization subscriptions are displacing fixed-scope transformation contracts as buyers demand ongoing technical debt monitoring and incremental refactoring. Industrial manufacturers in the US Midwest are unbundling modernization from capital expenditure cycles through operating-lease structures. This pattern is most visible in automotive supplier networks where quarterly software release cadences have replaced multi-year platform replacements.
Application Modernization Services Market Segmentation
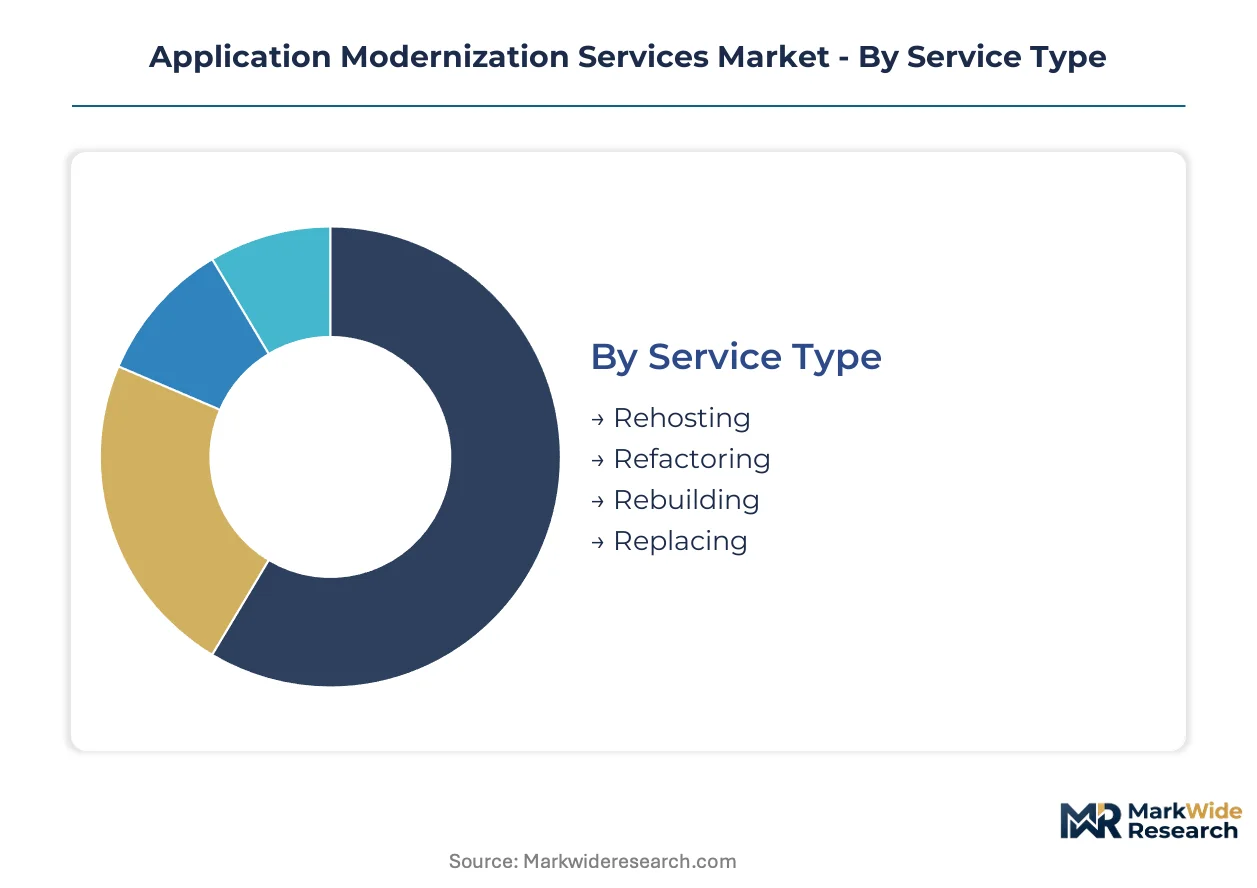
Segmentation reveals how modernization strategies diverge across technical maturity, regulatory exposure, and infrastructure constraints. Service buyers select transformation pathways based on risk tolerance, compliance mandates, and existing technical debt profiles.
Service Type:
After-sales engineering intensity varies sharply across service types, with refactoring demanding sustained architectural oversight while rehosting requires minimal ongoing intervention.
- Rehosting:Lift-and-shift migration preserves existing application logic while relocating workloads to cloud infrastructure without code modification. Financial services firms in the United States favor this approach for core banking systems where FDA-level audit trail preservation is not required but SEC disclosure readiness remains paramount.
- Refactoring:Code restructuring extracts cloud-native performance gains through microservices decomposition and containerization without functional changes. German automotive suppliers and Dutch healthcare providers are accelerating refactoring investments to satisfy EU AI Act algorithmic accountability requirements for high-risk automated decision systems.
- Rebuilding:Complete application reconstruction using modern technology stacks.
- Replacing:Substitution with commercial off-the-shelf or SaaS alternatives.
Rehosting holds the largest share; momentum sits with refactoring.
Deployment Model:
Cost tier stratification separates hyperscaler-dependent public deployments from capital-intensive private infrastructure, with hybrid configurations capturing mid-tier procurement budgets.
- Hybrid Cloud:Distributed workload placement across on-premise, sovereign cloud, and hyperscaler environments enables data residency compliance. Singaporean banks and French insurers deploy this model to reconcile GDPR constraints with elastic compute access.
- Public Cloud:Shared infrastructure delivered by hyperscale providers offers consumption-based scaling without capital commitment.
- Private Cloud:Dedicated single-tenant infrastructure satisfies classified workload requirements.
- On-Premises:Legacy data center retention for mainframe-dependent systems.
Hybrid Cloud dominates regulated verticals; Public Cloud is expanding most quickly among mid-market manufacturers.
End User:
Application complexity and regulatory burden segment end users by modernization urgency and available transformation budgets.
- Financial Services:Core banking system decomposition into API-driven service meshes addresses NIST cybersecurity framework alignment and SEC material incident disclosure obligations. US regional banks and Japanese securities firms prioritize this segment for customer-facing platform renewal.
- Healthcare:Clinical system modernization must preserve FDA 21 CFR Part 11 validation documentation while enabling interoperability. French and Dutch providers are reconstructing audit trails to preempt MDR-aligned quality enforcement.
- Retail:Commerce platform containerization for seasonal demand elasticity.
- Telecommunications:OSS/BSS transformation for 5G service orchestration.
Financial Services commands the deepest modernization budgets; Healthcare shows the steepest expansion trajectory.
Technology:
Architectural maturity separates container orchestration leaders from serverless adopters and API management consolidators.
- Microservices:Fine-grained service decomposition enables independent deployment cadences and technology heterogeneity. Indian banking and telecommunications sectors are standardizing on national API frameworks that presuppose microservices patterns.
- Containers:Portable runtime packaging collapses distinctions between development and production environments. German manufacturing networks and Singaporean logistics operators deploy Kubernetes-based orchestration for workload portability across sovereign cloud boundaries.
- Serverless:Event-driven compute abstraction eliminating infrastructure management.
- API Management:Unified governance layer for authentication, rate limiting, and schema reconciliation.
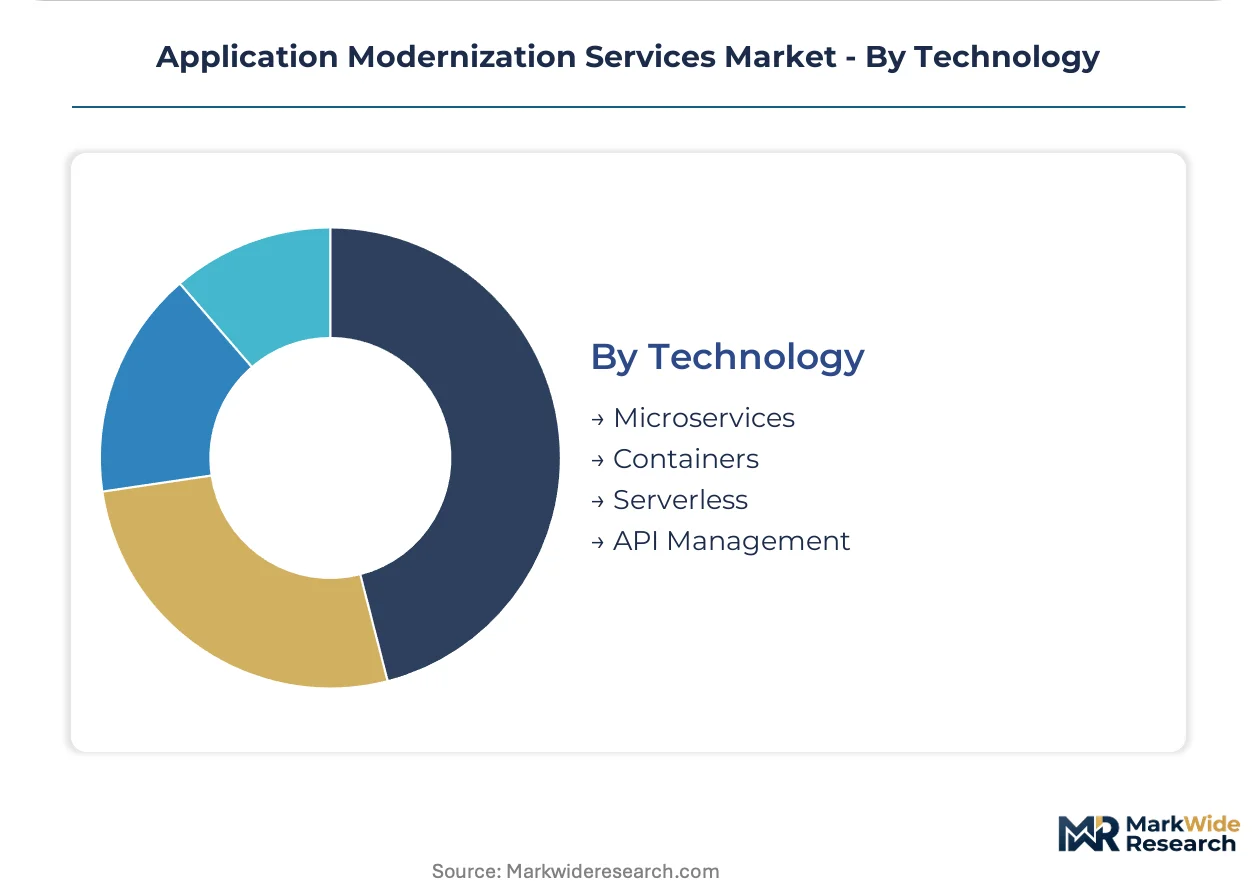
Containers hold the largest share; momentum sits with microservices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal cloud-first directives and algorithmic accountability mandates are compressing modernization timelines across major economies. Procurement concentrates in technology corridors where defense spending intersects with financial services compliance requirements.
United States
Defense contractor modernization programs and civilian agency cloud mandates are driving demand concentration in the Washington-Arlington corridor. SEC disclosure rules for material cyber incidents and NIST cybersecurity frameworks tighten compliance scope for financial services. Regional banks across the Midwest and Southeast prioritize core banking system decomposition to meet these obligations.
Germany
Automotive suppliers and industrial manufacturers are accelerating refactoring investments to satisfy EU AI Act algorithmic accountability requirements. The country's national cloud standards and GDPR residency constraints favor hybrid deployment models. Manufacturing networks in Bavaria and Baden-Württemberg deploy Kubernetes orchestration for workload portability across sovereign boundaries.
India
National cloud and API standards are creating localized modernization demand from banking and telecommunications sectors. RBI guidelines and the country's digital public infrastructure framework mandate interoperability layers. Technology clusters in Karnataka and Maharashtra standardize on microservices patterns aligned with national API frameworks.
Singapore
Financial institutions deploy hybrid cloud configurations to reconcile data residency requirements with elastic compute access. The Monetary Authority of Singapore's technology risk management guidelines shape procurement decisions. Banking and logistics operators in the city-state leverage container orchestration for cross-border workload placement.
France
Healthcare providers prioritize MDR-aligned quality management systems to preempt algorithmic accountability enforcement. CNIL guidance on automated decision-making systems shapes credit scoring and insurance underwriting modernization. Clinical systems in the Île-de-France region reconstruct audit trails to preserve FDA-equivalent validation documentation.
Application Modernization Services Market Key Industry Players
Channel-controlling players compete with product-specialist players for enterprise transformation budgets. The market structure tilts toward consolidated systems integrators with scalable cloud delivery platforms, though specialist boutiques retain pockets of differentiation. Three archetypes dominate: global consultancies with hybrid cloud orchestration capabilities, mainframe modernization specialists with deep legacy codebase expertise, and sustainability-embedded advisors targeting European compliance requirements. Competitive moves concentrate on outcome-based consumption models and AI-assisted code transformation tooling.
Among global systems integration providers, Accenture, IBM, and Capgemini occupy distinct positioning vectors. Accenture exemplifies the scale-driven archetype through its enterprise transformation footprint. IBM anchors the legacy-specialist tier with mainframe modernization depth. Capgemini represents the sustainability-embedded advisor model for European regulatory contexts.
| Leading Market Players |
|---|
| Infosys |
| Rocket Software |
| Accenture |
| Intellectsoft |
| ScienceSoft |
| Capgemini |
| Cognizant |
| 10Pearls |
| IBM |
| Others |
Cost & Logistics Intelligence
The Washington-Arlington technology corridor concentrates delivery capacity for defense contractor modernization programs, compressing specialist labor rates and amplifying pricing power for providers with FedRAMP-authorized platforms. This geographic concentration of cleared engineering talent feeds directly into project cost structures across federal and civilian agency procurement.
Pricing Analysis
Certification level (FedRAMP/NIST-800-53/FDA 21 CFR Part 11-grade) creates the primary spread between premium and standard service tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with compliance-bundled engagements commanding substantial premiums over lift-and-shift rehosting. Cost compression in mid-market manufacturing subscriptions is intensifying because outcome-based consumption models displace fixed-scope professional services contracts. Healthcare providers show least price sensitivity due to FDA validation documentation requirements, while retail commerce platforms exhibit highest sensitivity to per-workload unit economics.
Supply Chain Analysis
Upstream feedstock of COBOL and assembly language proficiency draws from India, the United States, and select Eastern European talent pools. Specialist labor scarcity rests on decades of educational pipeline neglect in mainframe-era programming languages. Supply chain risk centers on single-source vulnerability for cleared personnel serving defense contractor requirements. Distribution runs through global systems integrators with scalable cloud delivery platforms, though specialist boutiques retain niche differentiation in legacy codebase expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application modernization services constitute a platform-economics inflection where API-layer standardization and continuous integration pipelines are collapsing traditional project-based procurement into ongoing subscription relationships.
For Market Incumbents: Build certification moats around FedRAMP High and FDA 21 CFR Part 11 validation capabilities to defend against hyperscaler direct engagement models. Deepen mainframe modernization expertise through targeted acquisition of COBOL specialist boutiques in Eastern Europe. Channel control through embedded sustainability metrics for European regulatory contexts anchors retention against outcome-based competitors. For New Entrants and Emerging Players: India's digital public infrastructure presents underpenetrated white space where national API standards and RBI guidelines mandate interoperability layers unfamiliar to Western-centric providers. Target mid-market automotive suppliers in Bavaria and Baden-Württemberg with Kubernetes-native refactoring offerings priced below Accenture and IBM enterprise rates. Lead with AI-assisted code transformation tooling to compress assessment-to-migration cycles as the primary go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-utility play because algorithmic accountability mandates from the EU AI Act and similar frameworks are structurally embedding recurring modernization expenditure into enterprise operating budgets. Acquisition targets should profile as mainframe modernization specialists with deep legacy codebase expertise and existing FDA or FedRAMP certifications. Monitor defense contractor procurement velocity and civilian agency cloud-first directive implementation pace as the critical inflection signal for demand cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | FedRAMP-authorized cloud delivery platforms capture federal agency modernization budgets. |
| Acquisition of Specialist Firm | COBOL and assembly language boutiques in Eastern Europe secure legacy codebase capabilities. |
| Strategic Partnership | Hyperscaler alliances enable sovereign cloud workload placement for GDPR-constrained European clients. |
| Geographic Expansion | India's national cloud standards create localized demand from banking and telecommunications sectors. |
| Product Launch | AI-assisted code transformation tools compress Java and .NET assessment-to-migration cycles. |
Research Approach
Cross-validation between primary interviews with IT procurement officers, platform engineers, and channel partners anchors the qualitative findings against secondary validation from SEC filings, hyperscaler capex disclosures, and federal procurement databases. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical modernization spend patterns and regulatory implementation timelines shapes the projection framework. Segmentation dimensions include service type, deployment model, end-user vertical, and technology stack complexity. CAGRs derive from elasticity-adjusted demand curves incorporating EU AI Act compliance deadlines and NIST cybersecurity framework adoption curves.
Practitioners should monitor defense contractor procurement velocity, EU AI Act enforcement precedents, and COBOL talent pipeline indicators for early signals of forecast revision. Cross-checking against federal IT spending dashboards and hyperscaler revenue segment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Game Engines Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Online Voting System Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Global Domain and Hosting Market