
 Global Smartphone Sensors Market | 2026-2036
Global Smartphone Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartphone Sensors Market Outlook
Specialized MEMS process engineering talent is rotating from European semiconductor institutes toward Asian foundry ecosystems. STMicroelectronics leverages captive 8-inch MEMS fabs in Italy and Singapore to sustain vertical integration in motion sensors. Sony Corporation anchors high-end CMOS image sensor supply through proprietary stacked-die architectures. Bosch Sensortec GmbH competes on environmental sensor fusion software that integrates barometric pressure with inertial measurement units.
Smartphone sensors are microelectromechanical or solid-state transducers that convert physical stimuli—acceleration, angular velocity, electromagnetic flux, or photon intensity—into electrical signals for digital processing, typically fabricated on silicon wafers using bulk micromachining or CMOS backside-illumination processes with pixel pitches below one micron. Their primary commercial purpose is to enable real-time environmental awareness and user-interface responsiveness in handheld computing devices. MEMS technology dominates unit volume due to decades of cost curve optimization, while optical sensors command disproportionate margin pools in flagship camera modules. Capacitive sensing retains share in fingerprint authentication, though ultrasonic alternatives are gaining traction in premium tier devices.
FCC equipment authorization rules in the United States shape radio-frequency sensor integration timelines, while REACH and RoHS compliance in Europe constrains material selection for piezoelectric elements. China's SAMR enforces national standard GB/T specifications for sensor accuracy in domestic handsets. India's BIS certification requirements for electronic components are tightening import gatekeeping. Stakeholders must monitor divergent electromagnetic compatibility test regimes as regional fragmentation of type-approval processes intensifies procurement complexity.
Market Dynamics
OEM procurement of advanced imaging arrays is concentrating sensor demand into South Korean foundry ecosystems, while EU Ecodesign requirements and China's GB standards are tightening energy-efficiency benchmarks for MEMS devices.
Growth Catalysts
- Computational Photography Arrays:Flagship smartphone OEMs are sourcing larger optical formats and multi-sensor fusion modules for low-light performance and depth mapping.
- REACH and RoHS Compliance:European material restrictions are accelerating substitution of lead-based piezoelectric elements with compliant alternatives, driving process innovation.
- Vietnam Assembly Corridors:Contract manufacturers are expanding surface-mount capacity for MEMS inertial units, reducing logistics costs for ASEAN-bound handsets.
Market Restraints
- 8-inch MEMS Wafer Scarcity:Dedicated MEMS foundry capacity is concentrating in Italian and Singaporean fabrication sites, creating allocation bottlenecks for motion sensor suppliers.
- FCC Equipment Authorization Timelines:Radio-frequency sensor integration faces extended type-approval cycles in the United States, delaying product launches.
- Ultrasonic Fingerprint Alternatives:Capacitive biometric sensors face displacement pressure from piezoelectric acoustic solutions in premium device tiers.
Strategic Opportunities
- India BIS Certification Gatekeeping:Import restrictions on electronic components are creating captive demand for locally tested sensor modules.
- Environmental Sensor Fusion:Barometric pressure integration with inertial measurement units is opening new application layers in fitness and navigation.
- Stacked-die CMOS Architectures:Backside-illumination processes with sub-micron pixel pitches are enabling new form factors in slim camera modules.
Industry Challenges
- MEMS Process Engineering Talent Migration:Specialized fabrication expertise is rotating from European semiconductor institutes toward Asian foundry ecosystems, depleting regional skill pools.
- Electromagnetic Compatibility Fragmentation:Divergent test regimes across FCC, ETSI, and MIIT jurisdictions are multiplying certification costs for multi-region product launches.
- Dual Carbon Goals in China:MEE enforcement of energy-efficiency standards is forcing yield optimization investments in MEMS cleanroom operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartphone Sensors Market |
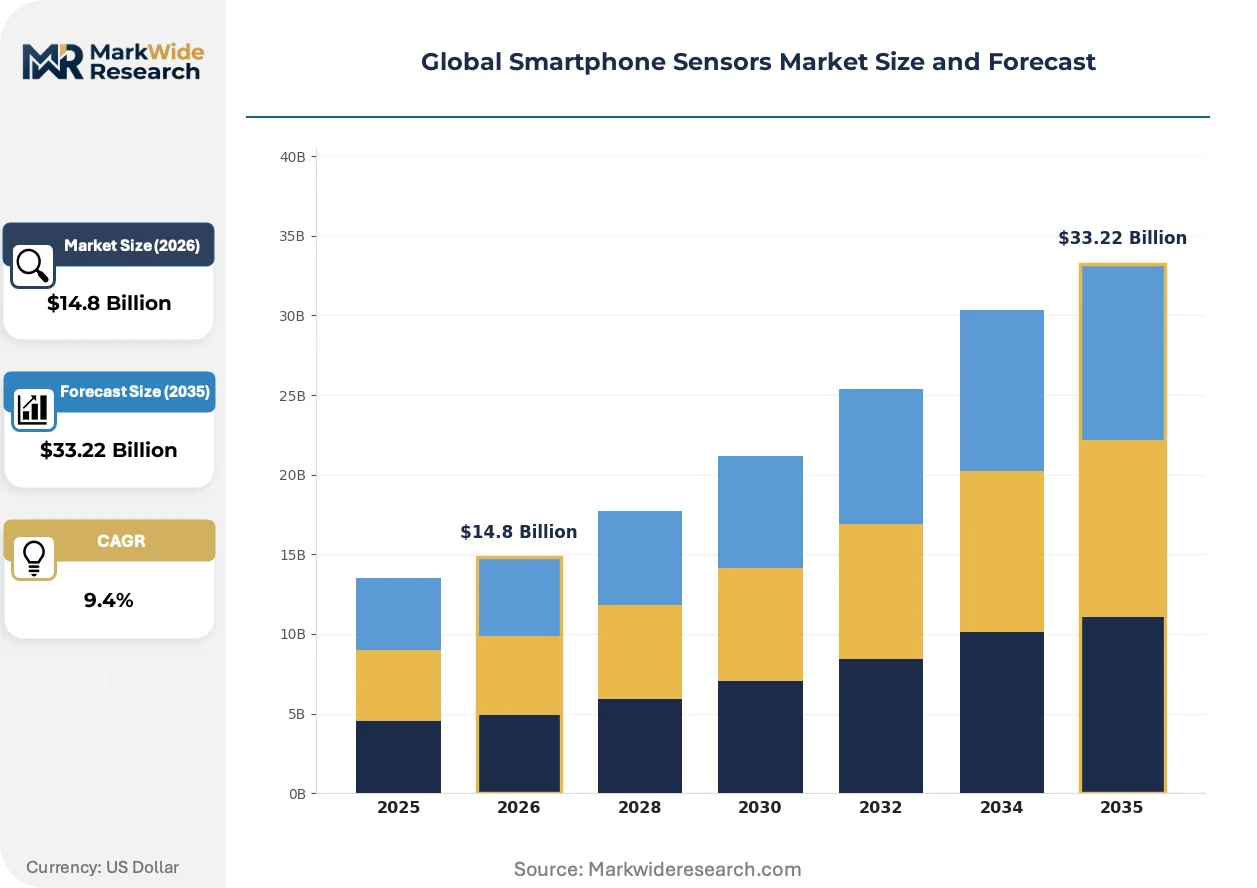
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Accelerometer, Gyroscope, Proximity, Ambient Light Application: Photography, Navigation, Fitness Tracking, Gaming Technology: MEMS, Optical, Ultrasonic, Capacitive End User: Consumers, Enterprises, OEMs, Developers |
| Companies Covered | Sony Corporation, Samsung Electronics, STMicroelectronics, Bosch Sensortec GmbH, OmniVision Technologies, Analog Devices, Texas Instruments, Infineon Technologies AG, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartphone Sensors Market Strategic Shifts
Sensor integration architectures are fragmenting as computational demands outpace monolithic silicon scaling. Three developments are compressing traditional supply relationships and reshaping procurement patterns.
Time-of-flight depth sensing is decomposing structured-light approaches in facial authentication and augmented reality applications. Flagship OEMs are adopting indirect time-of-flight arrays for sub-millimeter precision at reduced module thickness. This compression of optical path length is decomposing legacy dot-projector supply chains and reallocating margin toward vertical-cavity surface-emitting laser foundries.
China's GB/T sensor accuracy specifications are mandating calibration traceability for inertial measurement units in domestic handsets. SAMR enforcement is requiring documented temperature compensation across operating ranges. Domestic OEMs are responding by qualifying captive test facilities in Shenzhen and Beijing, while foreign suppliers face extended audit timelines.
Component distributors are unbundling sensor fusion software from hardware procurement. Tier-one EMS providers are licensing environmental sensor algorithms directly from Bosch Sensortec and STMicroelectronics, bypassing traditional module vendor markups. This disintermediation is most visible in South Korean smartphone supply chains, where LG Innotek and Samsung Electro-Mechanics are defending position through captive software stacks.
Global Smartphone Sensors Market Segmentation
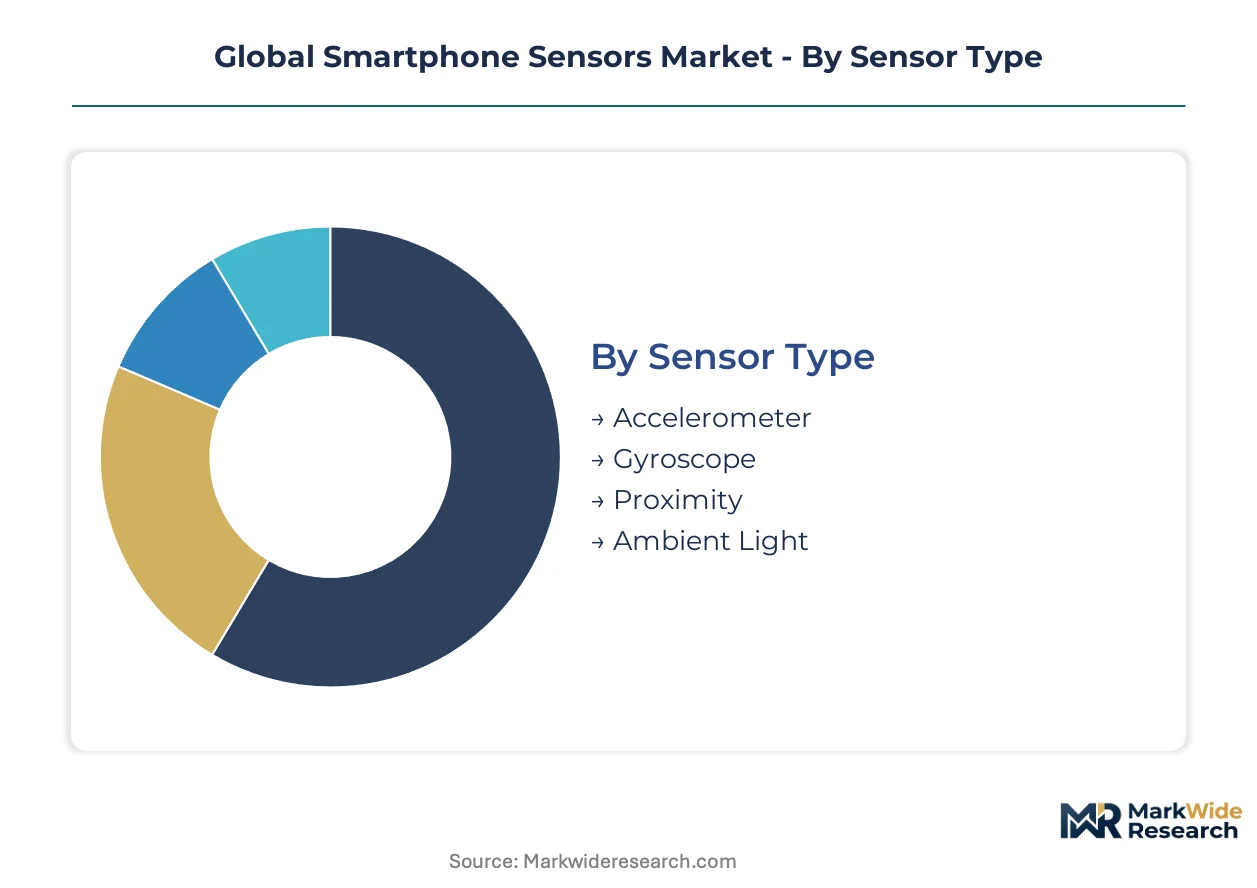
Smartphone sensor procurement patterns fragment sharply across technical specifications and commercial use cases. Tier-one OEMs source components through divergent qualification pathways depending on whether sensors serve imaging, motion, or biometric functions.
Sensor Type:
Margin pools concentrate in multi-axis inertial units where calibration complexity sustains pricing power against commoditized single-function alternatives.
- Accelerometer:Tri-axis MEMS devices measure linear acceleration through differential capacitance between proof masses and fixed electrodes. Demand concentrates in South Korean flagship assembly lines where computational stabilization requires sub-100 micro-g noise floors.
- Gyroscope:Coriolis-effect MEMS structures detect angular velocity via vibrating resonant elements. Procurement from Italian and Singaporean foundries is accelerating as gaming and AR applications demand six-degree-of-freedom tracking precision.
- Proximity:Infrared time-of-flight modules detect surface distance for display power management. Chinese domestic handsets drive volume through SAMR-mandated accuracy specifications.
- Ambient Light:Photodiode arrays with automatic gain control adapt screen brightness to environmental conditions. Integration with OLED power management is displacing discrete component sourcing in Vietnam assembly corridors.
The dominant share belongs to Accelerometer units, while Gyroscope is closing the gap fastest through AR and gaming adoption.
Application:
Volume flows track flagship refresh cycles, with imaging arrays commanding outsized revenue per unit against motion-sensing utilities.
- Photography:Computational imaging fuses data from primary, ultrawide, and telephoto sensors through dedicated ISP pipelines. Sony's stacked-die CMOS architectures anchor supply for premium tier devices requiring sub-micron pixel pitch.
- Navigation:Sensor fusion combines GNSS with barometric pressure and inertial dead reckoning for urban canyon positioning. Bosch Sensortec's environmental algorithms are penetrating South Korean supply chains through direct EMS licensing.
- Fitness Tracking:Pedometer and heart rate monitoring leverage accelerometer and photoplethysmography fusion. Indian BIS certification requirements are forcing localized test facility qualification for import clearance.
- Gaming:Haptic feedback and motion control demand low-latency gyroscope and accelerometer response. Ultrasonic fingerprint alternatives are displacing capacitive solutions in premium gaming handsets.
Photography captures the largest revenue pool, though Navigation is expanding most quickly through automotive-grade accuracy migration.
Technology:
Process maturity determines cost curves, with decades-old MEMS fabrication sustaining unit economics against newer solid-state alternatives.
- MEMS:Bulk micromachined silicon structures dominate motion and environmental sensing through foundry-scale cost optimization. STMicroelectronics' captive 8-inch fabs in Italy and Singapore defend vertical integration against Asian foundry competition.
- Optical:Backside-illuminated CMOS arrays with copper interconnect layers enable high-speed readout for computational photography. EU REACH compliance is accelerating lead-free piezoelectric substitution in actuator mechanisms.
- Ultrasonic:Piezoelectric acoustic sensing penetrates display stacks for fingerprint authentication. FCC equipment authorization timelines delay US market entry for new module suppliers.
- Capacitive:Traditional touch and proximity detection faces displacement pressure from ultrasonic and optical alternatives in premium device tiers.
MEMS retains volume leadership, while Optical commands the steepest margin expansion through stacked-die architecture differentiation.
End User:
Procurement authority concentrates in OEM engineering teams, with enterprise and developer segments emerging as specification influencers rather than direct purchasers.
- Consumers:Indirect demand drivers through feature prioritization in purchase decisions. Camera quality rankings and gaming performance benchmarks shape sensor specification requirements upstream.
- Enterprises:Ruggedized device procurement demands extended temperature range and shock tolerance certifications. China's GB/T accuracy mandates apply to domestic fleet deployment contracts.
- OEMs:Engineering teams at flagship smartphone manufacturers define sensor fusion architectures and qualification protocols. Samsung Electro-Mechanics and LG Innotek defend module integration positions through captive software stacks.
- Developers:API access to raw sensor streams enables augmented reality and health application innovation. Component distributors are unbundling fusion algorithms from hardware procurement in South Korean supply chains.
OEMs control the dominant procurement volume, while Developers are gaining specification influence fastest through platform ecosystem leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Flagship OEMs in South Korea and Japan prioritize imaging sensor density, while Chinese manufacturers emphasize cost-optimized MEMS volumes for domestic handsets. European demand concentrates on regulatory-compliant environmental sensing modules.
China
SAMR enforces GB/T accuracy specifications for inertial measurement units in domestic handsets. The Ministry of Ecology and Environment applies dual carbon goals to MEMS cleanroom energy efficiency. Shenzhen and Beijing host captive test facilities where domestic OEMs qualify sensor modules under accelerated audit timelines.
South Korea
Flagship smartphone assembly lines drive demand for sub-100 micro-g noise floor accelerometers. The Ministry of Food and Drug Safety regulates photoplethysmography sensors in health-monitoring devices. Seoul Capital Area fabrication clusters concentrate CMOS image sensor foundry capacity for computational photography arrays.
United States
FCC equipment authorization rules shape radio-frequency sensor integration timelines for multi-region product launches. The Environmental Protection Agency constrains material selection through TSCA enforcement on piezoelectric elements. California-based OEM engineering teams define sensor fusion architectures for premium tier devices.
Germany
REACH and RoHS compliance accelerates substitution of lead-based piezoelectric elements with compliant alternatives. The Federal Motor Transport Authority influences automotive-grade accuracy migration into smartphone navigation sensors. Bavaria hosts environmental sensor fusion software development for barometric pressure integration.
India
Bureau of Indian Standards certification requirements tighten import gatekeeping on electronic components. The Production-Linked Incentive scheme attracts MEMS assembly investment for ASEAN-bound handset supply chains. Tamil Nadu and Karnataka expand surface-mount capacity for inertial units in Vietnam-directed logistics corridors.
Global Smartphone Sensors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in motion and environmental sensing. The upper tier controls captive fabrication assets and sensor fusion software stacks. Mid-scale players compete through module integration and EMS licensing arrangements. Dominant competitive moves include backward integration into MEMS foundry capacity and direct algorithm licensing to tier-one manufacturers bypassing traditional distribution.
Among Asia-Pacific-based fabricators, Sony Corporation and Samsung Electronics occupy positions at the premium imaging tier, while STMicroelectronics exemplifies European vertical integration in motion sensing. Bosch Sensortec GmbH represents the environmental fusion software archetype through direct EMS engagement. These three anchors illustrate divergent strategic postures: proprietary stacked-die architectures, captive 8-inch MEMS fabs, and unbundled algorithm licensing respectively.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics |
| STMicroelectronics |
| Bosch Sensortec GmbH |
| OmniVision Technologies |
| Analog Devices |
| Texas Instruments |
| Infineon Technologies AG |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Captive 8-inch MEMS fabrication capacity in Italian and Singaporean foundries shapes both supply concentration and price floors for motion sensing modules. Scale economies at STMicroelectronics' integrated fabs create cost advantages that contract manufacturers in Vietnam assembly corridors cannot replicate without yield optimization investments.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-volume accelerometer and gyroscope units, while spot purchasing persists for specialty optical sensors in flagship camera modules. Three-tier pricing structure across premium, standard, and economy levels reflects calibration grade and SAMR certification status for Chinese domestic handsets. Cost compression in mid-tier MEMS is intensifying because 8-inch wafer scarcity concentrates bargaining power with captive foundry operators. OEM engineering teams show lowest price sensitivity for stacked-die CMOS arrays, while Vietnamese EMS providers face margin pressure on discrete inertial units.
Supply Chain Analysis
Strait of Malacca transit underwrites raw silicon wafer flows from Japanese and German suppliers to South Korean foundry ecosystems. Component fabrication concentrates in Taiwan, South Korea, and Italy, with final module assembly feeding from Vietnam and India. The supply chain draws from specialty silicon substrates, rare-earth dopants for piezoelectric elements, and copper interconnect layers for backside-illumination processes. Single-source vulnerability in VCSEL foundries for time-of-flight modules creates allocation risk during flagship launch cycles. Distribution runs through tier-one EMS providers and component distributors unbundling sensor fusion software from hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized MEMS process engineering expertise has migrated toward Asian foundry ecosystems faster than European institutes can replenish training pipelines, creating persistent capability gaps in calibration and temperature compensation disciplines.
For Market Incumbents: Shield proprietary stacked-die architectures through patent thickets around sub-micron pixel pitch processes while deepening backward integration into captive MEMS cleanroom operations. Displacement pressure from ultrasonic fingerprint alternatives in premium tiers demands accelerated R&D in piezoelectric acoustic integration. Certification investment in India's BIS test facilities defends module import clearance timelines against audit delays. For New Entrants and Emerging Players: Differentiate on environmental sensor fusion algorithms licensed directly to EMS providers, bypassing traditional module vendor markups. Fitness tracking applications in Indian supply chains represent the most penetrable white space, with localized test facility qualification creating captive demand. Direct algorithm licensing to South Korean smartphone OEMs offers the clearest go-to-market angle against entrenched Bosch Sensortec and STMicroelectronics positions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among environmental sensor fusion software providers with direct EMS licensing relationships. Over the projection horizon, vertically integrated specialists with captive 8-inch MEMS fabs and algorithm stacks present superior long-term viability against pure-play module integrators. Watch for FCC equipment authorization timeline extensions as an inflection indicator for radio-frequency sensor market entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Expansion | STMicroelectronics' 8-inch fab investments in Italy and Singapore defend motion sensor margins against Asian foundry competition. |
| Direct Algorithm Licensing | Bosch Sensortec's EMS bypass strategy captures software margin pools previously absorbed by module distributors. |
| Stacked-die Architecture Patenting | Sony's sub-micron pixel pitch processes anchor premium CMOS supply through proprietary fabrication know-how. |
| India BIS Test Facility Qualification | Localized certification investments accelerate import clearance timelines for MEMS inertial units in ASEAN-bound supply chains. |
| Ultrasonic Fingerprint Module Development | Piezoelectric acoustic sensing penetrates display stacks as capacitive alternatives face displacement in premium device tiers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MEMS fabrication engineers, OEM sensor qualification leads, EMS procurement managers, and distributor technical sales directors. Secondary validation drew from SAMR GB/T standard filings, FCC equipment authorization databases, EU REACH compliance registries, and SEC 10-K disclosures from listed semiconductor suppliers. Bottom-up module shipment estimates triangulated against top-down smartphone production forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled sensor type, application function, fabrication technology, and end-user procurement authority dimensions. CAGRs derived from regression analysis of historical foundry capacity utilization and OEM bill-of-materials trends. Industry-specific inputs included 8-inch MEMS wafer allocation data and computational photography array adoption curves in flagship refresh cycles.
Material uncertainties — regulatory timeline shifts, foundry yield volatility, and technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about SAMR enforcement intensity and FCC authorization processing capacity. Practitioners should keep alternative scenarios live as dual carbon goal implementation timelines and India PLI scheme disbursement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Echo Sounder Market