
 Global System Monitoring Market | 2026-2036
Global System Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global System Monitoring Market Foresight
Subscription-based telemetry ingestion is broadening what enterprises purchase, shifting buyers from perpetual licenses toward consumption-aligned contracts. Dynatrace leverages its AI-powered Davis engine to anchor premium pricing in full-stack observability. Datadog competes through aggressive platform bundling that extends its share of wallet across infrastructure and security monitoring. IBM Corporation sustains relevance in regulated sectors through deep mainframe and hybrid cloud integration capabilities.
System monitoring encompasses the continuous collection, analysis, and alerting of performance metrics across IT infrastructure, typically operating through agent-based or agentless architectures polling at intervals from seconds to minutes. The technology serves to preempt service degradation, automate incident response, and enforce service-level objectives in distributed computing environments. Cloud-based deployment leads solution type growth as organizations retire on-premises data centers, while security monitoring captures expanding budget share amid ransomware frequency. Application performance monitoring concentrates margin pools where root-cause analysis demands specialized instrumentation.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that shape how monitoring vendors architect European deployments, while the US SEC enforces cyber disclosure rules that mandate incident reporting timelines. Japan's METI promotes operational technology security guidelines that drive convergence between IT and industrial control system monitoring. Stakeholders must weigh sovereign cloud mandates against the cost of fragmented tooling architectures as regulatory jurisdictions proliferate.
Market Dynamics
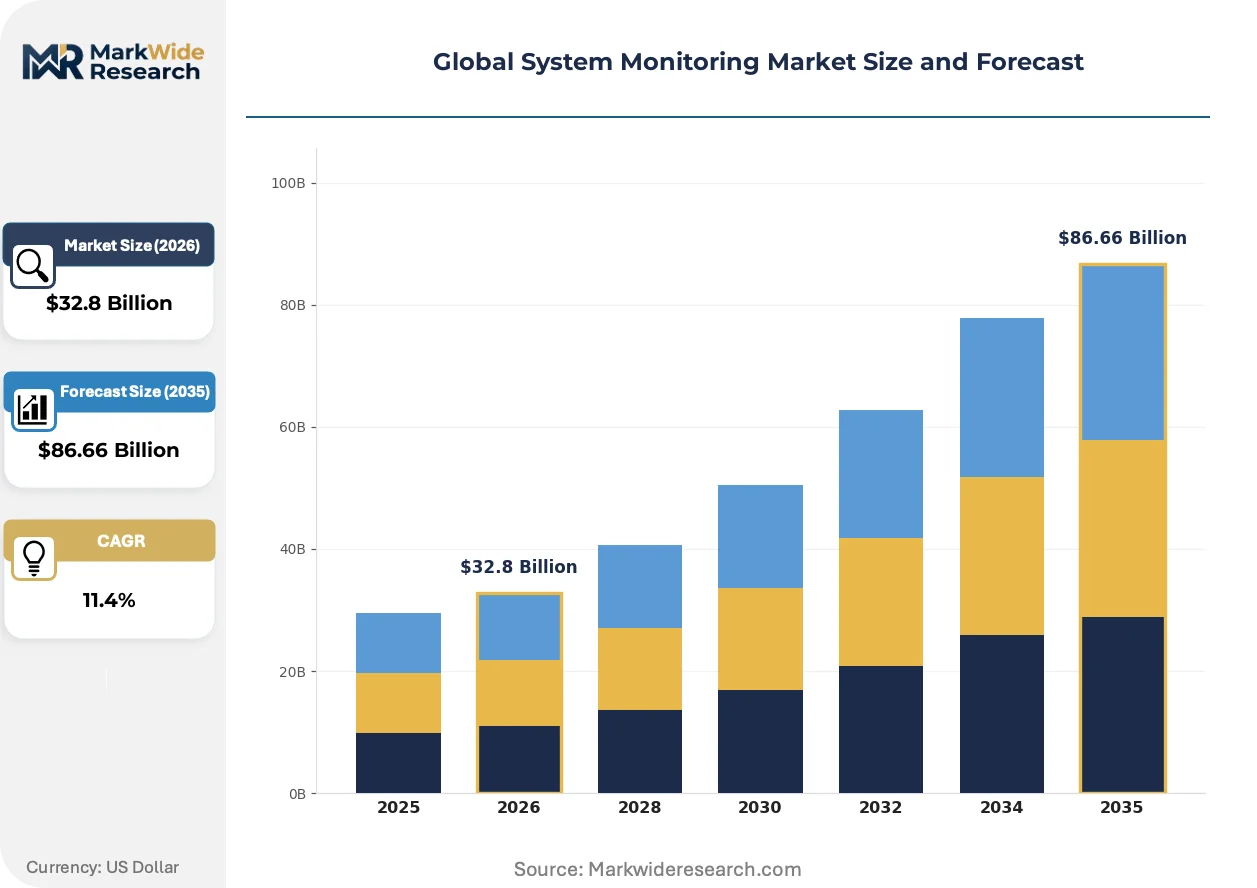
The migration from perpetual licensing to consumption-based telemetry contracts is compressing vendor margins while expanding addressable spend per enterprise account across infrastructure, application, and security monitoring layers.
Growth Catalysts
- Container orchestration expansion:Kubernetes-native observability requirements are pulling monitoring spend into DevOps workflows as microservices architectures proliferate across financial services and e-commerce platforms.
- SEC cyber disclosure mandates:US financial institutions must maintain continuous audit trails and sub-hour incident reporting capabilities, directly expanding monitoring tool procurement budgets.
- EU AI Act algorithmic transparency:Automated decision-making systems in European credit scoring and insurance pricing now require explainability logging that observability platforms must capture.
Market Restraints
- Cloud egress cost volatility:Telemetry data transfer fees from hyperscale providers consume 15-30% of total observability budgets, creating unpredictable operational expenditure spikes for large-scale deployments.
- Open-source stack substitution:Prometheus, Grafana, and Jaeger combinations displace commercial APM in mid-market technology companies comfortable with self-managed instrumentation.
- Data residency fragmentation:Divergent sovereign cloud requirements across Germany, Japan, and the United States force vendors to maintain redundant regional infrastructure, elevating cost-to-serve metrics.
Strategic Opportunities
- Industrial OT-IT convergence:Japan's METI cybersecurity guidelines for operational technology create first-mover advantage for vendors bridging SCADA and cloud-native monitoring stacks.
- Outcome-based pricing innovation:Vendors aligning contracts to mean-time-to-resolution improvements rather than data volume capture higher lifetime value from risk-averse healthcare and aviation buyers.
- Edge computing instrumentation:5G-enabled manufacturing and autonomous vehicle deployments in Germany and South Korea require distributed monitoring agents with sub-second latency thresholds.
Industry Challenges
- Observability engineer scarcity:Expertise in OpenTelemetry instrumentation, eBPF kernel programming, and SRE practice implementation commands premium compensation that mid-tier enterprises cannot match.
- Legacy mainframe integration complexity:Financial services and government agencies running COBOL and assembly workloads on IBM zSystems face multi-year modernization timelines to achieve unified telemetry pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global System Monitoring Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing, Fog Computing Solution Type: Network Monitoring, Server Monitoring, Application Performance, Security Monitoring, Database Monitoring Use Case: IT Operations, Security Compliance, Asset Management, Fault Detection, Capacity Planning End User: Information Technology Firms, Telecommunication Providers, Financial Services, Manufacturing Units, Educational Institutions |
| Companies Covered | SolarWinds, Cisco Systems, Dynatrace, IBM Corporation, Microsoft, Datadog, New Relic, Splunk, NETSCOUT Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global System Monitoring Market Shifts & Advancements
Artificial intelligence is displacing rule-based alerting thresholds with probabilistic anomaly detection, compressing incident response cycles while elevating data quality requirements for training corpora.
OpenTelemetry is modularizing telemetry collection across traces, metrics, and logs into vendor-neutral pipelines. Cloud-native enterprises in technology and digital media sectors are standardizing on this instrumentation layer to avoid proprietary agent lock-in. The specification is modularizing competitive differentiation away from data collection toward analytics engines and remediation automation.
The EU AI Act's algorithmic audit requirements are mandating observability into machine learning inference pipelines. Deployers of high-risk AI systems in credit, insurance, and recruitment must maintain continuous performance monitoring and bias detection logs. European financial services firms are responding by embedding ML model monitoring into existing APM contracts rather than procuring standalone MLOps tools.
Enterprise buyers are consolidating vendor relationships to reduce integration overhead and simplify procurement negotiations. Infrastructure and security monitoring budgets are merging under platform engineering teams that reject point solutions. This concentration is most visible among US technology and healthcare enterprises with mature FinOps practices and centralized cloud governance functions.
Global System Monitoring Market Segmentation
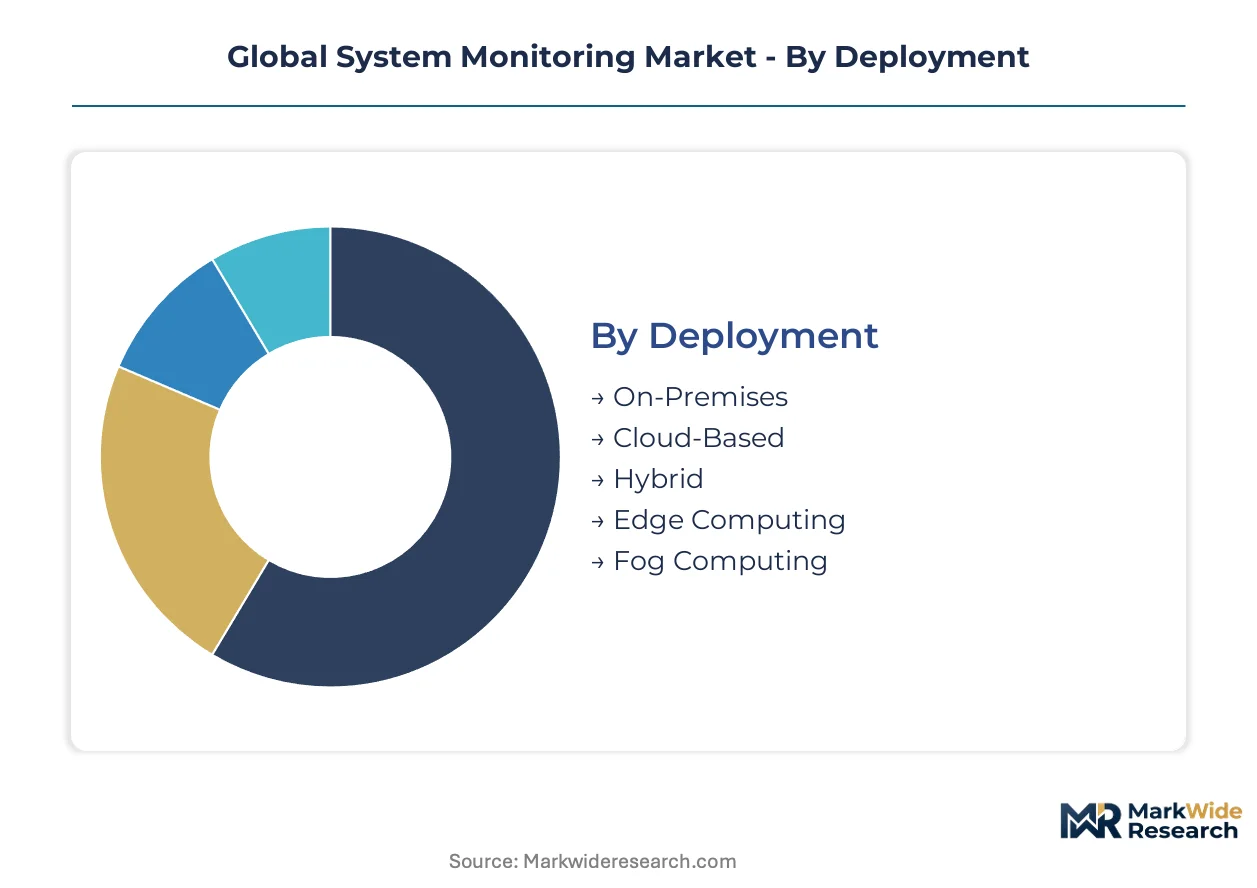
System monitoring procurement patterns diverge sharply across deployment architectures and operational use cases. Buyers align solution selection with regulatory exposure, cloud maturity, and the technical debt burden of legacy infrastructure.
Deployment:
Supply concentration in hyperscale infrastructure is tilting procurement toward consumption-aligned delivery models that reduce capital intensity.
- On-Premises:Dedicated hardware installations within enterprise data centers provide complete data sovereignty and sub-millisecond latency for regulated workloads. Financial services firms in Germany and Japan maintain these deployments to satisfy GDPR and METI operational technology guidelines.
- Cloud-Based:Fully managed SaaS platforms eliminate infrastructure maintenance overhead while enabling elastic telemetry ingestion. United States technology enterprises and digital media companies dominate adoption, driven by SEC cyber disclosure mandates requiring scalable audit trail retention.
- Hybrid:Split architectures preserve sensitive workloads on-premises while bursting analytics to public cloud. Manufacturing units across Germany leverage this model to bridge SCADA systems with cloud-native observability.
- Edge Computing:Distributed agents process telemetry at network peripheries for 5G-enabled industrial and autonomous vehicle deployments. South Korean automotive manufacturers and German precision engineering clusters drive demand for sub-second latency thresholds.
- Fog Computing:Hierarchical processing layers between edge devices and central clouds optimize bandwidth for smart city and utility grid applications. Japanese infrastructure operators deploy these architectures under METI cybersecurity convergence guidelines.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
Solution Type:
Margin pools concentrate where root-cause analysis demands specialized instrumentation beyond generic infrastructure polling.
- Network Monitoring:Continuous packet inspection and flow analysis across routers, switches, and software-defined networks. Telecommunication providers in Japan and Germany invest heavily here to maintain service-level agreements under stringent operational resilience mandates.
- Server Monitoring:CPU, memory, disk, and process-level telemetry collection from physical and virtual compute resources. Mid-market enterprises across the United States favor open-source Prometheus stacks over commercial alternatives.
- Application Performance:Distributed tracing and code-level profiling for microservices architectures. Financial services firms embed these capabilities to satisfy EU AI Act algorithmic transparency requirements for automated credit decisions.
- Security Monitoring:Real-time threat detection through log correlation and behavioral analytics. Expanding fastest as ransomware frequency elevates security observability to board-level priority.
- Database Monitoring:Query performance analysis and replication lag tracking across relational and NoSQL stores. E-commerce platforms rely on these tools during peak transaction periods.
Application Performance commands premium pricing. Security Monitoring is climbing the fastest.
Use Case:
Customer maturity determines whether procurement prioritizes reactive incident response or proactive capacity optimization.
- IT Operations:Day-to-day service health management and automated alerting for infrastructure teams. The foundational use case across all geographies and organization sizes.
- Security Compliance:Audit trail generation and regulatory evidence collection for mandated disclosure timelines. United States financial institutions expand budgets here to meet SEC cyber rules.
- Asset Management:Lifecycle tracking and utilization optimization for hardware and software inventories. Educational institutions deploy these capabilities with limited technical staffing.
- Fault Detection:Predictive identification of component failures before service degradation. Manufacturing units in Germany integrate these systems with operational technology stacks.
- Capacity Planning:Demand forecasting and resource allocation modeling for infrastructure scaling. Cloud-native enterprises mature into this use case after stabilizing incident response.
IT Operations remains the volume anchor. Security Compliance shows steepest expansion trajectory.
End User:
Vertical-specific regulatory exposure and digital transformation maturity shape solution complexity and contract value.
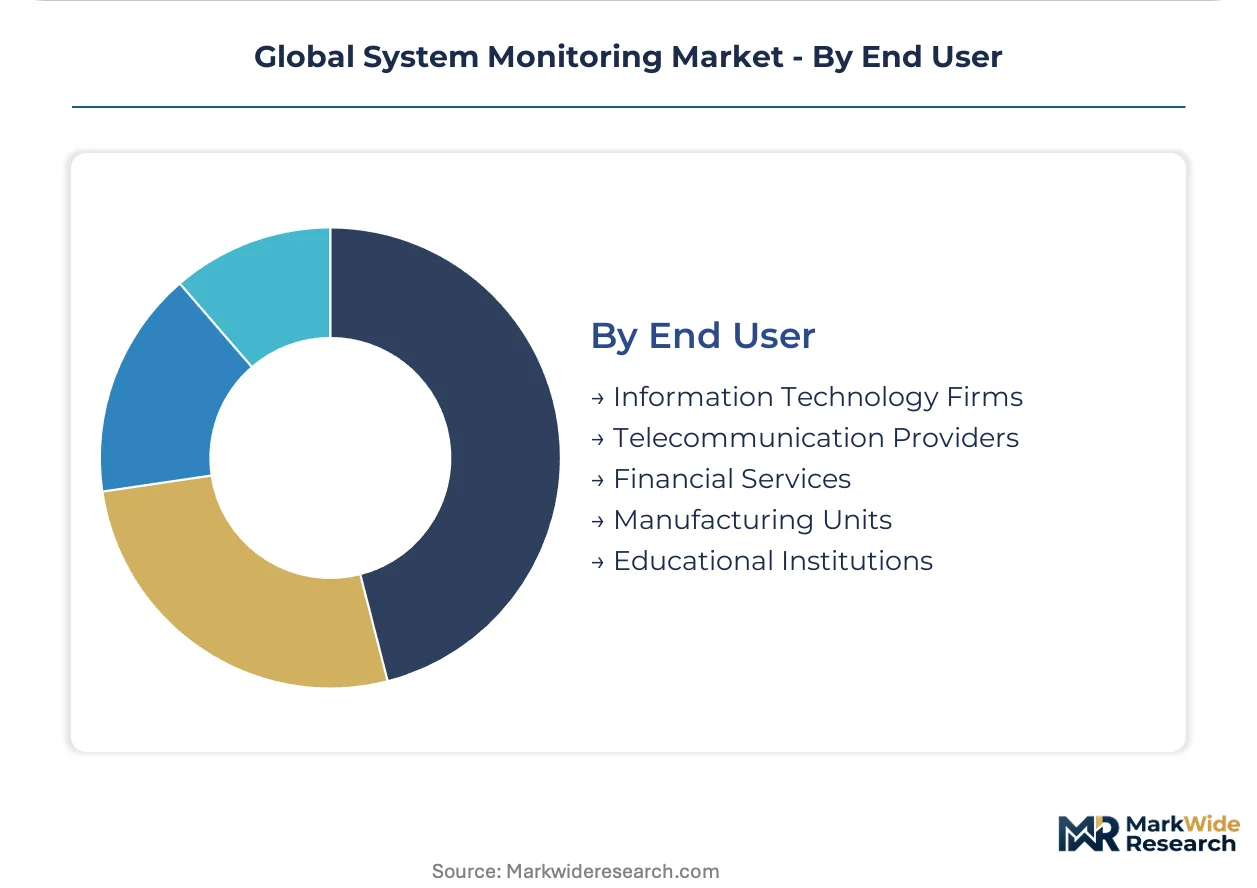
- Information Technology Firms:Internal platform engineering teams and managed service providers with sophisticated observability requirements. Early adopters of OpenTelemetry and eBPF instrumentation.
- Telecommunication Providers:National carriers requiring carrier-grade reliability and subscriber experience monitoring. Japanese and German operators face METI and BSI operational resilience mandates.
- Financial Services:Banks, insurers, and asset managers subject to SEC, GDPR, and EU AI Act compliance burdens. Highest per-seat spending on full-stack observability platforms.
- Manufacturing Units:Discrete and process industries bridging IT and operational technology monitoring. German automotive and Japanese electronics producers lead OT-IT convergence investments.
- Educational Institutions:Universities and research facilities with distributed campus networks and limited operational budgets. Price-sensitive adopters of open-source monitoring stacks.
Financial Services dominates contract value. Manufacturing Units are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains tighter SEC cyber disclosure timelines than Germany's BSI operational resilience frameworks, yet both jurisdictions drive comparable monitoring procurement intensity among financial institutions.
United States
SEC cyber disclosure mandates and FinOps maturity concentrate demand among cloud-native enterprises and financial services firms. HIPAA compliance requirements in healthcare expand security monitoring budgets across hospital networks. Silicon Valley technology clusters and New York financial centers anchor consumption-based telemetry contract adoption.
Germany
GDPR data residency rules and BSI critical infrastructure guidelines preserve on-premises and hybrid deployment preferences. Automotive precision engineering clusters in Bavaria and Baden-Württemberg drive OT-IT convergence investments for smart manufacturing monitoring. Frankfurt's financial hub maintains sovereign cloud architectures for audit trail retention.
Japan
METI operational technology security guidelines accelerate convergence between SCADA and cloud-native observability stacks. Kanto manufacturing belts and Osaka electronics production centers demand sub-second latency monitoring for automated quality control. Tokyo financial institutions integrate mainframe telemetry with modern APM pipelines.
South Korea
5G-enabled autonomous vehicle testing and semiconductor fabrication drive edge computing instrumentation requirements. Seoul metropolitan manufacturing complexes and Gyeonggi automotive clusters deploy distributed monitoring agents for real-time defect detection. National cybersecurity frameworks elevate security observability to board-level procurement priority.
United Kingdom
FCA operational resilience deadlines and post-Brexit data sovereignty considerations shape hybrid cloud monitoring strategies. London financial services firms embed EU AI Act-aligned algorithmic transparency logging into existing contracts. Cambridge technology corridors and Manchester digital hubs standardize on OpenTelemetry instrumentation layers.
Global System Monitoring Market Competitive Landscape
Top-tier vendors anchor full-stack observability platforms, while mid-tier specialists and open-source aggregators compete on price-sensitive infrastructure monitoring. The market exhibits tiered concentration where AI-powered root-cause analysis commands premium positioning against commoditized server polling. Three archetypes dominate: hyperscale cloud-integrated suites, mainframe-hybrid specialists, and Kubernetes-native challengers. Competitive moves center on platform bundling expansions and consumption-based pricing realignments.
Within the AI-native tier, Dynatrace and Datadog exemplify divergent monetization strategies—one anchoring premium positioning through proprietary analytics engines, the other capturing share of wallet through aggressive cross-module bundling. IBM Corporation occupies a distinct position serving regulated sectors with deep hybrid cloud and mainframe integration capabilities. These three represent how vendor archetypes map to buyer maturity segments across financial services, manufacturing, and technology verticals.
| Leading Market Players |
|---|
| SolarWinds |
| Cisco Systems |
| Dynatrace |
| IBM Corporation |
| Microsoft |
| Datadog |
| New Relic |
| Splunk |
| NETSCOUT Systems |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up observability specialists anchor supply-side discipline through aggressive platform consolidation, compressing vendor margins while elevating pricing power for full-stack suites that bundle infrastructure, application, and security monitoring layers under consumption-aligned contracts.
Pricing Analysis
Capacity additions in hyperscale cloud regions are reshaping price floors for telemetry ingestion, forcing mid-tier vendors toward SaaS-tiered subscription models that separate premium AI-powered root-cause analytics from standard infrastructure polling. Price differentiation rests on ISO 27001 certification tiers and OpenTelemetry instrumentation depth, with German financial institutions least sensitive due to GDPR-mandated sovereign cloud requirements. Cost compression in the mid-market is intensifying because Prometheus-Grafana-Jaeger open-source stacks displace commercial APM, while United States technology startups exhibit highest price sensitivity as they optimize cloud spend through FinOps practices.
Supply Chain Analysis
Silicon wafer supply rests on Taiwanese foundries and South Korean memory producers, with specialized GPU and AI accelerator hardware for inference pipelines drawing from United States semiconductor designers. Telemetry agent development hinges on eBPF kernel programming expertise concentrated in Israel and Germany, while cloud egress bandwidth feeds from hyperscale provider networks in Virginia, Frankfurt, and Tokyo. Single-source vulnerability runs through NVIDIA's datacenter GPU allocation for AI-powered anomaly detection engines. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings with consumption-based metering integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
System monitoring procurement functions as a geographic-arbitrage play where Japanese manufacturers face 40% higher observability engineer compensation than Indian managed service providers, creating cost-advantaged delivery centers for Southeast Asian expansion.
For Market Incumbents: Lock in mainframe-telemetry integration capabilities through captive development of COBOL and assembly instrumentation agents, defending against IBM Corporation's entrenched position in regulated financial services. Prioritize certification investment for EU AI Act algorithmic audit compliance to maintain premium positioning against Datadog's aggressive platform bundling.
For New Entrants and Emerging Players: The 60% price-point gap between Dynatrace premium full-stack contracts and self-managed Prometheus deployments opens white-space in mid-market manufacturing units across Germany and South Korea. Target edge computing instrumentation for 5G-enabled autonomous vehicle testing facilities, leveraging sub-second latency requirements that incumbent SaaS platforms cannot satisfy. Pursue channel partnerships with telecommunications providers bundling observability into managed 5G private network offerings.
For Investors and Strategic Acquirers: Valuations sit cheapest among Kubernetes-native challengers with OpenTelemetry-native architectures but limited enterprise sales infrastructure, presenting acquisition targets for hyperscaler platform engineering teams. Long-term viability over the next decade hinges on AI-powered remediation automation capabilities that compress mean-time-to-resolution below human-operated thresholds. Watch hyperscaler capex disclosures for telemetry pipeline infrastructure buildout as the inflection signal for vendor consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| OpenTelemetry Native Platform Development | Avoids proprietary agent lock-in for cloud-native enterprises standardizing on vendor-neutral instrumentation layers. |
| AI-Powered Remediation Automation | Compresses incident response cycles below human SRE team capacity through Davis-engine probabilistic anomaly detection. |
| Mainframe Telemetry Integration | Captures regulated financial services budgets requiring unified pipelines across IBM zSystems and cloud-native workloads. |
| Edge Computing Instrumentation | Addresses 5G-enabled manufacturing and autonomous vehicle latency requirements that central SaaS cannot satisfy. |
| Outcome-Based Pricing Contracts | Aligns vendor revenue to mean-time-to-resolution improvements for risk-averse healthcare and aviation procurement teams. |
Research Methodology
Multiple input streams — structured interviews with platform engineering directors and SRE team leads, observability procurement officers at financial institutions, and hyperscaler solution architects — were reconciled against SEC 10-K filings, hyperscaler capex disclosures, and OpenTelemetry community contribution metrics. Bottom-up telemetry spend estimates from individual enterprise deployments were cross-validated with top-down vendor revenue attribution across deployment models and solution types.
Historical spending patterns were cross-referenced against panel input from infrastructure software investors and channel partners to establish baseline assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, end-user vertical, and regional regulatory framework cluster. CAGRs were derived through logistic adoption curve fitting for cloud-native instrumentation, with specific inputs from Kubernetes cluster growth trajectories and SEC cyber disclosure mandate compliance timelines.
Caveats apply where hyperscaler pricing changes, open-source stack substitution acceleration, or sovereign cloud mandate fragmentation could materially shift the outlook. A small set of named triggers — including EU AI Act enforcement severity, NVIDIA GPU allocation constraints for AI inference, and telecommunications provider vertical integration into managed observability — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Content Analytics and Search Software Market
Analytics
Sales Intelligence Market
Analytics
Europe Predictive Analytics Market
Analytics
Content Intelligence Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Global Data Fusion Market
Analytics
Investigative Analytics Market
Analytics
Practice Analytics Market
Analytics
Web Analytics Market
Analytics
Active Data Warehousing Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
APAC Operational Intelligence Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
North America Location Analytics Market