
 Practice Analytics Market | 2026-2036
Practice Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Practice Analytics Market Outlook
The direct-to-provider software channel is rewriting how analytics platforms reach end users, bypassing traditional group purchasing organizations for subscription-based contracts. Epic Systems leverages deep EHR integration to sustain captive demand within its installed base. Cerner Corporation competes through modular cloud architectures that extend across acute and ambulatory settings.
Practice analytics encompasses the collection, processing, and visualization of operational, clinical, and financial data generated by healthcare delivery organizations, typically deployed through HL7 FHIR-compliant interfaces and SQL-based data warehouses to enable real-time dashboarding and predictive modeling. Cloud-based deployment leads in new installations as health systems prioritize elastic compute capacity and reduced capital expenditure, while revenue cycle management solutions capture disproportionate margin pools due to their direct impact on reimbursement velocity. Performance management applications are gaining share fastest among private practices seeking to qualify for Medicare accountable care programs.
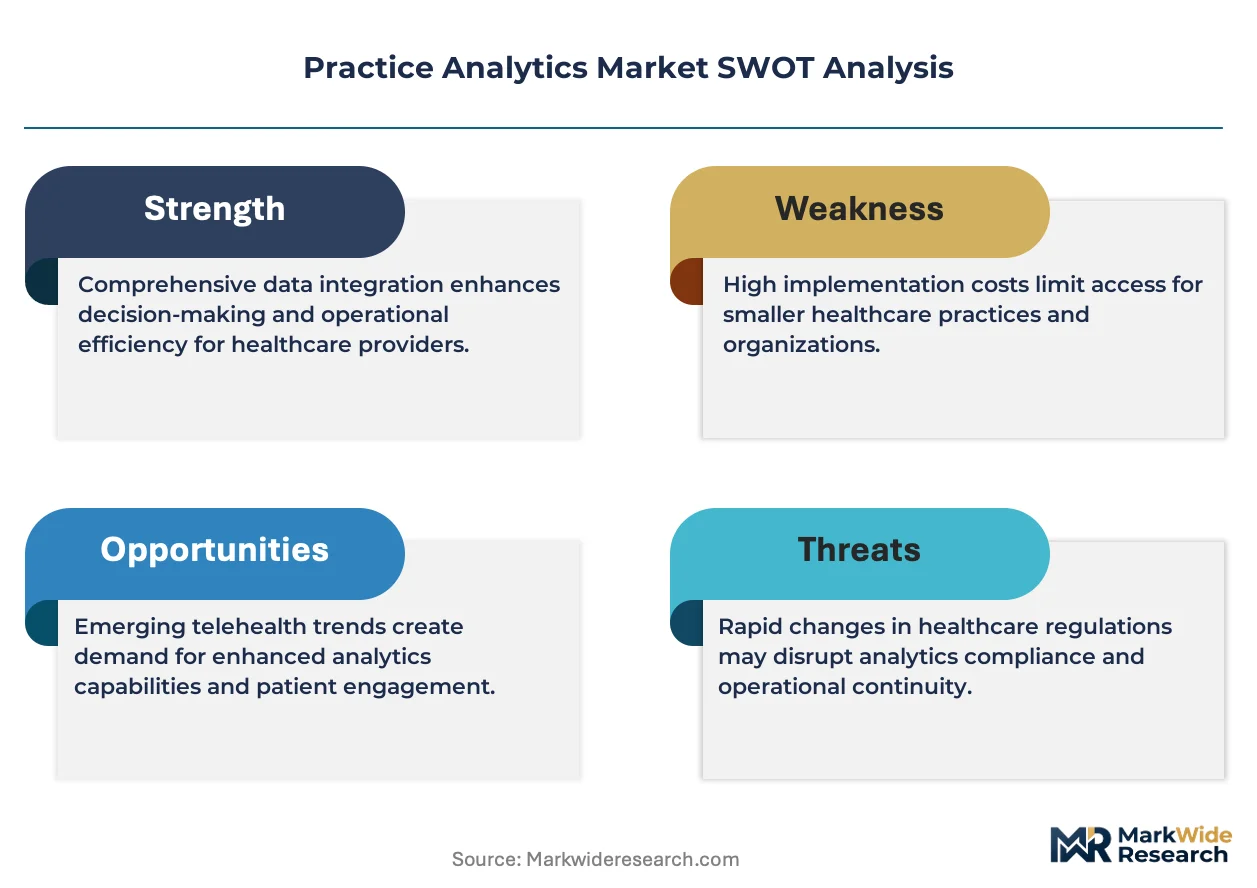
FDA oversight of clinical decision support algorithms, ONC certification requirements for health IT interoperability, and HIPAA security rule enforcement collectively elevate compliance costs for vendors while creating barriers to entry for unvalidated platforms. The EU AI Act and GDPR impose additional constraints on cross-border patient data analytics, forcing architecture segmentation by jurisdiction. Buyers must weigh vendor stability against the pace of regulatory change as certification timelines lengthen and enforcement intensifies.
Market Dynamics
Cloud migration mandates from the Office of the National Coordinator for Health IT are forcing hospital systems to retire on-premise data warehouses. This regulatory pressure is compressing deployment timelines and redistributing vendor bargaining power toward subscription-native platforms.
Growth Catalysts
- ONC Interoperability Mandates:Certification requirements under the 21st Century Cures Act are compelling health systems to replace legacy interfaces with HL7 FHIR-compliant architectures. This creates immediate replacement demand across installed bases.
- Value-Based Reimbursement:Medicare accountable care organizations are tying physician compensation to quality metrics. Analytics platforms that automate HEDIS measure calculation capture this procurement priority.
- Elastic Compute Infrastructure:Health systems are prioritizing cloud-native deployments to eliminate capital expenditure on server hardware. Amazon Web Services and Microsoft Azure health data lakes are displacing on-site SQL warehouses.
Market Restraints
- FDA Algorithm Oversight:Clinical decision support tools now face premarket review pathways when functioning as diagnostic aids. This extends certification timelines and elevates legal exposure for vendors.
- GDPR Cross-Border Friction:European patient data cannot flow to US cloud regions without adequacy determinations. Architecture segmentation by jurisdiction duplicates infrastructure costs.
- Specialized Talent Scarcity:Health informaticists with dual competency in clinical workflows and data engineering command premium compensation. Vendor hiring cycles stretch to six months for qualified candidates.
Strategic Opportunities
- Rural Health Network Consolidation:Critical access hospitals in Montana and North Dakota are forming shared services organizations. Multi-tenant analytics platforms can serve these federated buyers with standardized dashboards.
- EU AI Act Compliance Services:Risk classification requirements for patient-facing algorithms create advisory revenue streams. Vendors can bundle conformity assessment with core software licenses.
- Revenue Cycle Integration:Denial management tools that predict payer rejection patterns before claim submission are penetrating ambulatory surgery centers. This segment has historically underinvested in financial analytics.
Industry Challenges
- Epic EHR Integration Complexity:Proprietary data models require custom extract-transform-load pipelines. Third-party vendors must maintain dedicated engineering teams for each major health system.
- HIPAA Security Rule Enforcement:Office for Civil Rights audits are intensifying around access logging and encryption standards. Breach notification costs now average millions per incident.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Practice Analytics Market |
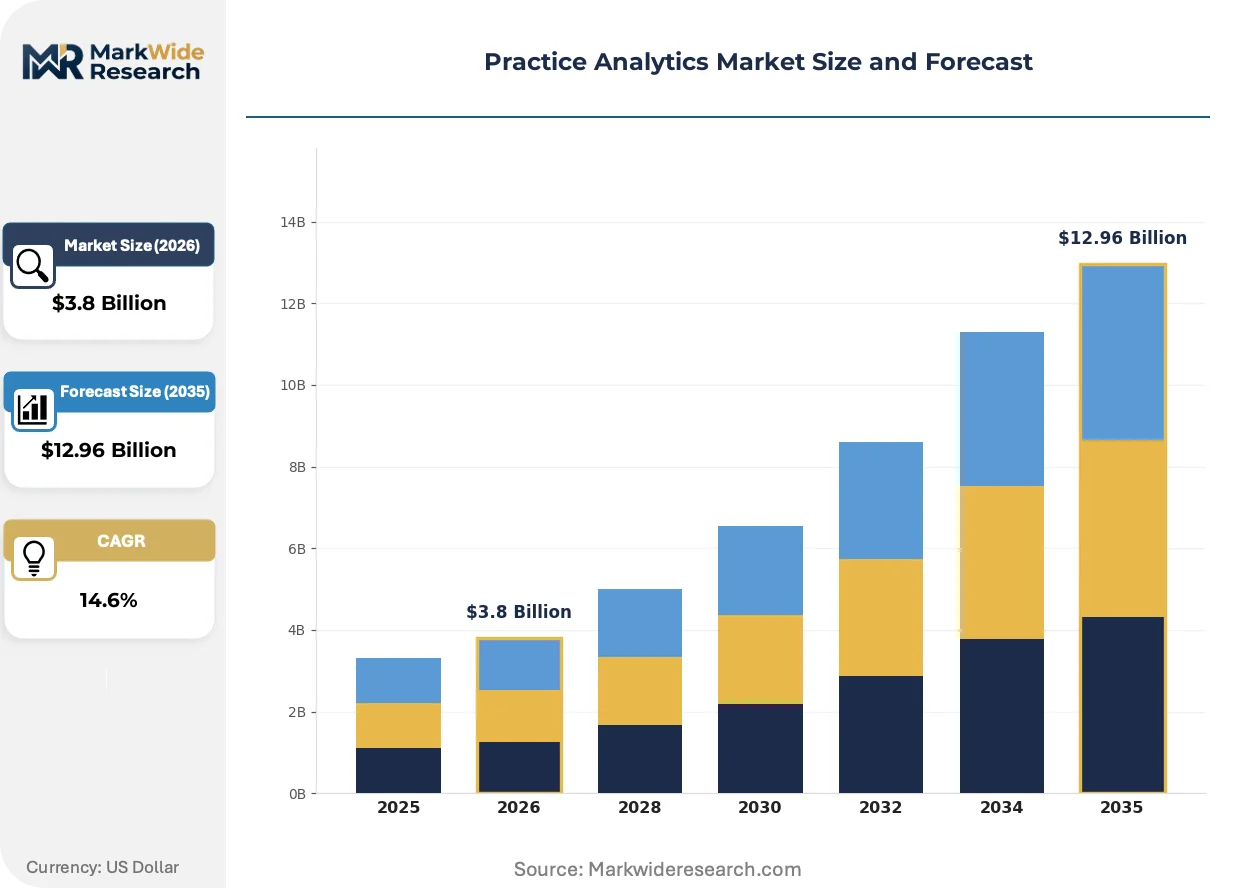
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Healthcare Providers, Clinics, Hospitals, Private Practices Solution: Data Analytics, Performance Management, Revenue Cycle Management, Reporting Tools Application: Clinical Data Analysis, Operational Insights, Patient Engagement, Financial Forecasting |
| Companies Covered | Epic Systems, Cerner Corporation, Optum, Allscripts Healthcare Solutions, McKesson Corporation, Athenahealth, IBM Watson Health, NextGen Healthcare, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Practice Analytics Market Strategic Shifts
Artificial intelligence is embedding into operational workflows without displacing human decision-making. Three convergent developments are compressing implementation cycles and redefining platform economics.
Natural language processing is migrating from retrospective documentation review to real-time ambient listening during patient encounters. Primary care networks in Wisconsin and Minnesota are piloting these tools to automate encounter coding. The technology is compressing revenue cycle timelines from weeks to hours while reducing physician administrative burden.
The EU AI Act's risk-based classification system is forcing vendors to reengineer clinical decision support modules. High-risk algorithms now require conformity assessment by notified bodies before market entry. European hospital procurement committees are prioritizing vendors with established quality management systems to preempt deployment delays.
Direct contracting between health system chief information officers and analytics vendors is displacing traditional group purchasing organization intermediaries. Subscription pricing with usage-based tiers is replacing perpetual license models. This shift is most visible among integrated delivery networks in Texas and Florida seeking flexibility to scale seats seasonally.
Practice Analytics Market Segmentation
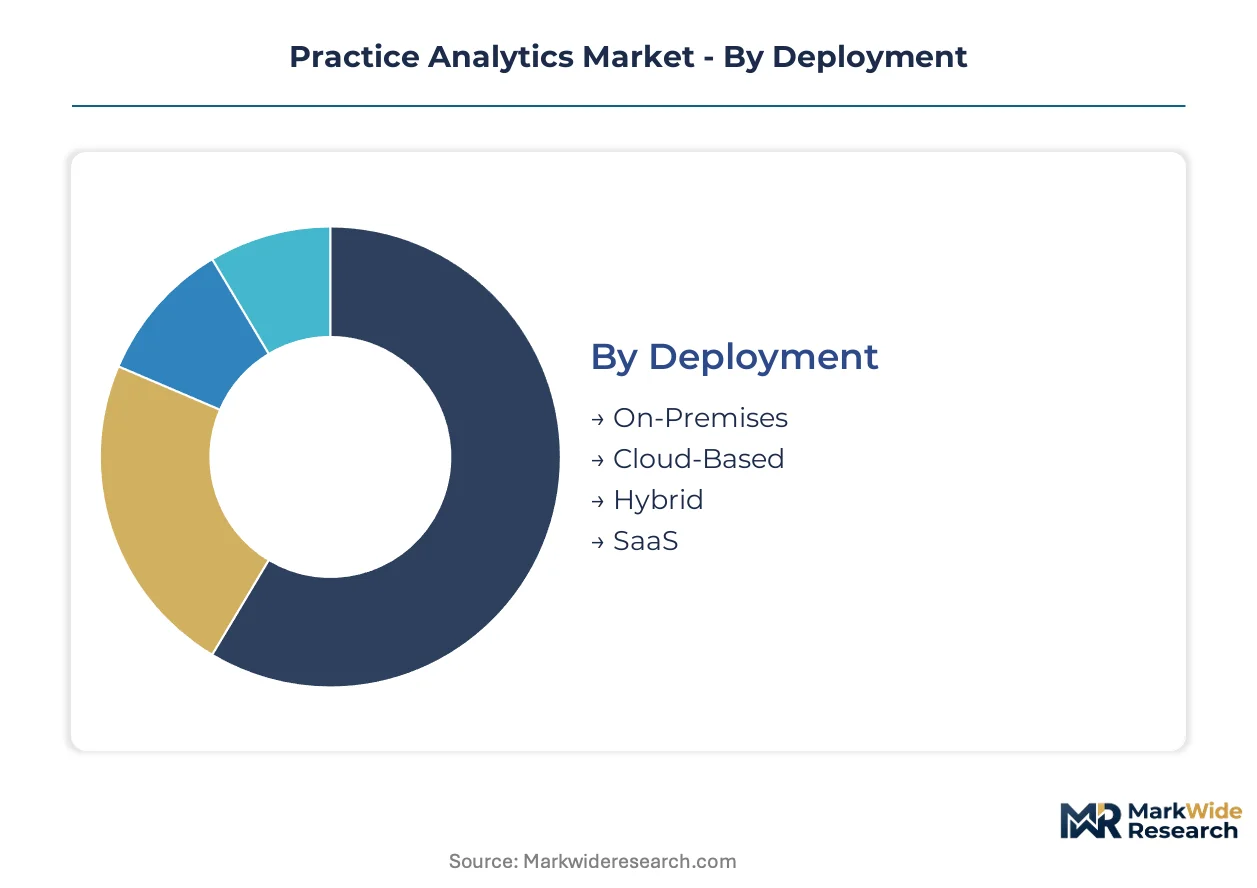
Deployment architecture dictates vendor service obligations and renewal economics in practice analytics. Cloud-native platforms demand continuous uptime guarantees and elastic support staffing, while on-premise installations require periodic field engineering visits for hardware maintenance and security patching cycles.
Deployment:
After-sales service intensity varies sharply across deployment modes, with cloud-native platforms demanding 24/7 infrastructure monitoring and on-premise systems requiring scheduled hardware interventions.
- On-Premises:Hardware-resident installations within health system data centers demand dedicated field engineering teams for server maintenance, security patch deployment, and disaster recovery testing. Large integrated delivery networks in Texas and Florida retain these configurations for legacy EHR integration requirements, though procurement committees increasingly view capital expenditure obligations as strategic liabilities.
- Cloud-Based:Vendor-managed infrastructure eliminates client-side hardware responsibility while imposing stringent service-level agreements around uptime, encryption key rotation, and cross-region failover. Health systems migrating from ONC mandate compliance prioritize these deployments for elastic compute scaling and reduced internal IT staffing.
- Hybrid:Split architectures segregate sensitive patient data on local servers while pushing anonymized analytics workloads to public cloud regions. This configuration addresses HIPAA Security Rule audit requirements while preserving computational flexibility for population health modeling.
- SaaS:Subscription-native delivery concentrates vendor-customer relationships around continuous feature releases and usage-based tier migrations. Ambulatory surgery centers and rural health networks favor this model for predictable operational expenditure and rapid implementation timelines.
By volume, Cloud-Based leads. By growth pace, SaaS is expanding most quickly.
End User:
Customer scale determines implementation complexity and pricing tier positioning, with enterprise hospital systems commanding dedicated account management and small practices receiving standardized self-service onboarding.
- Healthcare Providers:Multi-site physician organizations require unified analytics across disparate EHR instances, driving demand for vendor professional services to normalize data schemas. These buyers negotiate enterprise licensing with unlimited user seats and custom dashboard development.
- Clinics:Federally qualified health centers and community clinics prioritize Medicare accountable care program qualification, concentrating procurement on HEDIS measure automation and care gap identification tools. Budget constraints favor modular solutions with per-provider pricing.
- Hospitals:Acute care facilities demand real-time operational dashboards for emergency department throughput and surgical block utilization. ONC interoperability mandates are accelerating replacement of legacy business intelligence platforms with HL7 FHIR-compliant architectures.
- Private Practices:Solo and small-group physicians seek revenue cycle visibility and patient engagement metrics without dedicated IT staff. Direct-to-vendor subscription contracts are displacing traditional group purchasing organization intermediaries in this segment.
Hospitals generate the highest absolute revenue per account. Private Practices are climbing the fastest as direct contracting models proliferate.
Solution:
Margin structure diverges across solution categories, with revenue cycle management capturing disproportionate value pools due to direct reimbursement impact while reporting tools face commoditization pressure.
- Data Analytics:Core processing engines aggregating clinical, operational, and financial data through SQL-based warehouses and machine learning pipelines. Health systems in Minnesota and Wisconsin deploy these platforms for population health stratification and predictive readmission modeling.
- Performance Management:Benchmarking dashboards comparing provider productivity, quality metrics, and patient satisfaction against peer cohorts. Private practices pursuing Medicare accountable care contracts are the fastest-expanding user base for these tools.
- Revenue Cycle Management:Denial prediction, claims scrubbing, and prior authorization automation that compresses reimbursement timelines from weeks to days. Ambulatory surgery centers historically underinvested in financial analytics are now prioritizing these solutions.
- Reporting Tools:Standardized visualization templates for regulatory submission and internal governance. These modules face pricing pressure as EHR vendors bundle basic reporting with core platform licenses.
Revenue Cycle Management commands premium pricing. Performance Management is gaining share fastest among quality-program participants.
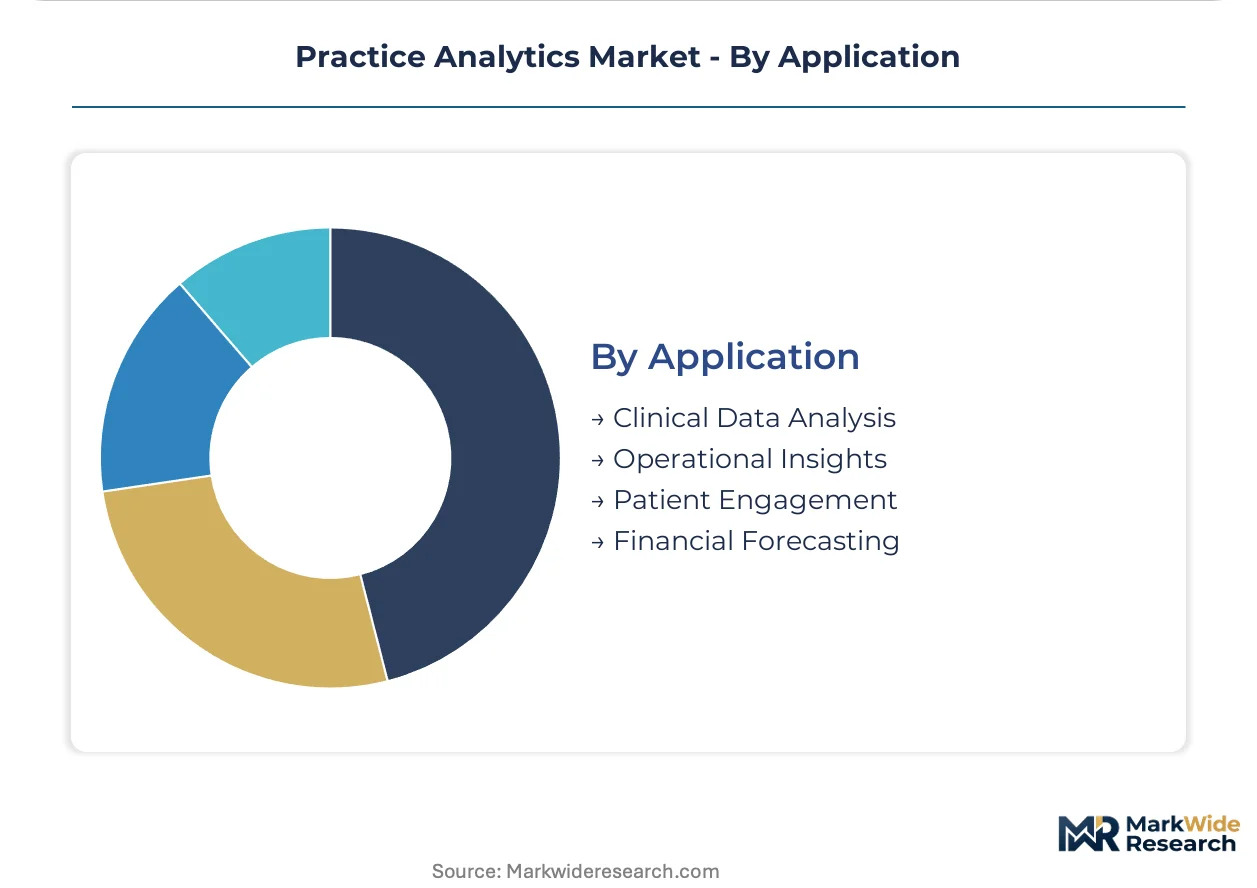
Application:
Use case specificity determines integration depth and workflow disruption, with clinical applications demanding EHR-native deployment and financial tools tolerating standalone implementation.
- Clinical Data Analysis:Real-time patient risk scoring and care pathway recommendations embedded within provider workflows. FDA oversight of diagnostic algorithms is extending certification timelines for vendors in this category.
- Operational Insights:Scheduling optimization, supply chain analytics, and facility utilization tracking that reduces per-case cost structures. Hospital systems in Florida deploy these tools to manage seasonal volume fluctuations.
- Patient Engagement:Portal analytics, appointment adherence prediction, and outreach campaign effectiveness measurement. Federally qualified health centers leverage these capabilities to improve Medicare star ratings.
- Financial Forecasting:Payer mix modeling, contract negotiation support, and cash flow projection for strategic planning. Critical access hospitals in Montana and North Dakota shared services organizations prioritize these applications for survival planning.
Clinical Data Analysis requires the deepest integration. Patient Engagement is expanding most rapidly as consumerism pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA interoperability mandates anchor the United States as the dominant geography, while GDPR constraints and EU AI Act risk classifications reshape European procurement patterns. Cloud migration timelines compress across jurisdictions as health systems retire legacy data warehouses.
United States
ONC certification requirements under the 21st Century Cures Act compel hospital systems to replace legacy HL7 interfaces with FHIR-compliant architectures. Medicare accountable care organizations tie physician compensation to quality metrics, driving demand for automated HEDIS calculation tools. Large integrated delivery networks in Texas and Florida command disproportionate purchasing power through direct vendor contracting.
Germany
EMA oversight of clinical decision support algorithms extends certification timelines for diagnostic aid modules entering the European market. The EU AI Act's high-risk classification system forces vendors to reengineer patient-facing tools before deployment. Hospital procurement committees in Bavaria and North Rhine-Westphalia prioritize vendors with established quality management systems.
United Kingdom
NHS England's cloud-first policies accelerate retirement of on-premise SQL warehouses across acute trusts. GDPR adequacy determinations constrain cross-border patient data flows to US cloud regions. London and Greater Manchester health systems pilot ambient listening technologies for real-time encounter coding automation.
Japan
METI digital health initiatives promote standardized data exchange protocols across prefectural hospital networks. PMDA regulatory pathways for AI-enabled diagnostic tools create certification bottlenecks for foreign vendors. Tokyo and Osaka metropolitan clusters concentrate demand for population health stratification platforms.
India
CDSCO emerging regulations for software-as-medical-device create compliance uncertainty for analytics vendors entering the market. Ayushman Bharat digital health mission drives interoperability investments across public hospital chains. Bangalore and Hyderabad technology corridors host development centers for cloud-native health data platforms.
Practice Analytics Market Competitive Environment
EHR-integrated incumbents and cloud-native challengers split the market between captive installed bases and subscription flexibility. Epic Systems leverages deep workflow integration to sustain demand within its existing customer footprint. Cerner Corporation competes through modular architectures spanning acute and ambulatory settings. Oracle and IBM Watson Health anchor enterprise data lake deployments. M&A activity concentrates around revenue cycle automation capabilities, while strategic partnerships address interoperability certification requirements.
Among EHR-native specialists, Epic Systems and Cerner Corporation exemplify the integrated-platform archetype, occupying positions where workflow embedding creates switching costs. Cloud-native challengers including Athenahealth and NextGen Healthcare represent the subscription-flexibility tier, serving ambulatory practices seeking rapid implementation without capital expenditure. Optum anchors the payer-affiliated segment, leveraging claims data access for denial prediction tools. These three archetypes—integrated EHR, cloud-native SaaS, and payer-backed analytics—define competitive positioning as procurement shifts from perpetual licenses to usage-based contracting.
| Leading Market Players |
|---|
| Epic Systems |
| Cerner Corporation |
| Optum |
| Allscripts Healthcare Solutions |
| McKesson Corporation |
| Athenahealth |
| IBM Watson Health |
| NextGen Healthcare |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in health informatics talent pools across the United States and Germany is compressing vendor margins while elevating implementation premiums. This scarcity simultaneously inflates professional services pricing tiers and forcing buyers toward subscription-native platforms that internalize operational complexity.
Pricing Analysis
Geographic price spreads between North American and European deployments exceed three-to-one for equivalent functionality, reflecting GDPR compliance architecture costs and EU AI Act conformity assessment burdens. Pricing stratifies across enterprise unlimited-seat licenses, modular per-provider subscriptions, and usage-based SaaS tiers. Cost compression in the ambulatory surgery center segment is intensifying because Epic Systems and Cerner Corporation bundle basic analytics with core EHR licenses. Private practices exhibit the highest price sensitivity, while large integrated delivery networks in Texas and Florida negotiate volume discounts that obscure list pricing.
Supply Chain Analysis
Upstream feedstock for practice analytics platforms draws from cloud infrastructure providers concentrated in the United States, Ireland, and Singapore, with Amazon Web Services and Microsoft Azure anchoring health data lake deployments. Core inputs encompass HL7 FHIR interface engines, SQL-based data warehouse architectures, and natural language processing training datasets. Single-source vulnerability around Epic Systems' proprietary data models forces third-party vendors to maintain dedicated engineering teams per health system. Distribution runs through direct vendor-to-provider contracts that displace traditional group purchasing organization intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control scarce health informatics talent and ONC certification timelines, while punishing those with undifferentiated reporting modules facing EHR-native bundling.
For Market Incumbents: Pre-empt cloud-native challengers by embedding predictive revenue cycle tools directly within EHR workflows before Athenahealth or NextGen Healthcare capture ambulatory market share. Invest in backward integration into natural language processing training data pipelines to reduce dependency on external AI vendors. Accelerate EU AI Act quality management system certifications to lock out unvalidated competitors from Bavaria and North Rhine-Westphalia procurement committees. For New Entrants and Emerging Players: Pursue rural health network consolidation in Montana and North Dakota, where critical access hospital shared services organizations lack dedicated IT staff and prize multi-tenant standardization. Target denial prediction modules for ambulatory surgery centers, a segment historically underinvested in financial analytics. Lead with rapid implementation timelines and per-case pricing that contrasts with incumbent enterprise licensing complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS-native deployment models as elastic compute eliminates server hardware procurement. Long-term viability favors vendors with established ONC certification pathways and recurring revenue bases exceeding eighty percent. Watch for FDA premarket review pathway announcements as inflection indicators for clinical decision support algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Compliance Certification | ONC mandates under the 21st Century Cures Act create immediate replacement demand across legacy installed bases. |
| Revenue Cycle Integration | Denial prediction tools penetrate ambulatory surgery centers seeking reimbursement velocity without IT overhead. |
| Ambient Listening Deployment | Real-time encounter coding automation compresses revenue cycle timelines from weeks to hours in primary care networks. |
| EU AI Act Conformity Assessment | High-risk algorithm classification forces quality management system investments that filter out undercapitalized vendors. |
| Rural Health Network Consolidation | Multi-tenant platforms serve Montana and North Dakota shared services organizations with standardized dashboards. |
Study Parameters
Cross-validation between hospital procurement database analysis and health system CIO interviews anchors the qualitative findings in this study. Primary fieldwork encompassed discussions with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and health informaticists across integrated delivery networks. Secondary validation drew from CMS Medicare data, ONC certification registries, FDA 510(k) filings, and hospital IT expenditure surveys. Bottom-up deployment modeling triangulates against top-down vendor revenue segmentation.
Calibration against historical EHR replacement cycles and cloud migration patterns informs the analytical framework across the projection horizon. Segmentation dimensions encompass deployment architecture, end-user scale, solution category, and application use case, with regulatory compliance tier as a healthcare-specific overlay. CAGRs derive from elasticity-adjusted adoption curves and vendor booking pipeline analysis. Forecast inputs incorporate ONC mandate enforcement intensity and EU AI Act implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in health system capital expenditure cycles or cloud infrastructure pricing would shift the trajectory. Forecasts reflect documented assumptions around certification timeline stability and interoperability standard adoption rates. Cross-checking against hospital IT budget benchmarks from Gartner or HIMSS is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Wi-Fi Analytics Market
Analytics
Online Analytical Processing Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Global Digital Intelligence Platform Market
Analytics
India Big Data Technology and Service Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Contact Center Intelligence Market
Analytics
North America Operational Intelligence Market
Analytics
Global Sales Performance Management Market
Analytics
North America HR Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Embedded Analytics Market
Analytics
Multichannel Analytics Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
UK Geospatial Analytics Market
Analytics
North America Speech Analytics Market