
 Active Data Warehousing Market | 2026-2036
Active Data Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Active Data Warehousing Market Analysis
Subscription-based software-defined query optimization is expanding how vendors monetize active data warehousing platforms. Teradata Corporation leverages its heritage in massively parallel processing to sustain premium positioning in on-premises deployments. Snowflake Computing Inc. differentiates through native separation of compute and storage. Oracle Corporation anchors enterprise accounts with integrated database-to-warehouse pipelines.
Active data warehousing refers to systems that continuously ingest, process, and serve analytical queries on operational data with sub-second latency, typically employing in-memory buffers, stream processing engines, and hybrid SQL-NoSQL engines to enable real-time decisioning without ETL batch windows. Cloud deployment models now capture the fastest expansion as enterprises migrate from fixed-capacity on-premises clusters to elastic consumption models. The predictive analytics application segment leads margin pools because it commands premium pricing for AI-ready data pipelines. In-memory computing technology dominates performance-sensitive workloads in financial services and telecommunications.
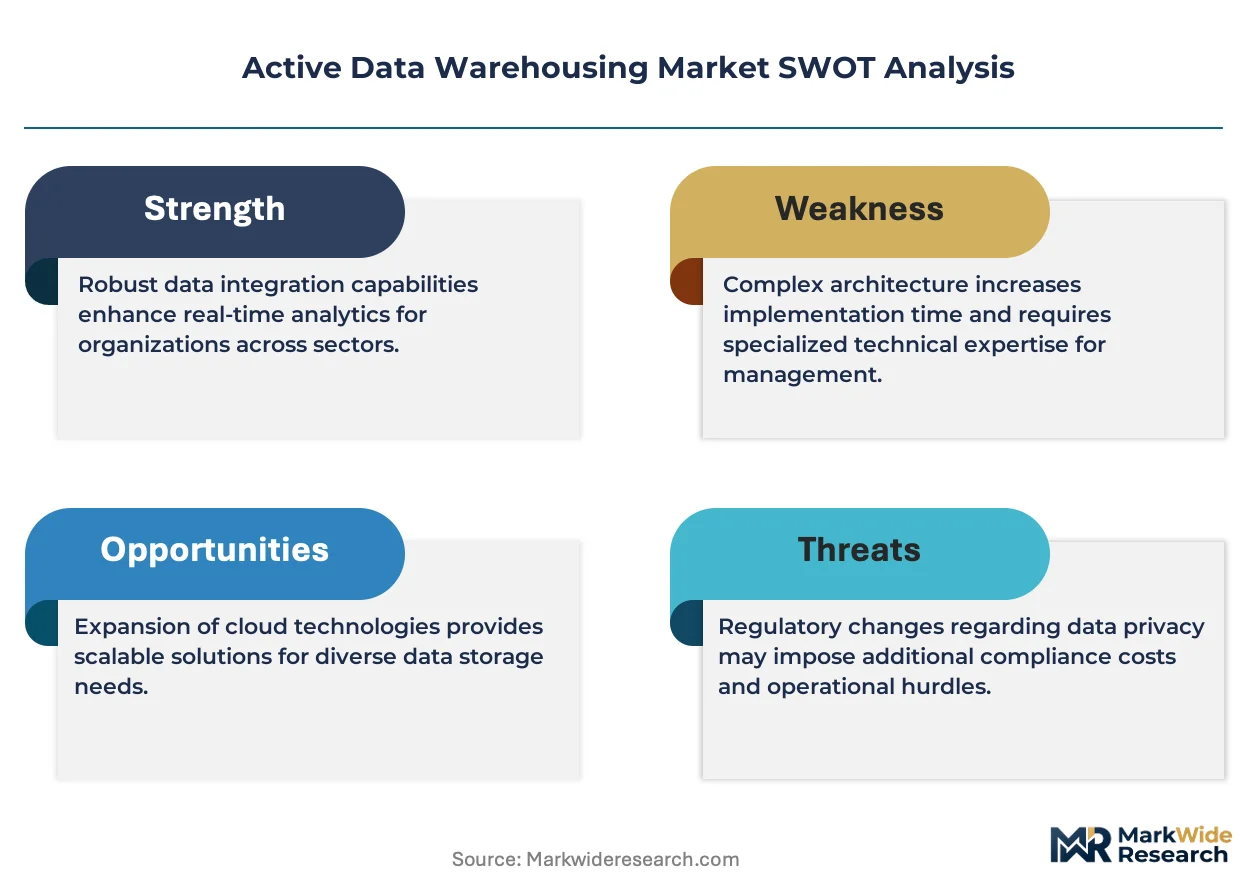
The EU AI Act, GDPR, and ISO 27001 framework collectively shape product roadmaps by mandating explainability, data lineage, and encryption standards that active warehouses must embed natively. HIPAA in the US imposes comparable constraints on healthcare deployments, while China's GB standards and Personal Information Protection Law restrict cross-border data flows. Stakeholders must monitor whether regulatory fragmentation forces vendors to maintain region-specific architecture variants or converge toward unified compliance templates.
Market Dynamics
The migration from batch ETL pipelines to continuous data streams is compressing architectural refresh cycles, forcing enterprises to consolidate operational and analytical systems into unified platforms rather than maintaining separate warehouses and data lakes.
Growth Catalysts
- EU AI Act explainability mandates:Financial services firms in Frankfurt and Stuttgart must deploy active warehouses to maintain real-time audit trails for algorithmic credit decisions.
- Stream processing engine maturation:Apache Flink and Kafka Streams enable sub-second latency at production scale, eliminating the technical barriers that previously restricted real-time analytics to niche applications.
- Germany industrial data unification:Automotive suppliers including Bosch and Continental require active warehouses to synchronize sensor telemetry from production lines with supply chain optimization models.
Market Restraints
- Specialized engineering talent scarcity:Organizations report 8-12 month hiring cycles for platform engineers with hybrid SQL-NoSQL and stream processing expertise.
- Memory cost volatility:DDR5 and high-bandwidth memory price fluctuations directly impact total cost of ownership for in-memory computing deployments.
- Cross-border data flow restrictions:China's Personal Information Protection Law and GB standards fragment cloud architectures, forcing vendors to maintain region-isolated infrastructure.
Strategic Opportunities
- Healthcare predictive analytics in the US:HIPAA-compliant active warehouses enable real-time patient monitoring and clinical decision support at integrated delivery networks.
- Edge-to-cloud convergence:Manufacturing facilities deploy lightweight stream processors at the edge with central warehouse aggregation, creating distributed active data architectures.
- India's digital public infrastructure:The Account Aggregator framework and RBI open banking mandates generate demand for low-latency data sharing platforms among fintech lenders.
Industry Challenges
- ISO 27001 and SOC 2 Type II certification timelines:Cloud-native vendors face 6-9 month audit cycles before enterprise procurement teams approve active warehouse deployments.
- Mainframe integration complexity:Large banks struggle to pipe core banking transaction streams into modern active warehouses without disrupting legacy COBOL batch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Data Warehousing Market |
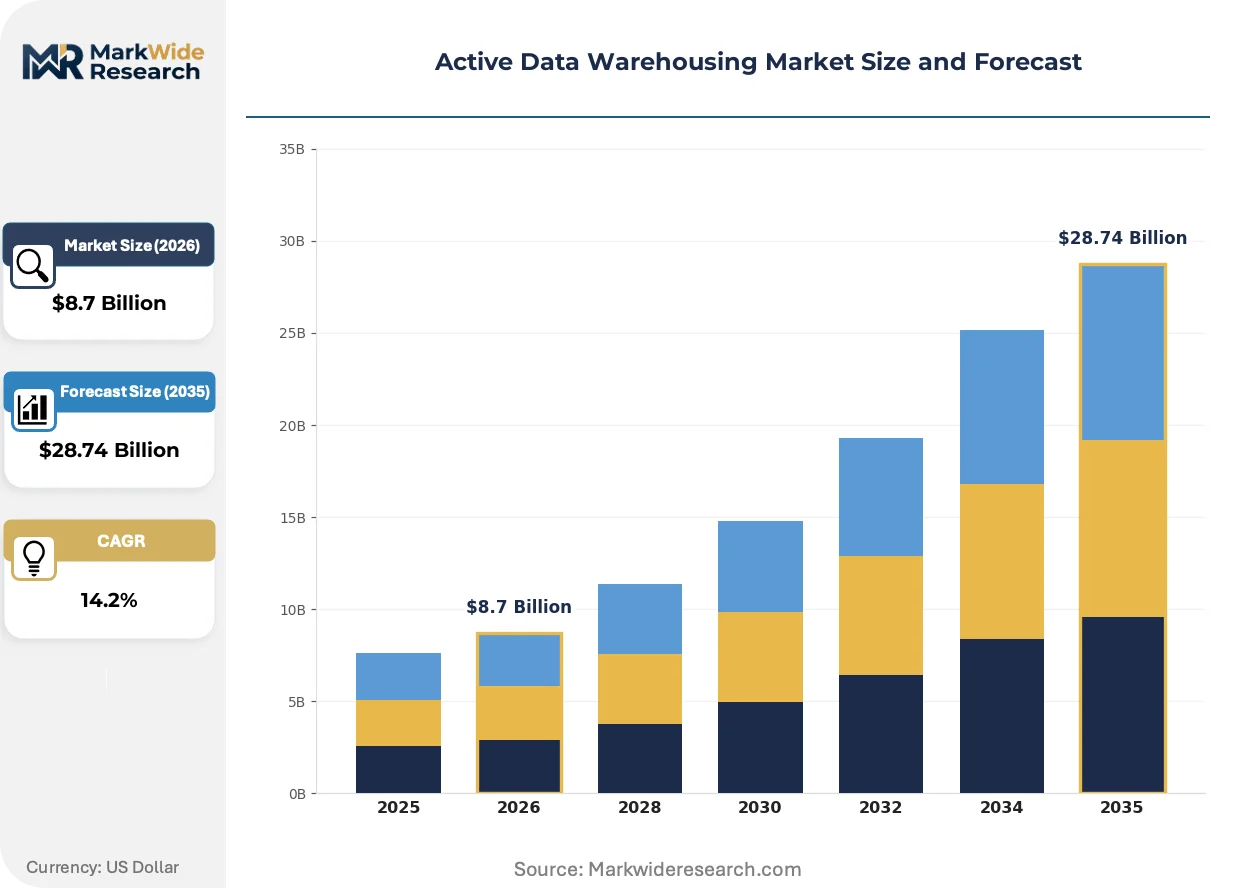
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Multi-Cloud End User: Healthcare, Retail, Manufacturing, Telecommunications Technology: In-Memory Computing, Data Lakes, SQL, NoSQL Application: Business Intelligence, Predictive Analytics, Data Integration, Reporting |
| Companies Covered | Amazon Web Services, Teradata Corporation, Oracle Corporation, International Business Machines Corporation, Microsoft Corporation, Snowflake Computing Inc., Hewlett Packard Enterprise Development LP, SAP SE, Cloudera Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Data Warehousing Market Emerging Trajectories
Hybrid transaction/analytical processing architectures are collapsing the traditional separation between operational databases and analytical warehouses, creating new competitive battlegrounds around latency guarantees and concurrent workload isolation.
Vectorized query execution engines are integrating with GPU acceleration to process high-velocity streaming data for fraud detection and algorithmic trading. Goldman Sachs and JPMorgan Chase deploy these architectures for real-time risk calculations. The technology is integrating machine learning inference directly into the data path, eliminating round-trips to separate model serving infrastructure.
GDPR Article 35 data protection impact assessments now require automated lineage tracking for all personal data flows. Active warehouse vendors embed column-level provenance and policy enforcement engines to satisfy supervisory authority audits. Healthcare and financial services buyers in France and Germany prioritize platforms with CNIL and BSI certification pre-approval.
Consumption-based pricing models displace perpetual licenses as the dominant procurement structure. Enterprise buyers negotiate commit-based contracts with burst capacity allowances rather than provisioning fixed clusters. This shift is most pronounced among SaaS-native companies in the US and UK, where finance teams prefer operational expenditure treatment for infrastructure software.
Active Data Warehousing Market Segmentation
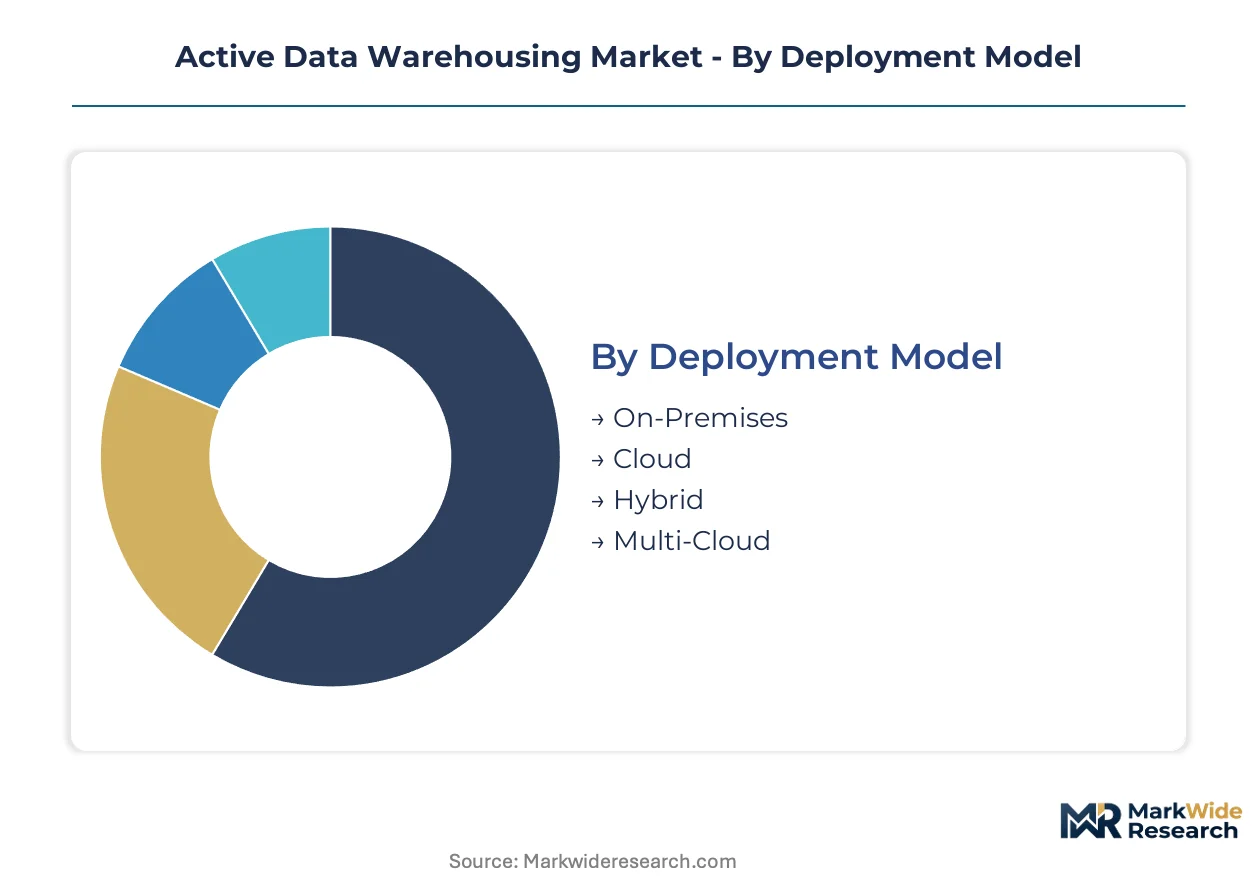
Architectural choices in active data warehousing determine latency profiles, compliance postures, and total cost trajectories. Procurement teams evaluate deployment models, technology stacks, and application priorities against specific workload requirements rather than adopting uniform platforms.
Deployment Model:
Refresh cycles accelerate as enterprises migrate from fixed-capacity infrastructure to elastic consumption frameworks.
- On-Premises:Massively parallel processing clusters with dedicated hardware deliver sub-millisecond latency for algorithmic trading floors. Frankfurt and Stuttgart financial institutions maintain these deployments to satisfy EU AI Act audit trail mandates without cloud data residency risks.
- Cloud:Separation of compute and storage enables automatic scaling during peak analytical workloads. SaaS-native companies in the US and UK prefer operational expenditure treatment and burst capacity allowances over fixed cluster provisioning.
- Hybrid:Sensitive workloads remain on-premises while batch analytics shift to elastic cloud resources. Manufacturing conglomerates in Germany deploy this architecture to keep production telemetry local while aggregating supply chain optimization models centrally.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP mitigates vendor lock-in and satisfies regional data sovereignty requirements. China's Personal Information Protection Law drives this pattern among multinationals requiring region-isolated infrastructure.
Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest.
End User:
Industry-specific latency requirements and regulatory constraints shape platform selection and integration complexity.
- Healthcare:HIPAA-compliant active warehouses enable real-time patient monitoring at integrated delivery networks. US hospitals prioritize platforms with pre-approved security certifications to compress 6-9 month procurement cycles.
- Retail:Inventory optimization and personalized recommendation engines demand continuous ingestion of point-of-sale streams. European retailers embed GDPR Article 35 automated lineage tracking to satisfy CNIL supervisory audits.
- Manufacturing:Bosch and Continental synchronize sensor telemetry from production lines with supply chain models. German automotive suppliers require hybrid transaction/analytical processing to collapse operational and analytical system separation.
- Telecommunications:Network performance monitoring and subscriber churn prediction process millions of events per second. In-memory computing dominates these performance-sensitive workloads due to strict latency service level agreements.
Manufacturing leads by revenue concentration, with Healthcare expanding most quickly.
Technology:
Performance guarantees and workload isolation capabilities determine competitive positioning among architectural approaches.
- In-Memory Computing:DDR5 and high-bandwidth memory enable real-time risk calculations at Goldman Sachs and JPMorgan Chase. Price volatility in memory components directly impacts total cost of ownership for financial services deployments.
- Data Lakes:Raw storage of unstructured telemetry supports downstream AI training pipelines. Organizations struggle to hire platform engineers with hybrid SQL-NoSQL expertise, extending hiring cycles to 8-12 months.
- SQL:Mature query optimization and broad analyst skill availability sustain enterprise adoption. Mainframe integration complexity restricts migration velocity at large banks with legacy COBOL batch windows.
- NoSQL:Schema flexibility accommodates variable-format IoT streams and social media feeds. Edge-to-cloud convergence patterns deploy lightweight stream processors with central warehouse aggregation.
In-Memory Computing commands premium pricing, with Data Lakes gaining share fastest.
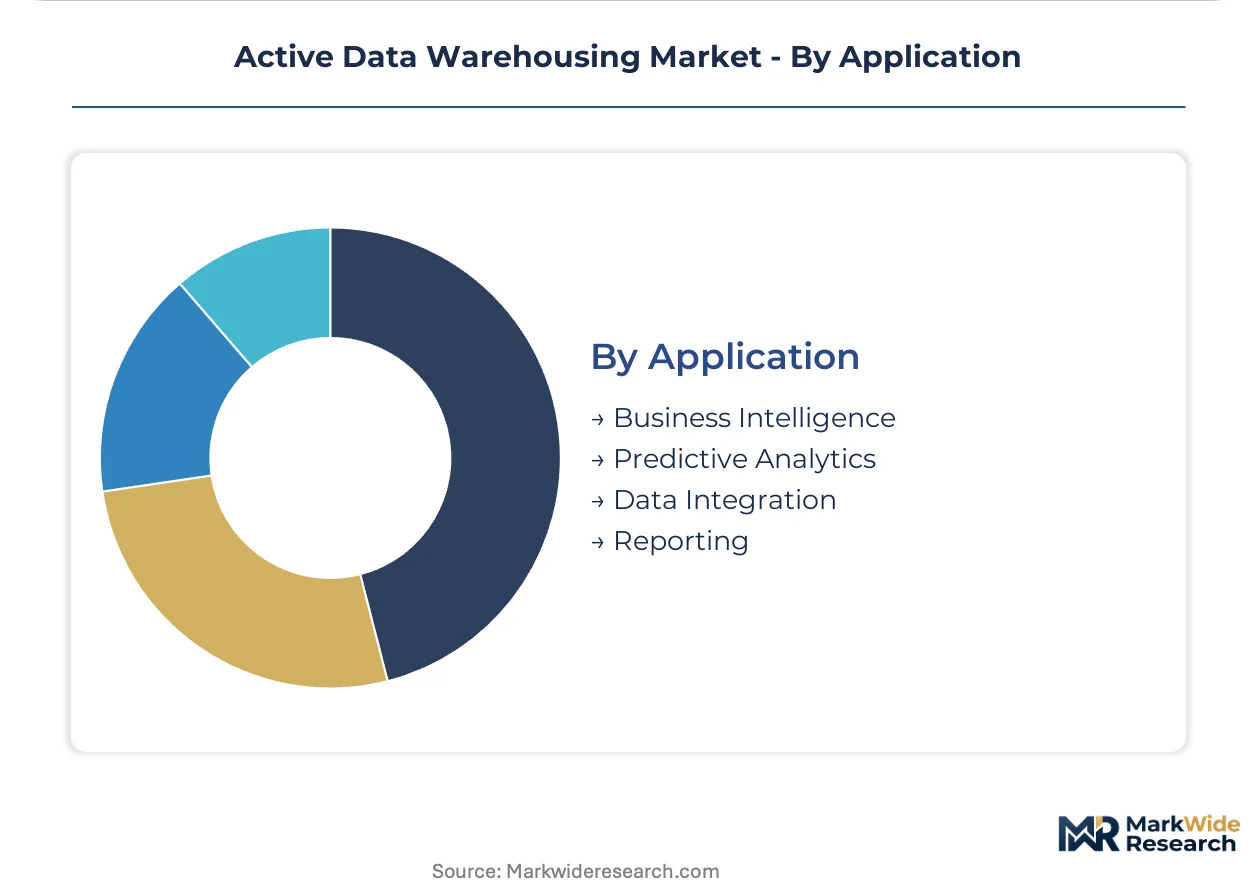
Application:
Value capture varies by analytical sophistication, with predictive workloads commanding higher margins than retrospective reporting.
- Business Intelligence:Dashboards and ad-hoc querying remain the foundational use case across industries. Consumption-based pricing models displace perpetual licenses as finance teams prefer operational expenditure treatment.
- Predictive Analytics:AI-ready data pipelines integrate machine learning inference directly into the data path. This segment leads margin pools due to premium pricing for real-time decisioning capabilities.
- Data Integration:Continuous ETL replacement with stream processing eliminates batch windows. Apache Flink and Kafka Streams enable sub-second latency at production scale.
- Reporting:Regulatory submissions and operational scorecards require governed, auditable data flows. GDPR and EU AI Act mandates accelerate investments in explainable, lineage-tracked architectures.
Business Intelligence retains the largest installed base, with Predictive Analytics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping deployment patterns as enterprises migrate workloads toward jurisdictions with clearer data governance frameworks. The EU AI Act and GDPR compliance costs in Frankfurt and Paris are pushing some financial services firms to evaluate UK and Swiss alternatives. Cloud providers are responding with region-isolated infrastructure that satisfies cross-border flow restrictions without sacrificing latency guarantees.
United States
HIPAA-compliant active warehouses dominate healthcare procurement at integrated delivery networks in Boston and Nashville. The SEC's real-time disclosure mandates accelerate adoption among New York and Chicago trading floors. Goldman Sachs and JPMorgan Chase anchor financial services demand with sub-millisecond risk calculation requirements.
Germany
Industrial conglomerates in Stuttgart and Munich deploy active warehouses to unify sensor telemetry with supply chain optimization. The EU AI Act's explainability requirements drive Frankfurt financial institutions toward governed, low-latency architectures. Bosch and Continental exemplify automotive supplier demand for hybrid transaction/analytical processing.
United Kingdom
Post-Brexit regulatory divergence creates positioning opportunities for London-based fintechs seeking flexible data residency options. The Financial Conduct Authority's operational resilience rules compress procurement cycles for real-time audit trail platforms. Edinburgh and Manchester financial centers concentrate demand for cloud-native warehouse deployments.
China
GB standards and the Personal Information Protection Law fragment cloud architectures, forcing region-isolated infrastructure investments. Shanghai and Beijing technology conglomerates prioritize domestic vendors for sensitive operational data processing. State-owned banks in Shenzhen maintain on-premises deployments to satisfy data localization mandates.
India
The RBI's open banking directives and Account Aggregator framework generate fintech demand for low-latency data sharing in Mumbai and Bangalore. SEBI's real-time surveillance requirements accelerate exchange technology modernization. Hyderabad and Chennai IT services hubs concentrate deployment expertise for hybrid cloud migrations.
Active Data Warehousing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across deployment models, with cloud-native vendors capturing elastic consumption growth while heritage on-premises players defend high-availability financial services accounts. Market structure tilts toward consolidation at the platform layer but fragments across specialized integration and consulting services. Three archetypes dominate: hyperscale cloud providers with warehouse-native services, independent software vendors with differentiated query engines, and systems integrators bridging legacy mainframe pipelines. Competitive moves concentrate on M&A for stream processing capabilities and strategic partnerships for edge-to-cloud orchestration.
Within the heritage database tier, Teradata Corporation and Oracle Corporation occupy positions shaped by decades of massively parallel processing investment and enterprise account penetration. Snowflake Computing Inc. exemplifies the cloud-native archetype with consumption-based pricing models that displace perpetual license structures. These three anchors span the competitive spectrum from on-premises high-availability deployments to elastic multi-cloud architectures, with each representing distinct migration pathways for enterprises consolidating operational and analytical workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Teradata Corporation |
| Oracle Corporation |
| International Business Machines Corporation |
| Microsoft Corporation |
| Snowflake Computing Inc. |
| Hewlett Packard Enterprise Development LP |
| SAP SE |
| Cloudera Inc. |
| Others |
Supply Flow & Price Mechanics
Performance-latency certification tiers bifurcate the market between sub-millisecond financial services deployments and elastic cloud consumption models, with premium on-premises clusters in Frankfurt commanding sustained margin premiums while SaaS-native buyers in London and New York negotiate burst-capacity allowances that compress distributor margins.
Pricing Analysis
Distributor margins compress most severely in the cloud-native channel, where hyperscaler marketplaces displace traditional value-added resellers. Consumption-based subscription models with commit-based contracts dominate procurement, displacing perpetual licenses. Price differentiation rests on latency guarantees and EU AI Act pre-certification status, with Frankfurt financial institutions showing lowest price sensitivity due to regulatory compliance imperatives while mid-market SaaS buyers in the US and UK drive hardest for operational expenditure treatment and volume discounts. Pricing pressure intensifies in the mid-tier as Snowflake and Databricks compress margins for second-tier query engines.
Supply Chain Analysis
Single-source vulnerability sits with DDR5 and high-bandwidth memory fabrication concentrated in South Korea and Taiwan, where Samsung and SK Hynix anchor global supply. Component dependencies extend to NVIDIA GPU accelerators for vectorized query execution and Intel Xeon Sapphire Rapids for mainstream deployments. Supply chain risk centers on memory price volatility driven by commodity DRAM cycles, with downstream distribution running through direct enterprise sales teams for on-premises deployments and hyperscaler marketplaces for cloud consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between Germany's EU AI Act compliance costs and Switzerland's regulatory divergence, where Zurich-based financial institutions capture equivalent latency performance with reduced audit trail mandates.
For Market Incumbents: To counter Snowflake's consumption-based pricing traction, Teradata and Oracle must accelerate hybrid cloud orchestration capabilities and secure BSI pre-certification for EU AI Act explainability mandates in Stuttgart automotive supplier accounts. Capacity investments in Frankfurt and London data center regions preserve high-availability positioning for algorithmic trading floors. For New Entrants and Emerging Players: Regional banks in India's Mumbai and Bangalore corridors present the most penetrable buyer archetype, underserved by legacy vendor direct sales coverage and newly compelled by RBI open banking latency requirements. A channel-native go-to-market through local systems integrators accelerates procurement cycle compression versus direct enterprise sales models. For Investors and Strategic Acquirers: Asymmetric upside sits with stream processing engine specialists possessing Apache Flink production deployments at scale, given the technology's centrality to sub-second latency architectures. Long-term viability hinges on embedding automated lineage tracking for GDPR Article 35 compliance. The signal to watch is CNIL or BSI certification pre-approval velocity as an inflection indicator for European financial services penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Stream Processing Engine Acquisition | Apache Flink expertise eliminates technical barriers to sub-second latency at Goldman Sachs-scale deployments. |
| EU AI Act Pre-Certification Investment | BSI and CNIL approval compresses 6-9 month procurement cycles for Frankfurt financial institutions. |
| Edge-to-Cloud Orchestration Partnership | Bosch production telemetry integration creates distributed active data architectures for Stuttgart automotive suppliers. |
| Healthcare HIPAA Compliance Pathway | Integrated delivery networks in Boston and Nashville prioritize pre-certified platforms for real-time patient monitoring. |
| Multi-Cloud Workload Portability Development | China's Personal Information Protection Law drives region-isolated infrastructure demand among multinationals. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs at integrated delivery networks, platform engineers with hybrid SQL-NoSQL expertise, IT procurement officers at Frankfurt financial institutions, and channel partners distributing Teradata and Oracle deployments. Secondary validation drew from SEC 10-K filings of publicly traded database vendors, hyperscaler capex disclosures, EU AI Act implementation guidance, and BSI certification databases. Bottom-up sizing of individual vendor revenues and top-down cross-check against aggregate IT infrastructure spending established triangulation boundaries.
Historical reference periods anchored the projection horizon through year-over-year growth pattern analysis and technology adoption curve positioning. Segmentation dimensions modeled include deployment architecture, latency requirement tier, regulatory compliance framework, and vertical industry concentration. CAGR derivation incorporated technology maturation curves for stream processing engines, memory cost trajectory assumptions, and regulatory enforcement timeline scenarios for GDPR and EU AI Act mandates.
Underlying measurement precision varies by segment; cloud deployment models carry tighter precision than on-premises configurations due to hyperscaler disclosure transparency. Forecasts reflect assumptions regarding DDR5 price stabilization, EU AI Act enforcement consistency across member states, and the velocity of mainframe-to-cloud migration at large banks with legacy COBOL dependencies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe HR Analytics Market
Analytics
Marketing Mix Optimization Market
Analytics
Cognitive Analytics Solutions Market
Analytics
Global Mobile BI Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Face Analytics Market
Analytics
Dark Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Load (ETL) Market
Analytics
Crowd Analytics Market
Analytics
Global Performance Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Cyprus ICT Market
Analytics
Global Talent Intelligence Software Market
Analytics
Construction Data Analytics Software Market
Analytics
In-Memory Analytics Tools Market