
 APAC Operational Intelligence Market | 2026-2036
APAC Operational Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Operational Intelligence Market Outlook
China's dual carbon goals under MEE oversight is realigning operational intelligence procurement across heavy industry. Schneider Electric SE leverages its energy management software stack to anchor factory digitization projects in East Asia. Rockwell Automation, Inc specializes in edge-to-cloud analytics for discrete manufacturing, while Splunk Inc. competes on IT-OT convergence platforms for telecommunications operators.
Operational intelligence denotes the real-time collection, correlation, and analysis of machine data, event streams, and business metrics to enable immediate operational decisions, typically processing sub-second latency requirements across distributed sensor networks. The primary commercial purpose centers on reducing unplanned downtime and optimizing resource throughput in complex production environments. Predictive maintenance applications now lead solution demand as asset-intensive sectors prioritize failure prevention over post-incident analysis. Cloud-based deployment models represent the fastest-expanding segment, though on-premise retains dominance in regulated telecommunications and defense-adjacent manufacturing.
Japan's METI enforces cybersecurity frameworks for critical infrastructure operators, directly shaping product certification requirements for operational intelligence vendors. India's BIS standards for industrial IoT interoperability and China's GB standards for data security in smart manufacturing jointly determine market access protocols across the region. Australia's TGA and South Korea's MFDS have issued complementary guidance on operational data integrity for pharmaceutical and medical device production, extending compliance obligations beyond traditional manufacturing sectors. Stakeholders must monitor divergence between national data localization mandates and cross-border cloud service architectures when architecting regional platform strategies.
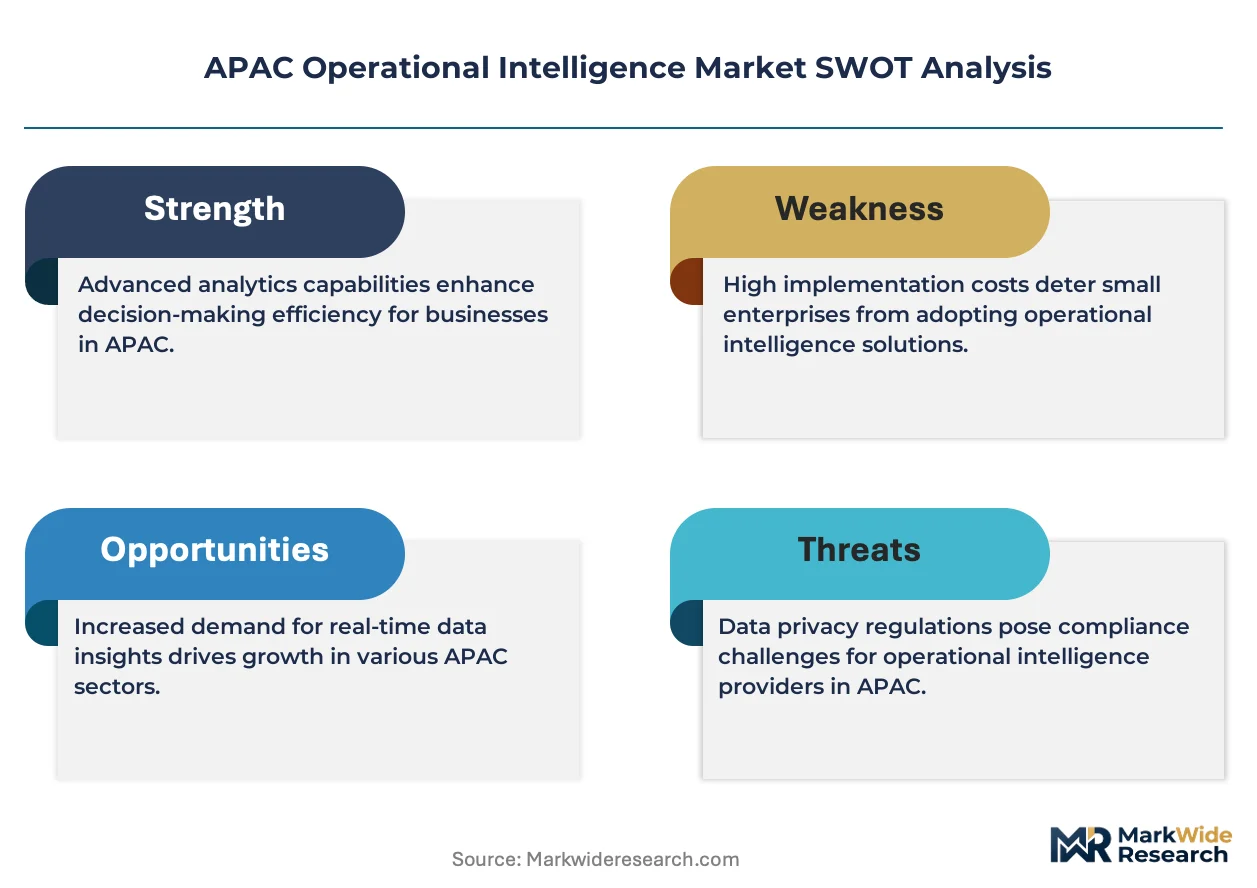
Market Dynamics
China's MIIT cloud migration mandates and India's MeitY data localization requirements are forcing manufacturers toward hybrid operational intelligence architectures that split processing between edge sensors and sovereign cloud instances.
Growth Catalysts
- Dual carbon enforcement:China's MEE oversight of heavy industry emissions is mandating real-time energy monitoring systems that operational intelligence platforms deliver.
- Discrete manufacturing automation:Japanese automotive suppliers are deploying edge-to-cloud analytics to compress quality feedback loops from hours to seconds.
- Smart manufacturing standards:India's BIS interoperability frameworks for industrial IoT are accelerating platform procurement across Maharashtra and Gujarat industrial corridors.
Market Restraints
- Semiconductor supply concentration:Edge device production depends on Taiwan and South Korea foundry capacity, exposing deployment timelines to geopolitical friction.
- Data localization compliance costs:China's GB standards for cross-border data transfer impose architectural constraints that inflate platform engineering overhead.
- Limited OT cybersecurity talent:Japan's METI framework requirements exceed available certified personnel, extending implementation timelines for critical infrastructure operators.
Strategic Opportunities
- Indonesia's nickel processing expansion:Battery material refineries in Sulawesi and Halmahera lack operational intelligence infrastructure, creating first-mover platform deployment potential.
- IT-OT convergence in telecommunications:5G network slicing is converging with operational intelligence to enable predictive maintenance for base station power systems.
- Vietnam's manufacturing FDI inflow:Samsung and Foxconn supplier parks in Bac Ninh and Hai Phong are greenfield sites without legacy system integration burdens.
Industry Challenges
- Legacy SCADA integration complexity:Brownfield facilities in China's rust belt provinces require protocol translation layers that degrade real-time performance guarantees.
- Cross-border certification timelines:Australia's TGA data integrity requirements for pharmaceutical manufacturing extend vendor qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Operational Intelligence Market |
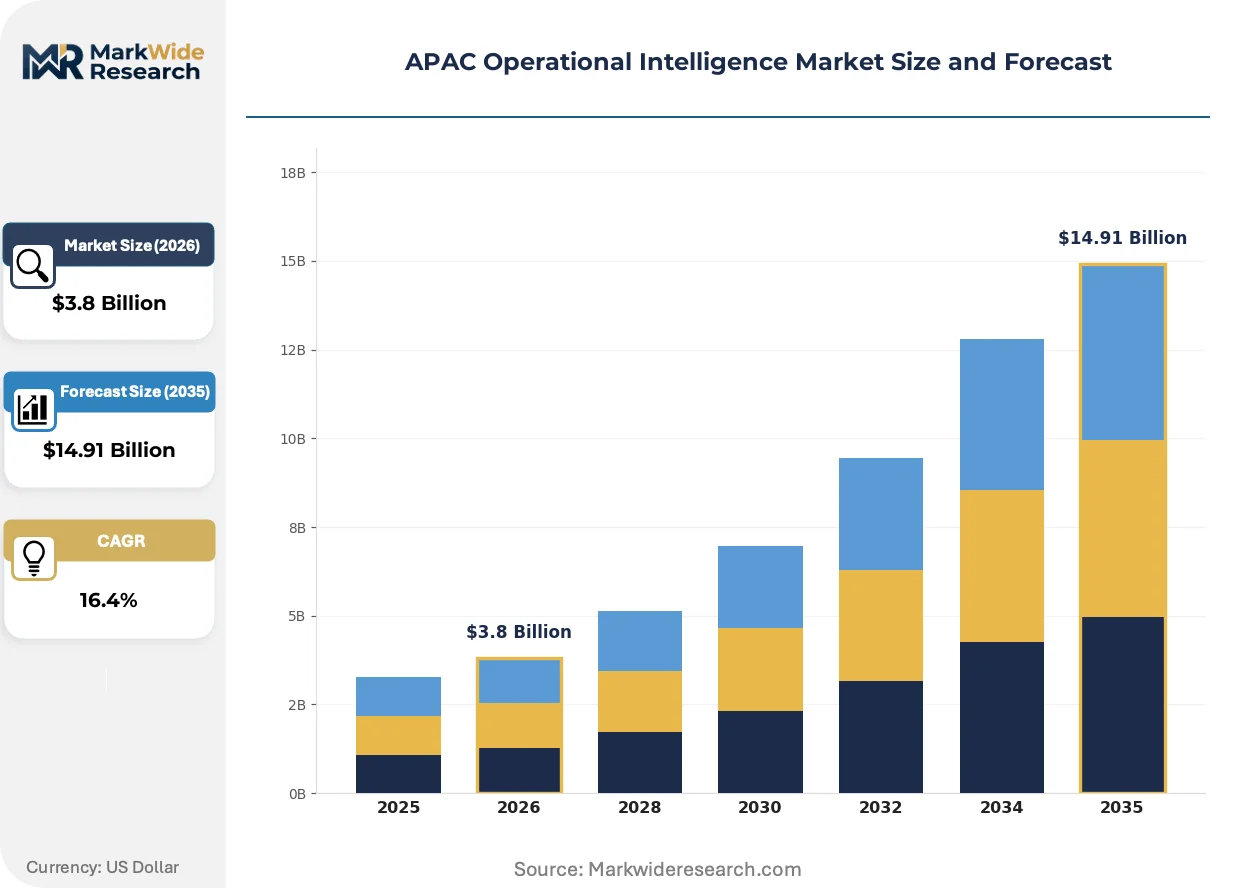
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Supply Chain Optimization, Predictive Maintenance, Workforce Management, Asset Tracking End User: Manufacturing, Logistics, Retail, Telecommunications Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services Solution Type: Real-Time Analytics, Reporting Tools, Data Integration, Visualization Platforms |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Splunk Inc., Schneider Electric SE, Microsoft Corporation, Hewlett Packard Enterprise Company, General Electric Company, Rockwell Automation, Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Operational Intelligence Market Strategic Shifts
Operational intelligence architectures are pivoting from centralized data lakes toward federated edge processing, driven by latency requirements for autonomous quality control and sovereign data constraints.
Digital twin technology is converging with physics-based simulation to enable virtual commissioning of production lines before physical deployment. Automotive manufacturers in Japan's Aichi prefecture are adopting these tools to reduce ramp-up time for new vehicle platforms. The structural compression of commissioning cycles is converging with operational intelligence to accelerate factory ROI realization.
Japan's METI cybersecurity framework for critical infrastructure is mandating air-gapped operational data zones with encrypted cross-domain transfer protocols. Heavy industry operators in steel and chemicals must now segment IT and OT networks with certified gateway appliances. Japanese petroleum refineries are responding by procuring operational intelligence platforms with built-in IEC 62443 compliance modules.
Asset-as-a-service contracting is displacing perpetual license purchases among Southeast Asian manufacturers with constrained capex budgets. Malaysian electronics contract manufacturers now prefer subscription-based operational intelligence with uptime guarantees over capital-intensive on-premise deployments. This preference shift is most visible in Penang's industrial free trade zone where facility ownership fragmentation complicates long-term software investment decisions.
APAC Operational Intelligence Market Segmentation
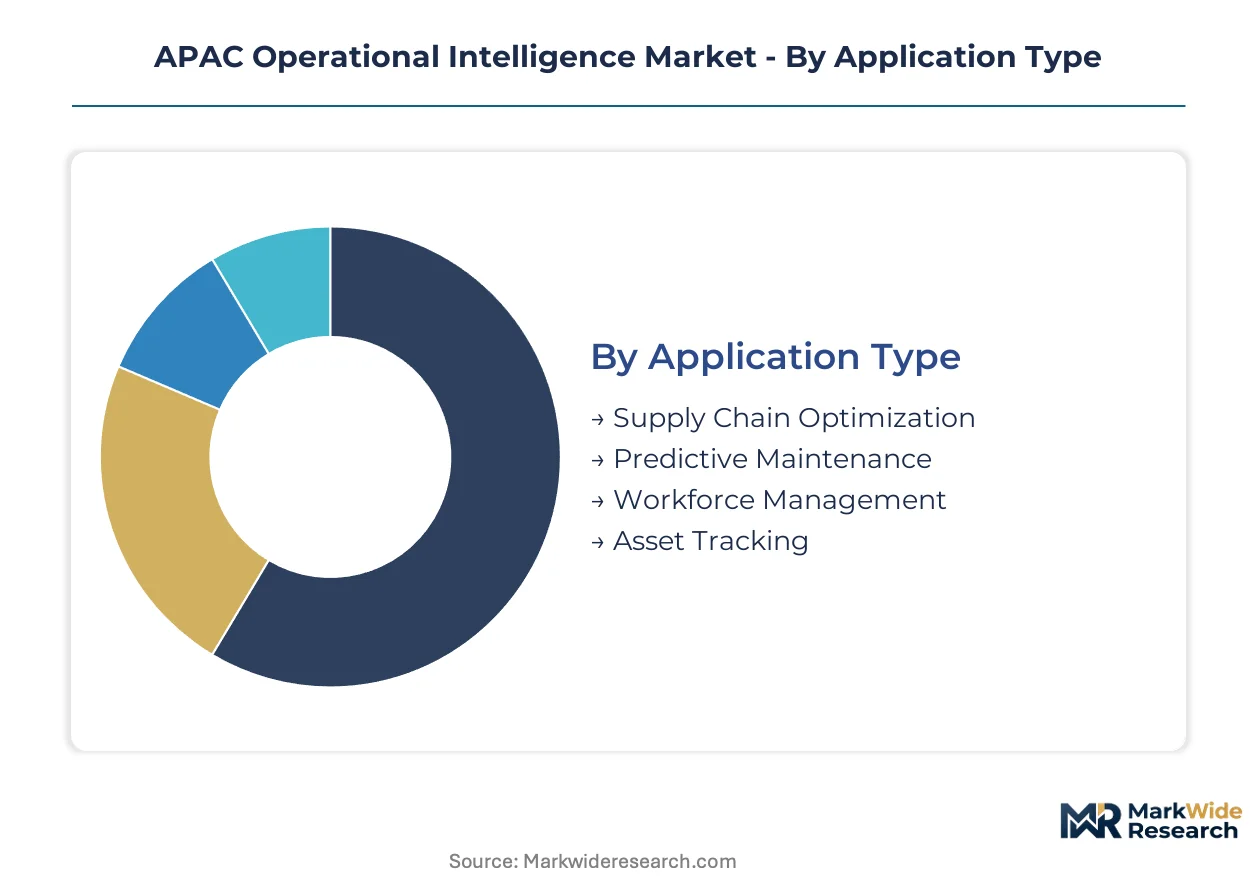
Operational intelligence procurement patterns across APAC diverge sharply by deployment architecture and latency tolerance. Solution buyers prioritize segments that reconcile sovereign data constraints with real-time processing requirements in factory and telecommunications environments.
Application Type:
Supply concentration among predictive maintenance vendors in China's industrial corridor is reshaping competitive dynamics across this category.
- Predictive Maintenance:Machine learning models process vibration, thermal, and acoustic sensor streams to forecast equipment failure before production interruption. Demand concentrates in China's steel and chemical installations under MEE emissions monitoring mandates, where unplanned downtime carries dual financial and regulatory penalties.
- Supply Chain Optimization:Multi-tier inventory visibility platforms correlate supplier production data with logistics positioning to compress replenishment cycles. Japanese automotive suppliers in Aichi prefecture deploy these tools to synchronize tier-2 component availability with final assembly sequencing, reducing buffer stock carrying costs.
- Workforce Management:Real-time labor allocation systems match operator skills with production schedule requirements in India's Maharashtra electronics parks.
- Asset Tracking:Indoor positioning and geofencing solutions monitor high-value equipment movement across Indonesia's nickel processing facilities in Sulawesi.
Today's leader: Predictive Maintenance. Tomorrow's challenger: Supply Chain Optimization.
End User:
Cost tier differentiation separates capital-intensive deployment patterns across manufacturing verticals from lighter-weight service sector implementations.
- Manufacturing:Discrete and process producers deploy edge-to-cloud architectures for quality feedback compression and energy optimization. China's Jiangsu and Guangdong province factories under MIIT cloud migration directives represent the densest concentration of platform procurement.
- Telecommunications:5G network operators integrate operational intelligence with network slicing to enable predictive maintenance for base station power and cooling systems. South Korea's MFDS cybersecurity requirements for critical infrastructure are accelerating IT-OT convergence platform adoption.
- Logistics:Port operators and third-party logistics providers in Singapore and Busan deploy asset tracking for container positioning optimization.
- Retail:Omnichannel inventory visibility systems process point-of-sale and warehouse data for demand sensing in Australia's urban distribution networks.
Manufacturing commands current procurement volume. Telecommunications offers the steepest expansion trajectory as network infrastructure scales.
Deployment Model:
Volume concentration favors hybrid architectures that split processing between edge sensors and sovereign cloud instances.
- Hybrid:Split processing architectures route latency-sensitive analytics to local edge nodes while aggregating historical data in sovereign cloud environments. India's MeitY data localization requirements and China's GB standards for cross-border transfer are forcing manufacturers toward this model despite elevated engineering overhead.
- Cloud-Based:Fully managed SaaS platforms deliver predictive analytics without on-premise infrastructure investment. Malaysian electronics contract manufacturers in Penang's free trade zone prefer subscription-based deployment with uptime guarantees over capital-intensive alternatives.
- On-Premise:Air-gapped installations persist in Japan's petroleum refineries under METI cybersecurity framework requirements for critical infrastructure.
- Managed Services:Outsourced platform operation with performance-based contracting appeals to Southeast Asian manufacturers with constrained technical staffing.
Hybrid dominates current architectural decisions. Cloud-Based deployment is gaining share fastest as vendor managed services mature.
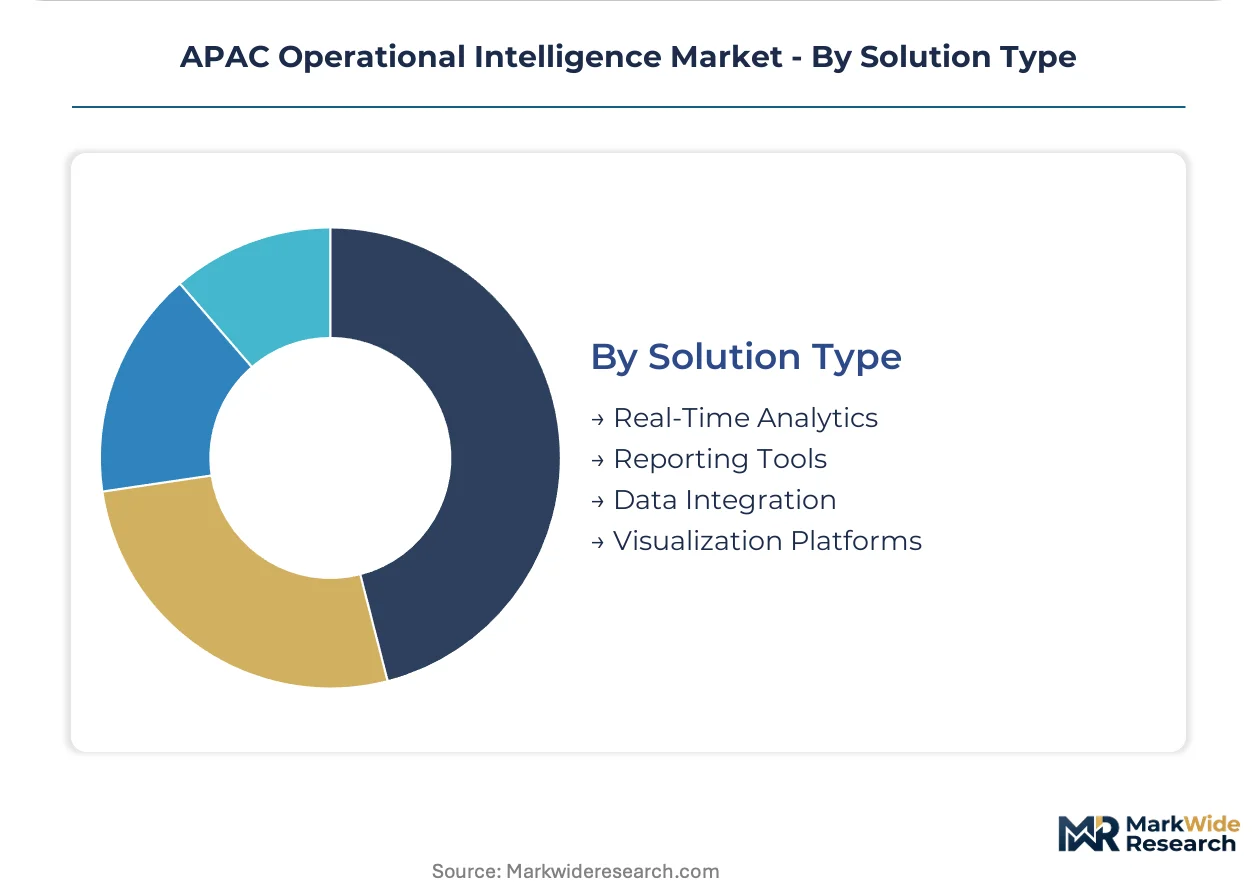
Solution Type:
Customer type separation distinguishes engineering-led buyers seeking simulation capabilities from operations teams prioritizing dashboard accessibility.
- Real-Time Analytics:Sub-second stream processing engines correlate machine data with business metrics for immediate operational intervention. Japan's automotive suppliers deploy these platforms to compress quality feedback loops from hours to seconds during production ramp-ups.
- Data Integration:Protocol translation and normalization layers connect legacy SCADA systems with modern analytics platforms. Brownfield facilities in China's rust belt provinces require these tools to bridge decades-old control systems with contemporary architectures.
- Visualization Platforms:Role-based dashboard systems present operational KPIs to floor supervisors and plant managers across India's Gujarat industrial corridor.
- Reporting Tools:Scheduled and ad-hoc analytical outputs support compliance documentation for Australia's TGA pharmaceutical manufacturing requirements.
Real-Time Analytics anchors current procurement. Data Integration is climbing fastest as legacy system connectivity demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OT cybersecurity specialists in Japan and cloud architects in India anchor the region's operational intelligence talent base, while China's factory automation engineers concentrate platform deployment expertise in the Yangtze and Pearl River deltas.
China
Steel and chemical producers under MEE emissions mandates drive predictive maintenance procurement. MIIT cloud migration directives force hybrid architectures splitting edge processing from sovereign cloud instances. Factory clusters in Shanghai, Jiangsu, and Guangdong provinces deploy real-time energy monitoring to meet dual carbon enforcement timelines.
Japan
Automotive suppliers in Aichi prefecture compress quality feedback loops through edge-to-cloud analytics platforms. METI cybersecurity frameworks mandate air-gapped operational data zones with encrypted cross-domain transfer for critical infrastructure. Petroleum refineries procure IEC 62443-compliant platforms to segment IT and OT networks.
India
Electronics manufacturers in Maharashtra and Gujarat industrial corridors accelerate platform procurement under BIS interoperability standards. MeitY data localization requirements route sensitive processing to domestic cloud instances. Real-time labor allocation systems match operator skills with production schedules in Pune and Chennai electronics parks.
South Korea
5G network operators integrate operational intelligence with network slicing for base station predictive maintenance. MFDS cybersecurity requirements for critical infrastructure accelerate IT-OT convergence platform adoption. Busan port operators deploy container positioning optimization alongside telecommunications infrastructure scaling.
Australia
Pharmaceutical manufacturers face TGA data integrity requirements extending vendor qualification cycles. Urban distribution networks process point-of-sale and warehouse data for omnichannel demand sensing. Sydney and Melbourne logistics hubs prioritize asset tracking for high-value equipment movement compliance.
APAC Operational Intelligence Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the operational intelligence landscape, with integrated automation vendors maintaining foundry-like control over hardware-software stacks while pure-play analytics firms operate asset-light model flexibility. The market structure tiers between multinational industrial conglomerates, specialized software vendors, and regional system integrators. Three archetypes dominate: energy management specialists anchoring factory digitization, edge-to-cloud analytics providers serving discrete manufacturing, and IT-OT convergence platforms targeting telecommunications. Competitive moves concentrate on strategic partnerships bridging legacy SCADA connectivity gaps and portfolio diversification into subscription-based managed services.
Within the industrial automation tier, Schneider Electric SE represents the energy management software archetype, Rockwell Automation, Inc exemplifies edge-to-cloud specialization for manufacturing environments, and Splunk Inc occupies a position exemplifying IT-OT convergence for telecommunications operators. These three companies anchor distinct competitive vectors without overlapping core positioning, allowing each to defend margin structure through differentiated technical capabilities rather than direct price competition.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Splunk Inc. |
| Schneider Electric SE |
| Microsoft Corporation |
| Hewlett Packard Enterprise Company |
| General Electric Company |
| Rockwell Automation, Inc |
| Others |
Value Chain & Pricing Dynamics
Edge computing hardware costs cascade through three downstream pricing tiers for operational intelligence platforms, with semiconductor foundry capacity in Taiwan and South Korea determining baseline module economics before MIIT cloud compliance requirements in China add sovereign architecture premiums.
Pricing Analysis
Subscription bundling separates platform vendors from component suppliers in operational intelligence procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with IEC 62443-compliant platforms commanding premiums in Japan's petroleum sector. Cost compression in standard-tier SaaS offerings is intensifying because Malaysian electronics contract manufacturers negotiate uptime-guarantee clauses. Price-sensitive buyers concentrate among Southeast Asian managed services adopters, while Japan's critical infrastructure operators show lowest sensitivity due to METI cybersecurity mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's Jiangsu and Guangdong factory clusters, while value-added resellers serve mid-tier discrete manufacturers. Distribution runs through Singapore and Hong Kong logistics hubs for edge hardware, with software delivery increasingly localized to sovereign cloud instances per India's MeitY requirements. Taiwan and South Korea anchor semiconductor supply for edge processors, with sensor components drawing from Japanese precision manufacturers. Single-source vulnerability concentrates in Taiwan foundry capacity for industrial-grade GPUs, exposing deployment timelines to geopolitical friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operational intelligence procurement is shifting toward premium specifications as China's MEE dual carbon enforcement mandates real-time energy monitoring with sub-second latency requirements that economy-tier platforms cannot satisfy.
For Market Incumbents: Anticipate margin compression from pure-play analytics vendors by deepening backward integration into edge hardware design and securing exclusive distribution partnerships with China's MIIT-certified cloud operators. Certify platforms under Japan's METI cybersecurity framework before competitor qualification cycles complete. For New Entrants and Emerging Players: Capture white-space opportunity in Indonesia's nickel processing corridor where Sulawesi and Halmahera refineries lack legacy SCADA integration burdens. Target Vietnam's Bac Ninh supplier parks with asset-as-a-service contracting models that eliminate capex barriers for Samsung and Foxconn ecosystem manufacturers. For Investors and Strategic Acquirers: Consolidation pressure builds where OT cybersecurity talent scarcity extends implementation timelines beyond customer tolerance. Long-term viability favors platforms with hybrid architecture capabilities spanning edge processing and sovereign cloud compliance. Monitor divergence between China's GB data localization mandates and cross-border SaaS expansion attempts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | IT-OT convergence platforms address METI cybersecurity requirements for Japanese critical infrastructure operators. |
| Strategic Partnership | Legacy SCADA protocol partnerships unlock brownfield deployment opportunities in China's rust belt provinces. |
| Geographic Expansion | Indonesia nickel corridor presence captures first-mover advantage in battery material refining digitization. |
| Acquisition of Specialist Firm | Edge hardware designers add sovereign cloud compliance capabilities for India's MeitY localization mandates. |
| Product Launch | IEC 62443-compliant modules penetrate Japan's petroleum refinery segmentation requirements. |
Study Parameters
Coverage spans China, Japan, India, South Korea, and Southeast Asian manufacturing corridors, with primary inputs from each market cluster. Plant engineers and OT cybersecurity specialists at heavy industry facilities provided operational requirements data, while IT procurement officers at telecommunications operators detailed network slicing integration priorities. Platform vendor product managers and systems integrators contributed deployment timeline and pricing intelligence. Secondary validation drew from MIIT cloud migration directives, METI cybersecurity framework documentation, BIS interoperability standards, and customs data on edge hardware imports. Bottom-up installation counts triangulated against top-down industrial automation spending estimates.
Granularity-level modeling addressed deployment architecture splits between edge, cloud, and hybrid instances; application type differentiation across predictive maintenance, supply chain optimization, and workforce management; and end-user vertical concentration in manufacturing versus telecommunications. CAGRs were derived from segment-level growth rate assumptions calibrated to regulatory enforcement timelines and cloud migration mandates. Forecast inputs incorporated foundry capacity constraints for industrial GPUs and certification cycle durations for pharmaceutical manufacturing platforms.
Underlying measurement precision varies by segment; cloud-based deployment forecasts carry tighter precision than on-premise projections due to vendor disclosure practices. Forecasts reflect assumptions regarding sustained MIIT and MeitY enforcement intensity, stable foundry capacity allocation to industrial semiconductors, and continued FDI inflow to Vietnam manufacturing parks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Marketing Mix Optimization Market
Analytics
Retail Analytics Market
Analytics
Data Wrangling Market
Analytics
China Contact Center Analytics Market
Analytics
Behavior Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Speech Analytics Market
Analytics
Online Analytical Processing Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Manufacturing Analytics Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Connected Device Analytics Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Advanced Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market