
 Asia-Pacific Mobile Analytics Market | 2026-2036
Asia-Pacific Mobile Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mobile Analytics Market Insights
Serverless compute infrastructure is decoupling mobile analytics from fixed-capacity data centers, collapsing per-query costs for high-velocity event streams. Google LLC leverages its Tensor Processing Unit roadmap to anchor inference workloads inside Android's edge ecosystem. Microsoft Corporation sustains hybrid differentiation through Azure Arc's on-premise-to-cloud synchronization for regulated Asian banks. TalkingData competes on deterministic device-graph accuracy across China's fragmented Android OEM landscape.
Asia-Pacific mobile analytics encompasses the collection, processing, and visualization of user interaction data from smartphones and tablets, typically ingesting 10,000-50,000 events per session through SDK-integrated pipelines that normalize iOS and Android telemetry into unified schemas. The technology serves commercial purposes spanning attribution modeling, churn prediction, and real-time personalization across e-commerce and financial services applications. Cloud-based deployment now leads volume adoption as telcos in Indonesia and Vietnam migrate from legacy on-premise clusters to managed Kubernetes environments. Marketing analytics commands the widest enterprise penetration, though predictive analytics segments show the steepest trajectory as BFSI institutions in Singapore and Hong Kong deploy gradient-boosted models for credit-risk scoring from mobile behavioral signals.
India's Digital Personal Data Protection Act and Australia's Privacy Act, enforced by the Office of the Australian Information Commissioner, reshape product architecture by mandating granular consent logging and data-localization provisions that inflate compliance costs for cross-border analytics vendors. Japan's Act on Protection of Personal Information, administered by the Personal Information Protection Commission, imposes additional constraints on pseudonymous identifier linking that limit cross-device tracking fidelity. Stakeholders must decide whether to absorb localization infrastructure costs or cede ground to domestic champions with native compliance architectures.
Market Dynamics
Serverless compute infrastructure is collapsing per-query costs for high-velocity event streams, decoupling mobile analytics from fixed-capacity data centers and forcing vendors to re-architect pricing models around consumption rather than provisioned capacity.
Growth Catalysts
- India's Digital Personal Data Protection Act:Mandates granular consent logging and data-localization provisions that create demand for compliant analytics infrastructure among domestic SaaS providers.
- Real-time behavioral tracking:Southeast Asian retailers deploy SDK-integrated pipelines to optimize conversion funnels, driving enterprise adoption of streaming analytics platforms.
- Gradient-boosted models:BFSI institutions in Singapore and Hong Kong deploy predictive analytics for credit-risk scoring from mobile behavioral signals, expanding addressable use cases.
Market Restraints
- Compliance cost inflation:Cross-border analytics vendors face inflated infrastructure costs from Australia's Privacy Act enforcement by the Office of the Australian Information Commissioner.
- Pseudonymous identifier limits:Japan's Act on Protection of Personal Information constrains cross-device tracking fidelity, degrading attribution accuracy for multi-touch campaigns.
- Fragmented Android OEM landscape:China's device ecosystem requires deterministic device-graph investments that strain smaller analytics providers.
Strategic Opportunities
- Vietnam and Indonesia telco migration:Legacy on-premise clusters shift to managed Kubernetes environments, opening cloud-native deployment contracts.
- Edge inference workloads:Tensor Processing Unit integration with Android ecosystems enables on-device model execution, reducing latency for real-time personalization.
- Hybrid synchronization:Regulated Asian banks seek on-premise-to-cloud pipelines for sensitive transaction data, creating demand for compliant middleware.
Industry Challenges
- Consent pipeline re-architecture:Platforms must rebuild data ingestion flows to satisfy granular opt-in requirements across multiple jurisdictions.
- Schema normalization complexity:iOS and Android telemetry require unified processing pipelines that accommodate diverging privacy frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mobile Analytics Market |
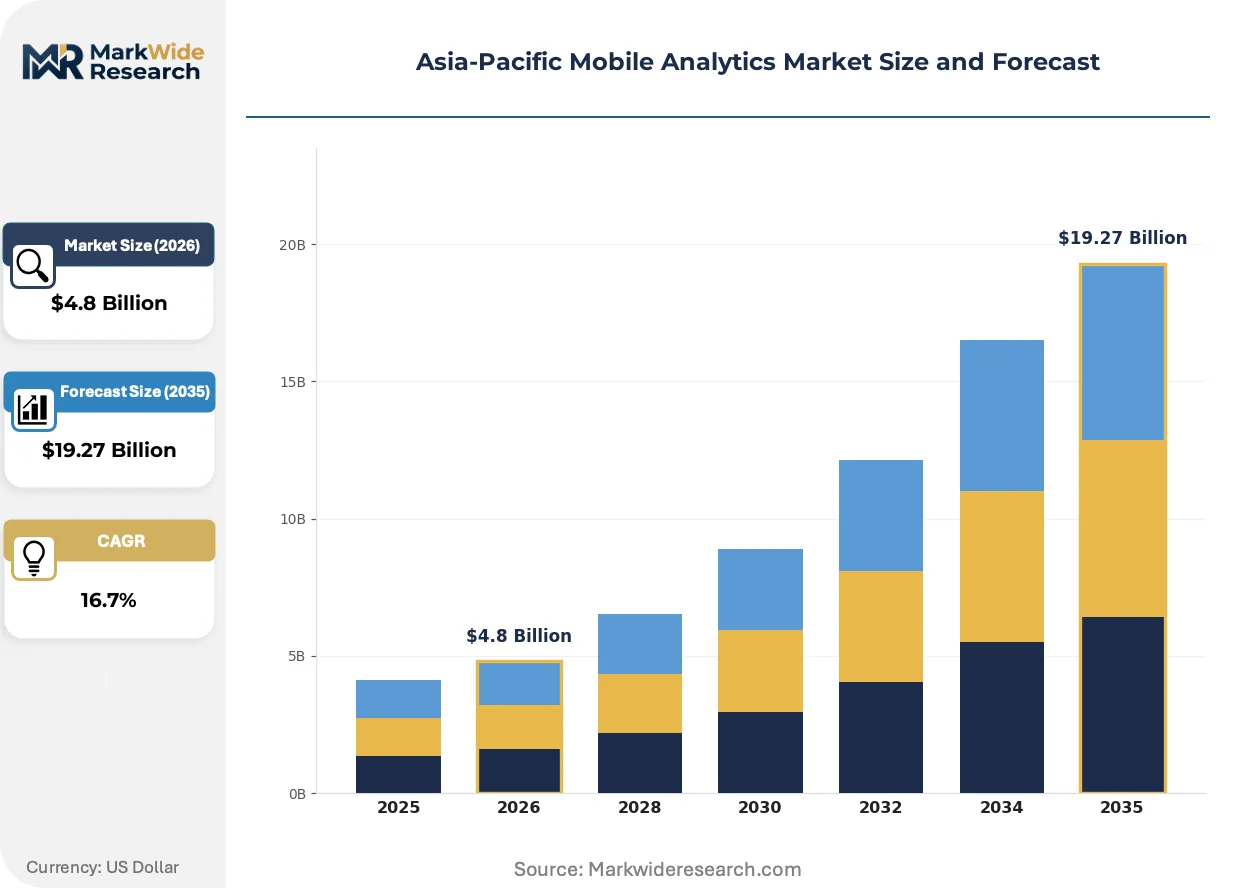
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Retail, BFSI, Healthcare, Telecommunications Application Type: Marketing Analytics, In-App Analytics, Customer Experience, Predictive Analytics Solution Type: Reporting Tools, Data Visualization, Dashboard Solutions, Integration Services |
| Companies Covered | Google LLC, Microsoft Corporation, IBM Corporation, Oracle Corporation, Adobe Inc., SAP SE, Kochava Inc., TalkingData, CleverTap, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mobile Analytics Market Trends and Innovations
Edge-native inference and privacy-preserving computation are restructuring how behavioral data flows from device to decision layer, compressing the latency window for real-time personalization while fragmenting vendor control over the data pipeline.
On-device machine learning is overtaking cloud-centric model serving as the dominant architecture for latency-sensitive mobile analytics. E-commerce applications in Southeast Asia deploy TensorFlow Lite runtimes to score user intent within 50 milliseconds of gesture completion. This shift is overtaking traditional batch-oriented analytics contracts and forcing vendors to license edge-optimized model compression IP.
Australia's Privacy Act amendments, enforced by the Office of the Australian Information Commissioner, mandate purpose limitation and data minimization for cross-border transfers. Financial services institutions must now maintain segregated data environments with audit-ready lineage documentation. Mobile banking providers in Sydney and Melbourne are responding by localizing inference workloads to domestic cloud regions.
Buyer procurement for mobile analytics is consolidating around outcome-based engagement models rather than per-seat licensing. Enterprise procurement teams in India's SaaS corridor negotiate contracts tied to measurable conversion lift or churn reduction. This pattern is most visible among Series C-stage fintechs in Bangalore and Mumbai that lack capital for upfront platform commitments.
Asia-Pacific Mobile Analytics Market Segmentation
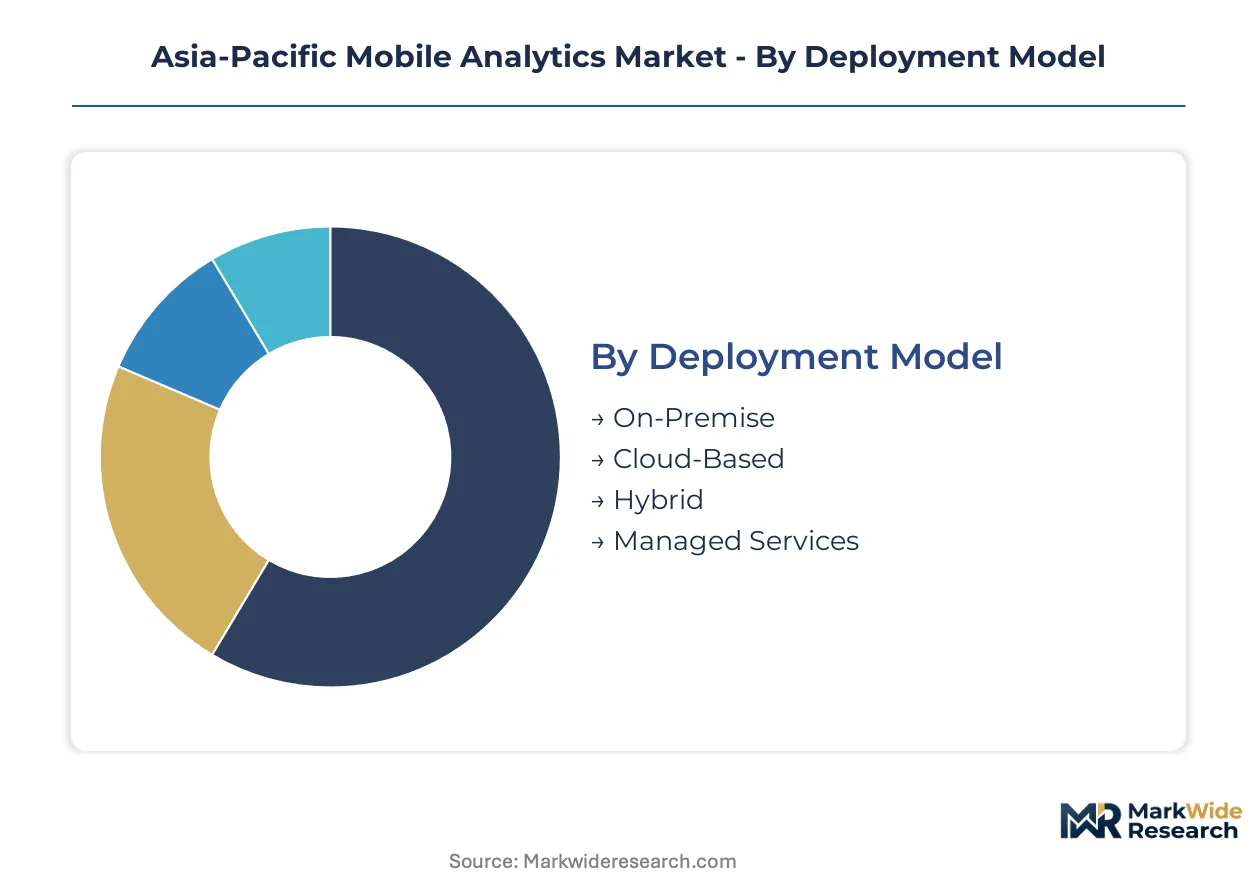
Asia-Pacific mobile analytics vendors structure offerings around deployment flexibility and regulatory compliance. Segmentation reveals where infrastructure investments concentrate and which application layers command premium pricing.
Deployment Model:
Upgrade cycles from legacy on-premise clusters to elastic infrastructure are compressing from five-year refresh windows to continuous migration patterns.
- Cloud-Based:Managed Kubernetes environments ingest 10,000-50,000 events per session through auto-scaling pipelines. Telcos in Indonesia and Vietnam favor consumption-based pricing over provisioned capacity.
- Hybrid:On-premise-to-cloud synchronization serves regulated Asian banks requiring domestic data residency with burst capacity abroad. Azure Arc and comparable middleware anchor these deployments.
- On-Premise:Fixed-capacity data centers persist among Japanese enterprises constrained by Act on Protection of Personal Information localization mandates.
- Managed Services:Third-party operators handle consent pipeline re-architecture and schema normalization for mid-market SaaS providers lacking in-house data engineering.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
End User:
Customer sophistication tiers separate high-velocity event processing demand from compliance-heavy transactional monitoring requirements.
- BFSI:Gradient-boosted models score credit risk from mobile behavioral signals. Singapore and Hong Kong institutions deploy predictive analytics for real-time fraud detection.
- Retail:Southeast Asian e-commerce platforms optimize conversion funnels through real-time behavioral tracking. SDK-integrated pipelines reduce cart abandonment latency.
- Telecommunications:Indonesian and Vietnamese carriers migrate subscriber analytics from legacy clusters to serverless architectures, collapsing per-query costs.
- Healthcare:Patient engagement apps in Australia navigate Privacy Act purpose-limitation rules through segregated data environments with audit-ready lineage.
Revenue concentration sits with BFSI; Retail claims the steepest expansion trajectory.
Application Type:
Functional maturity curves separate established attribution modeling from emerging edge-native inference workloads.
- Predictive Analytics:Machine learning pipelines forecast churn and lifetime value from telemetry patterns. Edge-optimized model compression IP differentiates vendor offerings.
- Marketing Analytics:Attribution modeling and campaign optimization command widest enterprise penetration. Cross-device tracking fidelity degrades under Japan's pseudonymous identifier constraints.
- In-App Analytics:Real-time gesture scoring through TensorFlow Lite runtimes enables sub-50-millisecond personalization decisions.
- Customer Experience:Journey mapping and sentiment analysis integrate voice-of-customer data with interaction telemetry.
Marketing Analytics holds installed base dominance; Predictive Analytics is expanding most quickly.
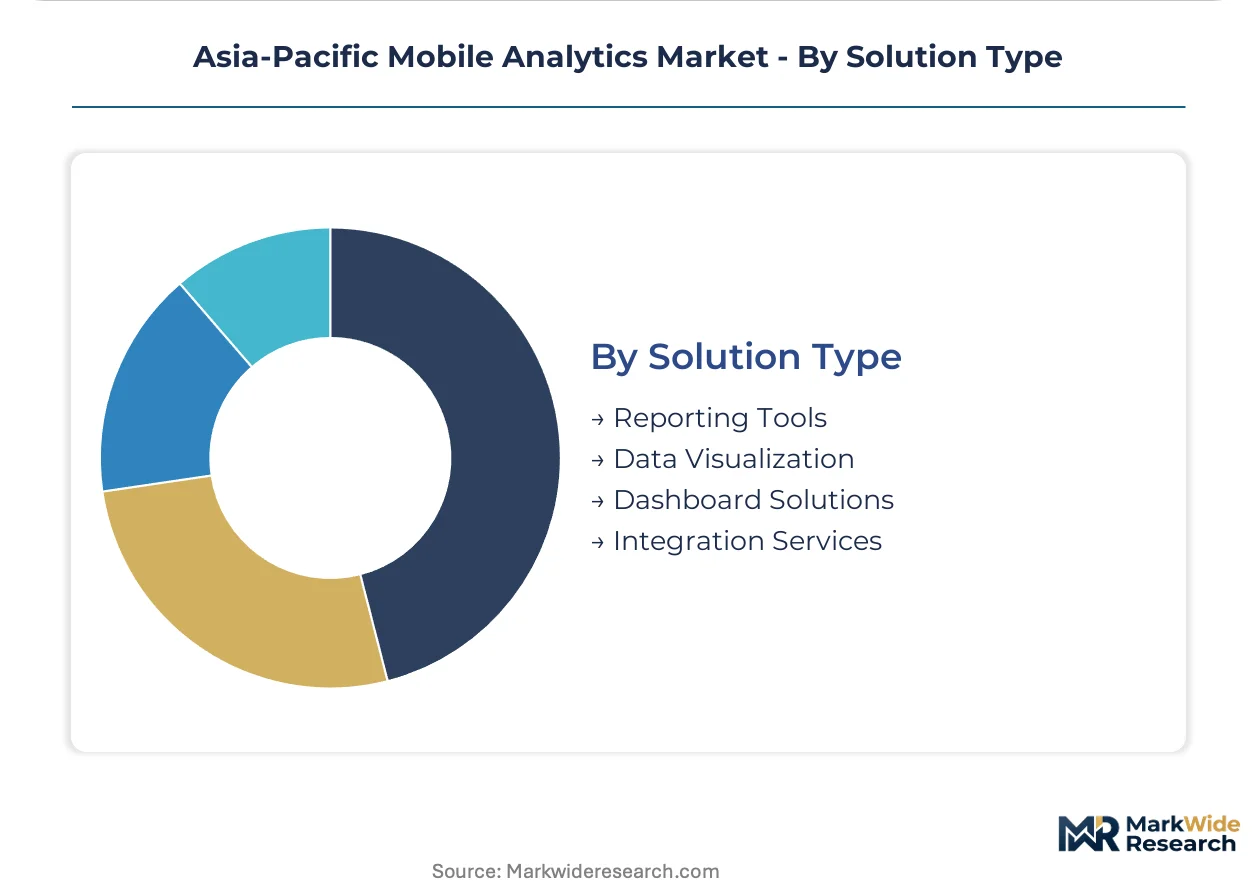
Solution Type:
Margin structures favor integrated platforms over point-tool procurement as buyers consolidate vendor relationships.
- Dashboard Solutions:Unified visualization layers normalize iOS and Android telemetry into coherent executive views. Self-service configuration reduces IT dependency.
- Data Visualization:Custom charting and exploratory analysis tools serve data science teams in India's enterprise SaaS corridor.
- Reporting Tools:Scheduled and ad-hoc report generation remains table stakes for compliance documentation.
- Integration Services:API middleware and ETL pipelines connect mobile analytics to CRM, ERP, and data warehouse investments.
Dashboard Solutions anchor average contract value; Integration Services gain share fastest through outcome-based engagement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise demand concentrates in India's SaaS corridor and Australia's privacy-compliant analytics stack, while Southeast Asian retailers drive real-time behavioral tracking adoption. Telcos in Indonesia and Vietnam anchor cloud migration volumes. BFSI institutions in Singapore and Hong Kong deploy predictive models for credit-risk scoring.
India
Domestic SaaS providers re-architect consent pipelines to satisfy the Digital Personal Data Protection Act's localization mandates. The TRAI framework governs telecom subscriber data handling. Bangalore and Mumbai host Series C-stage fintechs negotiating outcome-based analytics contracts tied to churn reduction metrics.
Australia
Financial services institutions localize inference workloads to domestic cloud regions under Privacy Act amendments. The Office of the Australian Information Commissioner enforces purpose limitation and data minimization rules. Sydney and Melbourne mobile banking providers maintain segregated data environments with audit-ready lineage documentation.
Singapore
BFSI institutions deploy gradient-boosted models for real-time fraud detection from mobile behavioral signals. The Monetary Authority of Singapore supervises data governance for cross-border financial flows. The city-state's banking cluster drives premium pricing for predictive analytics infrastructure.
Indonesia
Telcos migrate subscriber analytics from legacy on-premise clusters to serverless Kubernetes environments. The country's national data protection authority implements localization requirements for consumer telecommunications data. Jakarta-based carriers favor consumption-based pricing over provisioned capacity arrangements.
Vietnam
Telecommunications operators collapse per-query costs through managed cloud-native deployments. The Ministry of Information and Communications regulates data residency for mobile network operators. Ho Chi Minh City anchors enterprise adoption of streaming analytics platforms for subscriber monetization.
Asia-Pacific Mobile Analytics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers commanding infrastructure layers while regional specialists capture compliance-heavy application tiers. The vendor base concentrates around three strategic archetypes: edge-native inference specialists, hybrid synchronization middleware providers, and deterministic device-graph accuracy vendors. Capacity expansion and technology licensing dominate competitive moves as players localize infrastructure to satisfy data residency mandates.
Within the hyperscale infrastructure tier, Google LLC and Microsoft Corporation anchor platform offerings through Tensor Processing Unit integration and Azure Arc synchronization capabilities. TalkingData occupies a position among device-graph specialists addressing China's fragmented Android OEM landscape. These three exemplify the geographic and functional segmentation shaping procurement decisions across the region.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Adobe Inc. |
| SAP SE |
| Kochava Inc. |
| TalkingData |
| CleverTap |
| Others |
Pricing and Supply Chain Analysis
Outcome-based procurement contracts from India's Series C-stage fintechs are collapsing upfront platform commitments and forcing vendors to absorb localization infrastructure costs for data residency compliance, which compresses margins and accelerates tiered pricing stratification across consumption bands.
Pricing Analysis
Volume placements concentrate in consumption-based cloud tiers while premium margins attach to hybrid synchronization middleware. Three-tier pricing structure across premium, standard, and economy levels separates dedicated Kubernetes environments from shared serverless pools and basic dashboard solutions. Cost compression in the standard tier intensifies as Indonesian and Vietnamese telcos negotiate auto-scaling commitments. Series C-stage buyers in Bangalore and Mumbai exhibit highest price sensitivity; Singapore's BFSI institutions show lowest sensitivity given regulatory premium requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for Tensor Processing Unit-integrated inference workloads, while managed service providers intermediate mid-market SaaS procurement. Infrastructure supply concentrates in Singapore, India, and Australia as data residency mandates harden. Component dependencies span edge-optimized model compression IP, consent pipeline middleware, and deterministic device-graph algorithms. Single-source vulnerability runs through Google's Android ecosystem dominance for on-device inference. Distribution runs through hyperscaler marketplaces and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance-ready infrastructure capacity is supply-constrained across the region, with data localization mandates propping pricing power for vendors bearing domestic cloud region investments.
For Market Incumbents: Deploy edge-native inference specialization to defend against hyperscaler platform bundling. Deepen backward integration into consent pipeline middleware to capture re-architecture spend from India's Digital Personal Data Protection Act compliance cycles. Anchor capacity in Australia's domestic cloud regions to satisfy Privacy Act amendments. For New Entrants and Emerging Players: Enter via Vietnam and Indonesia telco migration white space, where legacy on-premise cluster displacement outpaces incumbent cloud-native deployment capacity. Target managed services tier for mid-market SaaS providers lacking in-house data engineering. Lead with outcome-based pricing tied to measurable churn reduction metrics. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid synchronization middleware specialists given Monetary Authority of Singapore cross-border data governance tightening. Long-term viability favors vendors with native compliance architectures across India's TRAI framework and Japan's Personal Information Protection Commission constraints. Monitor gradient-boosted model deployment velocity in Singapore and Hong Kong BFSI as inflection signal for predictive analytics segment premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Inference Platform Launch | TensorFlow Lite runtime deployment captures sub-50-millisecond personalization demand from Southeast Asian e-commerce. |
| Domestic Cloud Region Expansion | Australian Privacy Act compliance requires localized inference workloads with audit-ready lineage documentation. |
| Consent Pipeline Middleware Acquisition | India's Digital Personal Data Protection Act mandates granular opt-in architecture rebuilds across domestic SaaS providers. |
| Deterministic Device-Graph Partnership | China's fragmented Android OEM landscape requires specialized accuracy investments beyond standard probabilistic matching. |
| Outcome-Based Pricing Model Rollout | Bangalore and Mumbai fintechs negotiate contracts tied to measurable conversion lift rather than per-seat licensing. |
Research Methodology
Independent corroboration across primary interviews with platform engineering directors, IT procurement officers at Indonesian telcos, data protection compliance leads, and mobile banking CTOs, plus secondary validation through SEC filings from hyperscaler cloud providers, App Annie telemetry benchmarks, and TRAI regulatory disclosures, underwrites the qualitative findings. Bottom-up deployment model sizing triangulates against top-down enterprise SaaS spend estimates across the analysis window.
Rate-of-change decomposition separates cloud-based volume expansion from hybrid infrastructure acceleration and on-premise fixed-capacity erosion. Segmentation dimensions span deployment model, end-user vertical, application type maturity, and regional regulatory cluster. CAGRs derive from fitted adoption curves applied to event-stream velocity benchmarks and consent pipeline re-architecture spend patterns. Edge inference workload density and gradient-boosted model deployment rates inform predictive analytics trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt data localization mandate expansion or pseudonymous identifier constraint tightening. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Mining Tools Market
Analytics
Complex Event Processing Market
Analytics
UAE Geospatial Analytics Market
Analytics
Behavior Analytics Market
Analytics
Service Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Assortment Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Iraq ICT Market
Analytics
Voice Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Europe Location Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
India Big Data Technology and Service Market