
 Asia-Pacific and Middle-East Inflight Catering Market | 2026-2036
Asia-Pacific and Middle-East Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific and Middle-East Inflight Catering Market Outlook
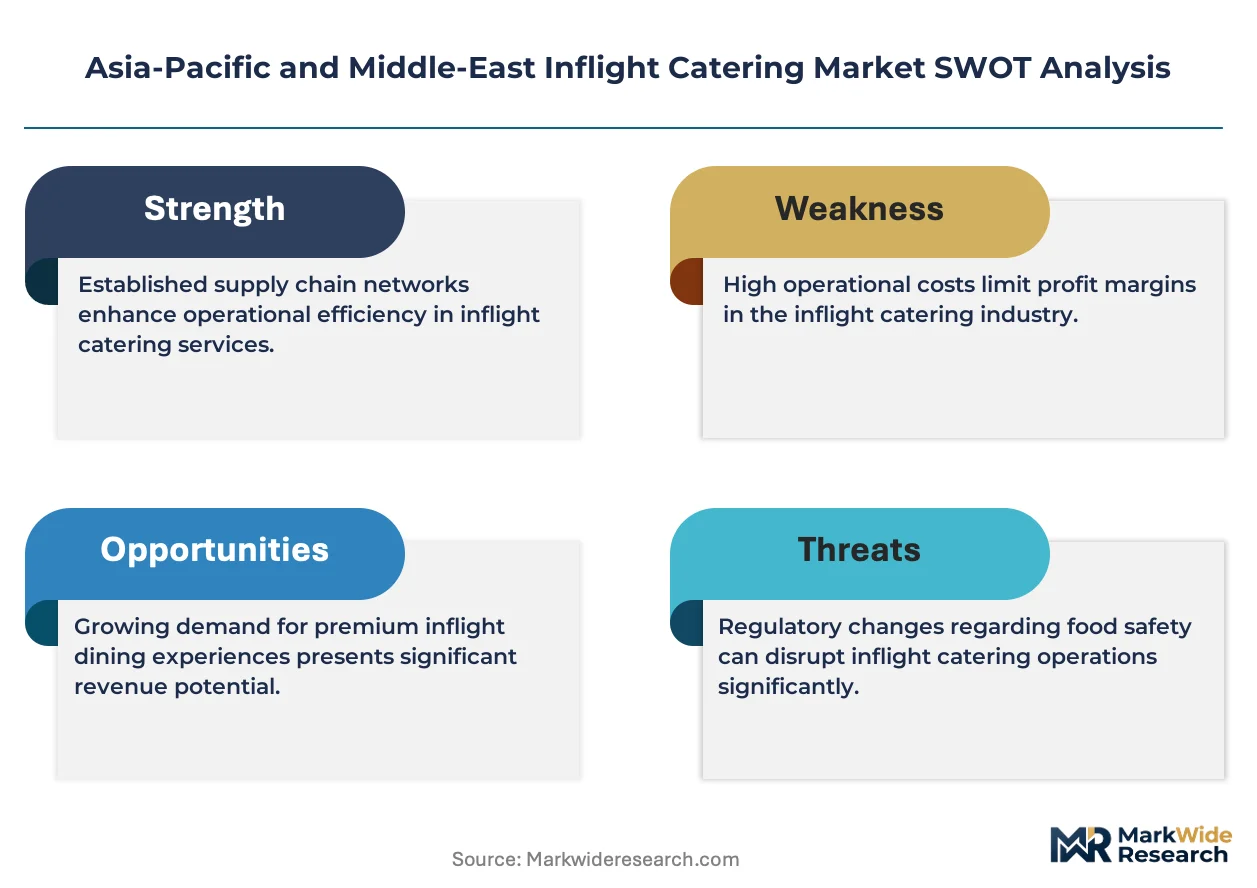
Plant-based protein formulations are broadening menu economics for premium cabin service. Gategroup leverages centralized commissary networks across Singapore and Hong Kong to sustain cold-chain reliability. Emirates Flight Catering anchors high-volume production through its Dubai-based mega-facility, while dnata Catering differentiates via specialized halal certification workflows across the Gulf Cooperation Council.
Asia-Pacific and Middle-East inflight catering encompasses the preparation, assembly, and logistics of ready-to-serve meals and beverages consumed aboard commercial aircraft, with strict adherence to HACCP protocols and altitude-adjusted seasoning profiles to compensate for diminished taste perception at cruising altitude. Meal Service generates the dominant revenue share due to long-haul route density, while Special Meals command premium positioning as dietary segmentation intensifies among business travelers. Eco-Friendly packaging represents the fastest-expanding segment within packaging type as regulatory deadlines for single-use plastics approach across multiple jurisdictions.
The General Administration of Customs China enforces import quarantine rules on all inbound catering supplies, while EASA-equivalent standards under GCAA UAE jurisdiction mandate real-time temperature logging across ground-to-air handoffs. India's FSSAI recently tightened additive disclosure requirements for international carriers operating through Delhi and Mumbai. Stakeholders must decide whether to build captive halal kitchens or outsource certification-dependent production as route networks expand into secondary Middle Eastern cities.
Market Dynamics
Full-service carriers across Southeast Asia are expanding premium cabin dining programs while the EU Green Deal's extraterritorial packaging standards pressure suppliers to adopt compostable meal containers. This dual pressure from demand upgrading and regulatory compliance is restructuring procurement priorities across the region.
Growth Catalysts
- Long-haul route density:Dubai International Airport anchors high-volume catering procurement for connecting traffic between Europe and Asia-Pacific. Mega-facility investments scale production capacity to match this traffic concentration.
- EU Green Deal packaging mandates:Extraterritorial standards on single-use plastics accelerate adoption of compostable meal containers across Gulf Cooperation Council suppliers. Regulatory alignment opens access to European carrier contracts.
- Halal certification workflows:Specialized halal kitchen infrastructure expands as route networks penetrate secondary Middle Eastern cities. Certification-dependent production creates service differentiation for Gulf-based caterers.
Market Restraints
- Perishables input volatility:Fresh protein and produce costs fluctuate with climate-driven supply disruptions across Australia and New Zealand sourcing regions. Cold-chain integrity requirements prevent substitution with frozen alternatives.
- Supply concentration in UAE:Emirates Flight Catering and dnata Catering dominate high-volume production capacity in Dubai. Secondary city expansion requires duplicative infrastructure investment or extended logistics legs.
- Altitude-adjusted formulation limits:Diminished taste perception at cruising altitude constrains menu complexity and premium positioning potential. Culinary innovation hits physiological boundaries regardless of ingredient cost.
Strategic Opportunities
- India secondary hubs:Delhi and Mumbai international traffic growth outstrips current catering infrastructure. FSSAI additive disclosure tightening creates first-mover advantage for compliant suppliers.
- Plant-based protein convergence:Menu economics broaden as alt-protein formulations meet halal certification requirements and altitude-adjusted seasoning protocols simultaneously.
- Centralized commissary networks:Singapore and Hong Kong cold-chain reliability investments enable regional hub-and-spoke distribution models for Southeast Asian carriers.
Industry Challenges
- HACCP protocol integration:Real-time temperature logging mandates under GCAA UAE jurisdiction require ground-to-air handoff system upgrades. Legacy tracking infrastructure gaps create compliance exposure.
- Quarantine clearance timelines:General Administration of Customs China import rules extend inbound supply lead times. Buffer inventory requirements strain working capital for China-route operators.
- Halal kitchen capex intensity:Captive certification-dependent production facilities demand specialized equipment and segregated workflows. Build-versus-outsource decisions lock in long-term cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific and Middle-East Inflight Catering Market |
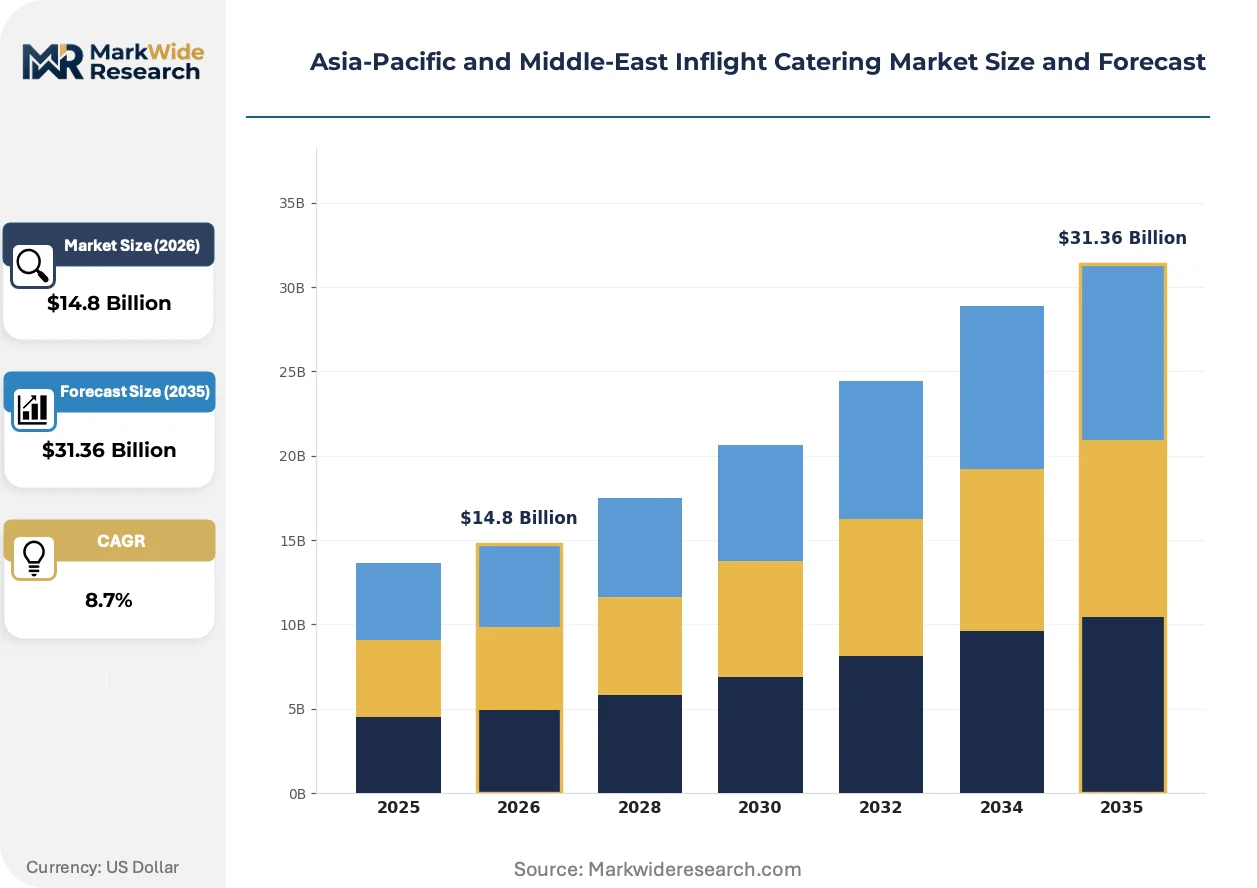
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Service, Snack Service, Beverage Service, Special Meals Customer Type: Airlines, Private Jets, Charter Services, Cargo Airlines Meal Type: Vegetarian, Non-Vegetarian, Vegan, Gluten-Free Packaging Type: Disposable, Reusable, Eco-Friendly, Traditional Containers |
| Companies Covered | Gategroup, Emirates Flight Catering, SATS Ltd., LSG Sky Chefs, Cathay Pacific Catering Services, dnata Catering, DO & CO, Newrest, Air India SATS, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific and Middle-East Inflight Catering Market Strategic Shifts
Compostable packaging materials and real-time cold-chain monitoring systems are restructuring production workflows. Regulatory deadlines for plastic elimination converge with carrier sustainability commitments to accelerate capital deployment.
Polylactic acid and molded fiber meal containers are overtaking conventional plastic across premium cabin service programs. Singapore Airlines and Cathay Pacific cabin procurement teams specify compostable materials for new route launches. This material transition is compressing supplier margins until scale economies emerge in regional manufacturing.
The EU Green Deal's extraterritorial packaging standards impose compliance obligations on Dubai-based suppliers serving European carriers. Industrial consequence includes accelerated R&D spending on biodegradable laminates that maintain moisture barriers during extended holding periods. Gulf Cooperation Council caterers most affected are consolidating procurement volumes to qualify for container manufacturer minimum order quantities.
Airline sustainability reporting requirements now extend to Scope 3 emissions from catering suppliers. Full-service carriers in Southeast Asia are embedding carbon disclosure clauses into multi-year catering contracts. This procurement pattern shift is most visible in Singapore and Hong Kong, where listed carriers face CSRD-aligned investor pressure for supply chain transparency.
Asia-Pacific and Middle-East Inflight Catering Market Segmentation
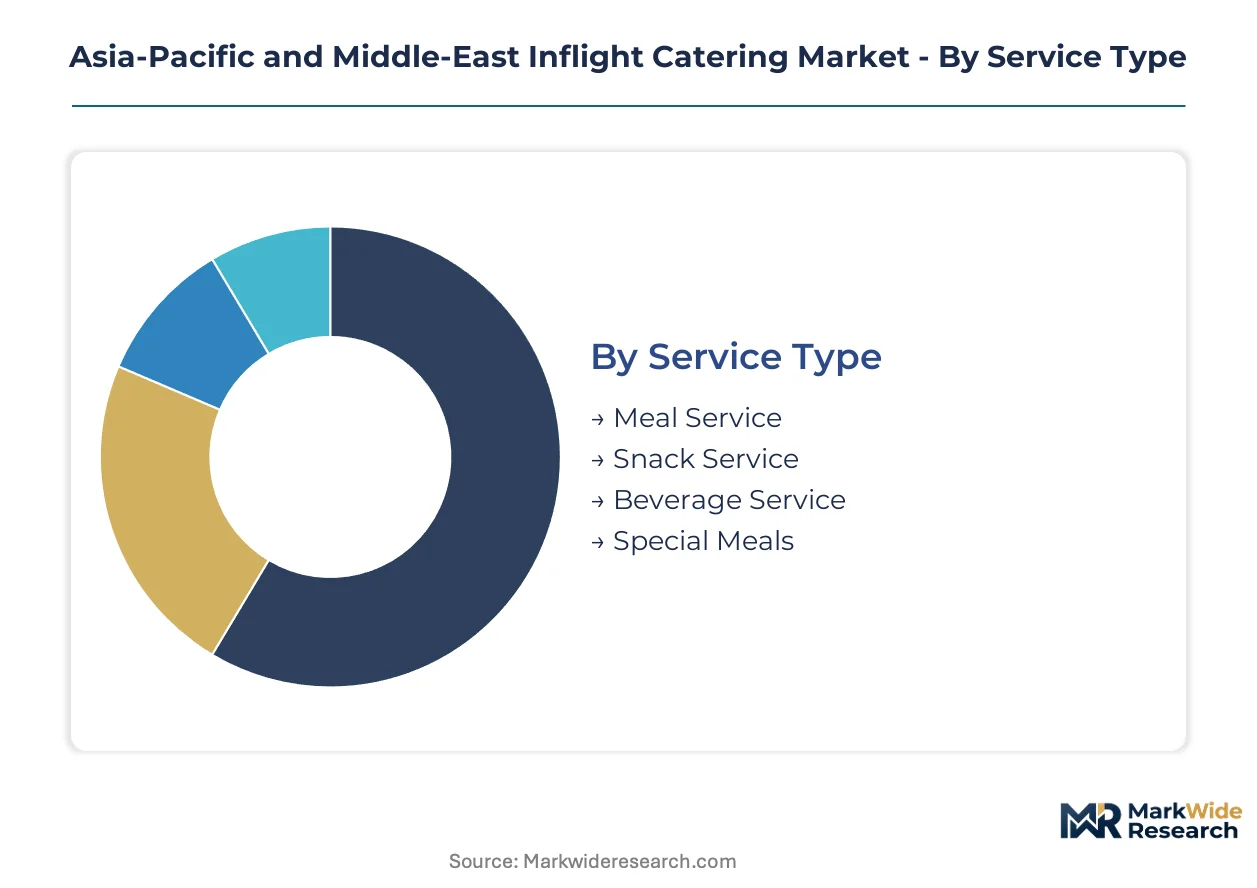
Segmentation in Asia-Pacific and Middle-East inflight catering reveals how certification burdens, route economics, and passenger demographics allocate procurement budgets across service tiers. Each dimension carries distinct regulatory and operational requirements that shape supplier capabilities and carrier contracting strategies.
Service Type:
Halal certification workflows under GCAA UAE jurisdiction apply differentially across service tiers, with hot meal production demanding the most rigorous segregation protocols and real-time temperature logging.
- Meal Service:Full tray sets with hot entrees, salads, and bread rolls dominate long-haul procurement from Dubai International Airport. Emirates Flight Catering's mega-facility scales this segment through centralized production lines serving connecting traffic between Europe and Asia-Pacific.
- Special Meals:Medical, religious, and lifestyle dietary specifications command premium positioning as business traveler segmentation intensifies. FSSAI additive disclosure requirements for India-route carriers add compliance layers to therapeutic meal formulations.
- Beverage Service:Altitude-adjusted wine selection and specialty coffee programs support premium cabin differentiation for Singapore Airlines and Cathay Pacific.
- Snack Service:Mid-flight retail and short-haul rotations favor shelf-stable packaging with extended holding periods.
Meal Service sits at the top of the volume ranking, with Special Meals climbing the fastest.
Customer Type:
Procurement scale and contract duration separate the customer tiers, with scheduled carriers locking in multi-year agreements while ad-hoc charter demand fluctuates with seasonal pilgrimage and corporate travel patterns.
- Airlines:Full-service and low-cost carriers generate baseline demand through hub-and-spoke networks centered on Dubai, Singapore, and Hong Kong. Sustainability reporting requirements now embed Scope 3 carbon disclosure clauses into catering contracts for listed Southeast Asian operators.
- Private Jets:Ultra-high-net-worth travelers demand bespoke menu development with 24-hour turnaround flexibility from fixed-base operators.
- Cargo Airlines:Flight deck crew provisioning follows simplified HACCP protocols without passenger-facing presentation requirements.
- Charter Services:Hajj and Umrah traffic from secondary Middle Eastern cities drives seasonal spikes in halal-certified volume.
Airlines anchor procurement volumes, while Private Jets deliver the steepest margin expansion trajectory.
Meal Type:
Plant-based protein convergence is restructuring menu development, with alt-protein formulations now meeting both halal certification requirements and altitude-adjusted seasoning protocols simultaneously.
- Vegetarian:Lacto-ovo preparations remain standard across Indian subcontinent routes, with paneer and dairy-based proteins dominating FSSAI-compliant formulations for Delhi and Mumbai operations.
- Non-Vegetarian:Poultry and lamb proteins sourced from Australia and New Zealand supply premium cabin programs, though perishables input volatility from climate-driven disruptions strains cold-chain integrity.
- Vegan:Elimination of all animal derivatives requires segregated preparation workflows and specialized supplier audits.
- Gluten-Free:Celiac-safe certification adds traceability requirements to grain and starch sourcing.
Non-Vegetarian retains volume leadership, with Vegan options gaining share fastest among business traveler segments.
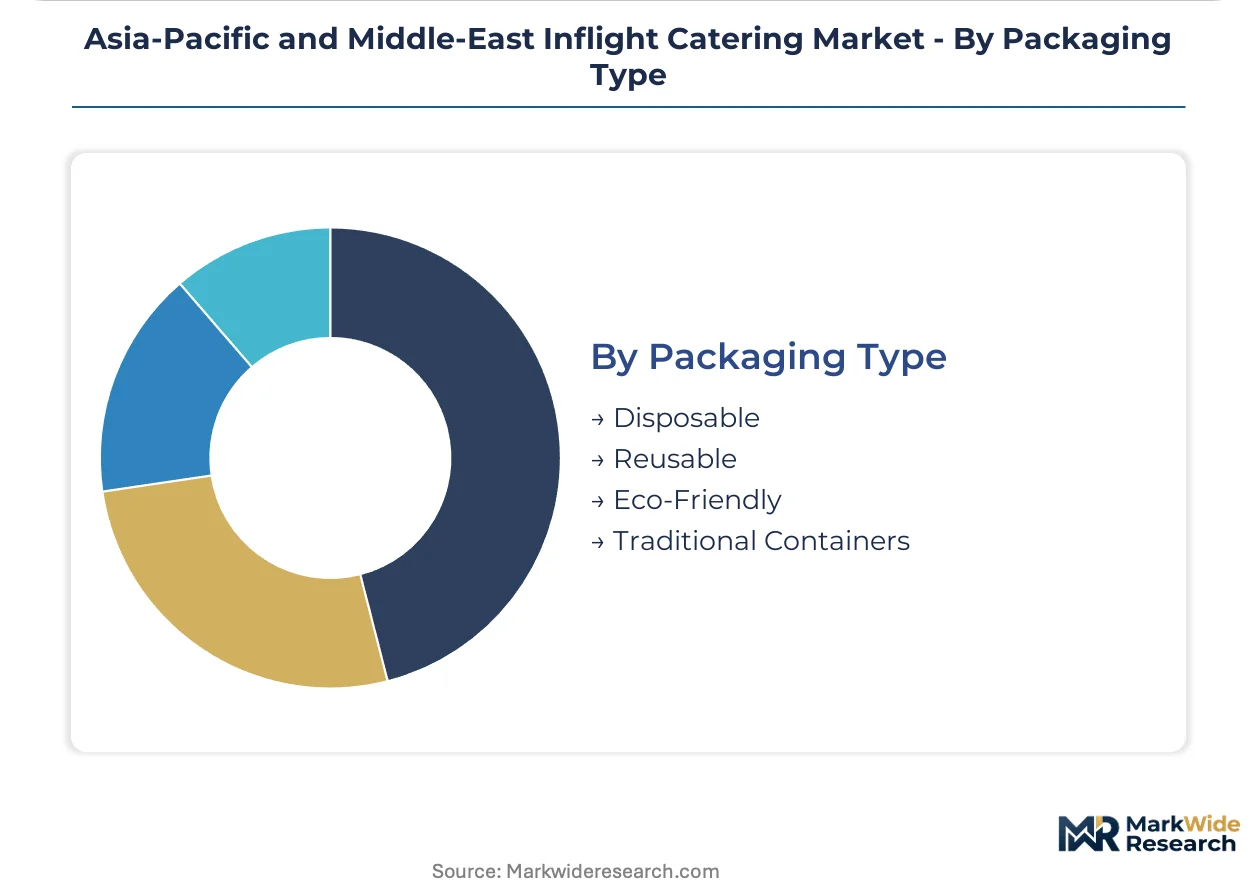
Packaging Type:
EU Green Deal extraterritorial standards are forcing material transitions across Gulf Cooperation Council suppliers, with compostable laminates now mandatory for European carrier contracts regardless of production location.
- Eco-Friendly:Polylactic acid and molded fiber containers are overtaking conventional plastic across premium cabin service programs. Singapore Airlines and Cathay Pacific procurement teams specify compostable materials for new route launches, compressing supplier margins until regional manufacturing scale economies emerge.
- Disposable:Conventional plastic and aluminum foil combinations face regulatory elimination timelines across multiple jurisdictions.
- Reusable:Ceramic and metal serviceware persists in first-class cabins where weight penalties are offset by brand positioning value.
- Traditional Containers:Legacy plastic laminates with moisture barriers remain in use for long-haul holding periods where biodegradable alternatives underperform.
Eco-Friendly packaging is expanding most quickly, while Disposable retains residual volume in cost-sensitive short-haul operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Airport anchors procurement volumes for long-haul connecting traffic between Europe and Asia-Pacific, while secondary hubs across India and Southeast Asia expand capacity to capture shifting route networks.
United Arab Emirates
Dubai's mega-facility infrastructure processes high-volume catering for Emirates and connecting carriers under GCAA UAE jurisdiction. Real-time temperature logging mandates govern ground-to-air handoffs. The Dubai Airport Freezone clusters Emirates Flight Catering and dnata Catering operations serving Gulf Cooperation Council routes.
Singapore
Changi Airport's hub status drives premium cabin dining program investments from full-service carriers. The country's national food safety regulator enforces strict cold-chain protocols for inbound supplies. Gategroup operates centralized commissary networks enabling regional distribution across Southeast Asian markets.
India
Delhi and Mumbai international traffic growth outstrips existing catering infrastructure capacity. FSSAI additive disclosure requirements for international carriers operating through these hubs tighten compliance layers. Air India SATS anchors production at Indira Gandhi International Airport while secondary city expansion proceeds.
Hong Kong
Cathay Pacific's procurement specifications for compostable materials on new route launches compress supplier margins until manufacturing scale emerges. The city's environmental protection department aligns with EU Green Deal extraterritorial standards on single-use plastics. Cathay Pacific Catering Services maintains cold-chain reliability investments for regional hub-and-spoke distribution.
Saudi Arabia
Hajj and Umrah seasonal traffic from Jeddah and Medina drives spikes in halal-certified volume requirements. The Saudi Food and Drug Authority governs import quarantine rules on all inbound catering supplies. Specialized halal kitchen infrastructure expands as route networks penetrate secondary cities beyond Riyadh.
Asia-Pacific and Middle-East Inflight Catering Market Competitive Environment
Global majors compete with regional champions across certification-dependent production and cold-chain reliability dimensions. Market structure tilts toward consolidation around mega-facility operators with captive halal workflows and centralized commissary networks. Three archetypes dominate: Gulf-based halal specialists with mega-facility scale, Southeast Asian hub operators with regional distribution reach, and European-origin global caterers with sustainability compliance capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as carriers lock in multi-year contracts with Scope 3 disclosure clauses.
Within the Gulf-based halal specialist tier, Emirates Flight Catering and dnata Catering occupy positions defined by Dubai mega-facility scale and GCAA UAE certification workflows. Among Southeast Asian hub operators, Gategroup exemplifies the centralized commissary archetype through Singapore and Hong Kong cold-chain networks. SATS Ltd. represents the integrated airport services model spanning ground handling and catering operations.
| Leading Market Players |
|---|
| Gategroup |
| Emirates Flight Catering |
| SATS Ltd. |
| LSG Sky Chefs |
| Cathay Pacific Catering Services |
| dnata Catering |
| DO & CO |
| Newrest |
| Air India SATS |
| Others |
Value Chain & Pricing Dynamics
Perishables input volatility from Australia and New Zealand sourcing regions cascades through cold-chain logistics into three-tier pricing stratification across premium cabin, standard service, and economy meal programs. Fresh protein and produce costs fluctuate with climate-driven disruptions, compressing margins at the economy tier while premium segments absorb markups through brand positioning value.
Pricing Analysis
Input-cost pass-through from fresh protein and compostable packaging materials intensifies margin pressure across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates Emirates Flight Catering's mega-facility scale from regional commissary operators and ad-hoc charter providers. Price differentiation hinges on halal certification grade and volume commitment duration. Cost compression in economy short-haul rotations is intensifying because EU Green Deal packaging mandates force premature material transitions before scale economies emerge. Charter services and low-cost carriers exhibit highest price sensitivity; full-service carriers with Scope 3 disclosure obligations show lowest.
Supply Chain Analysis
Fresh poultry and lamb supply rests on Australian and New Zealand livestock producers, with polylactic acid container manufacturing drawing from Thailand and Malaysia biopolymer specialists. Cold-chain equipment and real-time temperature logging systems hinge on Japanese and South Korean sensor technology. Single-source vulnerability concentrates in Dubai mega-facility capacity for Gulf Cooperation Council routes. Distribution runs through hub-and-spoke commissary networks anchored at Changi Airport and Hong Kong International Airport, with secondary spokes reaching Southeast Asian secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where premium cabin dining program expansion and EU Green Deal compliance obligations favor suppliers with captive certification infrastructure and cold-chain reliability investments.
For Market Incumbents: Anticipate margin compression from compostable packaging scale requirements and defend position through backward integration into biopolymer container manufacturing or regional hub capacity consolidation. Threat vectors include emerging halal-certified entrants in Indian secondary cities and FSSAI disclosure tightening that advantages first-mover compliance investments. Priority levers center on GCAA UAE certification workflow deepening and Singapore-Hong Kong commissary network densification. For New Entrants and Emerging Players: Launch via specialized halal kitchen infrastructure serving secondary Middle Eastern cities beyond Dubai-Riyadh-Jeddah corridors where Emirates Flight Catering and dnata Catering concentration leaves service gaps. White-space targets include Delhi and Mumbai international traffic growth exceeding current catering infrastructure, and plant-based protein formulation contracts for premium cabin alt-protein convergence. Go-to-market angle emphasizes FSSAI additive disclosure compliance as competitive wedge against legacy operators. For Investors and Strategic Acquirers: Consolidation pressure builds where route network expansion into secondary cities requires duplicative halal certification infrastructure or extended logistics legs that strain standalone operator economics. Long-term viability over the projection horizon favors Gulf-based mega-facility operators with captive GCAA UAE workflows and Southeast Asian hub operators with regional distribution reach. Acquisition target archetype: mid-scale halal-certified caterers in India or Saudi Arabia with established airline relationships but suboptimal capacity utilization. Signal to watch: Emirates Flight Catering or dnata Catering vertical integration moves into biopolymer packaging manufacturing as margin defense.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Kitchen Infrastructure Expansion | Captive certification workflows under GCAA UAE jurisdiction lock in airline contract renewals for Gulf-based operators. |
| Compostable Packaging Manufacturing Integration | Backward control over polylactic acid container supply secures EU Green Deal compliance before regional scale economies emerge. |
| Centralized Commissary Network Densification | Singapore and Hong Kong cold-chain reliability investments enable Southeast Asian carrier hub-and-spoke distribution capture. |
| FSSAI Compliance-First Market Entry | Additive disclosure tightening at Delhi and Mumbai creates first-mover advantage for compliant suppliers against legacy operators. |
| Plant-Based Protein R&D Partnership | Alt-protein formulations meeting halal and altitude-adjusted protocols simultaneously broaden premium cabin menu economics. |
Study Parameters
Direct dialogue with catering procurement directors at full-service carriers, halal certification officers under GCAA UAE jurisdiction, cold-chain logistics managers at Dubai International Airport, and FSSAI regulatory affairs leads grounded qualitative findings. Secondary validation drew from airline sustainability reports, GCAA UAE regulatory filings, EU Green Deal packaging standard documents, and customs data on perishables imports through Australia and New Zealand. Bottom-up segmentation modeling triangulated against top-down route density and passenger traffic projections.
Market sizing and growth trajectories across the analysis window reflect disaggregated modeling of meal service volumes, special meals premium positioning, and eco-friendly packaging transition timelines. Segmentation dimensions included service type, customer tier, meal category, and packaging material grade alongside route-specific regulatory cluster assignments. CAGRs were derived from trend extrapolation of long-haul traffic density, EU packaging mandate compliance deadlines, and halal certification workflow expansion patterns. Industry-specific inputs incorporated altitude-adjusted formulation constraints and real-time temperature logging infrastructure deployment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Green Deal enforcement acceleration or climate-driven perishables supply disruptions across Australian and New Zealand sourcing regions. Assumptions reflect documented regulatory timelines and carrier procurement disclosure patterns. A small set of triggers—GCAA UAE certification requirement expansion, FSSAI additive disclosure scope broadening, and biopolymer container manufacturing regionalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Europe Pizza Oven Market
Food Service
Food and Grocery Retail Market
Food Service
Quick-Service Restaurants Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Vacuum Flask Market
Food Service
One-Off Chopsticks Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Gourmet Street Food Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Peer-To-Peer Dining Market
Food Service
Netherlands Food Service Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Benelux Foodservice Market