
 United States Smokeless Indoor Grills Market | 2026-2036
United States Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smokeless Indoor Grills Market Insights
China is reconfiguring component supply chains for small kitchen appliances, indirectly influencing cost structures for US-bound smokeless grill manufacturers. Hamilton Beach leverages its Ohio-based distribution network to sustain shelf presence across mass retail channels. Ninja competes through R&D intensity in ceramic heating platforms. Cuisinart anchors the premium electric grill tier with stainless-steel construction lines.
Smokeless indoor grills are enclosed electric cooking appliances that use infrared, convection, or induction heating elements to sear proteins and vegetables while channeling grease into removable drip trays and filtering smoke through activated carbon or catalytic converters. These devices operate at temperatures between 350°F and 500°F, designed for residential kitchens and commercial foodservice settings where ventilation constraints prohibit traditional grilling. Electric grills dominate unit volume through accessibility and price positioning, while infrared technology captures margin pools via faster preheat cycles and reduced energy draw. Hybrid grills that combine radiant and convection modes represent the fastest-growing configuration as consumers seek versatility across proteins and vegetables. Households remain the core end-user segment, though food trucks in dense urban corridors are emerging as a concentrated commercial buyer.
The Consumer Product Safety Commission oversees electrical safety certification requirements for indoor grill heating elements and cord assemblies. The EPA's Energy Star program and DOE appliance efficiency standards shape wattage thresholds and standby power limits that manufacturers must navigate for market access. California's Title 20 appliance efficiency regulations impose additional constraints on products sold in that state. Stakeholders must monitor evolving municipal fire codes in high-density housing markets and the FTC's green marketing guidelines as brands emphasize smoke-reduction claims.
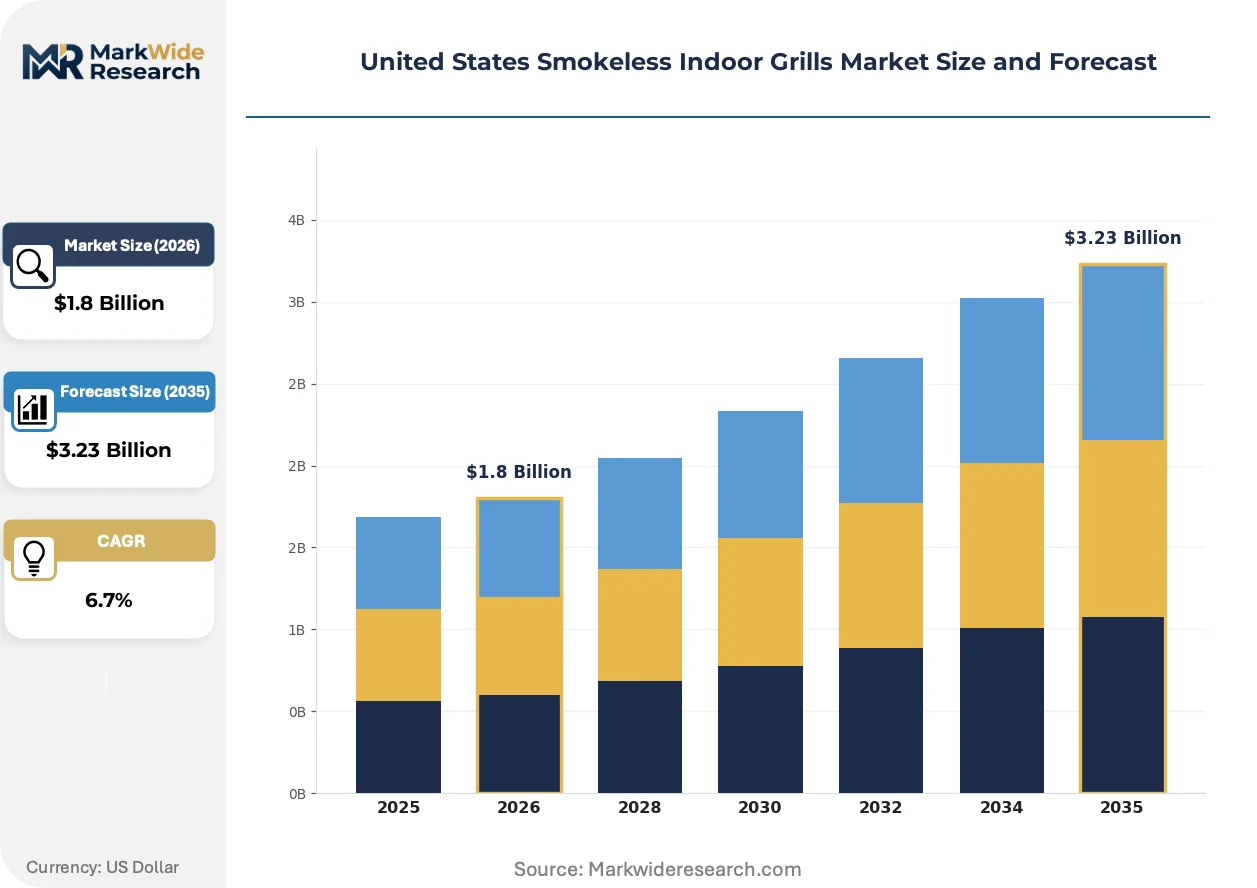
Market Dynamics
EPA indoor air quality standards and DOE appliance efficiency thresholds are compressing wattage tolerances for heating elements while catalyzing R&D investment in ceramic and infrared platforms. Manufacturers must navigate California's Title 20 constraints alongside municipal fire codes in high-density housing corridors.
Growth Catalysts
- Urban Housing Restrictions:Municipal fire codes in New York and Chicago prohibit balcony grilling, channeling demand toward enclosed electric alternatives with activated carbon filtration systems.
- DOE Efficiency Standards:Tightening standby power limits and wattage benchmarks are accelerating substitution of conventional hot plates with precision-controlled infrared cooking surfaces.
- Cold-Climate Concentration:Northeast and Midwest households facing extended winter seasons lack viable outdoor alternatives, sustaining year-round indoor grill utilization rates.
Market Restraints
- Copper and Aluminum Input Volatility:Heating element manufacturing depends on base metal prices subject to commodity exchange fluctuations, compressing margin stability for mid-tier producers.
- Component Supply Concentration:Ceramic heating substrate production clusters in East Asian manufacturing zones, exposing US-bound assemblers to shipping cost swings and customs processing delays.
- Convection Oven Substitution:Multi-function countertop appliances with air-fry capabilities capture overlapping use cases at comparable price points, fragmenting dedicated grill demand.
Strategic Opportunities
- Food Truck Channel Expansion:Mobile foodservice operators in dense urban corridors face ventilation constraints that favor compact electric grilling platforms over propane alternatives.
- FTC Green Marketing Tailwinds:Evolving guidelines on smoke-reduction claims create first-mover advantage for brands investing in third-party emissions certification and catalytic converter documentation.
- Smart Home Convergence:Integration of Bluetooth-enabled temperature probes with mobile application control is digitizing user interfaces and enabling subscription-based recipe content monetization.
Industry Challenges
- Electrical Safety Certification Timelines:CPSC review cycles for heating element and cord assembly testing extend product launch windows, compressing seasonal selling windows.
- Cross-State Compliance Fragmentation:California Title 20 efficiency thresholds diverge from federal DOE baselines, forcing SKU proliferation or feature-limited state-specific variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smokeless Indoor Grills Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Infrared Grills, Hybrid Grills, Portable Grills Technology: Induction Heating, Radiant Heating, Convection Heating, Ceramic Heating End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Philips, Hamilton Beach, George Foreman, Cuisinart, T-Fal, Ninja, Breville, Weber, Presto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smokeless Indoor Grills Market Trends and Innovations
Product development is pivoting toward hybrid heating architectures and connected interfaces as baseline expectations, with regulatory pressure on energy draw and emissions filtering accelerating platform consolidation.
Ceramic infrared heating technology is digitizing temperature control precision and reducing preheat latency for residential users. Apartment households in Chicago and Boston are adopting these platforms at accelerating rates, replacing coil-based electric grills. The technology is digitizing competitive differentiation around energy efficiency metrics and sear-quality consistency, compressing market share for conventional convection-only alternatives.
California's Title 20 appliance efficiency regulations are imposing wattage ceilings and standby power limits that exceed federal DOE thresholds. Manufacturers serving the California market must engineer state-specific variants or absorb compliance costs across national SKU lines. Premium stainless-steel product tiers are absorbing the bulk of redesign investment, while economy lines face delisting risk in the state.
Direct-to-consumer subscription models for replacement drip trays and carbon filters are displacing traditional retail attachment sales. Urban millennial households in Seattle and Denver are enrolling in automated replenishment programs at rates outpacing suburban buyers. This shift concentrates recurring revenue with brands possessing proprietary filter geometries, locking out third-party aftermarket suppliers.
United States Smokeless Indoor Grills Market Segmentation
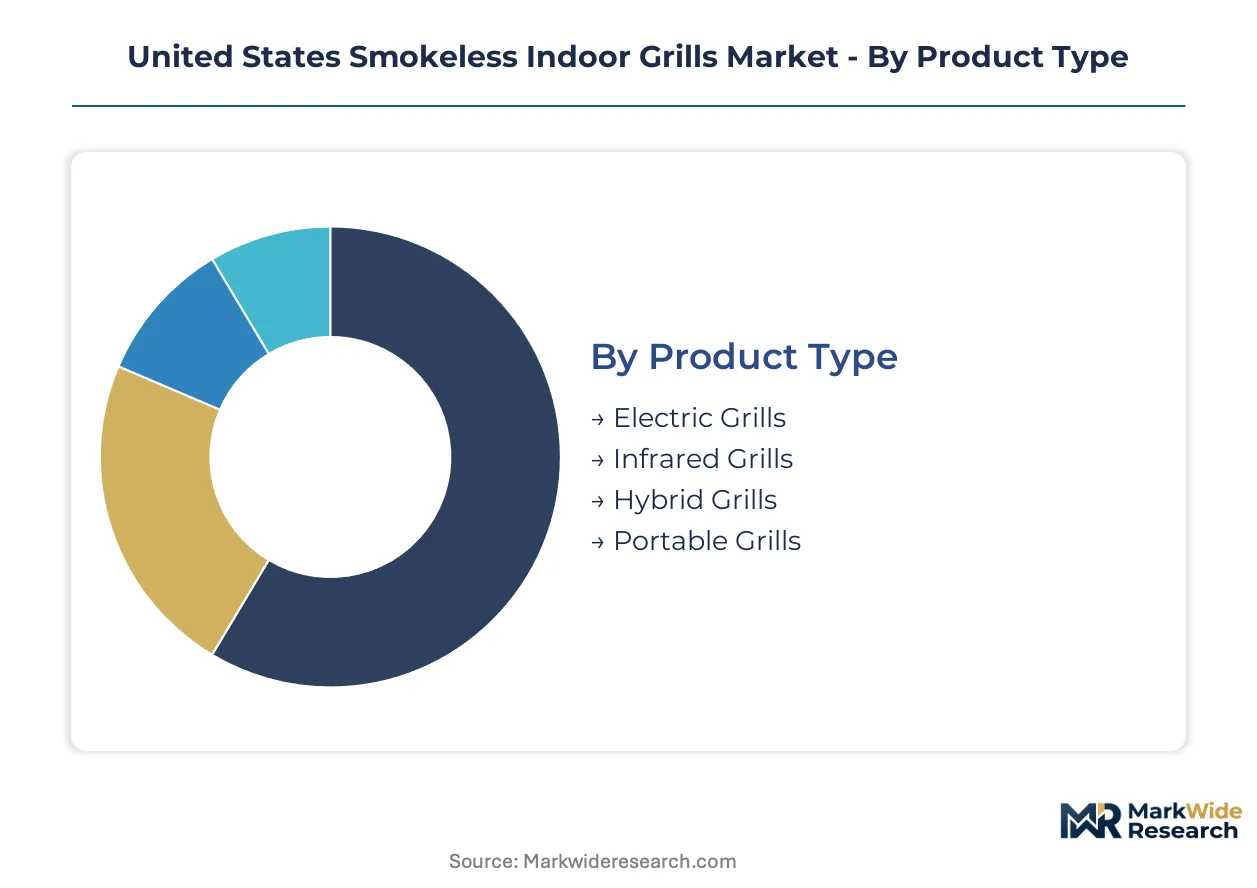
Smokeless indoor grill manufacturers engineer distinct product architectures to match ventilation constraints, power availability, and cooking performance expectations across residential and commercial environments. Segmentation choices directly determine warranty exposure, replacement part demand, and service network density requirements.
Product Type:
After-sales-service intensity varies sharply across product types, with heating element replacement rates and filter replenishment cycles driving recurring revenue attachment.
- Electric Grills:Coil-based or plate-style heating elements operating at 120V residential circuits dominate unit shipments through mass retail accessibility. Northeast apartment households in Boston and Philadelphia rely on these entry platforms where building electrical codes restrict higher-wattage alternatives.
- Infrared Grills:Ceramic or quartz infrared emitters deliver 700°F+ surface temperatures with sub-5-minute preheat latency. Chicago and Minneapolis households facing extended winter seasons favor these platforms for year-round grilling without balcony access.
- Hybrid Grills:Dual-mode radiant and convection architectures enable protein searing alongside vegetable roasting. Food trucks in Seattle and Portland deploy these units for menu versatility under strict municipal ventilation ordinances.
- Portable Grills:Compact sub-10-pound form factors with detachable power cords target tailgating and RV applications. Weekend recreational users in Colorado and Utah mountain corridors sustain seasonal demand spikes.
By volume, Electric Grills leads. By growth pace, Hybrid Grills is ahead.
Technology:
Technology selection determines energy efficiency certification pathways and California Title 20 compliance costs, with ceramic and induction platforms absorbing disproportionate R&D investment.
- Induction Heating:Electromagnetic coil systems generate heat directly in ferrous cookware, eliminating thermal mass and reducing standby losses. Commercial kitchens in New York City high-rises specify these platforms where fire codes prohibit open flames and traditional electric elements face wattage caps.
- Radiant Heating:Quartz or metal-sheathed elements provide direct infrared radiation for char-mark replication. Households in Detroit and Cleveland industrial corridors favor these systems for familiarity with traditional electric cooking surfaces.
- Convection Heating:Forced-air circulation with auxiliary heating coils enables multi-function roasting and baking. Apartment dwellers in San Francisco and Los Angeles select these units where kitchen counter space constraints favor single-appliance versatility.
- Ceramic Heating:Porous ceramic substrates with embedded resistance wire deliver rapid thermal response and uniform surface temperatures. Premium product tiers in the Northeast corridor integrate these elements to satisfy DOE efficiency benchmarks while maintaining sear performance.
By installed base, Radiant Heating dominates. By technology transition velocity, Ceramic Heating is expanding most quickly.
End User:
End-user segmentation dictates sales cycle length, with commercial accounts requiring municipal health department approvals and residential channels moving through seasonal retail patterns.
- Households:Primary demand concentration in urban apartment markets and suburban homes with restricted outdoor space. Winter climate severity in the Upper Midwest sustains replacement purchase velocity through Q1 selling periods.
- Restaurants:Full-service and fast-casual operators in downtown districts with ventilation infrastructure limitations. Chicago and Boston restaurant rows deploy these units for front-of-house grilling theater without exhaust hood investments.
- Catering Services:Mobile event operators requiring NSF-certified equipment for temporary kitchen permits. Wedding and corporate event caterers in Atlanta and Dallas corridors favor portable electric platforms for venue flexibility.
- Food Trucks:Dense urban mobile foodservice operators facing propane restrictions and noise ordinances. Seattle, Portland, and Austin food truck clusters represent concentrated commercial adoption zones with high unit utilization rates.
By absolute units, Households commands the base. By commercial application expansion, Food Trucks shows the steepest trajectory.
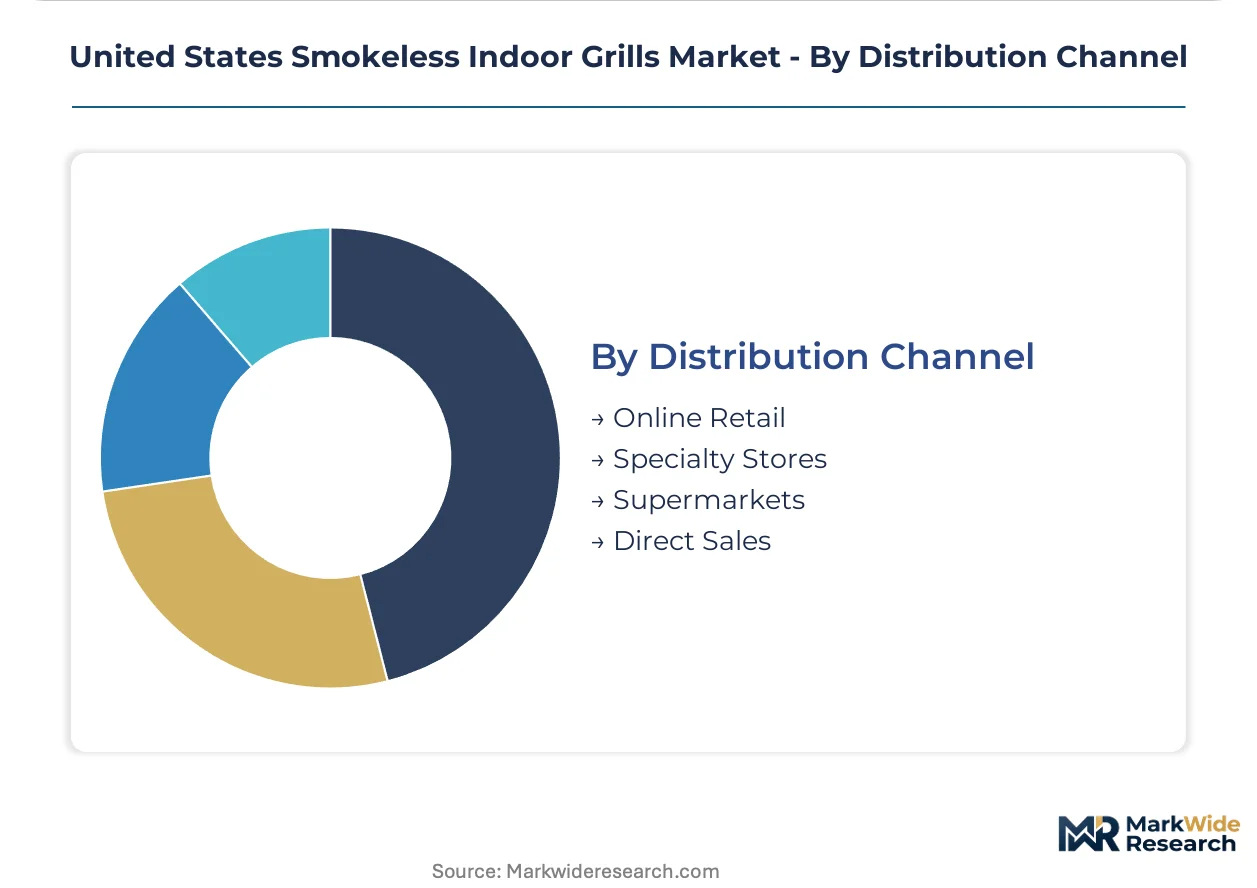
Distribution Channel:
Channel selection determines margin capture and customer acquisition economics, with direct and digital routes displacing traditional retail attachment sales for consumable replenishment.
- Online Retail:Amazon and DTC brand sites dominate research-intensive purchases with review-dependent conversion. Millennial households in Denver and Seattle enroll in automated filter replenishment programs at rates exceeding brick-and-mortar attachment.
- Specialty Stores:Williams Sonoma and Sur La Table locations provide hands-on demonstration and premium positioning. Affluent suburban markets in Connecticut and Northern Virginia sustain these channels for gift-oriented purchases.
- Supermarkets:Mass merchant and grocery big-box placements capture impulse and seasonal promotional demand. Midwest retailers including Meijer and Hy-Vee move volume through holiday promotional windows.
- Direct Sales:Manufacturer-owned channels enable proprietary filter geometry lock-in and subscription revenue concentration. Ninja and Hamilton Beach direct platforms capture recurring attachment sales previously lost to aftermarket suppliers.
By transaction volume, Supermarkets leads. By customer lifetime value expansion, Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for heating elements clusters in East Asian industrial zones, while final assembly and brand marketing concentrate in domestic Midwest and Southeast facilities. The EPA's regional air quality enforcement varies across state environmental agencies, creating compliance patchwork that shapes distribution logistics.
Northeast Corridor
New York and Boston apartment households drive replacement demand where municipal fire codes prohibit balcony propane grilling. Massachusetts and New York environmental agencies enforce stricter indoor air quality monitoring than federal baselines. Philadelphia and Baltimore retail corridors sustain seasonal promotional velocity through Q4 holiday windows.
Midwest Manufacturing Belt
Chicago and Minneapolis households facing extended winter seasons favor infrared platforms for year-round protein preparation without outdoor access. Illinois and Ohio state energy efficiency programs subsidize ENERGY STAR-certified appliance purchases. Cleveland and Detroit industrial corridors host legacy electric cooking equipment distributors pivoting toward smokeless grill SKUs.
Southeast Growth Markets
Atlanta and Charlotte suburban expansion creates first-time appliance demand among relocating professionals. Florida building codes emphasize electrical safety certification for high-humidity environments. Miami and Tampa food truck clusters adopt compact electric platforms under municipal noise and ventilation ordinances.
Pacific Coast Regulatory Zone
California Title 20 efficiency regulations impose wattage ceilings exceeding federal DOE thresholds, forcing SKU adaptation for West Coast distribution. Seattle and Portland foodservice operators face strict municipal ventilation requirements favoring catalytic converter-equipped units. Denver and Salt Lake City households enroll in direct-to-consumer filter replenishment programs at elevated rates.
Southwest Urban Corridors
Phoenix and Las Vegas apartment construction restricts outdoor grilling infrastructure across master-planned communities. Arizona and Nevada state energy offices promote electric cooking efficiency rebates during summer peak demand periods. Austin and Dallas food truck operators represent concentrated commercial adoption zones with high unit utilization rates.
United States Smokeless Indoor Grills Market Competitive Landscape
Mass-market appliance conglomerates and specialty kitchen equipment firms split the market along price-performance vectors. The structure consolidates around three tiers: premium stainless-steel positioning, mid-range feature differentiation, and entry-level volume distribution. Dominant competitive moves include portfolio diversification into adjacent countertop categories and direct-to-consumer channel expansion for recurring consumable revenue.
Among established kitchen appliance manufacturers, Hamilton Beach, Cuisinart, and Ninja occupy positions representing distinct strategic archetypes. Hamilton Beach exemplifies mass-market distribution scale through Midwest-based logistics networks. Cuisinart anchors premium-tier positioning with stainless-steel construction lines. Ninja represents R&D-intensive platform development in ceramic heating architectures. These three firms collectively illustrate the competitive spectrum from volume efficiency through innovation premium.
| Leading Market Players |
|---|
| Philips |
| Hamilton Beach |
| George Foreman |
| Cuisinart |
| T-Fal |
| Ninja |
| Breville |
| Weber |
| Presto |
| Others |
Pricing and Supply Chain Analysis
East Asian ceramic heating substrate concentration determines both pricing tier spreads and supply chain shape, forcing US-bound assemblers to absorb shipping cost volatility while engineering state-specific California Title 20 variants that fragment national SKU lines.
Pricing Analysis
California Title 20 dictates the pricing tier structure by imposing wattage ceilings that exceed federal DOE baselines, forcing manufacturers to engineer premium stainless-steel variants or delist economy lines in the state. Pricing stratifies across premium, standard, and economy tiers based on certification grade and ceramic heating element quality. Cost compression in mid-tier electric grills is intensifying because copper and aluminum input volatility compresses margin stability. Urban apartment households in the Northeast exhibit highest price sensitivity, while food truck operators demonstrate lowest sensitivity due to ventilation constraint-driven necessity.
Supply Chain Analysis
Extended payment terms from East Asian ceramic substrate suppliers are tightening working capital requirements for US assemblers navigating customs processing delays. Component manufacturing clusters in China, South Korea, and Taiwan feed heating element production, with raw material dependencies centering on copper wire, aluminum extrusions, and porous ceramic substrates. Single-source vulnerability in ceramic heating substrate production exposes assemblers to shipping cost swings and tariff exposure. Distribution runs through Midwest-based logistics networks serving mass retail channels alongside direct-to-consumer platforms capturing recurring filter replenishment revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against convection oven substitution as multi-function countertop appliances with air-fry capabilities fragment dedicated grill demand at comparable price points.
For Market Incumbents: Pre-empt convection oven substitution by deepening R&D investment in ceramic infrared platforms that digitize temperature precision and reduce preheat latency below competing multi-function alternatives. Secure backward integration into proprietary filter geometries to lock out third-party aftermarket suppliers and concentrate recurring subscription revenue. Prioritize Ohio-based distribution network expansion to defend shelf presence against DTC-native entrants. For New Entrants and Emerging Players: Southeast suburban expansion corridors around Atlanta and Charlotte offer concentrated first-time appliance demand among relocating professionals with limited brand loyalty. Food truck clusters in Austin and Dallas represent the most penetrable commercial segment, with high unit utilization rates and propane restriction-driven urgency. Pursue NSF certification pathways early to unlock temporary kitchen permits for catering services and mobile event operators. For Investors and Strategic Acquirers: EPA indoor air quality standard evolution reshapes the acquisition landscape by elevating the value of third-party emissions certification and catalytic converter documentation assets. Target firms possessing proprietary ceramic heating architectures and established direct-to-consumer filter replenishment programs for long-term viability through recurring revenue concentration. Monitor FTC green marketing guideline enforcement intensity as the signal indicating which smoke-reduction claims will survive regulatory scrutiny.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating R&D Intensification | Ninja's platform development demonstrates margin capture through preheat latency reduction. |
| Direct-to-Consumer Channel Expansion | Hamilton Beach's proprietary filter geometry locks out aftermarket suppliers for recurring revenue. |
| Food Truck Channel Penetration | Seattle and Portland municipal ventilation ordinances favor compact electric grilling platforms. |
| California Title 20 Compliance Engineering | State-specific variant development absorbs redesign investment concentrated in premium tiers. |
| Smart Home Integration Development | Bluetooth-enabled temperature probes enable subscription-based recipe content monetization. |
Research Methodology
The analysis maps electric, infrared, hybrid, and portable grill sub-sectors, each validated through product development executives, retail category buyers, food truck operators, and regulatory compliance officers. Primary interviews with Hamilton Beach, Cuisinart, and Ninja distribution and R&D stakeholders combined with secondary validation from EPA Energy Star filings, DOE appliance efficiency standards, California Title 20 regulations, and CPSC safety certification records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Assumptions held fixed include prevailing EPA indoor air quality standards and DOE wattage benchmarks, while variables included ceramic heating technology adoption velocity and food truck commercial penetration rates. The analytical framework models product type, technology platform, end-user segment, and distribution channel dimensions across the analysis window. CAGRs derived from regression analysis of historical shipment data against urban housing restriction intensity and cold-climate household concentration metrics. Forecast inputs incorporated municipal fire code evolution in high-density housing corridors and FTC green marketing guideline enforcement trajectories.
Practitioners should monitor ceramic substrate supply chain disruption indicators and EPA regulatory revision timelines for early signals of forecast deviation. Macroeconomic contraction affecting discretionary appliance purchases, regulatory relaxation of indoor air quality standards, or breakthrough multi-function appliance technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Smoker Grill Market
Food Service
France Foodservice Market
Food Service
Beverage Coaster Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Flat Top Grills Market
Food Service
China Inflight Catering Market
Food Service
United Kingdom Foodservice Market
Food Service
Kamado Grill Market
Food Service
Europe Vending Machine Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
United Arab Emirates Full Service Restaurants Market
Food Service
Singapore Food Service Market
Food Service
UAE Food Service Market
Food Service
South Africa Fast Food Market
Food Service
Pizza Oven Market
Food Service
Asia-Pacific Halal Food and Beverage Market