
 Global Spinal Imaging Treatment Market | 2026-2036
Global Spinal Imaging Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spinal Imaging Treatment Market Foresight
Gadolinium-based contrast agents are decoupling from standard MRI protocols as non-contrast sequences and artificial intelligence reconstruction advance. Siemens Healthineers leverages proprietary compressed sensing technology to sustain scan-time reductions without chelated agents. GE Healthcare anchors its portfolio through deep learning image reconstruction that competes on diagnostic confidence in degenerative spine cases.
Spinal imaging treatment encompasses diagnostic modalities that visualize vertebral anatomy, neural foramina, and paraspinal soft tissues to guide surgical planning, monitor disease progression, or rule out malignancy. MRI systems dominate procedural volume due to superior soft-tissue contrast and absence of ionizing radiation, while CT scanners occupy emergency settings where fracture detection speed determines triage. The product type dimension shows MRI Systems capturing the largest installed base, whereas CT Scanners represent the fastest-growing segment driven by trauma protocol standardization. Among end users, specialty spine centers differentiate through dedicated coil arrays and streamlined workflows that concentrate high-acuity referrals.
FDA 510(k) premarket notification governs device clearance in the United States, while the EU MDR and CE marking framework reshape conformity assessment timelines for European launches. Japan's PMDA enforces QMS inspections that extend lead times but reinforce product reliability for export markets. Stakeholders must monitor reimbursement code consolidation for AI-augmented reads and prepare for divergent evidentiary requirements across notified bodies.
Market Dynamics
Gadolinium decoupling from routine MRI protocols is compressing contrast-agent revenues while forcing hardware manufacturers to differentiate on reconstruction software. This structural shift rewards vendors with proprietary compressed-sensing algorithms and penalizes legacy equipment lacking AI-native pipelines.
Growth Catalysts
- FDA 510(k) AI Pathway:The streamlined premarket notification for diagnostic software accelerates commercial entry of machine-learning reconstruction tools. US-based spine centers adopt these cleared algorithms to reduce scan times without contrast.
- Germany's DRG Reimbursement:Diagnosis-related group coding for minimally invasive spinal procedures reimburses advanced imaging at premium rates. German hospitals upgrade coil arrays and workstation capacity to capture these payments.
- Compressed Sensing:This mathematical framework enables sub-Nyquist sampling that preserves diagnostic fidelity. Siemens Healthineers deploys it across MAGNETOM platforms to eliminate gadolinium dependence in degenerative disc evaluation.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over 75% of global helium extraction. MRI magnet cooling depends on this concentrated supply, exposing installed base maintenance to geopolitical disruption and price volatility.
- EU MDR Transition:The Medical Device Regulation extends conformity assessment timelines by 12-18 months for European launches. Manufacturers face working capital strain from delayed revenue recognition on new coil designs.
- CT Radiation Dose Accumulation:Repeated trauma protocol scans in emergency settings accumulate ionizing exposure. This technical limitation restricts CT monitoring of chronic spinal conditions where MRI dominates.
Strategic Opportunities
- Japan's Super-Aged Society:Over 29% of Japan's population exceeds 65 years, generating sustained demand for degenerative spine assessment. PMDA's reliability-focused inspection regime positions Japanese-manufactured systems for premium export markets.
- Outpatient Imaging Centers:Freestanding facilities in the United States capture shifting volume from hospital-based radiology. These centers prioritize throughput-optimized protocols and lease-based equipment financing.
- AI-Augmented Triage:Deep learning classifiers integrated into emergency CT workflows flag unstable fractures for priority surgical consultation. This technology convergence addresses radiologist staffing gaps in overnight coverage.
Industry Challenges
- MR Physicist Shortage:Specialized training for sequence optimization and artifact correction requires 4-6 years post-graduate preparation. Academic medical centers compete with industry for this limited talent pool.
- Legacy PACS Integration:Picture archiving systems deployed in the 2010s lack API architectures for AI-native reconstruction outputs. Hospitals face middleware development costs or complete replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spinal Imaging Treatment Market |
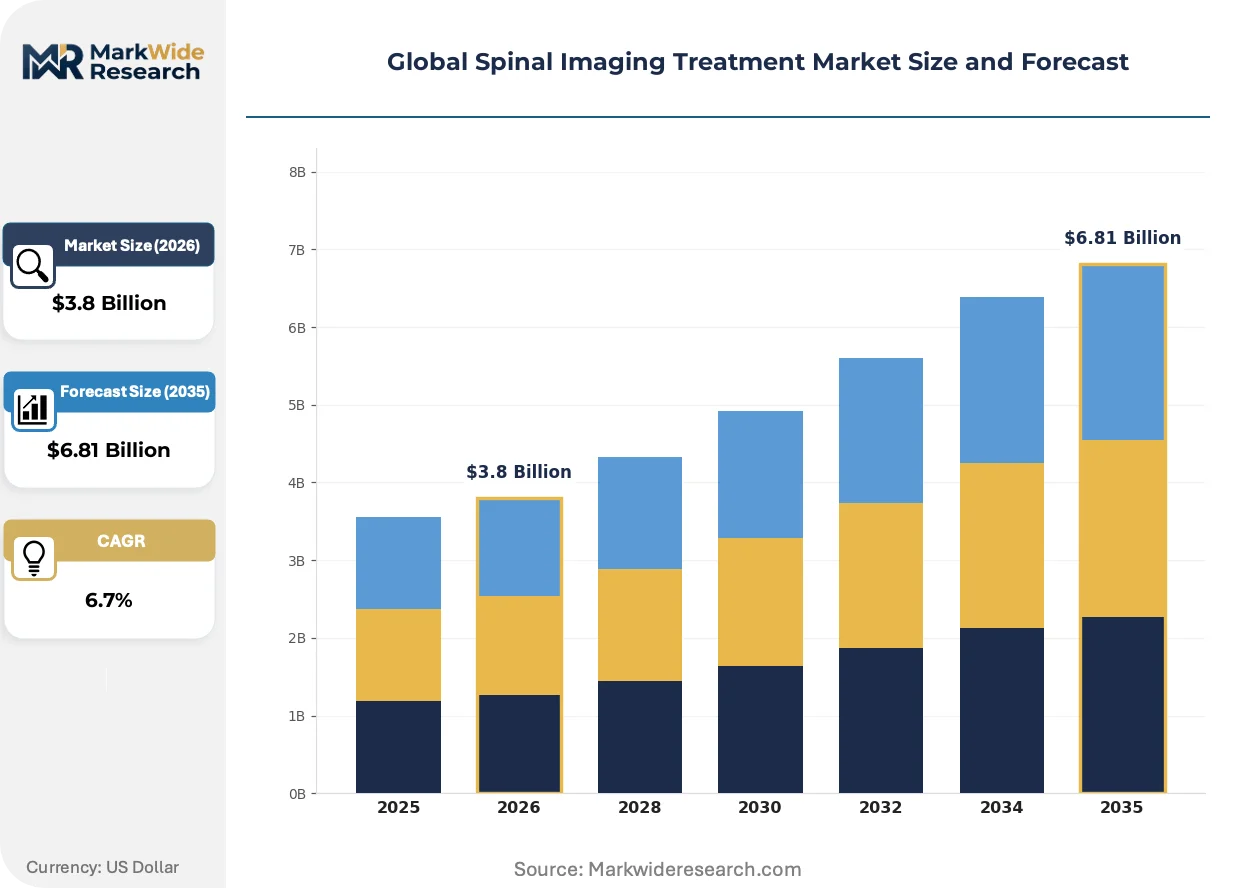
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MRI Systems, CT Scanners, X-Ray Devices, Ultrasound Systems, Fluoroscopy Equipment Imaging Technology: Magnetic Resonance Imaging, Computed Tomography, Digital Radiography, Fluoroscopy, Ultrasound Imaging Treatment Application: Degenerative Disorders, Traumatic Injuries, Tumor Diagnosis, Infections, Congenital Spine Deformities End User: Hospitals, Rehabilitation Centers, Diagnostic Laboratories, Orthopedic Clinics, Specialty Spine Centers |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems, Bruker, FUJIFILM, Shimadzu Corporation, Hitachi Ltd., Mediso Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spinal Imaging Treatment Market Shifts & Advancements
Artificial intelligence reconstruction is compressing scan durations while eliminating contrast dependence, fundamentally altering equipment procurement criteria and service contract structures across hospital systems.
Synthetic MRI sequences are rewriting the economics of spinal imaging by generating multiple contrast weightings from single acquisitions. Academic medical centers in the United States deploy these protocols for surgical planning in complex deformity cases. The technology is compressing examination slots from 45 minutes to under 20, enabling volume expansion without capital expansion.
Japan's PMDA has tightened QMS inspection protocols for AI-embedded diagnostic devices, extending lead times but reinforcing reliability benchmarks for export certification. European manufacturers seeking Japanese market entry must demonstrate training data diversity across Asian anatomical variations. This regulatory friction is concentrating vendor resources on multi-regional validation studies rather than single-market launches.
Hospital procurement committees now weight total cost of ownership over acquisition price, unbundling maintenance from equipment financing and demanding outcome guarantees on uptime metrics. United States health systems with centralized supply chain functions lead this behavioral shift, pressuring manufacturers toward subscription-based software licensing and away from perpetual hardware sales.
Global Spinal Imaging Treatment Market Segmentation
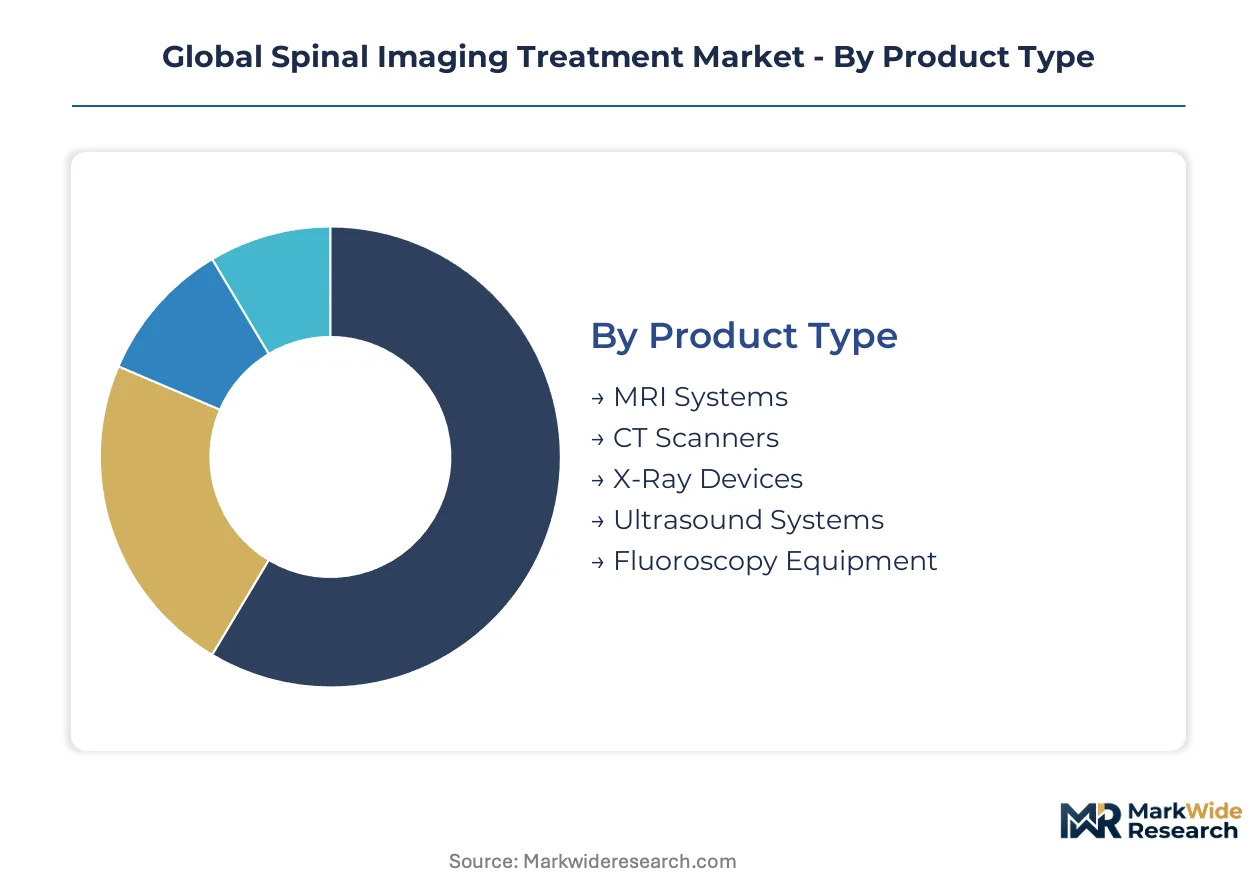
Spinal imaging treatment procurement diverges sharply across clinical settings, with hardware specifications and workflow integration requirements driving fundamentally different purchasing criteria. Understanding these segment boundaries clarifies why vendors maintain parallel product architectures rather than unified platforms.
Product Type:
Capital allocation thresholds separate buyers who prioritize soft-tissue resolution from those optimizing throughput per square meter.
- MRI Systems:Superconducting magnets with 1.5T to 3T field strength generate T1-weighted, T2-weighted, and STIR sequences for disc herniation and cord compression assessment. United States academic medical centers concentrate demand here, driven by neurosurgical referral networks requiring preoperative nerve root visualization. Compressed sensing algorithms now enable sub-30-minute spine protocols without gadolinium.
- CT Scanners:Multi-detector arrays with 64-slice minimum configuration deliver sub-millimeter isotropic resolution for fracture line detection. German trauma centers anchor European volume, where fall-related vertebral compression injuries in aging populations sustain 24/7 scanner utilization. Dual-energy subtraction techniques distinguish bone marrow edema from soft tissue.
- X-Ray Devices:Digital radiography systems with dynamic flat-panel detectors support weight-bearing scoliosis series. Orthopedic clinics in Japan deploy these for post-operative fusion assessment.
- Ultrasound Systems:High-frequency linear transducers enable intraoperative pedicle screw guidance. Rehabilitation centers leverage portable units for real-time needle placement in pain management procedures.
- Fluoroscopy Equipment:C-arm configurations with pulsed fluoroscopy minimize dose during interventional spine procedures. Ambulatory surgery centers prioritize compact footprint models.
Volume sits with MRI Systems; growth tilts toward CT Scanners.
Imaging Technology:
Reconstruction mathematics now differentiates competitive positioning more than hardware specifications.
- Magnetic Resonance Imaging:Proton density mapping exploits differential T1 and T2 relaxation times across cerebrospinal fluid, neural tissue, and bone marrow. Siemens Healthineers' compressed sensing implementation at University Hospital Heidelberg eliminates contrast agents in 40% of degenerative spine cases.
- Computed Tomography:Iterative reconstruction algorithms reduce noise at fixed radiation dose, or equivalently permit dose reduction at fixed image quality. Massachusetts General Hospital's emergency department processes 200+ trauma spine studies weekly through deep learning-optimized protocols.
- Digital Radiography:CsI scintillator panels with 139-micron pixel pitch resolve cortical bone detail. Community hospitals in Texas deploy these for pre-authorization screening before MRI referral.
- Fluoroscopy:Last-image-hold and pulsed acquisition modes limit cumulative exposure. Pain management practices in Florida favor mobile C-arms for office-based procedures.
- Ultrasound Imaging:Compound imaging with spatial compounding reduces speckle artifact. Physiatrists at Johns Hopkins apply these for zygapophyseal joint injections.
Procurement concentrates on Magnetic Resonance Imaging; Computed Tomography gains share fastest through AI reconstruction adoption.
Treatment Application:
Reimbursement intensity and procedure complexity create divergent equipment utilization patterns.
- Degenerative Disorders:Spondylosis, disc degeneration, and spinal stenosis generate recurring imaging for disease monitoring. Japanese super-aged society demographics concentrate demand here, with patients over 70 requiring serial assessment of canal narrowing progression.
- Traumatic Injuries:Vertebral fractures, dislocations, and cord contusions demand rapid protocol execution. Level I trauma centers in Chicago and Los Angeles maintain dedicated CT capacity for 15-minute turnaround from arrival to report.
- Tumor Diagnosis:Primary spine tumors and metastatic lesions require whole-spine screening with contrast-enhanced sequences. Oncology networks in Germany integrate these into staging protocols.
- Infections:Discitis-osteomyelitis and epidural abscess evaluation combines MRI with CT-guided biopsy. Infectious disease services at Mayo Clinic coordinate these workflows.
- Congenital Spine Deformities:Scoliosis, kyphosis, and segmentation anomalies need longitudinal growth monitoring. Pediatric orthopedic centers in Philadelphia track Cobb angle progression.
Revenue concentrates in Degenerative Disorders; Traumatic Injuries drive capacity expansion.
End User:
Capital intensity and case mix sophistication stratify purchasing authority across facility types.
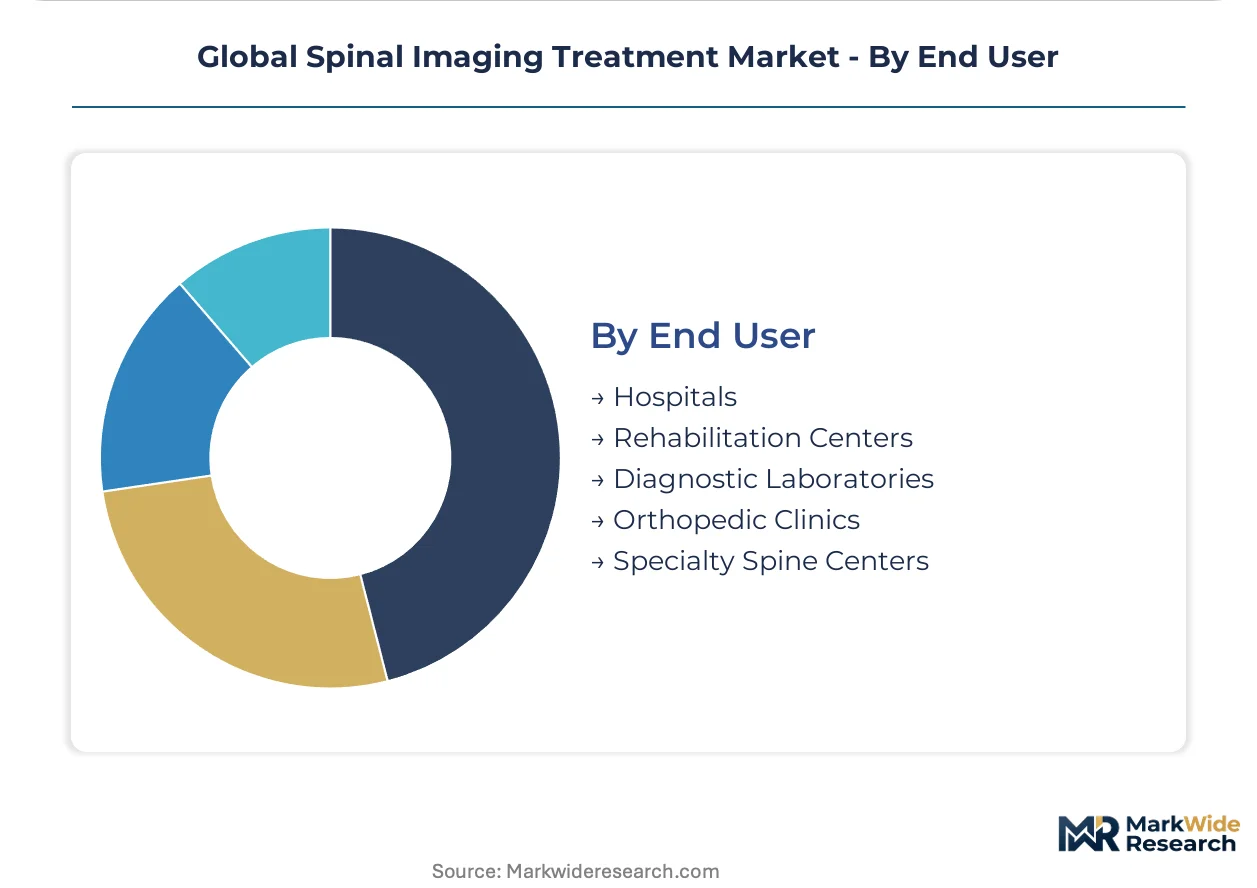
- Hospitals:Integrated health systems with neurosurgical and orthopedic service lines maintain 3T MRI and 256-slice CT portfolios. Cleveland Clinic's spine institute processes 15,000+ advanced imaging studies annually through dedicated technologist teams.
- Specialty Spine Centers:Focused facilities combine diagnostic and surgical services with streamlined scheduling. Texas Back Institute operates dedicated MRI suites with 48-hour appointment windows.
- Orthopedic Clinics:Private practice groups prioritize digital X-ray with limited CT access. Suburban Chicago practices lease equipment to manage capital exposure.
- Diagnostic Laboratories:Independent imaging centers compete on price and convenience. RadNet facilities in California offer evening and weekend spine MRI slots.
- Rehabilitation Centers:Post-acute facilities emphasize functional assessment over diagnostic resolution. Spaulding Rehabilitation Network in Boston applies ultrasound for injection guidance.
Installed base concentrates in Hospitals; Specialty Spine Centers expand capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for spinal imaging treatment concentrates in aging economies with established reimbursement infrastructure. The United States, Germany, and Japan absorb disproportionate equipment shipments due to DRG-based hospital payments and super-aged demographics. Regulatory pathways diverge sharply across these markets, shaping vendor launch sequencing and service contract structures.
United States
Academic medical centers in Boston and Houston drive 3T MRI upgrades for neurosurgical referral networks. FDA's 510(k) premarket notification accelerates AI-assisted reconstruction software entry, compressing clearance timelines for machine-learning diagnostic tools. Cleveland Clinic's spine institute processes over 15,000 advanced imaging studies annually through dedicated technologist teams and compressed sensing protocols.
Germany
Diagnosis-related group coding reimburses minimally invasive spinal procedures at premium rates, incentivizing hospital investment in advanced coil arrays. EU MDR conformity assessment extends European launch timelines by 12-18 months, straining manufacturer working capital. Trauma centers in Berlin and Munich maintain 24/7 CT capacity for fall-related vertebral compression injuries in aging populations.
Japan
Over 29% of Japan's population exceeds 65 years, generating sustained demand for degenerative spine assessment and serial canal narrowing monitoring. PMDA enforces QMS inspections that extend lead times but reinforce reliability benchmarks for export certification. Tokyo and Osaka academic hospitals anchor demand for synthetic MRI sequences that compress examination slots from 45 minutes to under 20.
United Kingdom
NHS England's imaging networks consolidate procurement authority, shifting purchasing toward framework agreements with outcome-based uptime guarantees. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines, creating parallel conformity assessment requirements. London and Manchester spine centers prioritize lease-based equipment financing to manage capital exposure amid budget constraints.
China
Hospital construction in provincial capitals expands MRI and CT installed base beyond tier-one cities. NMPA medical device registration requires in-country clinical trials for imported systems, extending market entry timelines. Beijing and Shanghai tertiary hospitals anchor demand for 3T platforms with AI-native reconstruction pipelines, while secondary cities absorb refurbished 1.5T systems.
Global Spinal Imaging Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated health systems favoring full-service OEM relationships while outpatient centers prioritize equipment leasing flexibility. The vendor landscape consolidates around three strategic archetypes: diversified conglomerates with cross-modality portfolios, pure-play MRI specialists leveraging proprietary reconstruction mathematics, and regional fabricators competing on localized service response. Dominant competitive moves include strategic partnerships for AI software integration and backward integration into magnet manufacturing to secure helium supply chains.
Among diversified conglomerates, GE Healthcare and Siemens Healthineers exemplify the full-modality archetype, anchoring competitive positioning through integrated hardware-software ecosystems and compressed sensing implementations. Koninklijke Philips N.V. occupies a position within the premium-tier diagnostic imaging segment, representing the Netherlands-based multinational approach to cross-border regulatory navigation and centralized R&D coordination.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Bruker |
| FUJIFILM |
| Shimadzu Corporation |
| Hitachi Ltd. |
| Mediso Ltd. |
| Others |
Supply & Pricing Matrix
Hospital procurement committees demanding outcome-based uptime guarantees are forcing manufacturers toward subscription-based software licensing and unbundled maintenance contracts, compressing hardware margins while elevating recurring revenue streams.
Pricing Analysis
Volume concentrates in high-field MRI systems where compressed sensing algorithms command premium positioning, while margin expansion sits with AI-native reconstruction software sold on subscription tiers. Price differentiation separates FDA-cleared diagnostic platforms from CE-marked equivalents, with Japanese PMDA-inspected systems capturing additional reliability premiums. Pricing pressure stems from outpatient imaging centers prioritizing lease-based equipment financing over capital purchase. Community hospitals exhibit highest price sensitivity; academic medical centers with neurosurgical referral networks demonstrate lowest.
Supply Chain Analysis
Helium supply rests on concentrated extraction in Qatar and the United States, with MRI magnet cooling drawing from this geographic concentration. Superconducting wire production sources from Japan and Germany, while gradient coil assemblies hinge on specialized copper winding facilities in China. Single-source vulnerability runs through helium refining capacity exposed to geopolitical disruption. Distribution runs through OEM direct sales for hospital systems and third-party leasing channels for outpatient centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium supply concentration props pricing power for manufacturers with captive magnet cooling infrastructure, creating a supply-constrained environment where equipment availability determines contract terms.
For Market Incumbents: To counter gadolinium decoupling from routine MRI protocols, Siemens Healthineers and GE Healthcare must accelerate proprietary compressed sensing deployment while securing backward integration into helium supply chains. Investment in AI-native reconstruction pipelines at University Hospital Heidelberg and Massachusetts General Hospital preserves diagnostic confidence without contrast agents. Certification investment for PMDA QMS inspection readiness protects Japanese market access. For New Entrants and Emerging Players: AI-augmented triage algorithms for emergency CT workflows represent the most penetrable wedge, addressing radiologist staffing gaps in overnight coverage at Level I trauma centers. Outpatient imaging centers in the United States offer white-space expansion through throughput-optimized protocols and flexible lease structures. Synthetic MRI sequence development for degenerative spine assessment provides a go-to-market angle distinct from incumbent hardware portfolios. For Investors and Strategic Acquirers: The window for entry favors pure-play MRI specialists with proprietary reconstruction mathematics and established helium supply relationships. Long-term viability centers on software-defined imaging platforms capable of decoupling revenue from magnet sales. The signal to watch is FDA 510(k) clearance velocity for AI-assisted diagnostic tools as an inflection indicator for competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines for AI reconstruction tools at US spine centers compress competitive entry windows. |
| CE Marking Pathway | EU MDR conformity assessment restructuring demands extended validation timelines for European coil array launches. |
| Hospital System Partnership | Cleveland Clinic's dedicated technologist teams demonstrate outcome-based procurement criteria spreading across academic networks. |
| Software Companion Development | Compressed sensing algorithms eliminating gadolinium dependence reshape service contract structures toward recurring revenue. |
| Reimbursement Strategy | Germany's DRG premium rates for minimally invasive spinal procedures anchor coil array upgrade cycles. |
Research Methodology
Multi-period observation of FDA 510(k) clearance volumes, PMDA QMS inspection timelines, and hospital procurement database trends anchored the trend analysis, supplemented by interviews with MRI physicists, GPO contracts managers, biomedical engineers, and hospital purchasing committee members. Secondary validation drew from FDA filings, CMS Medicare reimbursement data, EU MDR notified body disclosures, and hospital capital expenditure records. Bottom-up equipment shipment tracking and top-down healthcare spending allocation models were triangulated.
Segment-weighting across product type, imaging technology, treatment application, and end user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Forecast inputs incorporated helium supply elasticity parameters and AI software adoption curves across academic versus community hospital settings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption scenarios and divergent EU MDR enforcement intensity. Forecasts reflect documented assumptions on reimbursement code consolidation for AI-augmented reads and synthetic MRI protocol penetration rates. A small set of triggers—PMDA inspection backlog accumulation, Qatar helium export policy shifts, and NHS England framework agreement renegotiations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Italy Magnetic Resonance Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market