
 Global Semiconductor Device Market | 2026-2036
Global Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Device Market Foresight
Buyer concentration is shifting as automotive OEMs and hyperscale data center operators consolidate procurement power while IoT and edge-AI startups fragment demand across smaller volumes. TSMC anchors advanced-node foundry supply through massive capital deployment in Arizona and Japan. Nvidia dominates AI accelerator architecture, sustaining pricing power through proprietary interconnects and software ecosystems. Intel Corporation navigates manufacturing process recovery while competing for foundry customers against established pure-play alternatives.
Semiconductor devices are electronic components fabricated on crystalline silicon, gallium arsenide, or silicon carbide substrates, typically featuring nanoscale transistor densities measured in billions per square millimeter, functioning as switches, amplifiers, or memory cells in virtually all electronic systems. Memory Chips lead revenue contribution due to cyclical capacity expansion in DDR5 and HBM3E generations, while Power Semiconductors built on SiC and GaN technologies represent the fastest-expanding margin pool as electrification accelerates. CMOS technology occupies the mature volume base across consumer and computing applications, whereas Photonic integration is concentrating R&D investment for co-packaged optics in data centers.
FDA oversight affects medical device semiconductor content through embedded system validation, while FCC certification governs RF component emission standards for telecommunications deployment. EPA regulations on fluorinated greenhouse gases constrain etching chemistry choices in US fabrication, and REACH compliance in Europe mandates material disclosure across complex supply chains. Stakeholders must monitor how export control coordination between the US Department of Commerce and allied regulators reshapes equipment sourcing and customer access for advanced logic and memory products.
Market Dynamics
Advanced-node foundry capacity concentrates in Taiwan, South Korea, and the United States while automotive electrification and AI infrastructure build-out pull silicon carbide and high-bandwidth memory into supply-constrained allocation queues.
Growth Catalysts
- EU Chips Act subsidies:European governments are directing capital toward domestic fabrication facilities, altering investment flows for mature-node and specialty production.
- Electric vehicle powertrains:Automotive OEMs are expanding silicon carbide adoption for traction inverters and onboard chargers, creating sustained demand for wide-bandgap substrates.
- HBM3E memory generation:AI accelerator architectures require stacked memory with terabyte-scale bandwidth, pulling capacity expansion from commodity DRAM.
Market Restraints
- Neon gas supply concentration:Ukrainian and Russian-sourced noble gases face disruption risk, constraining lithography laser operation for deep-ultraviolet exposure systems.
- EPA fluorinated gas constraints:Etching chemistry choices in US fabrication face regulatory limits on perfluorinated compound emissions, raising process conversion costs.
- Advanced packaging bottleneck:CoWoS and 2.5D interposer capacity trails demand from AI chip designers, extending lead times for high-performance compute modules.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor assembly and testing are attracting OSAT investment to diversify geographic risk.
- Photonic integration:Co-packaged optics for data center interconnects converges silicon photonics with CMOS logic, opening new packaging revenue pools.
- Edge-AI inference:Low-power neural accelerators for industrial and consumer endpoints represent underpenetrated volume relative to cloud training demand.
Industry Challenges
- Process engineer scarcity:Advanced-node yield optimization requires specialized expertise in atomic-layer deposition and EUV resist chemistry that outpaces university pipeline output.
- Legacy node equipment sourcing:200mm wafer tool refurbishment faces component obsolescence, complicating capacity expansion for automotive microcontrollers and power discretes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Device Market |
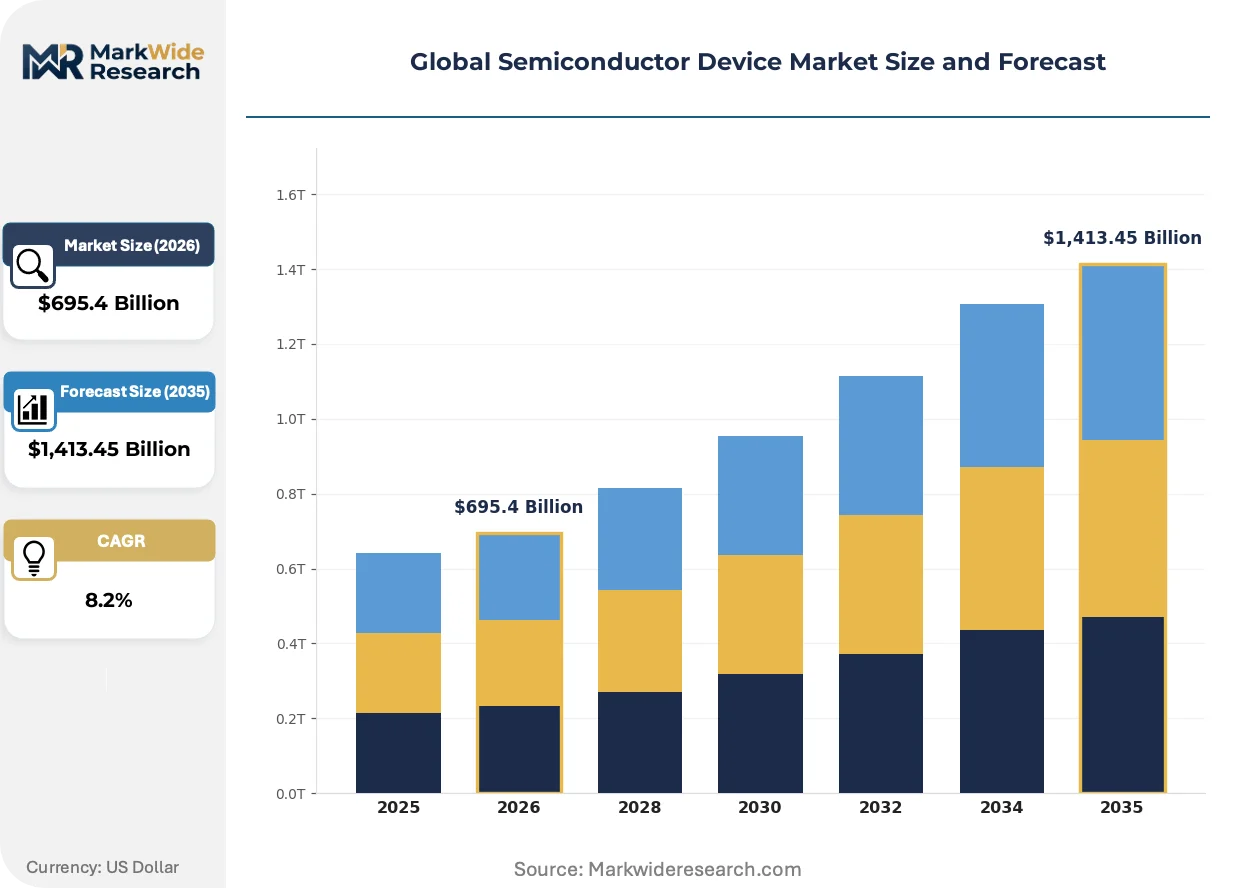
| Market Size in 2026 | $695.4 Billion |
| Market Size in 2035 | $1,413.45 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Memory Chips, Analog ICs, Power Semiconductors, Sensors Technology: CMOS, Bipolar, GaN, SiC, MEMS, Photonic Application: Consumer Electronics, Telecommunications, Industrial Automation, Aerospace, Defense End User: OEMs, Electronic Manufacturing Service Providers, System Integrators, Research Institutes |
| Companies Covered | Intel Corporation, Nvidia Corporation, TSMC, Samsung Electronics, Qualcomm Incorporated, Texas Instruments, SK Hynix, Micron Technology, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Device Market Shifts & Advancements
Chiplet-based architectures are fragmenting monolithic die designs while regulatory pressure on process emissions intensifies chemistry substitution timelines.
Silicon carbide MOSFETs are decentralizing power conversion architectures across electric vehicle drivetrains and renewable energy inverters. Automotive Tier-1 suppliers are qualifying 800-volt battery systems at accelerated pace. This voltage platform shift is decentralizing thermal management requirements and enabling smaller cable gauges that compress vehicle weight and cost structures.
REACH compliance in Europe mandates material disclosure across complex semiconductor supply chains. ECHA substance restrictions are forcing substitution of certain flame retardants and plasticizers in encapsulation materials. Memory module manufacturers serving EU industrial automation customers are accelerating halogen-free substrate qualification to maintain market access.
Hyperscale data center operators are consolidating accelerator procurement through direct foundry relationships rather than merchant silicon vendors. Cloud infrastructure divisions at Amazon, Google, and Microsoft are designing custom AI training chips that displace standard GPU sockets. This direct engagement pattern is most visible in United States and Chinese server deployments where vertical integration into silicon design compresses supplier margins.
Global Semiconductor Device Market Segmentation
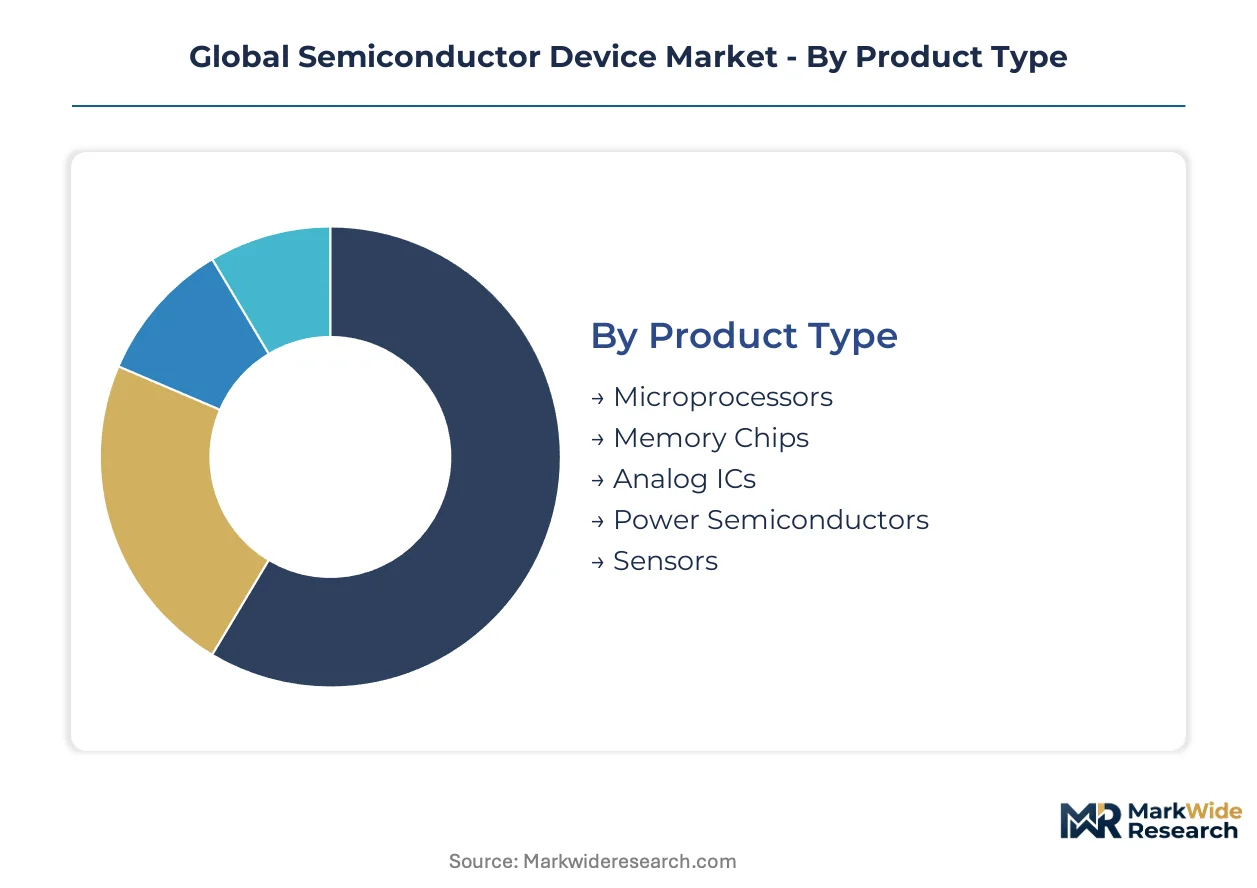
Semiconductor device segmentation reveals how procurement priorities diverge across power efficiency, computational density, and environmental tolerance requirements. Buyers in automotive and data center verticals weight thermal performance and bandwidth specifications differently than consumer electronics manufacturers chasing cost-optimized integration.
Product Type:
Procurement teams prioritize thermal envelopes and computational throughput when selecting device categories for specific system architectures.
- Memory Chips:Stacked DRAM architectures including HBM3E and DDR5 generations deliver terabyte-scale bandwidth for AI training clusters. Hyperscale operators in the United States and Taiwan are pulling capacity expansion away from commodity DRAM toward high-bandwidth variants, constrained by CoWoS packaging bottlenecks.
- Power Semiconductors:Silicon carbide and gallium nitride substrates enable switching efficiencies above 98% in traction inverters and onboard chargers. Automotive OEMs in Germany and Japan are qualifying 800-volt battery platforms, decentralizing thermal management and compressing vehicle weight through reduced cable gauges.
- Microprocessors:Advanced-node CPUs and GPUs fabricated at 3nm and below dominate high-performance computing sockets.
- Analog ICs:Signal conditioning and power management circuits serve industrial automation and automotive sensor fusion.
- Sensors:MEMS and image sensors enable environmental perception in consumer devices and autonomous systems.
Volume sits with Memory Chips; growth tilts toward Power Semiconductors.
Technology:
Process selection hinges on frequency requirements, breakdown voltage tolerances, and integration complexity with photonic or mechanical elements.
- SiC:Wide-bandgap substrates withstand electric fields ten times higher than silicon, enabling compact power modules for electric vehicle drivetrains. Foundries in South Korea and the United States are expanding 150mm and 200mm SiC wafer capacity to serve automotive qualification timelines.
- Photonic:Silicon photonics integrates lasers, modulators, and detectors with CMOS logic for co-packaged optics in data center interconnects. Cloud operators in Virginia and Oregon are deploying photonic-enabled switches to reduce electrical I/O power consumption.
- CMOS:Complementary metal-oxide-semiconductor processes dominate digital logic at mature and advanced nodes.
- GaN:Gallium nitride enables megahertz-switching frequencies in compact chargers and RF power amplifiers.
- MEMS:Microelectromechanical systems combine mechanical sensing with electronic signal processing.
- Bipolar:Bipolar junction technologies persist in high-linearity analog and RF applications.
CMOS commands wafer volume; SiC and Photonic technologies are climbing the fastest.
Application:
End-use environments dictate reliability grading, temperature specifications, and regulatory certification requirements.
- Telecommunications:Baseband processors and RF front-ends for 5G infrastructure require FCC emission compliance and carrier-grade reliability. Equipment vendors in Finland and Sweden are qualifying Open RAN chipsets through the O-RAN Alliance certification framework.
- Aerospace:Radiation-hardened devices for satellite and avionics systems must satisfy EASA and FAA DO-254 design assurance guidelines. European satellite manufacturers in Toulouse and Munich are sourcing qualified FPGAs through defense procurement channels.
- Consumer Electronics:Mobile handsets and wearables drive high-volume demand for application processors and display drivers.
- Industrial Automation:Programmable logic controllers and motor drives require extended temperature ranges and functional safety certification.
- Defense:Secure microelectronics face export control restrictions under ITAR and allied regulatory coordination.
Consumer Electronics absorbs the greatest unit volume; Aerospace and Defense command the steepest expansion trajectory.
End User:
Supply chain positioning determines whether buyers access foundry capacity directly or through distribution intermediaries.
- OEMs:Original equipment manufacturers in automotive and consumer electronics increasingly engage foundries through direct capacity reservation agreements. Tesla and Apple have secured dedicated wafer starts at TSMC Arizona and Samsung Texas.
- Electronic Manufacturing Service Providers:Foxconn and Jabil manage component procurement and assembly for brand owners, consolidating semiconductor demand across multiple product lines.
- System Integrators:Industrial and enterprise IT integrators specify semiconductor content within subsystem designs.
- Research Institutes:CERN, MIT, and similar institutions prototype novel device architectures through multi-project wafer services.
Procurement leverage concentrates with OEMs; Research Institutes generate the most experimental architecture demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced-node logic and memory concentrates in Taiwan, South Korea, and the United States, while automotive electrification and AI infrastructure build-out pull silicon carbide and high-bandwidth memory into supply-constrained allocation queues across fabrication clusters.
United States
Hyperscale data center operators in Virginia and Oregon are consolidating accelerator procurement through direct foundry relationships. EPA regulations on fluorinated greenhouse gases constrain etching chemistry choices in domestic fabrication, raising process conversion costs for facilities in Arizona and Texas. TSMC Arizona and Intel Corporation anchor advanced-node capacity expansion in the Phoenix and Hillsboro metro areas.
Taiwan
Advanced-node foundry capacity for 3nm and below logic concentrates on the island, serving AI accelerator and smartphone application processor demand. The region operates under export control coordination between the US Department of Commerce and allied regulators that reshapes equipment sourcing and customer access. Hsinchu Science Park anchors the densest cluster of EUV lithography and advanced packaging capacity globally.
South Korea
Memory chip producers are pulling capacity expansion from commodity DRAM toward HBM3E generations for AI training clusters. The country's national industrial regulator supports domestic fabrication through targeted investment frameworks. Samsung Electronics and SK Hynix anchor production complexes in Pyeongtaek and Icheon, where 3D NAND and high-bandwidth memory stacks are manufactured.
Japan
Automotive OEMs and industrial equipment manufacturers source analog ICs and power semiconductors from domestic suppliers. METI directs capital toward mature-node and specialty production through subsidy programs aligned with economic security objectives. Kumamoto and Hiroshima host expanding 300mm wafer facilities serving automotive microcontroller and image sensor demand.
Germany
Automotive OEMs in Munich and Stuttgart are qualifying 800-volt battery platforms, accelerating silicon carbide MOSFET adoption for traction inverters. REACH compliance mandates material disclosure across complex semiconductor supply chains, forcing substitution of certain flame retardants in encapsulation materials. Dresden anchors the Saxony semiconductor cluster where automotive power semiconductor and sensor production concentrates.
Global Semiconductor Device Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty substrates and photonic integration. The market structure consolidates around advanced-node foundries and integrated device manufacturers with captive fabrication, while memory and power semiconductor segments support mid-scale specialists. Three archetypes dominate: pure-play foundries with process leadership, integrated device manufacturers competing for external customers, and memory specialists with commodity and high-bandwidth product lines. Capacity reservation agreements and direct OEM-foundry relationships represent the dominant competitive moves, alongside geographic diversification of fabrication footprints.
Within the integrated device manufacturer tier, Intel Corporation and Samsung Electronics exemplify the transition toward foundry service models. Nvidia Corporation occupies a position as an architecture licensor and accelerator designer without captive fabrication. Among memory specialists, SK Hynix and Micron Technology represent the HBM3E capacity expansion race. These three anchors illustrate how competitive positioning diverges between fabrication-heavy and design-heavy business models.
| Leading Market Players |
|---|
| Intel Corporation |
| Nvidia Corporation |
| TSMC |
| Samsung Electronics |
| Qualcomm Incorporated |
| Texas Instruments |
| SK Hynix |
| Micron Technology |
| Broadcom |
| Others |
Supply & Pricing Matrix
EUV lithography specialists in Hsinchu and Hillsboro command compensation premiums that widen spreads between leading-edge and trailing-node wafer pricing. Labor-cost differentials between Taiwan, South Korea, and the United States amplify tier stratification across mature-node commodity production and advanced-logic premium sockets.
Pricing Analysis
Volume concentrates in commodity DRAM and mature-node microcontrollers where margins compress under cyclical oversupply, while pricing power accumulates in HBM3E and 3nm logic where CoWoS bottlenecks sustain premiums. Three-tier pricing structure across automotive-grade, industrial-temperature, and consumer-commercial qualification levels reflects certification investment recovery. Cost compression in mature-node 200mm production is intensifying because Chinese foundries expand capacity without equivalent equipment depreciation burdens. Automotive OEMs exhibit lowest price sensitivity given functional safety certification requirements, whereas consumer electronics brands arbitrage aggressively across second-source qualified vendors.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers including JSR and Shin-Etsu, with EUV-grade formulations sourcing from single-qualified facilities in Ibaraki and Kanagawa. Advanced-node fabrication draws from neon gas purification in Ukraine and Russia, high-purity silicon from Germany and the United States, and photomask blanks from Japan. Single-source vulnerability concentrates in EUV pellicle production where Dutch and Japanese suppliers hold process exclusivity. Distribution runs through direct foundry relationships with hyperscale operators and automotive OEMs, bypassing traditional semiconductor distributors for advanced logic and memory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a substrate-transition phase as silicon carbide displaces silicon IGBTs in traction inverters above 400 volts. Legacy silicon power semiconductor capacity faces stranded asset risk as automotive platforms standardize on 800-volt architectures.
For Market Incumbents: Lock in wafer start commitments at TSMC Arizona and Samsung Texas through multi-year offtake agreements that freeze pricing against foundry cost inflation. Defend margin position by accelerating in-house production of silicon carbide substrates at 150mm and 200mm diameters, reducing dependence on Wolfspeed and Coherent supply allocations threatened by automotive qualification backlogs.
For New Entrants and Emerging Players: OSAT partners in India and Vietnam offer assembly and test capacity without the capital intensity of captive fabrication. Edge-AI inference modules for industrial automation represent the most penetrable white-space target, with design wins available through direct engagement with German and Japanese equipment manufacturers rather than competing for cloud accelerator sockets dominated by incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with photonic integration specialists given co-packaged optics deployment at Virginia and Oregon data centers. Long-term viability favors companies with demonstrated packaging roadmaps converging silicon photonics with CMOS logic. Watch hyperscale capex guidance revisions as the inflection indicator for AI accelerator demand cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Agreements | Direct wafer commitments at TSMC Arizona secure allocation priority against automotive and AI demand surges. |
| Silicon Carbide Substrate Integration | Backward integration into 200mm SiC crystal growth reduces reliance on Wolfspeed and Coherent supply allocations. |
| Co-Packaged Optics Development | Photonic integration with CMOS logic addresses power consumption constraints at Virginia and Oregon data centers. |
| Edge-AI Accelerator Design Wins | Low-power neural processors target underpenetrated industrial endpoints in Germany and Japan automation markets. |
| Geographic Diversification of OSAT Footprint | India PLI scheme incentives attract assembly and test investment away from China concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this semiconductor device market assessment. Primary interviews with foundry operations executives, automotive Tier 1 procurement directors, hyperscale infrastructure planners, and EUV equipment specialists combined with SEC 10-K disclosures, SEMI silicon shipment reports, and national customs wafer import records. Bottom-up die shipment estimates by node and application triangulated against top-down foundry revenue and capex disclosures.
Segment-level modeling operated at technology-node granularity for logic and memory, substrate material for power semiconductors, and packaging format for advanced integration. CAGRs derived from supply-demand balance analysis across the projection horizon, with capacity expansion schedules, yield learning curves, and equipment delivery lead times as semiconductor-specific forecast inputs. Regional splits reflected known fab construction timelines and subsidy program disbursement patterns.
Caveats apply where neon supply disruption, export control expansion, or foundry yield misses could materially shift the outlook. Forecasts embed assumptions about EUV scanner delivery schedules and automotive platform voltage standardization trajectories. A small set of named triggers—hyperscale capex guidance, CHIPS Act disbursement velocity, and SiC substrate qualification timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market