
 Singapore Gaming Gadgets Market | 2026-2036
Singapore Gaming Gadgets Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Gaming Gadgets Market Insights
Multi-source component procurement is hardening across Singapore's gaming gadget supply chain as brands diversify beyond single foundry relationships. Razer Inc. leverages its Singapore headquarters to sustain regional distribution control over Southeast Asian markets. Logitech International S.A. anchors its premium peripheral positioning through sustained investment in wireless latency reduction technologies. SteelSeries competes aggressively in the esports sponsorship channel, securing team partnerships that reinforce brand visibility among competitive players.
Gaming gadgets encompass dedicated electronic hardware engineered for interactive entertainment, typically featuring sub-1ms input response protocols, mechanical or optical switch architectures, and ergonomic form factors optimized for extended session durability. Accessories and VR Headsets command expanding margin pools as Singaporean consumers prioritize immersive fidelity and haptic feedback depth over base console purchases. Cloud Gaming infrastructure requirements are reshaping hardware specifications, with peripherals now requiring low-latency synchronization to streaming endpoints rather than local processing units. The End User segmentation reveals Competitive Players and Streaming Influencers as the most specification-sensitive buyer cohorts, driving premium average selling prices for broadcast-grade audio and capture equipment.
IMDA's equipment registration framework and the country's national cybersecurity certification standards constrain market access for uncertified wireless devices, compelling manufacturers to pre-validate radio frequency emissions and data encryption protocols. The country's central bank, MAS, oversees payment infrastructure rules that affect in-game transaction hardware and digital wallet integrations embedded in gaming ecosystems. Stakeholders must monitor how Singapore's evolving personal data protection obligations intersect with cloud gaming telemetry collection, as this regulatory boundary will determine permissible feature sets for next-generation peripherals and streaming accessories.
Market Dynamics
Cloud gaming infrastructure is compressing peripheral specification cycles as Singaporean manufacturers retool hardware for streaming synchronization rather than local compute latency benchmarks.
Growth Catalysts
- IMDA Equipment Registration:Mandatory pre-certification of radio frequency emissions creates quality floor that filters low-grade competitors and elevates trusted brand positioning among specification-sensitive buyers.
- Esports Arena Construction:Purpose-built competitive venues in Singapore's central business district generate concentrated procurement demand for broadcast-grade peripherals and capture hardware.
- Optical Switch Architecture:Sub-1ms response protocols are displacing mechanical alternatives in premium peripheral tiers, driving replacement cycles among competitive players seeking marginal performance gains.
Market Restraints
- Multi-Foundry Component Sourcing:Semiconductor supply diversification raises procurement complexity and extends qualification timelines for new peripheral designs.
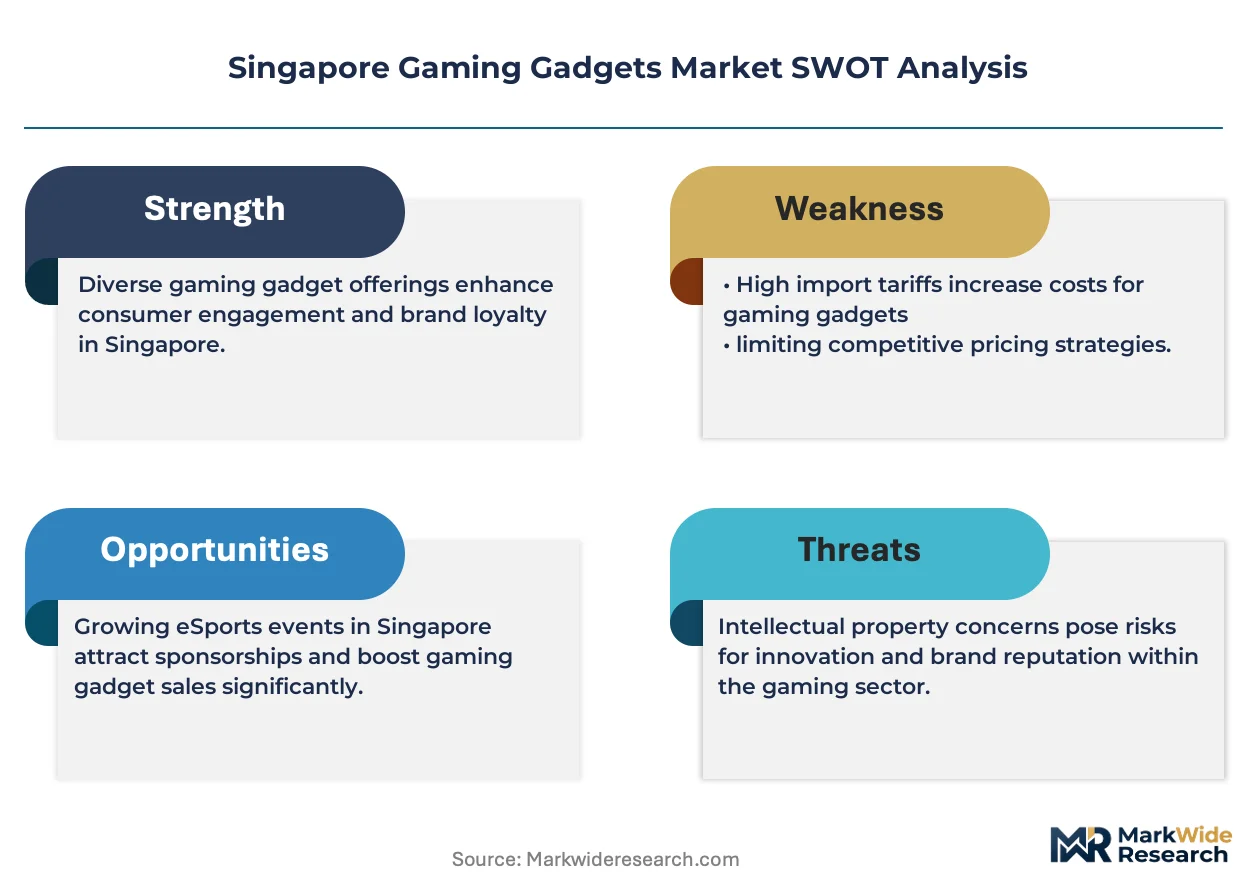
- MAS Payment Infrastructure Rules:Central bank oversight of in-game transaction hardware constrains feature integration for wallet-embedded gaming ecosystems.
- Wireless Latency Floor:Radio frequency physics limits current generation wireless peripherals from matching wired response consistency in tournament conditions.
Strategic Opportunities
- VR Headset Margin Expansion:Immersive fidelity prioritization among Singaporean consumers opens premium positioning for haptic feedback peripherals beyond base console economics.
- Streaming Influencer Channel:Broadcast-grade audio and capture equipment demand from content creators represents underpenetrated vertical with sustained ASP elevation potential.
- Personal Data Protection Alignment:Evolving telemetry collection regulations create first-mover advantage for peripherals with privacy-by-design architectures.
Industry Challenges
- Certification Timeline Compression:IMDA cybersecurity validation requirements extend product launch windows, compressing revenue realization against rapid specification turnover.
- Legacy Peripheral Integration:Cloud gaming synchronization protocols demand firmware architecture incompatible with installed base hardware, stranding existing consumer investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Gaming Gadgets Market |
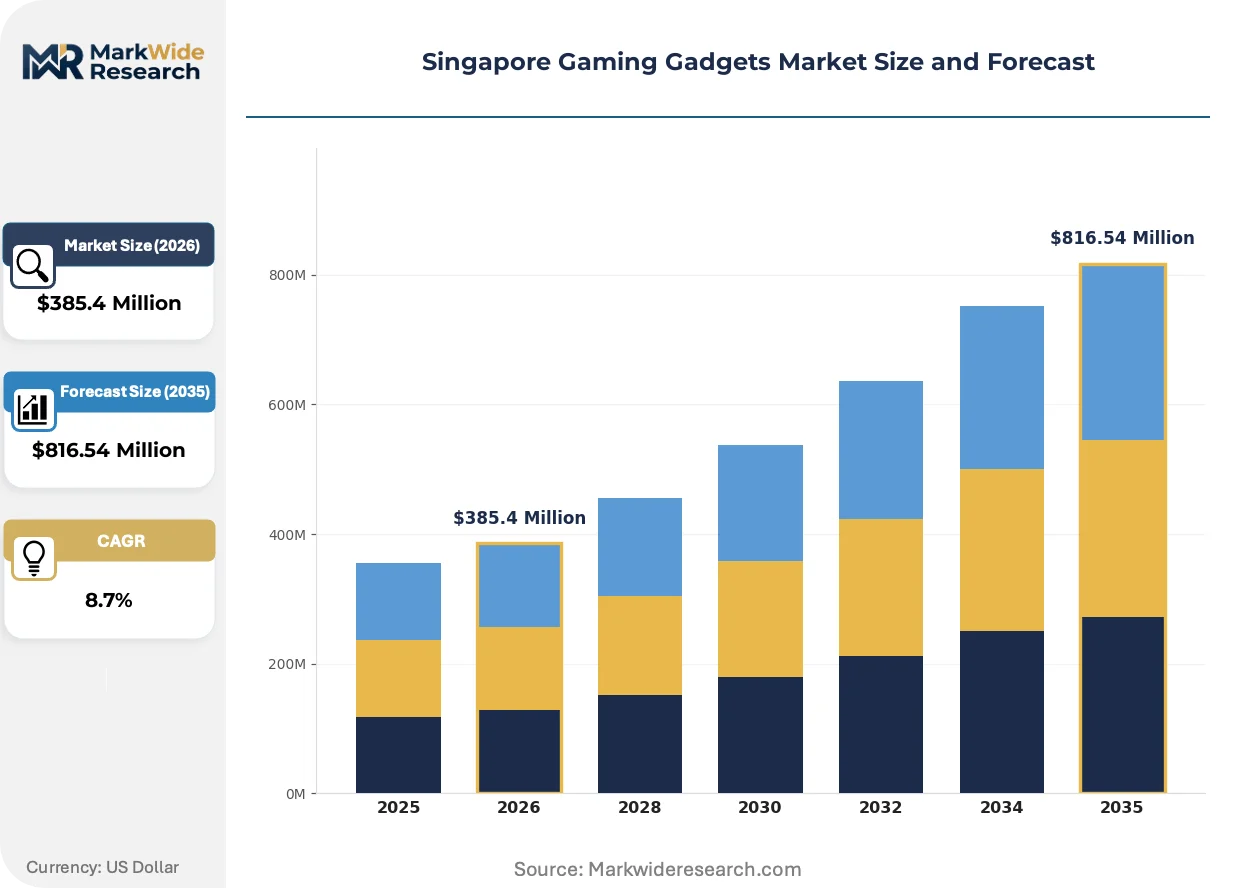
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consoles, Handhelds, Accessories, VR Headsets Technology: Cloud Gaming, Mobile Gaming, Augmented Reality, E-Sports End User: Casual Gamers, Competitive Players, Streaming Influencers, Educational Institutions Distribution Channel: Online Retail, Physical Stores, Gaming Events, Direct Sales |
| Companies Covered | Razer Inc., SteelSeries, Logitech International S.A., Corsair Gaming Inc., HyperX, Turtle Beach Corporation, Sony Group Corporation, Nintendo Co. Ltd., ASUS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Gaming Gadgets Market Trends and Innovations
Hardware specification cycles are accelerating as streaming infrastructure demands reshape peripheral design priorities away from local processing benchmarks toward network-synchronized performance metrics.
Optical switch technology is rewriting competitive peripheral standards by eliminating mechanical debounce delay through infrared beam interruption detection. Tournament-grade mouse and keyboard manufacturers are adopting this architecture at accelerating pace. The shift is compressing product lifecycles for mechanical switch incumbents while enabling sub-0.2ms response claims that command premium positioning.
Singapore's national cybersecurity certification standards are mandating encryption protocol validation for all wireless gaming peripherals prior to market entry. Hardware vendors must pre-submit radio frequency emission profiles and data transmission security documentation. Streaming accessories with embedded capture and cloud upload functions face the most stringent review timelines, reshaping product roadmaps toward compliance-first development sequences.
Competitive players are consolidating purchase authority through team procurement contracts rather than individual retail acquisition. Esports organizations now negotiate volume agreements directly with peripheral manufacturers, displacing traditional distributor relationships. This concentration is most visible in Singapore's central business district gaming lounges, where facility-wide standardization on single vendor ecosystems reduces training overhead and spare parts complexity.
Singapore Gaming Gadgets Market Segmentation
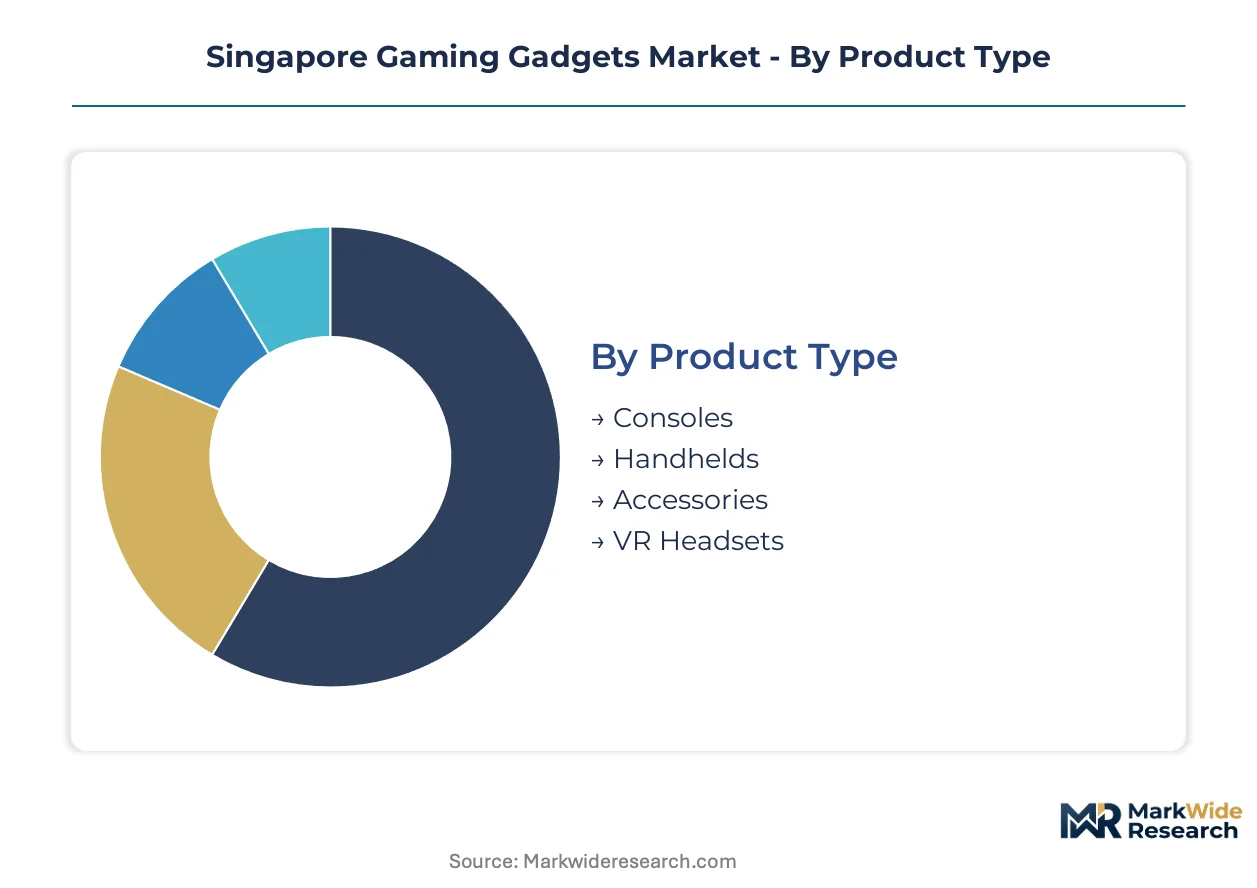
Segmentation in Singapore's gaming gadgets market reveals how hardware specifications, connectivity protocols, and buyer sophistication stratify across distinct commercial channels. Understanding these divides allows manufacturers to align certification investments, distribution partnerships, and feature roadmaps with the most specification-sensitive buyer cohorts.
Product Type:
Accessories and VR Headsets command premium positioning through haptic depth and immersive fidelity, while consoles and handhelds compete on volume throughput in retail channels.
- Accessories:Dedicated peripherals featuring sub-1ms input response protocols and optical switch architectures. Demand concentrates in Singapore's central business district gaming lounges and esports arenas, where facility-wide standardization reduces training overhead and spare parts complexity.
- VR Headsets:Immersive hardware engineered for spatial computing with embedded haptic feedback systems. Singaporean consumers prioritize immersive fidelity over base console purchases, opening margin expansion opportunities for premium positioning beyond traditional gaming economics.
- Consoles:Integrated gaming systems with local processing units. Retail volume flows through online channels and physical store networks serving casual gamer demographics.
- Handhelds:Portable gaming devices optimized for mobile session durability. Cloud gaming infrastructure requirements are reshaping specifications toward low-latency synchronization with streaming endpoints.
Mature deployment sits with Consoles. Newer deployment is concentrated in VR Headsets.
Technology:
Cloud Gaming and E-Sports are compressing peripheral specification cycles, while Mobile Gaming and Augmented Reality expand addressable user bases through accessibility and spatial computing applications.
- Cloud Gaming:Streaming infrastructure demanding peripherals with low-latency synchronization to remote processing units rather than local compute benchmarks. IMDA's equipment registration framework constrains market access for uncertified wireless devices, compelling manufacturers to pre-validate radio frequency emissions.
- E-Sports:Competitive gaming protocols requiring tournament-grade response consistency. Optical switch technology is displacing mechanical alternatives through sub-0.2ms response claims that command premium positioning among specification-sensitive buyers.
- Mobile Gaming:Smartphone-optimized interactive entertainment with embedded controller peripherals. Accessibility expands addressable demographics beyond dedicated hardware purchasers.
- Augmented Reality:Spatial computing overlays blending digital content with physical environments. Singapore's national cybersecurity certification standards mandate encryption protocol validation prior to market entry.
Revenue concentration aligns with E-Sports procurement contracts. Steepest expansion trajectory belongs to Cloud Gaming.
End User:
Competitive Players and Streaming Influencers drive premium average selling prices through broadcast-grade requirements, while Casual Gamers and Educational Institutions anchor volume throughput.
- Competitive Players:Specification-sensitive buyers seeking marginal performance gains through sub-1ms response protocols. Esports organizations negotiate volume agreements directly with peripheral manufacturers, displacing traditional distributor relationships in Singapore's central business district venues.
- Streaming Influencers:Content creators demanding broadcast-grade audio and capture equipment. This underpenetrated vertical offers sustained ASP elevation potential as procurement concentrates through team and agency contracts.
- Casual Gamers:Recreational users prioritizing accessibility over performance specifications. Volume flows through retail and online channels with lower certification burden.
- Educational Institutions:Structured gaming programs requiring durable hardware for extended session use. Procurement cycles align with academic budgeting timelines.
Procurement authority is consolidating with Competitive Players. Emerging demand concentration is visible in Streaming Influencers.
Distribution Channel:
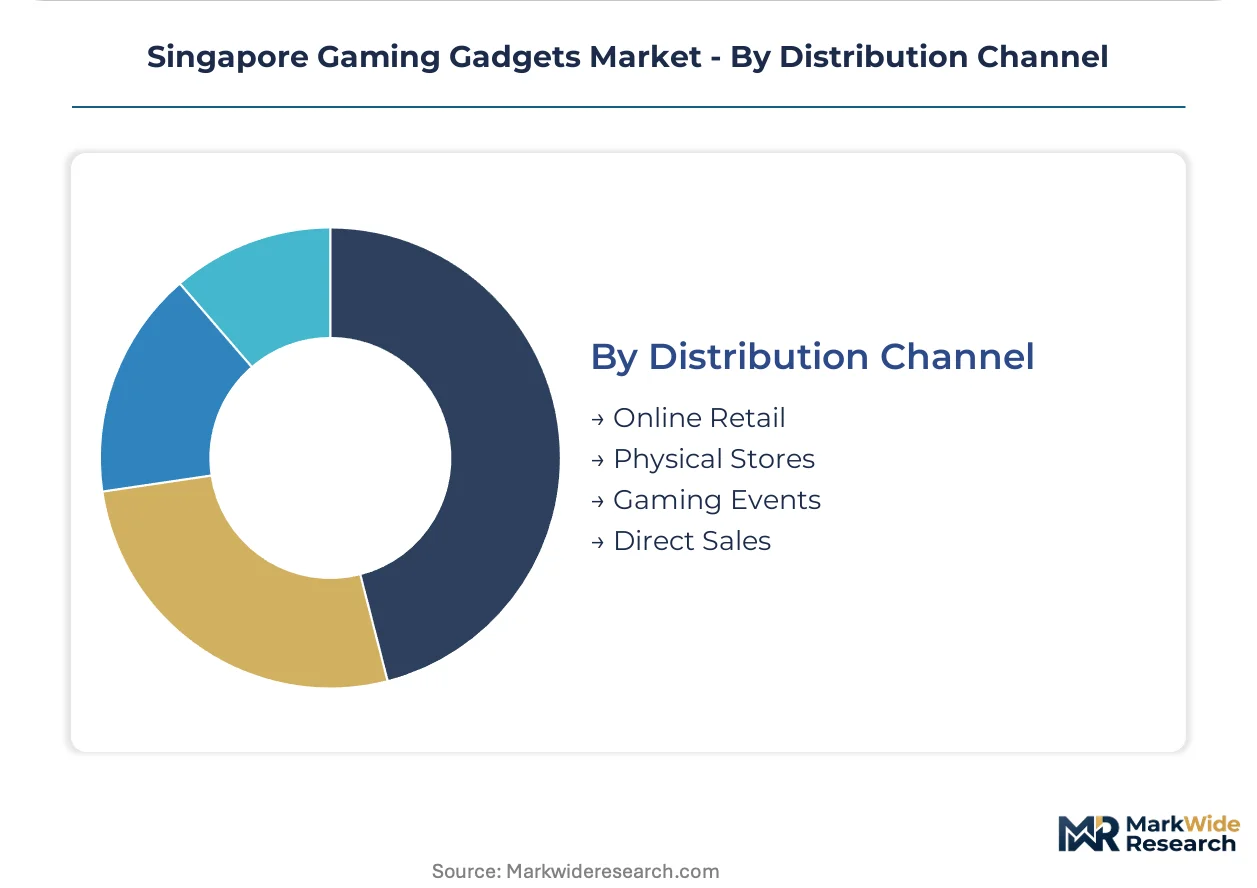
Online Retail and Physical Stores handle volume throughput, while Gaming Events and Direct Sales capture premium positioning through experiential engagement and organizational procurement.
- Online Retail:Digital commerce platforms serving dispersed consumer geography with rapid fulfillment. MAS payment infrastructure rules affect in-game transaction hardware and digital wallet integrations embedded in gaming ecosystems.
- Gaming Events:Tournament and exhibition venues enabling experiential product demonstration. Singapore's esports arena construction generates concentrated procurement demand for broadcast-grade peripherals.
- Physical Stores:Brick-and-mortar retail networks offering tactile evaluation before purchase. Casual gamer demographics rely on immediate availability and staff guidance.
- Direct Sales:Manufacturer-to-organization contracts bypassing distributor markup. Esports teams and gaming lounges in the central business district standardize on single vendor ecosystems through these channels.
Volume scale sits with Online Retail. Margin capture is concentrating in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication capacity in Southeast Asia anchors the regional gaming hardware supply chain, with Singapore's advanced packaging facilities serving as the critical node for peripheral component validation and regional distribution routing.
Central Region
Marina Bay and the central business district concentrate Singapore's esports arena construction, driving facility-wide procurement contracts for broadcast-grade peripherals. IMDA's equipment registration framework mandates pre-certification of radio frequency emissions for all wireless devices entering these venues. Gaming lounges along Orchard Road standardize on single-vendor ecosystems to reduce training overhead and spare parts complexity.
East Region
Changi and Tampines host logistics hubs that route Southeast Asian distribution for regional headquarters operations. The country's cybersecurity certification standards require encryption protocol validation prior to customs clearance. Peripheral manufacturers locate regional compliance laboratories here to compress IMDA validation timelines for new product launches.
West Region
Jurong and Tuas anchor advanced manufacturing and semiconductor packaging facilities supporting gaming gadget component supply. MAS payment infrastructure rules affect in-game transaction hardware development for wallet-embedded ecosystems. Research partnerships between hardware vendors and local institutes concentrate here, focusing on wireless latency reduction technologies.
North Region
Woodlands and Yishun serve as residential catchments with growing demand from casual gamers accessing online retail channels. The personal data protection framework intersects with cloud gaming telemetry collection requirements, shaping permissible feature sets for peripherals sold into these demographics. Last-mile fulfillment centers for gaming hardware concentrate along the North-South corridor.
Singapore Gaming Gadgets Market Competitive Landscape
Global majors compete with regional champions across distribution architecture and certification velocity. Singapore's market structure shows moderate consolidation around headquarters-advantaged players with direct IMDA relationship access. Three archetypes dominate: integrated peripheral-stack vendors, audio-capture specialists, and console ecosystem anchors. Competitive moves concentrate on esports sponsorship contracting and firmware architecture differentiation for cloud synchronization protocols.
Within the headquarters-advantaged tier, Razer Inc. and Logitech International S.A. exemplify players leveraging Singapore-based operations to compress regional distribution timelines and sustain IMDA certification priority. SteelSeries occupies a position representing the audio-capture specialist archetype competing through team procurement channel penetration. These three names anchor the competitive set visible in current market dynamics, with each exemplifying distinct strategic positioning around regulatory relationship depth, technology licensing architecture, or sponsorship-driven brand visibility.
| Leading Market Players |
|---|
| Razer Inc. |
| SteelSeries |
| Logitech International S.A. |
| Corsair Gaming Inc. |
| HyperX |
| Turtle Beach Corporation |
| Sony Group Corporation |
| Nintendo Co. Ltd. |
| ASUS |
| Others |
Pricing and Supply Chain Analysis
Optical switch architecture migration is simultaneously compressing mechanical switch margins and concentrating procurement authority among esports organizations with volume negotiating leverage. IMDA certification timelines add fixed compliance costs that filter low-grade competitors while elevating trusted brand positioning among specification-sensitive buyers in Singapore's central business district venues.
Pricing Analysis
Warranty and firmware update bundling separates premium peripheral tiers from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and optical switch performance claims. Price differentiation hinges on IMDA pre-validation status and sub-1ms response protocol verification. Cost compression in the economy tier is intensifying because mechanical switch incumbents face replacement cycle acceleration. Casual gamers accessing online retail channels exhibit highest price sensitivity, while esports organizations demonstrate lowest sensitivity due to team procurement contract structures.
Supply Chain Analysis
Dual-sourcing mandates from Singapore-based esports organizations require peripheral manufacturers to qualify components across Taiwan, South Korea, and China foundries. Semiconductor supply draws from Taiwanese advanced packaging, South Korean memory fabrication, and Chinese PCB assembly. Single-source vulnerability concentrates in optical sensor die supply. Distribution runs through Changi logistics hubs for Southeast Asian regional routing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's gaming gadgets market sits in a technology-transition phase where optical switch architectures displace mechanical alternatives and cloud gaming synchronization protocols reshape firmware development priorities.
For Market Incumbents: Lock in esports organization procurement contracts through facility-wide standardization agreements that reduce competitor access to Singapore's central business district gaming lounges. Invest in IMDA certification velocity to compress launch windows against rapid specification turnover. Threat of emerging audio-capture specialists penetrating the streaming influencer channel demands defensive sponsorship contracting. For New Entrants and Emerging Players: Esports arena construction contractors represent the most penetrable channel partner type for bypassing established distributor relationships. Target white-space in broadcast-grade capture equipment for streaming influencers, where team procurement contracts remain underpenetrated. Pursue privacy-by-design architectures as first-mover differentiation against evolving personal data protection obligations. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated peripheral-stack vendors seeking optical switch technology licensing or IMDA relationship depth. Long-term viability favors targets with demonstrated esports sponsorship ROI and cloud gaming firmware architecture capabilities. Signal to monitor: IMDA cybersecurity validation timeline compression rates as inflection indicator for certification-advantaged players.| Strategic Initiative | Industry Significance |
|---|---|
| Esports Sponsorship Contracting | Team procurement agreements displace traditional distributor relationships in Singapore's central business district venues. |
| IMDA Certification Investment | Pre-validation priority compresses launch windows against rapid optical switch specification turnover. |
| Optical Switch Technology Licensing | Sub-0.2ms response claims command premium positioning among specification-sensitive competitive players. |
| Privacy-by-Design Architecture | Evolving personal data protection obligations create first-mover advantage for telemetry-compliant peripherals. |
| Cloud Gaming Firmware Development | Low-latency synchronization protocols reshape hardware specifications away from local compute benchmarks. |
Research Methodology
Trade databases, IMDA equipment registration filings, and esports arena procurement records formed the secondary backbone for supply chain mapping and certification timeline analysis. Primary interviews with peripheral manufacturer product managers, esports organization procurement leads, gaming lounge facility operators, and IMDA compliance officers validated specification sensitivity patterns. Bottom-up demand estimation across end-user segments triangulated against top-down market sizing from distribution channel data.
Historical trendline analysis of peripheral replacement cycles and optical switch adoption curves anchored the projection framework. Segmentation modeling spanned product type, technology architecture, end-user sophistication, and distribution channel across the analysis window. CAGR derivation incorporated IMDA regulatory velocity assumptions and cloud gaming infrastructure deployment trajectories. Forecast inputs included esports arena construction pipelines and streaming influencer demographic expansion rates.
Caveats apply where IMDA cybersecurity validation timeline extensions or optical switch supply disruptions could materially shift the outlook. Forecasts reflect assumptions on esports sponsorship contract concentration and cloud gaming synchronization protocol standardization. Deviation in IMDA equipment registration backlog accumulation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Tarot Cards Market
Gaming
Shooter Game Market
Gaming
GCC Gaming Headsets Market
Gaming
Mobile Game Controller Market
Gaming
Playstation Network (PSN) Market
Gaming
Gaming Chair Market
Gaming
Global NFT Gaming Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
VR Racing Gaming Market
Gaming
VR Melee Games Market
Gaming
Animation, VFX & Game Market
Gaming
Southeast Asia Gaming Market
Gaming
Traditional Casual Games Market
Gaming
India Gaming Market
Gaming
Global Game Testing Service Market
Gaming
Game API Market