
 Game Engine Management Market | 2026-2036
Game Engine Management Market Size, Share, and Industry Trends Forecast 2026-2036
Game Engine Management Market Foresight
Enterprise training departments is rotating toward managed game engine infrastructure as defense contractors and healthcare simulation labs expand procurement. Epic Games anchors its position through Unreal Engine's dominance in photorealistic rendering pipelines for non-gaming verticals. Unity Technologies competes aggressively on cross-platform deployment tools that reduce porting overhead for mobile-first studios. Tencent extends its influence through strategic investments in middleware providers across Southeast Asian developer ecosystems.
Game Engine Management encompasses the orchestration, optimization, and lifecycle governance of real-time 3D engines used to render interactive environments, typically requiring GPU cluster coordination, asset pipeline automation, and frame-rate benchmarking across target hardware profiles. Cloud-Based deployment leads the solution architecture as studios abandon capital-intensive render farm ownership in favor of elastic compute consumption models. Real-Time Rendering commands the largest solution offering revenue pool, while Performance Optimization tools are capturing the fastest expansion as live-service games demand continuous latency reduction across geographically distributed player bases.
FCC guidelines on broadband infrastructure quality indirectly shape engine streaming performance requirements for US-based platforms, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European deployments of AI-assisted asset generation tools. China's MIIT enforces domestic cloud localization standards that fragment cross-border engine service architectures. Stakeholders must monitor how divergent data sovereignty frameworks fragment global engine service delivery models and force region-specific compliance investments.
Market Dynamics
Cloud rendering mandates under the EU AI Act and emerging digital content standards are compressing engine service delivery timelines while fragmenting compliance architectures across sovereign jurisdictions.
Growth Catalysts
- Live-service game architectures:Continuous content delivery models require elastic GPU cluster orchestration that managed engine services provide at scale.
- GDPR and EU AI Act data residency rules:European deployments of AI-assisted asset generation tools create demand for region-specific engine infrastructure.
- Defense contractor simulation procurement:Enterprise training departments in the United States are expanding managed engine infrastructure for mission-critical visualization systems.
Market Restraints
- GPU supply concentration:Taiwan and South Korea dominate advanced semiconductor fabrication, creating single-point-of-failure risk for render cluster provisioning.
- MIIT cloud localization mandates:China's domestic data sovereignty requirements fragment cross-border engine service architectures and duplicate infrastructure costs.
- Proprietary shader compilation:Vendor-locked graphics pipelines limit interoperability and inflate porting overhead for multi-engine studios.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentivized domestic cloud infrastructure buildout creates localized engine service nodes for South Asian developer ecosystems.
- Neural radiance fields (NeRF) convergence with real-time ray tracing:Hybrid reconstruction pipelines enable photorealistic environment generation without manual asset production.
- Subscription-based middleware licensing:Revenue predictability attracts private equity capital to consolidate fragmented tool vendors.
Industry Challenges
- Graphics programmer scarcity:Specialized shader optimization and compute shader expertise commands premium compensation that mid-tier studios cannot match.
- Multi-jurisdiction certification timelines:FCC broadband quality guidelines, GDPR algorithmic transparency, and MIIT localization standards create overlapping compliance sprints.
- Legacy engine version fragmentation:Long-tail support obligations for deprecated API versions drain engineering resources from next-generation feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Game Engine Management Market |
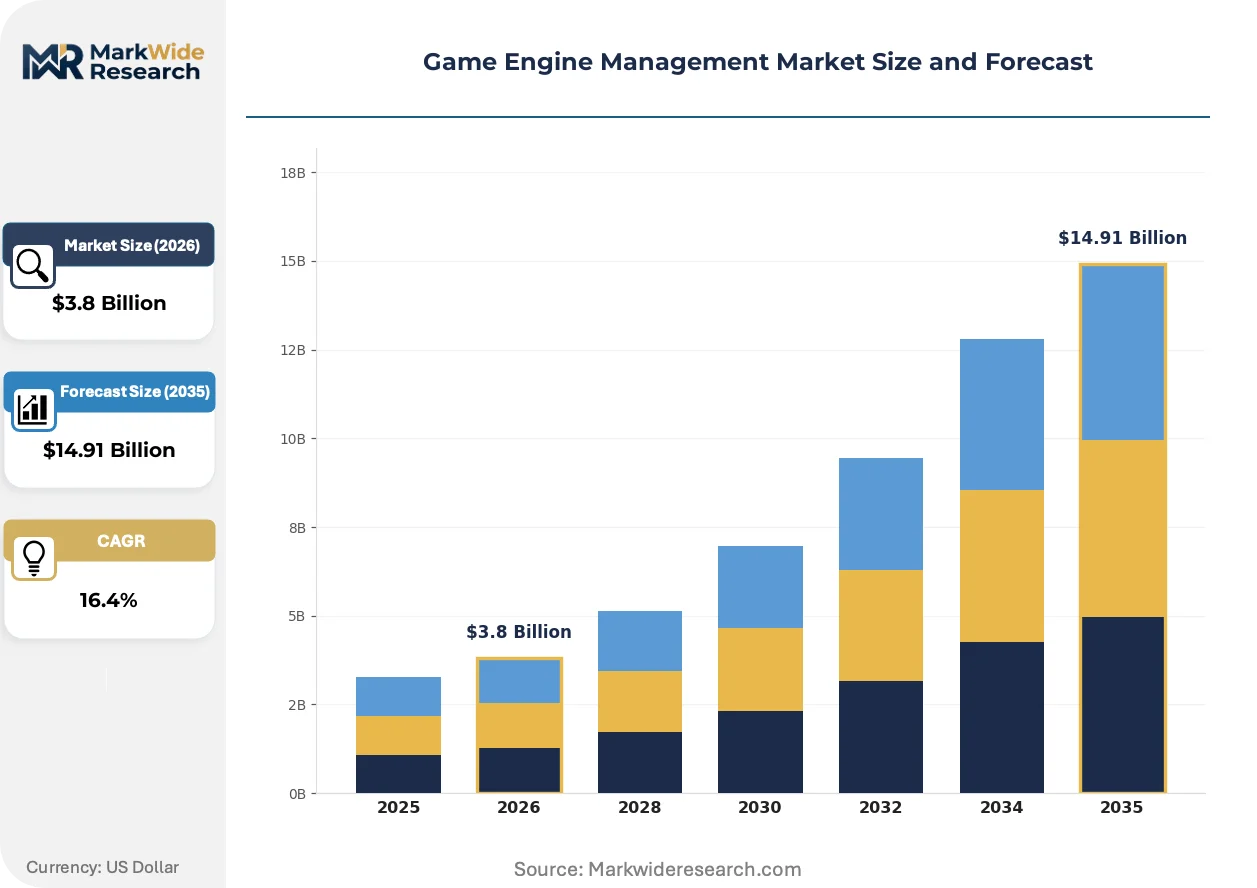
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Real-Time Rendering, Asset Management, Performance Optimization, Collaboration Tools, Analytics Application: Video Games, Simulation Training, Virtual Reality, Augmented Reality, Interactive Media End User: Game Developers, Training Providers, Content Creators, Educational Institutions |
| Companies Covered | Microsoft, Tencent, Epic Games, Take-Two Interactive, Roblox Corporation, Unity Technologies, Sony Interactive Entertainment, Iron Galaxy Studios, Electronic Arts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Game Engine Management Market Shifts & Advancements
Neural rendering techniques and sovereign cloud architectures are compressing traditional asset production pipelines while redrawing competitive boundaries between engine providers.
Neural radiance field (NeRF) reconstruction is supplanting conventional photogrammetry workflows in environment capture pipelines. Automotive design studios and architectural visualization firms are adopting NeRF-based scene generation to reduce location shoot costs. This compression of physical production requirements is enabling smaller teams to deliver cinematic fidelity without capital-intensive stage builds.
The EU AI Act's algorithmic transparency obligations are forcing disclosure of training data provenance for generative texture and mesh tools. Engine providers must now document dataset composition and consent chains for AI-assisted asset pipelines. European deployments face the strictest audit requirements, with some studios pre-emptively segregating generative workflows by jurisdiction.
Consumption of engine services is fragmenting from perpetual licenses toward metered compute-hour billing tied to actual render farm utilization. Indie studios in California and Washington State are abandoning fixed infrastructure commitments in favor of elastic burst capacity during crunch periods. This behavioral shift concentrates pricing power with hyperscale cloud providers who control underlying GPU allocation.
Game Engine Management Market Segmentation
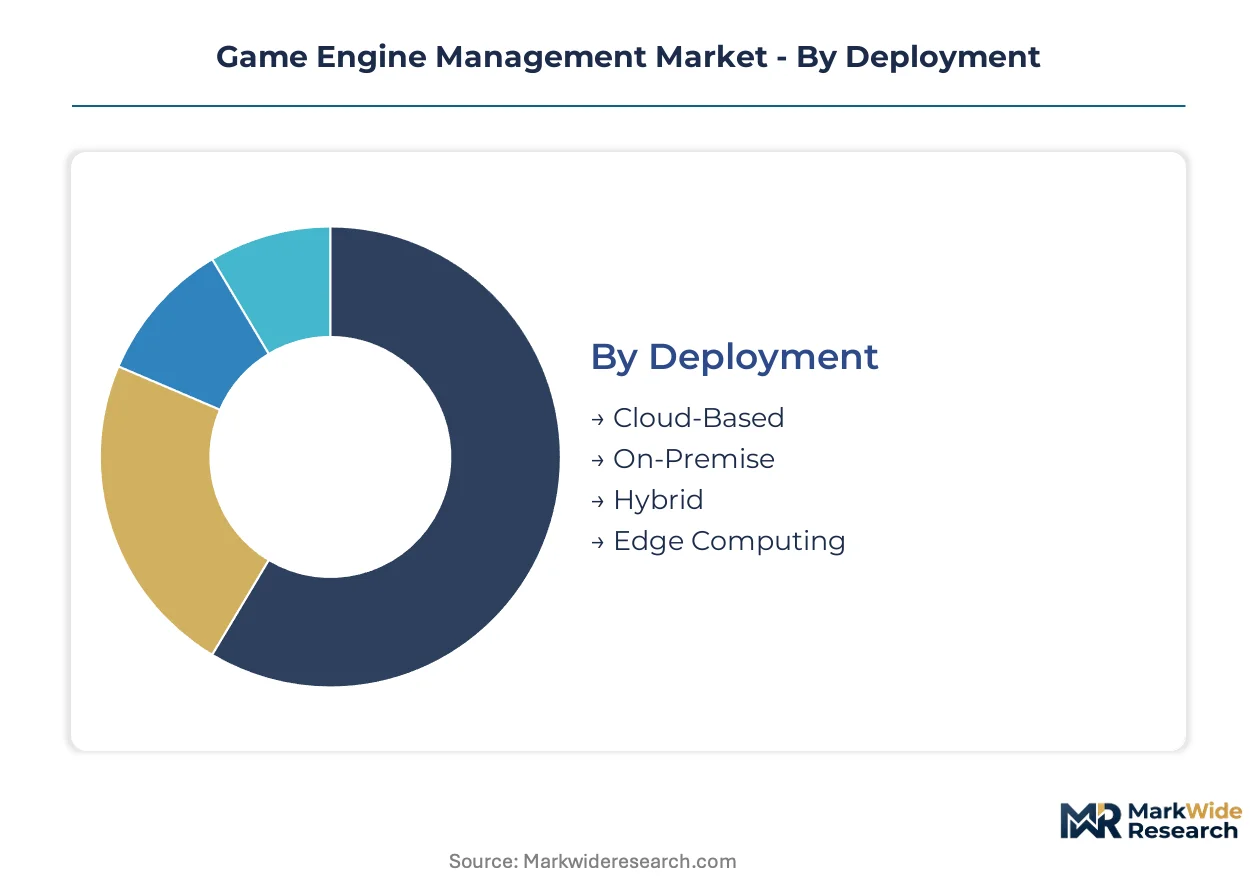
Game engine management services fragment across infrastructure topology, functional capability, and end-use intensity. Segmentation clarity matters because deployment architecture directly determines regulatory exposure under data sovereignty frameworks, while solution specialization shapes GPU utilization economics.
Deployment:
GDPR data residency rules and the EU AI Act's algorithmic transparency mandates create divergent compliance burdens across infrastructure models.
- Cloud-Based:Elastic GPU cluster provisioning eliminates capital-intensive render farm ownership for studios. California and Washington State developer ecosystems concentrate demand here as indie teams abandon fixed infrastructure commitments for metered consumption during crunch periods.
- On-Premise:Captive hardware deployment retains full data control within facility perimeter. Defense contractors and healthcare simulation labs in the United States favor this model for mission-critical visualization systems subject to ITAR and HIPAA constraints.
- Hybrid:Split workloads between local development and burst cloud rendering. China's MIIT localization requirements force this architecture for cross-border studios serving domestic and international markets simultaneously.
- Edge Computing:Distributed nodes minimize latency for location-based AR experiences and multiplayer synchronization. Southeast Asian mobile-first markets drive experimentation here.
Cloud-Based handles the majority of throughput; Edge Computing is gaining share fastest as 5G infrastructure matures.
Solution Offering:
Functional specialization tracks the shift from perpetual licensing toward subscription and consumption-based monetization.
- Real-Time Rendering:Photorealistic pipeline orchestration across ray-traced and rasterized workflows. Automotive design studios and architectural visualization firms in Germany and Japan anchor demand as NeRF reconstruction compresses physical production requirements.
- Performance Optimization:Continuous frame-rate benchmarking and latency reduction for live-service architectures. This segment climbs fastest as geographically distributed player bases demand sub-20ms response times.
- Asset Management:Version control and pipeline automation for 3D model libraries. Mid-tier studios leverage these tools to offset graphics programmer scarcity.
- Collaboration Tools:Real-time co-editing and review workflows for distributed teams. Remote work normalization post-2020 cemented this as standard infrastructure.
- Analytics:Player behavior telemetry and hardware profiling data. GDPR consent chain requirements complicate European deployments of AI-assisted insight generation.
Real-Time Rendering commands the largest revenue pool; Performance Optimization shows the steepest expansion trajectory as service games dominate release calendars.
Application:
Use-case intensity varies dramatically in GPU utilization patterns and content update frequency.
- Video Games:Interactive entertainment spanning AAA production to indie releases. Live-service monetization models in the United States and South Korea drive continuous content delivery demands.
- Simulation Training:Mission-critical visualization for defense, healthcare, and industrial safety. Procurement expansion by US defense contractors and European healthcare labs anchors this segment.
- Virtual Reality:Immersive environment rendering with stringent motion-to-photon latency requirements. Enterprise training departments rotate toward VR for hazardous scenario replication.
- Augmented Reality:Real-world overlay rendering with spatial anchoring. India's PLI-scheme electronics manufacturing incentives support localized cloud nodes for South Asian AR developer ecosystems.
- Interactive Media:Non-linear storytelling and experiential marketing installations. Brand activation budgets in the UAE and Saudi Arabia fuel premium deployment here.
Video Games absorbs the bulk of compute cycles; Simulation Training is expanding most quickly as defense and healthcare procurement accelerates.
End User:
Customer sophistication and procurement authority shape pricing tolerance and support requirements.
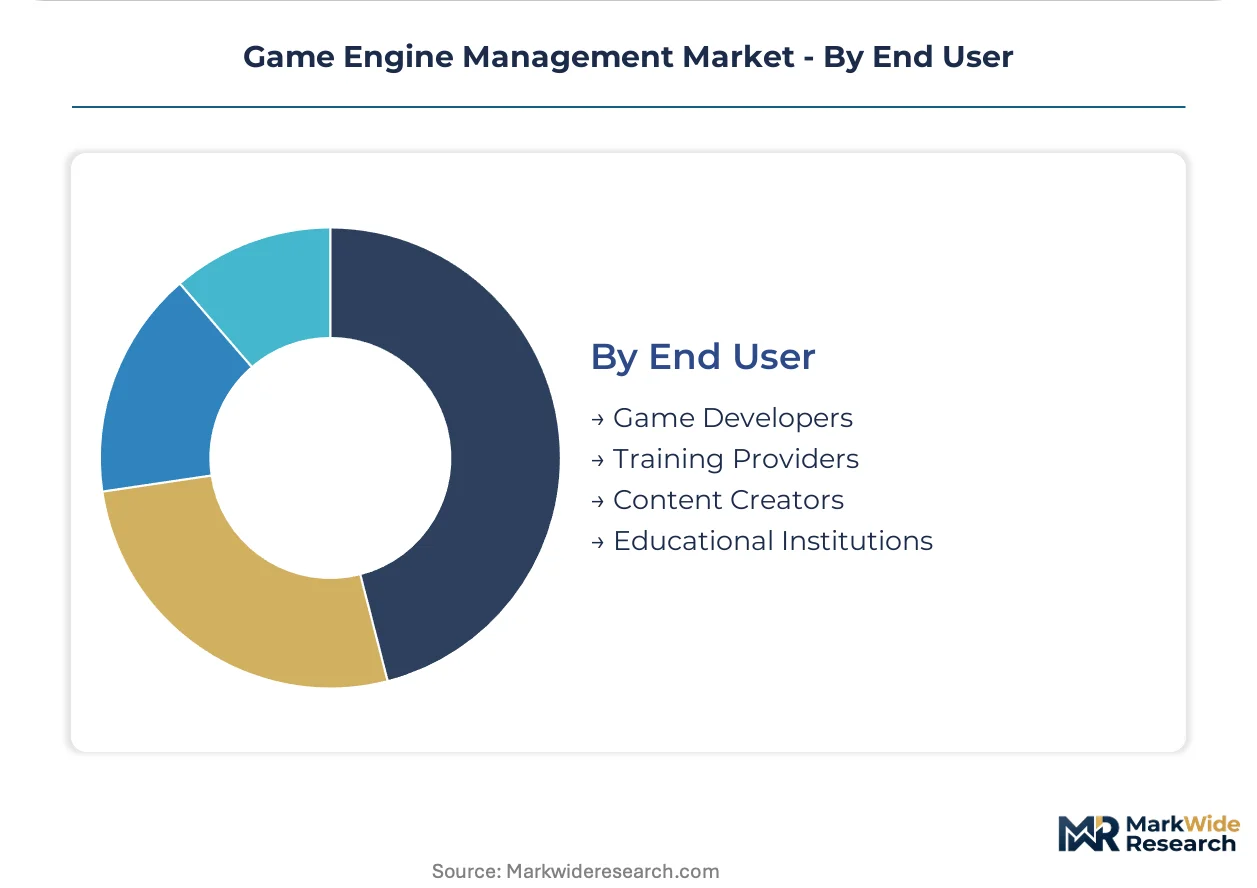
- Game Developers:Studios ranging from solo indie creators to multi-team production houses. California and Washington State clusters concentrate the densest ecosystems of engine technology firms and their customers.
- Training Providers:Corporate L&D departments and specialized simulation vendors. HIPAA and ITAR compliance requirements elevate infrastructure specifications above entertainment use cases.
- Content Creators:Individual artists and small collectives producing real-time 3D assets. Subscription-based middleware licensing attracts this price-sensitive cohort.
- Educational Institutions:University programs and vocational training centers building pipeline talent. EU AI Act disclosure obligations for generative tools complicate curriculum deployment in European institutions.
Game Developers represent the dominant customer volume; Training Providers are climbing fastest as enterprise simulation procurement expands beyond traditional gaming verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landings at Los Angeles and Seattle anchor trans-Pacific data flows that sustain California and Washington State's dominance in cloud-rendered engine services. These fiber optic corridors carry the bulk of GPU cluster traffic between North American developer ecosystems and Asian semiconductor foundries.
United States
Defense contractors in Virginia and Maryland expand procurement of managed engine infrastructure for mission-critical simulation systems. FCC broadband quality guidelines shape streaming performance requirements for US-based platforms. California's Bay Area and Seattle metropolitan clusters concentrate the densest ecosystems of engine technology firms and their developer customers.
China
Domestic cloud providers build localized engine service nodes to serve mobile-first studios across Shenzhen and Chengdu. MIIT enforces data sovereignty standards that fragment cross-border architectures and duplicate infrastructure costs. The Yangtze River Delta and Pearl River Delta regions host the primary concentration of middleware investment and developer talent.
Germany
Automotive design studios in Stuttgart and Munich adopt NeRF-based scene generation to compress physical production requirements. GDPR and the EU AI Act impose algorithmic transparency obligations on AI-assisted asset generation tools. Bavaria's industrial corridor anchors demand for photorealistic rendering pipelines in non-gaming verticals.
South Korea
Live-service game architectures in Seoul drive continuous content delivery demands for elastic GPU cluster orchestration. MFDS and national cybersecurity frameworks govern healthcare simulation deployments using real-time engines. The Seoul Capital Area concentrates developer ecosystems pushing sub-20ms latency requirements for geographically distributed player bases.
India
PLI scheme incentives for electronics manufacturing support localized cloud infrastructure buildout for South Asian developer ecosystems. TRAI guidelines on data localization shape engine service delivery models for domestic AR markets. Karnataka and Telangana host emerging clusters of engine middleware providers serving Southeast Asian expansion.
Game Engine Management Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and creative tool verticals. The vendor base stratifies between hyperscale platform operators, dedicated engine providers, and diversified entertainment conglomerates. Three archetypes dominate: cloud-native service orchestrators, vertically integrated creative suites, and gaming-first technology licensors. Competitive moves concentrate on strategic partnerships with semiconductor fabricators and geographic expansion through regional cloud node deployment.
Within the cloud-native tier, Microsoft exemplifies platform-scale infrastructure integration. Epic Games and Unity Technologies occupy positions as dedicated engine specialists competing on rendering pipeline differentiation. Tencent anchors the diversified conglomerate archetype through strategic middleware investments across Southeast Asian ecosystems. These three represent the primary competitive vectors shaping pricing power and developer ecosystem capture.
| Leading Market Players |
|---|
| Microsoft |
| Tencent |
| Epic Games |
| Take-Two Interactive |
| Roblox Corporation |
| Unity Technologies |
| Sony Interactive Entertainment |
| Iron Galaxy Studios |
| Electronic Arts |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with hyperscale cloud providers lock in GPU cluster access for indie studios while capping per-hour render costs against spot-market volatility. These arrangements concentrate pricing power with Taiwan Semiconductor Manufacturing and NVIDIA as they control advanced node allocation for AI-accelerated ray tracing hardware.
Pricing Analysis
Volume-discount tiering structures separate enterprise simulation contracts from indie metered consumption. Three-tier pricing stratifies across premium dedicated clusters, standard shared infrastructure, and economy spot-instance bursting. Price differentiation hinges on SLA guarantees and data residency certification levels. Cost compression in the economy tier intensifies as hyperscalers compete for California and Washington State developer ecosystems. Indie studios exhibit highest price sensitivity, while defense contractors accept premium rates for ITAR-compliant captive infrastructure.
Supply Chain Analysis
Inventory lead times for H100 and MI300X accelerators now stretch 26-40 weeks, forcing studios into multi-quarter capacity planning. Taiwan, South Korea, and the United States anchor advanced semiconductor fabrication for render clusters. Supply chains draw from specialized memory foundries in South Korea, substrate manufacturers in Japan, and packaging facilities in Malaysia. Single-source vulnerability concentrates in TSMC's CoWoS advanced packaging capacity. Distribution runs through direct hyperscaler procurement with secondary channels for on-premise hardware resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Game Engine Management functions as a service-attach opportunity where managed optimization and compliance tooling expand faster than raw compute licensing. Recurring revenue from performance monitoring and GDPR audit automation now exceeds perpetual engine license growth across European deployments.
For Market Incumbents: Consolidate middleware vendors in Southeast Asian ecosystems to preempt Tencent's platform envelopment strategy. Acquire NeRF reconstruction specialists before automotive design studios internalize scene generation capabilities. Vertical integration into sovereign cloud nodes mitigates MIIT localization mandate costs for cross-border studios.
For New Entrants and Emerging Players: Edge orchestration for 5G-enabled AR represents an under-served layer where hyperscalers lack low-latency node density. Target India's PLI-supported electronics corridors with localized render farm partnerships. Lead with consumption-based billing to displace perpetual license incumbents in price-sensitive South Asian markets.
For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with captive shader optimization talent and defense sector certification. Long-term viability centers on regulatory arbitrage capabilities across GDPR, EU AI Act, and MIIT compliance architectures. Watch for hyperscaler capex guidance cuts as the inflection signal for GPU oversupply and pricing power reversal.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Rendering Acquisition | NeRF specialists compress photogrammetry costs for automotive design studios in Germany and Japan. |
| Sovereign Cloud Node Deployment | EU AI Act data residency mandates force region-specific infrastructure buildout beyond hyperscale availability zones. |
| Defense Sector Certification Investment | ITAR and HIPAA compliance opens mission-critical simulation procurement from Virginia and Maryland contractors. |
| Performance Optimization Subscription Launch | Live-service latency demands create recurring revenue streams from sub-20ms benchmarking tools. |
| Middleware Platform Integration | Asset pipeline automation consolidates fragmented tool vendors serving graphics programmer-scarce mid-tier studios. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, engine provider SEC filings, and EU regulatory impact assessments. Primary interviews engaged technical directors at California and Washington State studios, cloud infrastructure procurement leads, defense simulation program officers, and compliance officers at European automotive visualization firms. Secondary validation drew from FCC broadband quality reports, MIIT localization standards documentation, and GPU supply chain analyst coverage. Bottom-up triangulation across deployment models and solution offerings converged with top-down market sizing from aggregate cloud rendering spend.
Segmentation dimensions modeled span cloud-based, on-premise, hybrid, and edge computing deployment topologies crossed with real-time rendering, performance optimization, asset management, and analytics solution categories. Application intensity varies across video games, simulation training, virtual reality, and augmented reality use cases with end-user sophistication stratifying between AAA studios, indie developers, training providers, and educational institutions. CAGRs derive from elastic compute consumption elasticity curves and live-service content delivery frequency benchmarks across geographic player bases.
Underlying assumptions cover sustained GPU supply chain expansion, stable hyperscaler pricing competition, and progressive EU AI Act enforcement timelines, with deviation risk concentrated in Taiwan semiconductor export restrictions and abrupt MIIT data localization expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Serious Games Market
Gaming
Flat Gaming Monitors Market
Gaming
Gaming Simulator Market
Gaming
Arcade Cabinet Market
Gaming
Casino Gaming Equipment Market
Gaming
Australia Gaming Accessories Market
Gaming
Global Gaming Market
Gaming
Social Gaming Market
Gaming
Global Casino and Gaming Market
Gaming
Global Online Simulation Games Market
Gaming
Shooter Game Market
Gaming
Global 3D Gaming Console Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Southeast Asia Gaming Market
Gaming
Mobile Game Controller Market