
 Unmanned Combat Aerial Vehicle Market | 2026-2036
Unmanned Combat Aerial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Combat Aerial Vehicle Market Analytics
ITAR reform discussions in Washington are shifting the cost-of-entry calculus for foreign component suppliers seeking Pentagon contracts. General Atomics Aeronautical Systems leverages its vertically integrated production campus in Poway, California, to control lead times on turboprop propulsion systems. Northrop Grumman Corporation anchors the high-altitude segment with the RQ-4 Global Hawk family and derivative strike platforms. Lockheed Martin Corporation competes through Skunk Works rapid prototyping, reducing development cycles for classified UCAV programs.
An unmanned combat aerial vehicle is a military aircraft designed for armed engagement without an onboard human pilot, typically featuring composite airframes, satellite-linked command architectures, and payload capacities exceeding 500 kilograms for precision munitions. Its primary purpose is to conduct strike, suppression of enemy air defenses, and intelligence-gathering missions in contested airspace while reducing operator risk. Fixed-wing platforms dominate procurement volumes due to endurance advantages exceeding 24 hours, though hybrid configurations are gaining traction where runway independence matters. AI-powered navigation systems represent the fastest-expanding technology segment as operators demand reduced satellite dependency in electronic warfare environments.
The U.S. Federal Aviation Administration and Department of Defense jointly govern domestic airspace integration for large unmanned systems, while the U.S. State Department controls export through ITAR and the Missile Technology Control Regime. The European Union's proposed European Defence Fund and Permanent Structured Cooperation framework are creating parallel certification pathways for continental UCAV development. Stakeholders must monitor how emerging autonomous weapons conventions at the United Nations reshape rules of engagement and liability frameworks for machine-initiated targeting decisions.
Market Dynamics
The U.S. Department of Defense's Replicator initiative is compressing procurement timelines for attritable autonomous systems, forcing contractors to abandon traditional waterfall development in favor of iterative hardware sprints. This directive is redistributing contract awards toward suppliers capable of rapid scale-up without ITAR-triggered foreign component dependencies.
Growth Catalysts
- AI-powered navigation systems:Operators in contested electronic warfare environments demand reduced satellite dependency, accelerating adoption of machine-vision-based autonomous flight control architectures.
- NATO procurement budgets:Member states are accelerating platform modernization timelines through collective defense spending commitments, creating pooled demand for interoperable UCAV architectures.
- Turkish and Israeli export authorizations:These nations are expanding operational deployments and loosening foreign military sale restrictions, opening access for second-tier militaries previously excluded from advanced UCAV procurement.
Market Restraints
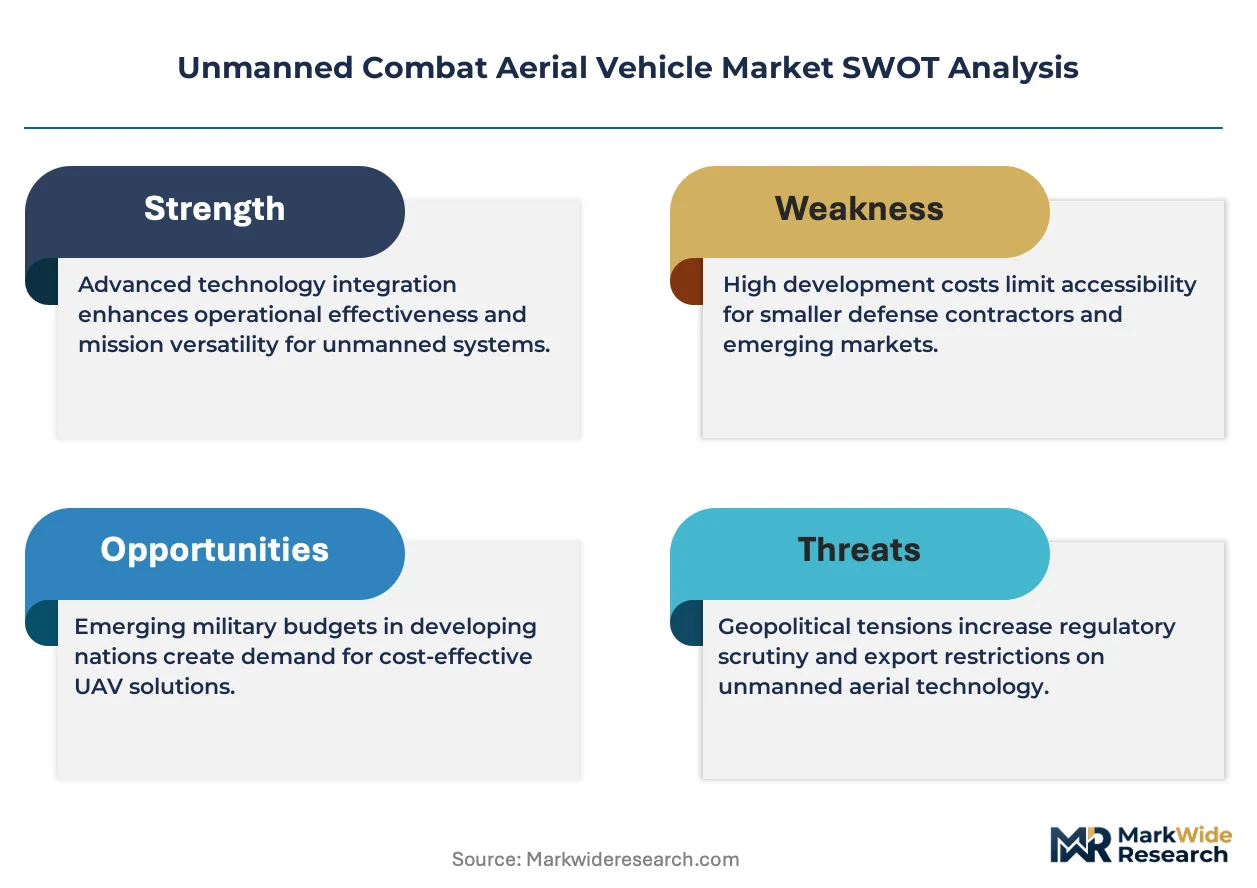
- ITAR component restrictions:The U.S. State Department's export control regime blocks foreign suppliers from Pentagon supply chains unless they establish costly domestic production facilities.
- Turboprop propulsion concentration:Lead times for military-grade engines remain captive to a narrow supplier base in North America, creating single-source vulnerability for endurance-critical platforms.
- Autonomous weapons convention uncertainty:United Nations deliberations on machine-initiated targeting liability are freezing procurement decisions in risk-averse defense ministries.
Strategic Opportunities
- European Defence Fund pathways:The EU's Permanent Structured Cooperation framework is creating parallel certification standards that bypass traditional ITAR dependencies for continental developers.
- Hybrid VTOL configurations:Runway-independent platforms are gaining traction in expeditionary force structures where austere basing limits fixed-wing deployment.
- Suppression of enemy air defenses missions:High-risk penetration roles previously assigned to manned strike aircraft are migrating to expendable UCAV architectures.
Industry Challenges
- AI ethics compliance talent:Defense contractors face acute shortages of engineers capable of implementing explainable autonomous decision frameworks that satisfy emerging rules of engagement standards.
- FAA-DOD airspace coordination:Domestic flight testing of large unmanned systems requires simultaneous Federal Aviation Administration and Department of Defense clearance, creating bureaucratic latency.
- Composite airframe certification:Military airworthiness boards lack established protocols for validating structural integrity of novel material stacks under combat damage scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Combat Aerial Vehicle Market |
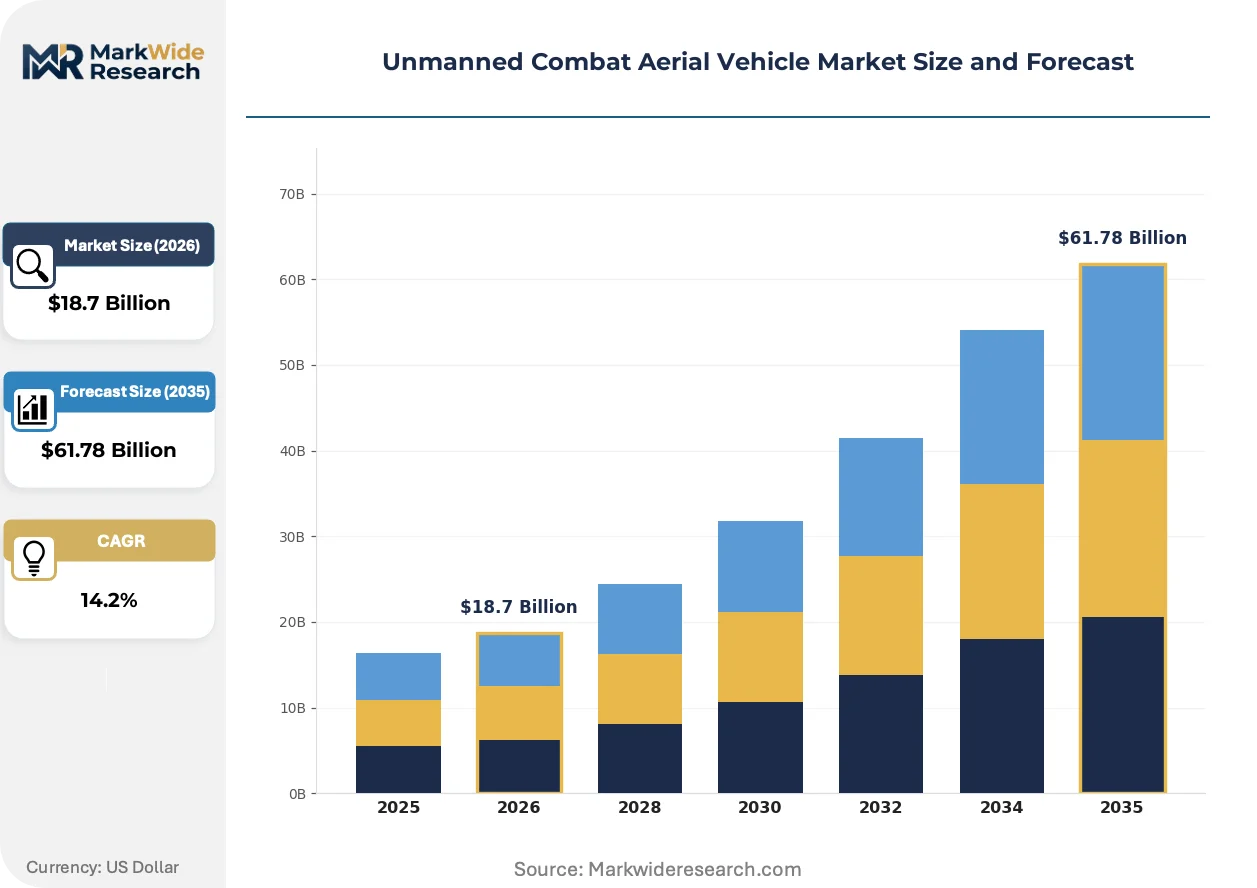
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Take-Off, Fixed-Wing, Hybrid, Multi-Rotor Technology: AI-Powered Navigation, Remote Control, Autonomous Systems, Surveillance Technology End User: Military, Defense Contractors, Government Agencies, Research Institutions Application: Reconnaissance, Target Acquisition, Surveillance, Combat |
| Companies Covered | General Atomics Aeronautical Systems, Northrop Grumman Corporation, Lockheed Martin Corporation, BAE Systems, Leonardo S.p.A., Israel Aerospace Industries, Boeing, L3Harris Technologies, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Combat Aerial Vehicle Market Evolving Landscape
Autonomous targeting architectures are displacing human-in-the-loop strike authorization models, compressing sensor-to-shooter timelines while triggering regulatory backlash. This shift is forcing platform developers to embed transparent decision-auditing capabilities that satisfy emerging international humanitarian law scrutiny.
Machine-vision-based navigation is integrating satellite-denied flight control into next-generation platforms. Special operations commands are field-testing these systems in GPS-jammed environments. The technology is integrating reduced-dependency architectures that compress electronic warfare vulnerability windows for deep-penetration missions.
The European Union's proposed AI Act and autonomous systems liability frameworks are tightening compliance burdens for exporters targeting continental defense markets. Manufacturers must now document algorithmic decision trails to satisfy product liability exposure. High-altitude endurance platforms with extended mission profiles face the steepest documentation requirements.
Defense procurement offices are consolidating vendor relationships around full-lifecycle support contracts rather than discrete platform acquisitions. Middle Eastern and Southeast Asian air forces are leading this transition, bundling training, sustainment, and software update rights into initial awards. Turkey's Baykar and Israel's Elbit Systems have restructured offerings to capture this bundled demand.
Unmanned Combat Aerial Vehicle Market Segmentation
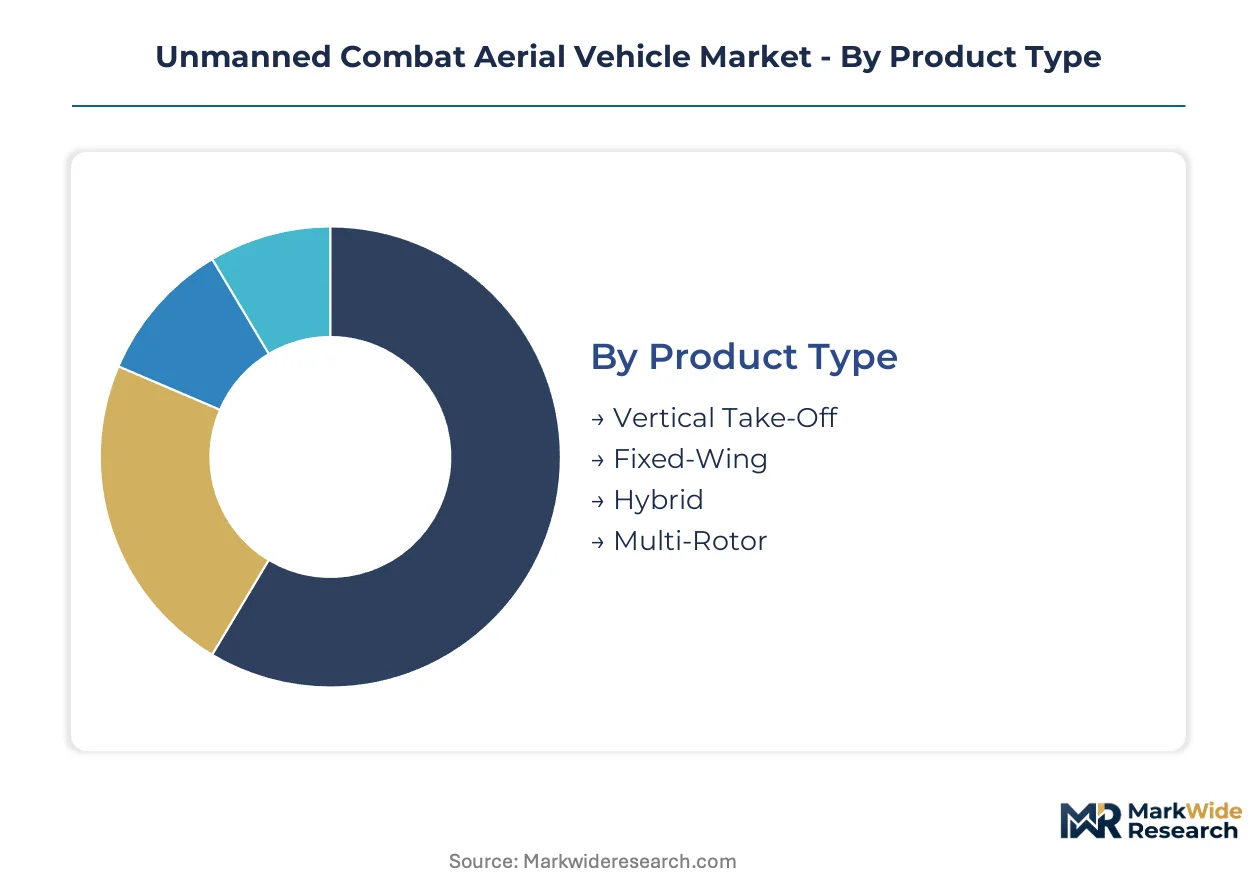
UCAV procurement decisions hinge on platform endurance, payload capacity, and operational autonomy levels. Segment boundaries blur as hybrid architectures absorb fixed-wing range with VTOL flexibility, forcing suppliers to position across multiple technical categories simultaneously.
Product Type:
Fixed-wing platforms demand the heaviest capital commitment due to airframe tooling, engine integration, and runway infrastructure requirements.
- Fixed-Wing:Extended endurance exceeding 24 hours dominates intelligence-gathering missions for the U.S. Air Force and allied NATO operators. Demand concentrates in the United States and Israel where permissive airspace supports long-duration orbits over contested regions.
- Hybrid:Runway-independent architectures merge VTOL flexibility with cruise efficiency, attracting expeditionary force structures in Turkey and special operations commands requiring austere basing. The segment climbs fastest as electronic warfare environments degrade traditional runway availability.
- Vertical Take-Off:Compact footprint suits naval deployments and urban proximity operations where space constraints eliminate fixed-wing options.
- Multi-Rotor:Limited payload and endurance relegate this architecture to tactical overwatch and short-range targeting support.
Fixed-wing absorbs the bulk of installed capacity; hybrid configurations are expanding most quickly.
Technology:
Development resource allocation tilts toward autonomy stacks that reduce operator cognitive burden and satellite dependency.
- AI-Powered Navigation:Machine-vision flight control enables GPS-denied operations in electronic warfare theaters. The U.S. Department of Defense's Replicator initiative accelerates fielding of reduced-dependency architectures for deep-penetration missions against integrated air defenses.
- Autonomous Systems:Machine-initiated targeting decisions compress sensor-to-shooter timelines while triggering compliance burdens under emerging autonomous weapons conventions. Procurement freezes in risk-averse European defense ministries constrain near-term deployment.
- Remote Control:Human-in-the-loop authorization persists in strike roles where rules of engagement require positive identification protocols.
- Surveillance Technology:Multi-spectral sensor fusion supports non-kinetic intelligence collection where kinetic engagement remains restricted.
Remote control retains the largest operational footprint; AI-powered navigation is gaining share fastest.
End User:
Contract qualification requirements and security clearance thresholds create steep barriers between customer tiers.
- Military:Service-specific airworthiness certification and ITAR compliance dominate procurement workflows for the U.S. Department of Defense and allied armed forces. Budget authority for attritable systems is climbing under distributed maritime operations doctrines.
- Defense Contractors:Prime integrators and subsystem suppliers absorb development risk through cost-plus prototyping contracts before transitioning to fixed-price production.
- Government Agencies:Border security and coast guard applications drive dual-use platform demand with modified payload configurations.
- Research Institutions:Experimental flight testing and algorithm validation occur under FAA-DOD joint airspace governance with restricted operational envelopes.
Military end users command the dominant procurement volume; defense contractors are scaling most aggressively.
Application:
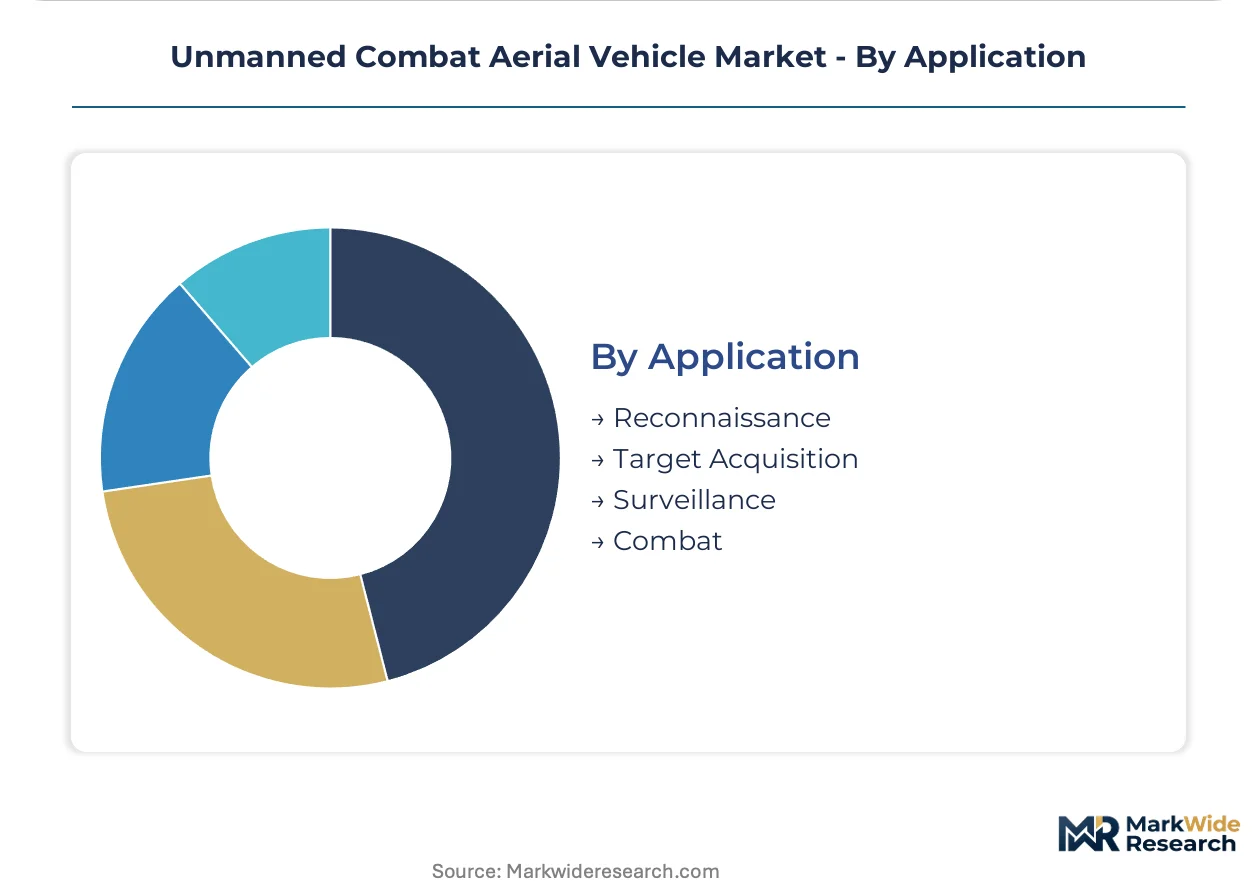
Mission risk profiles determine platform expendability thresholds and corresponding unit cost tolerance.
- Combat:Strike and suppression of enemy air defenses missions absorb the highest platform loss rates, driving demand for attritable architectures below manned aircraft cost floors. Turkish and Israeli export authorizations are opening access for second-tier militaries previously excluded from armed UCAV procurement.
- Surveillance:Persistent overwatch requirements favor high-altitude endurance platforms with multi-day mission profiles. Documentation burdens under the EU AI Act impose steepest compliance costs on these extended-duration systems.
- Reconnaissance:Pre-strike intelligence collection prioritizes sensor resolution and low-observable signatures over payload capacity.
- Target Acquisition:Laser designation and coordinate generation bridge sensor-to-shooter networks for manned-unmanned teaming architectures.
Surveillance claims the largest operational deployment base; combat applications are accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's defense industrial zones around Haifa and the Negev Desert concentrate UCAV development through state-backed R&D tax credits and military procurement offsets. These incentives anchor production clusters serving both domestic forces and export markets.
United States
The Department of Defense's Replicator initiative drives procurement acceleration for attritable autonomous systems. FAA-DOD joint airspace governance governs domestic flight testing of large unmanned platforms. Poway, California hosts vertically integrated production campuses controlling turboprop propulsion lead times.
Israel
Export authorization liberalization opens access for second-tier militaries previously excluded from armed UCAV procurement. The national defense regulator coordinates technology transfer frameworks under MTCR commitments. Haifa's aerospace corridor concentrates development of satellite-denied navigation architectures.
Turkey
Operational deployment expansion in Syria and Libya validates platform performance for foreign military sales. Defense procurement offices bundle training, sustainment, and software update rights into initial awards. Ankara's defense industrial zone anchors Baykar's production scaling for hybrid VTOL configurations.
United Kingdom
Team Tempest UCAV development absorbs Ministry of Defence funding through BAE Systems-led consortia. The UK national aerospace regulator participates in EU parallel certification pathway discussions despite Brexit. Lancashire's military airworthiness boards lack established protocols for validating novel composite material stacks.
Germany
FCAS program commitments redirect Luftwaffe modernization budgets toward Franco-German-Spanish collaborative platforms. KBA and national defense procurement offices coordinate ITAR-independent supply chain qualification. Bavaria's aerospace clusters face capability scarcity in AI ethics compliance engineering talent.
Unmanned Combat Aerial Vehicle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered contract qualification thresholds. Prime integrators absorb development risk through cost-plus prototyping before transitioning to fixed-price production. Three archetypes dominate: vertically integrated airframe-propulsion houses, autonomy-stack software vendors, and full-lifecycle service bundlers. Consolidation concentrates around M&A capture of cleared engineering talent and strategic partnerships securing ITAR-compliant component supply.
Among US-based defense primes, General Atomics Aeronautical Systems, Northrop Grumman Corporation, and Lockheed Martin Corporation occupy positions spanning the fixed-wing endurance, high-altitude surveillance, and rapid-prototyping classified program archetypes respectively. These three exemplify how scale advantages in cleared facility infrastructure and captive propulsion supply create defensive moats against mid-tier challengers seeking Pentagon Replicator contract access.
| Leading Market Players |
|---|
| General Atomics Aeronautical Systems |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| Leonardo S.p.A. |
| Israel Aerospace Industries |
| Boeing |
| L3Harris Technologies |
| Elbit Systems |
| Others |
Value Network & Pricing Analysis
Platform certification tiers—ITAR-compliant versus export-restricted—create divergent cost structures that propagate through both contract pricing and supplier qualification pathways. Premium-tier systems command substantial premiums for cleared-facility production, while attritable architectures trade unit economics against satellite-dependent navigation stacks.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with Replicator-aligned rapid fielding commands absorbing cost premiums against traditional waterfall programs. Three-tier pricing structure across ITAR-restricted, NATO-interoperable, and export-limited configurations segments buyer access. Cost compression in attritable platforms intensifies as Turkish and Israeli suppliers expand foreign military sale catalogs. Second-tier militaries exhibit highest price sensitivity; U.S. Department of Defense programs demonstrate lowest elasticity given mission-critical specifications.
Supply Chain Analysis
Domestic-content mandates under the U.S. State Department's ITAR regime reshape sourcing toward captive North American turboprop propulsion and composite airframe facilities. Supply concentration centers on the United States, Israel, and Turkey for platform integration, with satellite navigation subsystems drawing from specialized European and Israeli vendors. Single-source vulnerability pervades military-grade engine supply chains. Distribution runs through defense procurement offices bundling training and sustainment into lifecycle contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as Replicator initiative timelines favor suppliers with cleared-facility infrastructure and rapid scale-up capacity, squeezing mid-tier challengers lacking ITAR-compliant production footprints.
For Market Incumbents: Cement defensive positioning through backward integration into turboprop propulsion supply and captive AI ethics compliance engineering capacity. Lockheed Martin's Skunk Works rapid prototyping model and General Atomics' Poway campus exemplify how in-house production control neutralizes lead-time vulnerability against emergent Turkish and Israeli export competitors.
For New Entrants and Emerging Players: Digital-channel routes through European Defence Fund parallel certification pathways offer lowest barrier to Pentagon-adjacent contract access. White-space opportunity concentrates in hybrid VTOL configurations for expeditionary force structures and explainable autonomous decision frameworks satisfying emerging UN weapons convention scrutiny. Target EU defense ministries frozen by machine-initiated targeting liability uncertainty with algorithmic auditing documentation services.
For Investors and Strategic Acquirers: Re-rating potential sits with autonomy-stack software vendors given Replicator initiative acceleration of reduced-satellite-dependency architectures. Long-term viability favors suppliers with demonstrated electronic warfare theater deployment records. Watch Turkish and Israeli foreign military sale authorization volumes as inflection signal for second-tier military demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Compliant Facility Certification | Unlocks Pentagon Replicator contract access against export-restricted competitors. |
| Machine-Vision Navigation Integration | Enables GPS-denied operations for contested electronic warfare environments. |
| Full-Lifecycle Support Bundling | Captures Middle Eastern and Southeast Asian procurement office preferences. |
| Hybrid VTOL Configuration Development | Addresses austere basing requirements in expeditionary force structures. |
| AI Ethics Compliance Engineering Investment | Satisfies emerging UN autonomous weapons convention liability frameworks. |
Research Methodology
Document review covered U.S. Department of Defense budget justification materials, FAA-DOD joint airspace governance filings, and NATO collective defense spending commitments, complemented by interviews with UCAV program executives, military procurement officers, composite airframe certification specialists, and satellite navigation subsystem engineers. Secondary validation drew from Missile Technology Control Regime documentation, EU Permanent Structured Cooperation framework publications, and customs trade data on turboprop propulsion components. Bottom-up platform deployment tracking and top-down defense budget allocation analysis provided triangulation.
Historical procurement velocity cross-referenced against expert panel input on Replicator initiative implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform architecture, autonomy technology tier, end-user clearance level, mission application, and regional regulatory cluster. CAGRs derived from deployment trajectory extrapolation moderated by ITAR reform uncertainty and autonomous weapons convention negotiation status. Forecast inputs incorporated electronic warfare environment degradation rates and foreign military sale authorization liberalization patterns.
The model holds under sustained NATO procurement budget growth and continued U.S. Replicator initiative funding; deviation in UN autonomous weapons convention binding status or major ITAR regulatory overhaul would shift attritable platform demand curves. Forecasts reflect documented assumptions on satellite-denied navigation technology maturation and Turkish-Israeli export competitiveness. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Fixed-Wing VTOL UAV Market
UAV
Tethered Drones Market
UAV
Middle-East and Africa Drones Market
UAV
Global Multirotor UAV Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Rc Helicopter Market
UAV
Passenger Drones Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Micro Drone Market
UAV
Drone Lens Market
UAV
Drone Camera Market
UAV
Global Electric Drone Market
UAV
Home Security Drone Market
UAV
Bubble Drone Market
UAV
Utility Drone Market
UAV
Europe Tethered Drone Market