
 Sales Enablement Software Market | 2026-2036
Sales Enablement Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Enablement Software Market Outlook
Subscription-based software-defined feature layers is rebalancing what vendors monetize, shifting value from perpetual licenses toward recurring access to AI-driven coaching and real-time content recommendation engines. Seismic Software leverages extensive CRM connector libraries to anchor enterprise deployments across Fortune 500 accounts. Highspot differentiates through native buyer engagement analytics that sustain premium pricing in competitive RFP cycles. Mindtickle competes by embedding revenue intelligence directly into rep workflow tools rather than bolting it on as a separate module.
Sales enablement software encompasses integrated platforms that combine content management, training delivery, conversation intelligence, and analytics to accelerate revenue team productivity, typically deployed through cloud-native architectures with API-first connectivity to CRM systems. The primary commercial purpose centers on reducing sales cycle duration and improving win rates by delivering contextually relevant assets and coaching at precise pipeline stages. Cloud-Based deployment now captures the dominant margin pool as vendors sunset on-premises variants and redirect engineering toward multi-tenant elasticity. Content Management leads in absolute revenue contribution due to universal need across B2B and B2C sales organizations, while Analytics Solutions represents the fastest-expanding segment as predictive forecasting capabilities displace static reporting dashboards.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that constrain how European customer data flows through AI-powered recommendation engines, directly shaping vendor product roadmaps and hosting architectures. In the United States, the SEC's marketing compliance frameworks and state-level privacy statutes such as CCPA create fragmented but consequential obligations for financial services sales enablement deployments. Stakeholders must monitor how evolving AI liability regimes and cross-border data governance standards will redefine competitive moats and vendor qualification criteria.
Market Dynamics
AI-powered coaching modules are compressing sales cycle velocity by embedding real-time guidance directly into rep workflows, forcing vendors to rearchitect data pipelines around EU AI Act transparency mandates and GDPR residency requirements.
Growth Catalysts
- EU AI Act Algorithmic Transparency:Mandatory explainability standards for AI-driven recommendation engines are accelerating vendor investment in interpretable machine learning architectures, creating competitive differentiation for compliant platforms.
- Financial Services Marketing Compliance:SEC frameworks governing sales communications are driving demand for automated compliance checking within content management systems, particularly among broker-dealers and asset managers.
- Cloud-Native API Connectivity:Native CRM integration via REST APIs and webhook architectures is eliminating deployment friction, enabling faster time-to-value for enterprise B2B sales organizations.
Market Restraints
- Cross-Border Data Residency:GDPR's data localization requirements impose infrastructure duplication costs, constraining how European customer data flows through centralized AI training pipelines hosted in US cloud regions.
- Legacy System Integration Debt:On-premises CRM instances and proprietary data warehouses create technical friction, extending implementation timelines and inflating professional services margins.
- Subscription Margin Compression:Perpetual license revenue runoff combined with multi-tenant infrastructure investments is pressuring vendor profitability during the cloud transition window.
Strategic Opportunities
- Revenue Intelligence Convergence:Integration of conversation intelligence with forecasting algorithms represents unmonetized white space, enabling predictive pipeline scoring that displaces static reporting.
- Mid-Market Underpenetration:Sub-500 employee B2B organizations remain underserved by enterprise-focused platforms, creating opportunity for vertically specialized solutions with streamlined onboarding.
- CSRD Disclosure Alignment:EU Corporate Sustainability Reporting Directive requirements on workforce training metrics are creating procurement tailwinds for platforms with built-in skills tracking and certification management.
Industry Challenges
- Prompt Engineering Talent Scarcity:Shortage of specialists capable of tuning large language models for sales-specific use cases is constraining AI feature development velocity and inflating compensation costs.
- Algorithmic Audit Complexity:Demonstrating EU AI Act compliance for high-risk AI systems requires documentation workflows that extend product release cycles and demand specialized legal-technical hybrid roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Enablement Software Market |
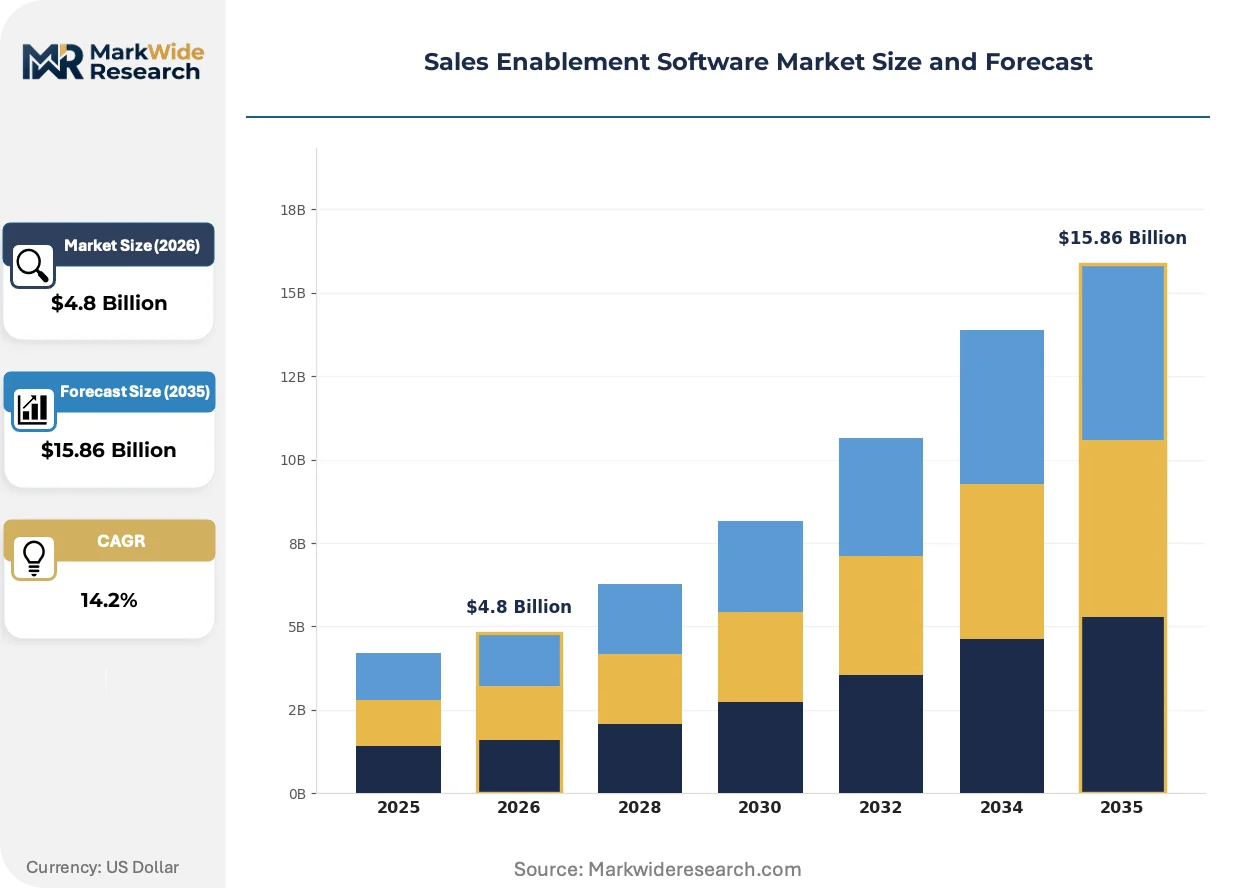
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Management, Training Tools, Analytics Solutions, CRM Integrations Feature: Reporting Tools, Lead Scoring, Mobile Access, Collaboration Tools Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services End User: B2B Companies, B2C Enterprises, Small Businesses, Large Corporations |
| Companies Covered | Seismic Software, Highspot, Salesloft, Showpad, Allego, Mindtickle, Bigtincan, Outreach, HubSpot Sales Hub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Enablement Software Market Strategic Shifts
Federated learning architectures and edge-deployed inference are redistributing computational load away from centralized cloud regions, while procurement criteria increasingly weight algorithmic explainability alongside functional capability.
Conversational AI is decentralizing the locus of coaching intelligence from manager-led sessions toward real-time, in-call guidance systems. Mid-market SaaS vendors are adopting these capabilities fastest, compressing the traditional 90-day onboarding window toward immediate productivity. This shift is enabling continuous skill development without removing reps from active selling time.
The EU AI Act's risk-based classification system is mandating human oversight protocols for AI systems influencing sales decisions. Vendors must now implement logging and review workflows that satisfy notified body scrutiny. Financial services deployments across Germany, France, and Italy are experiencing the steepest compliance cost escalation.
Enterprise buyers are unbundling content management from full-platform contracts, selecting best-of-breed point solutions for specific pipeline stages. Procurement committees now include revenue operations specialists alongside traditional IT stakeholders. This pattern is most pronounced in US technology and healthcare verticals where specialized sales methodologies dominate.
Sales Enablement Software Market Segmentation
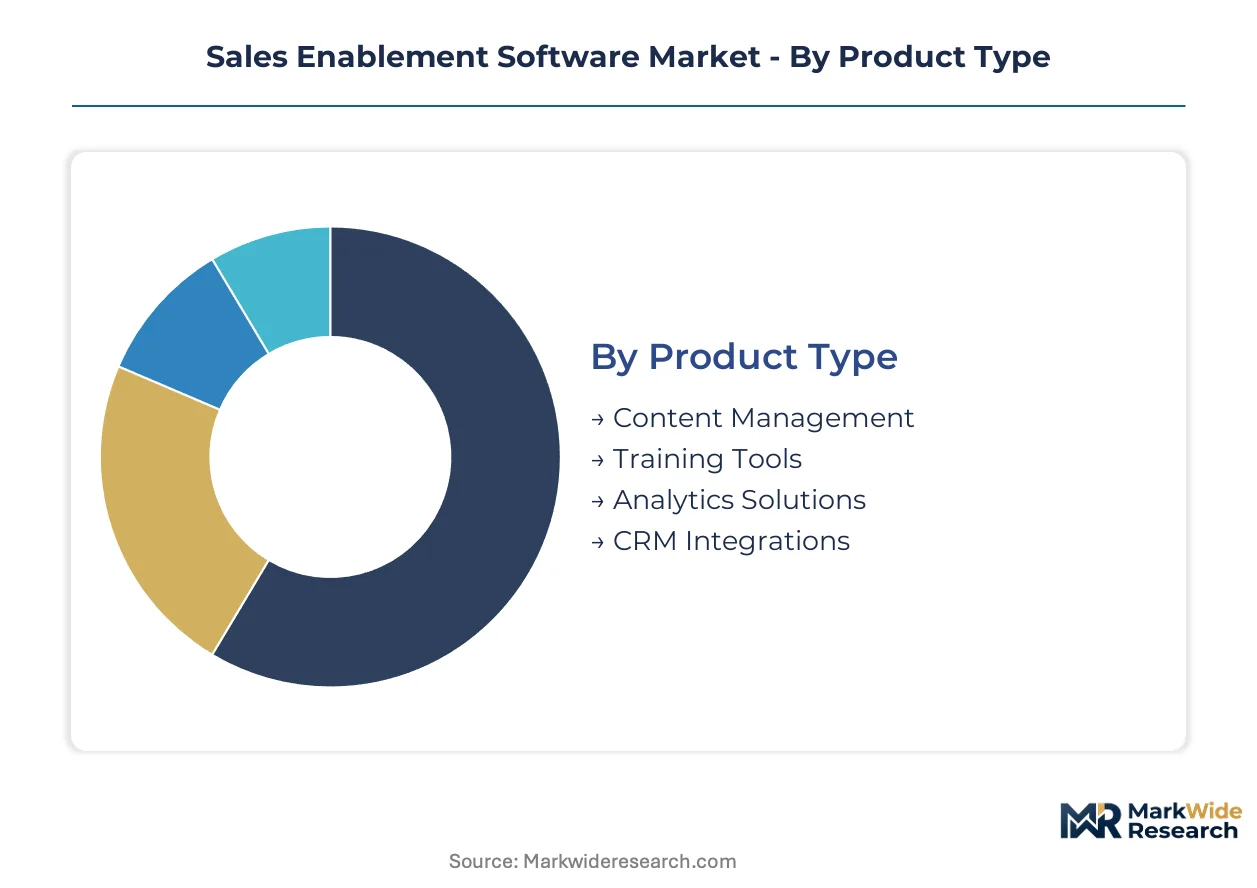
Segmentation in sales enablement software reveals how vendor architectures align with distinct operational requirements across enterprise scale, technical infrastructure, and functional priorities. Buyers select configurations based on CRM ecosystem compatibility, compliance mandates, and sales cycle complexity rather than generic feature checklists.
Product Type:
Functional architecture determines integration depth and recurring revenue potential across the technology stack.
- Content Management:Centralized repositories with version control and dynamic asset personalization anchor enterprise deployments. Demand concentrates among US financial services and healthcare verticals where SEC marketing compliance and HIPAA documentation requirements mandate audit trails for every customer-facing material.
- Analytics Solutions:Predictive forecasting modules and pipeline scoring algorithms displace static dashboards through machine learning architectures. Growth is climbing fastest in technology and professional services sectors where revenue operations teams prioritize real-time win probability metrics over historical reporting.
- Training Tools:Microlearning platforms with AI-adaptive curricula reduce onboarding duration for distributed salesforces.
- CRM Integrations:Native connector libraries and bidirectional data sync eliminate manual entry friction between systems.
Mature deployment sits with Content Management. Newer deployment is concentrated in Analytics Solutions.
Feature:
Capability prioritization reflects how procurement committees weight manager visibility against rep productivity.
- Reporting Tools:Customizable dashboards with drill-down attribution modeling satisfy revenue operations requirements for pipeline hygiene scoring. Demand clusters in Germany and France where CSRD workforce training disclosure mandates require granular certification tracking and skills gap documentation.
- Lead Scoring:Behavioral signal aggregation from email engagement, content consumption, and meeting sentiment prioritizes prospect outreach sequences. Expansion is steepest among B2B SaaS vendors with product-led growth motions seeking to identify expansion revenue signals within existing accounts.
- Mobile Access:Offline-capable tablet and smartphone interfaces enable field sales productivity without connectivity dependencies.
- Collaboration Tools:Real-time annotation and peer feedback loops accelerate deal strategy alignment across distributed teams.
Established adoption patterns favor Reporting Tools. Accelerating investment flows toward Lead Scoring.
Deployment:
Infrastructure choices balance elasticity requirements against data sovereignty constraints in regulated industries.
- Cloud-Based:Multi-tenant architectures with API-first connectivity to Salesforce, HubSpot, and Microsoft Dynamics capture the dominant margin pool. Procurement concentrates in the United States where SaaS budgets remain deepest and implementation friction tolerance is lowest.
- Hybrid Solutions:Split processing with sensitive data residing on-premises while AI inference runs in cloud regions addresses GDPR residency requirements. Uptake is expanding most quickly across German, French, and Italian financial services deployments subject to EU AI Act high-risk system classification and algorithmic audit obligations.
- On-Premises:Single-tenant installations persist in defense and classified government contracts with air-gapped security requirements.
- Managed Services:Vendor-operated private cloud instances with dedicated infrastructure reduce internal DevOps burden.
Volume leadership belongs to Cloud-Based. Regulatory pressure is redirecting new procurement toward Hybrid Solutions.
End User:
Organizational scale dictates platform complexity tolerance and integration ecosystem breadth.
- Large Corporations:Fortune 500 deployments require global content localization, role-based permission architectures, and dedicated customer success management. Demand anchors in the United States where enterprise SaaS procurement committees include revenue operations, legal, and IT stakeholders evaluating EU AI Act compliance readiness.
- B2B Companies:Complex sales cycles with multiple stakeholder touchpoints necessitate conversation intelligence and mutual action plan tooling. Growth is sharpest among mid-market SaaS vendors with 200-2,000 employees seeking to compress enterprise sales cycles without expanding headcount.
- B2C Enterprises:High-velocity transactional sales prioritize mobile-first coaching and real-time competitive battlecards.
- Small Businesses:Simplified onboarding and out-of-box CRM connectors reduce time-to-first-value for resource-constrained teams.
Platform maturity and feature depth concentrate with Large Corporations. Emerging vendor investment targets B2B Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates heavily in the United States, while consumption spreads across developed economies with stringent compliance requirements. European demand is accelerating fastest among financial services verticals facing EU AI Act deadlines. Asia-Pacific adoption lags but shows concentrated growth in technology hubs seeking CRM modernization.
United States
Enterprise SaaS procurement budgets and Fortune 500 CRM consolidation are driving platform deployments. SEC marketing compliance frameworks impose automated content checking requirements on broker-dealers. San Francisco and New York Metro anchor vendor headquarters clusters while Boston's financial services sector demands specialized regulatory tooling.
Germany
Industrial B2B sales teams prioritize conversation intelligence for complex machinery procurement cycles. GDPR data residency mandates and EU AI Act high-risk system classifications are accelerating hybrid cloud adoption. Frankfurt's financial services concentration and Munich's industrial automation corridor represent the steepest compliance cost escalation zones.
United Kingdom
Professional services and fintech verticals are expanding analytics solution procurement for pipeline forecasting. The Financial Conduct Authority's consumer duty rules are reshaping sales communication audit requirements. London's technology corridor dominates vendor commercial operations while Edinburgh's asset management cluster drives specialized feature demand.
France
CSRD workforce training disclosure mandates are creating procurement tailwinds for certification-tracking platforms. CNIL algorithmic governance guidelines intersect with EU AI Act implementation timelines. Paris anchors enterprise software decision-making while Lyon and Toulouse manufacturing clusters adopt sales enablement for export-oriented B2B operations.
Japan
Manufacturing and automotive B2B sales organizations are modernizing legacy CRM integrations with API-first platforms. METI's data governance guidelines influence vendor selection criteria for cross-border data flows. Tokyo's corporate headquarters concentration and Osaka's industrial sales networks represent the primary deployment corridors.
Sales Enablement Software Market Competitive Environment
Top-tier vendors anchor enterprise Fortune 500 deployments, while mid-market specialists compete on streamlined onboarding and vertical specialization. The market structure exhibits tiered consolidation with three to five dominant platforms capturing the majority of recurring revenue. Strategic archetypes include CRM-native incumbents, AI-first challengers, and vertical specialists targeting regulated industries. Competitive moves center on M&A for conversation intelligence capabilities and strategic partnerships for algorithmic audit compliance.
Within the AI-native tier, Seismic Software and Highspot occupy positions as archetype representatives for enterprise content management and buyer engagement analytics respectively. Mindtickle exemplifies the revenue intelligence convergence archetype through embedded workflow tooling. These three companies collectively illustrate how vendor differentiation is concentrating around compliance-ready architectures and real-time coaching delivery rather than static repository functionality.
| Leading Market Players |
|---|
| Seismic Software |
| Highspot |
| Salesloft |
| Showpad |
| Allego |
| Mindtickle |
| Bigtincan |
| Outreach |
| HubSpot Sales Hub |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists with consolidated CRM connector portfolios anchor supply-side discipline, translating platform integration depth into subscription pricing power that resists commoditization pressure from point-solution challengers.
Pricing Analysis
Margin tightening in mid-market tiers reflects feature unbundling as enterprise buyers negotiate à la carte content management contracts separate from full-platform suites. Pricing stratifies across premium AI-coaching bundles, standard workflow automation, and economy content repository tiers, with differentiation resting on EU AI Act compliance certification and native Salesforce integration depth. Cost-down pressure on standard tiers accelerates because hyperscaler infrastructure costs are being passed through via annual subscription escalators. Small businesses exhibit highest price sensitivity, while Fortune 500 procurement committees prioritize algorithmic audit documentation over per-seat economics.
Supply Chain Analysis
Prompt engineering talent scarcity in San Francisco and Bangalore constrains AI feature velocity, forcing vendors to redistribute model training workloads across distributed engineering nodes. Cloud infrastructure draws from hyperscaler regions in the United States, Ireland, and Singapore, while specialized GPU clusters for LLM fine-tuning rest on Taiwan and South Korean semiconductor supply. Single-source vulnerability sits with NVIDIA H100 allocation queues, which gate model development timelines for revenue intelligence modules. Distribution runs through direct enterprise sales teams with dedicated customer success managers, supplemented by systems integrator partnerships for hybrid deployment implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in algorithmic audit talent prop pricing resilience for compliance-ready platforms, insulating premium vendors from margin compression affecting feature-undifferentiated competitors.
For Market Incumbents: Acquire conversation intelligence startups with pre-trained sales-domain LLMs to close capability gaps against AI-native challengers. Defend position by embedding revenue intelligence directly into rep workflows rather than bolting it on as separate modules, while investing in EU AI Act documentation workflows to sustain premium pricing in German and French financial services procurement cycles. For New Entrants and Emerging Players: API-first distribution partnerships with mid-market CRM consultancies offer lowest-friction customer acquisition channels. White-space concentration sits with sub-500 employee B2B organizations in professional services verticals underserved by enterprise-focused onboarding complexity. Target CSRD-aligned certification tracking as the wedge application, leveraging built-in skills documentation to displace generic learning management systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical specialists with pre-built SEC marketing compliance modules in the United States, where regulatory complexity sustains acquisition premiums. Long-term viability hinges on federated learning architectures that satisfy GDPR data residency without sacrificing model performance. Watch EU AI Act enforcement patterns across German Bafin and French AMF jurisdictions as the inflection signal for compliance-ready platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and HubSpot connectors reduce implementation friction for enterprise B2B deployments. |
| Acquisition of Specialist Firm | Conversation intelligence startups with sales-domain LLMs close capability gaps against AI-native challengers. |
| Strategic Partnership | Hyperscaler alliances for EU-region GPU clusters satisfy GDPR training data residency requirements. |
| Product Launch | Federated learning architectures enable model improvement without centralizing sensitive European customer data. |
| Geographic Expansion | Frankfurt and Munich data centers address Bafin scrutiny for financial services algorithmic audit compliance. |
Study Parameters
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone, cross-referenced against primary interviews with sales enablement platform CTOs, revenue operations directors at Fortune 500 accounts, and CRM integration specialists. Bottom-up sizing triangulated vendor-reported subscription metrics with top-down IT spend allocation models across the analysis window.
Historical trendline analysis tracked deployment model shifts and AI feature penetration across organization size tiers, with segmentation modeling incorporating deployment architecture, end-user scale, vertical industry, and regional regulatory cluster dimensions. CAGRs were derived from curve-fitting observed adoption velocities against infrastructure investment cycles, with specific inputs including EU AI Act implementation timelines and SEC marketing compliance enforcement patterns.
The model holds under stable regulatory enforcement intensity; deviation in EU AI Act notified body appointment delays or hyperscaler GPU allocation shocks would shift vendor competitive positioning. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Media Editing App Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Intelligent Apps Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
Workstation Software Market
Software & Services
North America IT Services Market
Software & Services
Global Retail Execution Software Market
Software & Services
Advanced Process Control Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global Core Banking Software Market
Software & Services
Subscription Management Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Team Collaboration Software Market