
 Driver and Staff Management Software Market | 2026-2036
Driver and Staff Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Driver and Staff Management Software Market Foresight
Third-party logistics providers is collapsing as the dominant buyer archetype while in-house fleet operators gain procurement share in driver and staff management software. Samsara leverages its IoT-native architecture to anchor subscription revenue among enterprise transportation clients. Motive competes through AI-powered dashcam integration that extends its platform beyond basic compliance tracking. Verizon Connect sustains geographic dominance in North American telematics through dense cellular network partnerships.
Driver and staff management software encompasses cloud-native and on-premises platforms that coordinate workforce scheduling, real-time GPS tracking, hours-of-service compliance logging, and driver performance scoring through embedded telematics hardware and API-connected third-party data feeds. These systems serve commercial fleets by reducing administrative overhead, enforcing regulatory driving limits, and optimizing route-to-driver assignments through algorithmic dispatch. Cloud-based deployment leads in new installations due to lower capital requirements and faster feature iteration cycles, while on-premises systems retain share among operators with stringent data sovereignty constraints. Fleet management as a product category captures the broadest margin pool through recurring telematics subscriptions, whereas performance analytics represents the fastest-expanding segment as predictive driver risk scoring becomes standard in insurance-linked contracts.
FAA regulations governing commercial driver medical certification and hours-of-service logging shape product functionality requirements for cross-border fleet operators. The EPA's SmartWay program and emerging state-level emissions tracking mandates in California and New York compel vendors to embed fuel-efficiency metrics directly into driver scorecards. OSHA workplace safety standards further extend platform scope into warehouse staff coordination and loading dock scheduling modules. Stakeholders must evaluate whether to build compliance engines in-house or absorb rising API costs from fragmented third-party certification databases.
Market Dynamics
Cloud migration is compressing deployment timelines while fragmenting vendor competitive moats across fleet management software procurement.
Growth Catalysts
- EU AI Act compliance mandates:European fleet operators must deploy algorithmic audit trails for driver scoring systems, accelerating replacement cycles for legacy platforms.
- Telematics hardware miniaturization:Smaller form-factor GPS and accelerometer modules enable retrofit installation across aging vehicle fleets without downtime.
- Insurance-linked driver risk contracts:Commercial auto underwriters now mandate real-time performance data feeds, converting software from operational tool to policy prerequisite.
Market Restraints
- Cellular connectivity cost volatility:Fleet management platforms depend on carrier data plans, and roaming charges for cross-border operators create unpredictable operating expense spikes.
- Data sovereignty requirements:German and French national cloud certification programs fragment vendor architecture choices and multiply compliance engineering overhead.
- Substitute platform consolidation:Enterprise ERP vendors embed lightweight fleet modules, capturing price-sensitive buyers who previously purchased standalone solutions.
Strategic Opportunities
- India commercial vehicle digitization:Mandatory FASTag toll integration and upcoming national logistics platform standards create first-mover advantage for compliant software providers.
- AI-powered predictive maintenance convergence:Marrying driver behavior data with engine diagnostics enables subscription revenue expansion beyond core workforce management.
- California emissions scorecard mandates:CARB regulations require fuel-efficiency visibility at driver level, opening performance analytics modules to mandated adoption.
Industry Challenges
- Embedded systems engineering talent scarcity:Vendors struggle to hire firmware developers capable of optimizing telematics hardware for battery-constrained installations.
- Hours-of-service API fragmentation:DOT-certified medical examiner databases lack standardized interfaces, forcing costly custom integration for each new state jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driver and Staff Management Software Market |
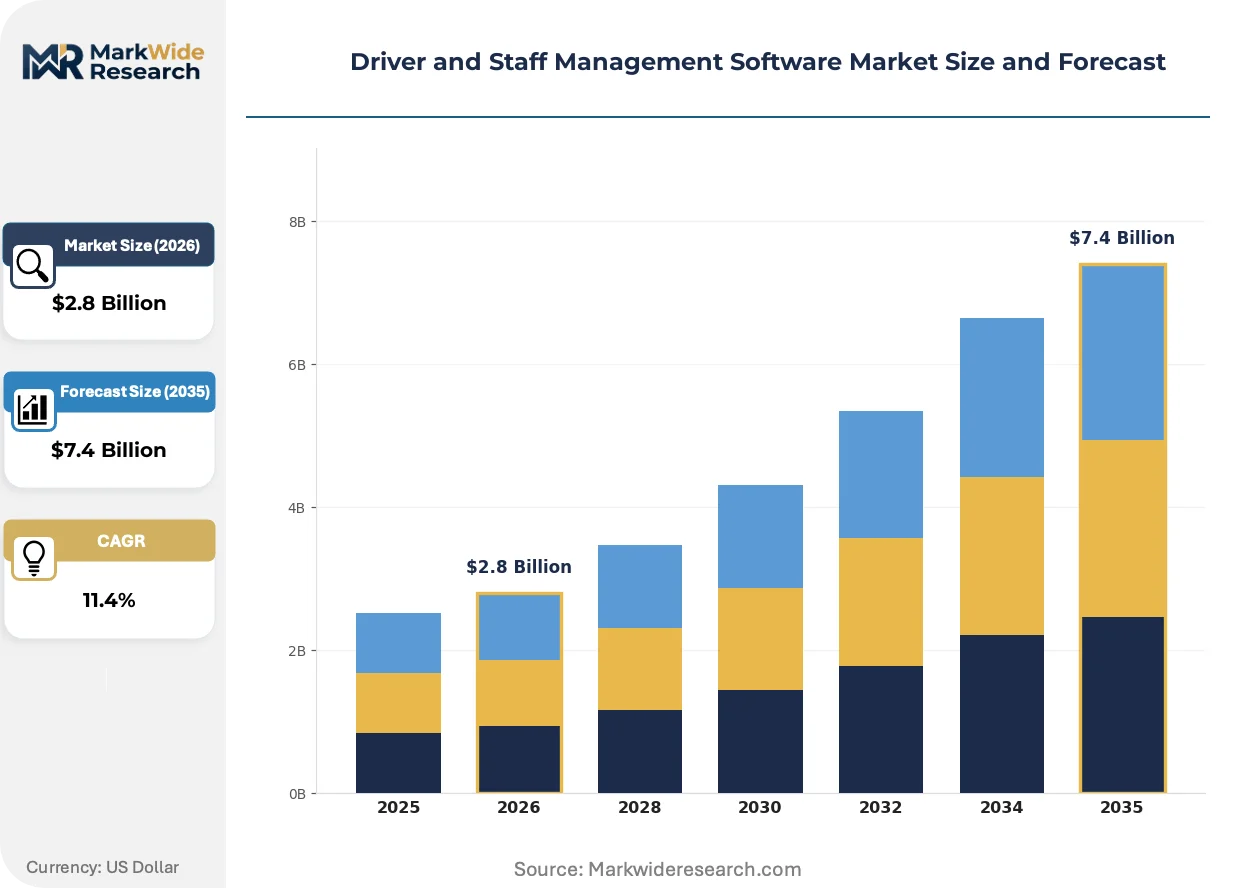
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driver Scheduling, Staff Tracking, Fleet Management, Performance Analytics Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Logistics Companies, Transportation Firms, Delivery Services, Fleet Operators Integration Level: API Integration, Third-Party Services, Standalone, Custom Solutions |
| Companies Covered | Verizon Connect, Fleetio, Motive, Azuga, Omnitracs, Samsara, Lytx, Driver Schedule, Locus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driver and Staff Management Software Market Shifts & Advancements
Artificial intelligence is penetrating driver safety systems at the edge, while regulatory pressure and procurement model evolution reshape how fleet software reaches end-users.
Edge AI inference chips embedded directly into dashcam hardware is bifurcating the market between premium real-time coaching systems and delayed cloud-upload alternatives. Large for-hire carriers with dedicated safety departments adopt instant feedback loops, compressing accident frequency metrics that drive insurance renewals. This technology split forces mid-market vendors to choose between silicon partnerships and margin erosion.
GDPR Article 22 automated decision-making restrictions constrain how European platforms generate driver termination recommendations from algorithmic scoring. Vendors must engineer human-in-the-loop review workflows, adding product complexity but creating defensible positioning against non-compliant imports. German fleet operators particularly scrutinize these audit capabilities during procurement evaluations.
Subscription bundling with vehicle financing is displacing standalone software sales among small fleet buyers acquiring new equipment. OEM captive finance arms embed telematics as a service-line item, capturing customer relationships that independent software vendors previously owned. This channel consolidation concentrates most visible in United States commercial truck retail transactions.
Driver and Staff Management Software Market Segmentation
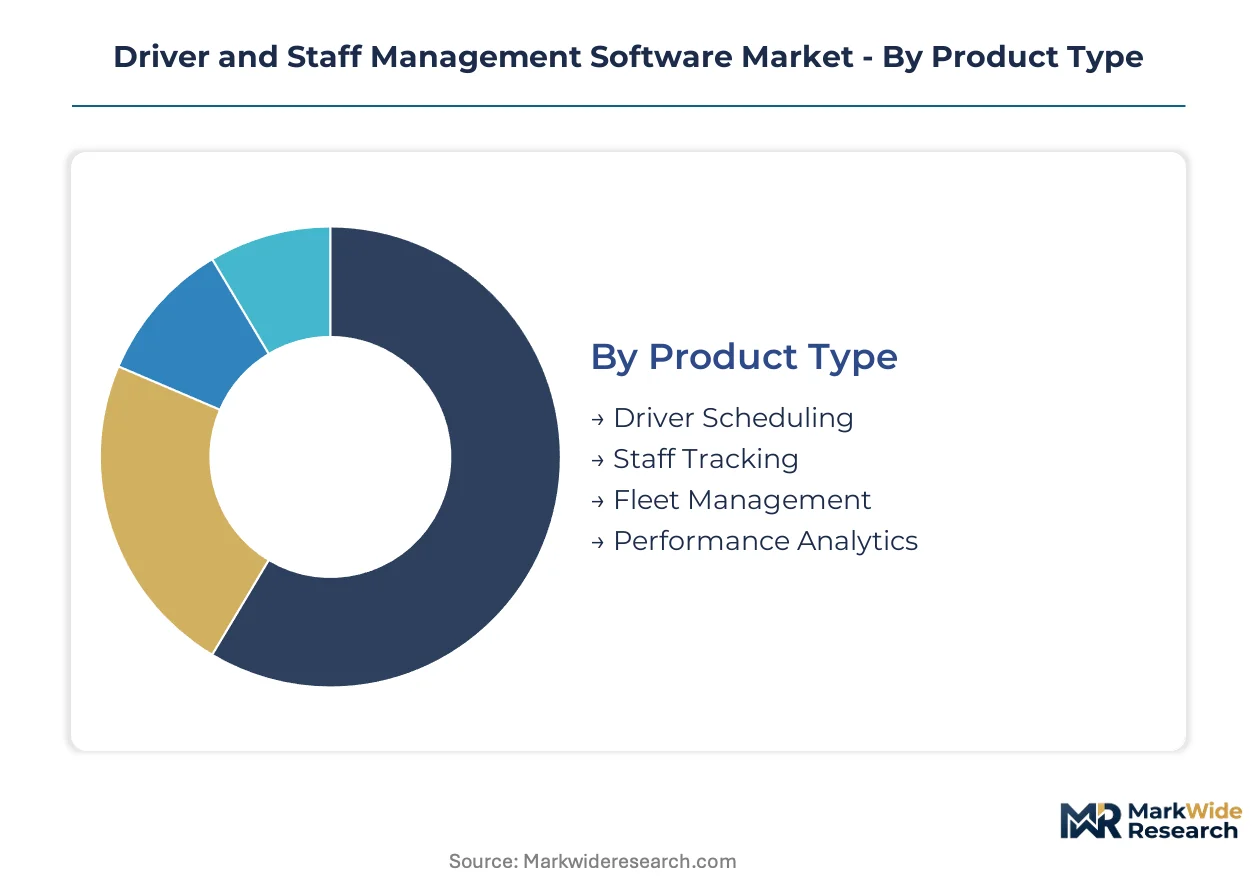
Fleet operators configure software procurement around operational scale and data sovereignty constraints. Segment boundaries blur where ERP vendors bundle lightweight modules, pressuring standalone specialists to differentiate through compliance depth.
Product Type:
Substitute pressure concentrates in basic scheduling modules where generic workforce platforms undercut specialized vendors on price. Premium analytics and integrated fleet systems retain defensible positioning through regulatory complexity.
- Driver Scheduling:Cloud-native platforms automate shift allocation, break compliance, and route-to-driver matching through algorithmic dispatch engines. Demand clusters among United States for-hire carriers facing DOT hours-of-service enforcement. Substitution risk from generic workforce management tools compresses margins at the low end.
- Performance Analytics:Predictive scoring engines fuse telematics data with engine diagnostics to generate driver risk profiles and fuel-efficiency benchmarks. Insurance-linked contracts in California and Texas mandate real-time data feeds, converting analytics from operational luxury to policy prerequisite. Expansion into predictive maintenance subscriptions extends revenue per vehicle.
- Staff Tracking:GPS-enabled mobile applications coordinate warehouse personnel and loading dock workflows through geofenced check-in systems.
- Fleet Management:Integrated platforms combine vehicle telematics, maintenance logging, and compliance documentation through unified dashboards.
Fleet Management anchors the volume base while Performance Analytics gains share at the steepest rate.
Deployment:
Cost tier stratification separates capital-constrained operators from enterprises prioritizing feature velocity over data control. Mid-market buyers increasingly reject on-premises burden despite sovereignty concerns.
- Cloud-Based:Multi-tenant SaaS architectures enable rapid feature deployment and elastic scaling without infrastructure capital. German and French operators scrutinize GDPR Article 22 compliance and data residency certifications during procurement, favoring EU-sovereign cloud instances. Subscription economics align vendor incentives with customer retention.
- On-Premises:Single-tenant installations behind customer firewalls satisfy defense contractors and government fleets with classified route requirements. High upfront license fees and dedicated infrastructure costs restrict addressable market to regulated industries. Maintenance burden shifts to internal IT organizations.
- Hybrid:Sensitive compliance data remains local while analytics workloads burst to cloud infrastructure.
- Mobile:Native iOS and Android applications extend core platform functionality to field supervisors and drivers.
Cloud-Based deployment commands the installed base while Mobile delivery expands most quickly among last-mile operators.
End User:
Application intensity varies by fleet complexity and regulatory exposure. Asset-heavy operators demand deeper integration than service brokers.
- Logistics Companies:Third-party providers manage heterogeneous vehicle fleets across multiple shipper contracts, requiring flexible dispatch algorithms and cross-customer reporting. E-commerce volume spikes in United States and Germany drive seasonal capacity planning complexity. Multi-client data segregation mandates elevate security requirements.
- Transportation Firms:Dedicated freight carriers optimize asset utilization through driver-home-time balancing and predictive maintenance scheduling. Long-haul operations across state and national borders compound hours-of-service compliance complexity.
- Delivery Services:Urban route density and customer time-window constraints prioritize real-time traffic integration.
- Fleet Operators:Captive vehicle pools in utilities and telecommunications emphasize safety scoring and incident liability reduction.
Logistics Companies generate the largest contract values while Delivery Services show the steepest expansion trajectory.
Integration Level:
Customer technical maturity determines build-versus-buy calculus for connectivity layers. API standardization remains incomplete across telematics hardware vendors.
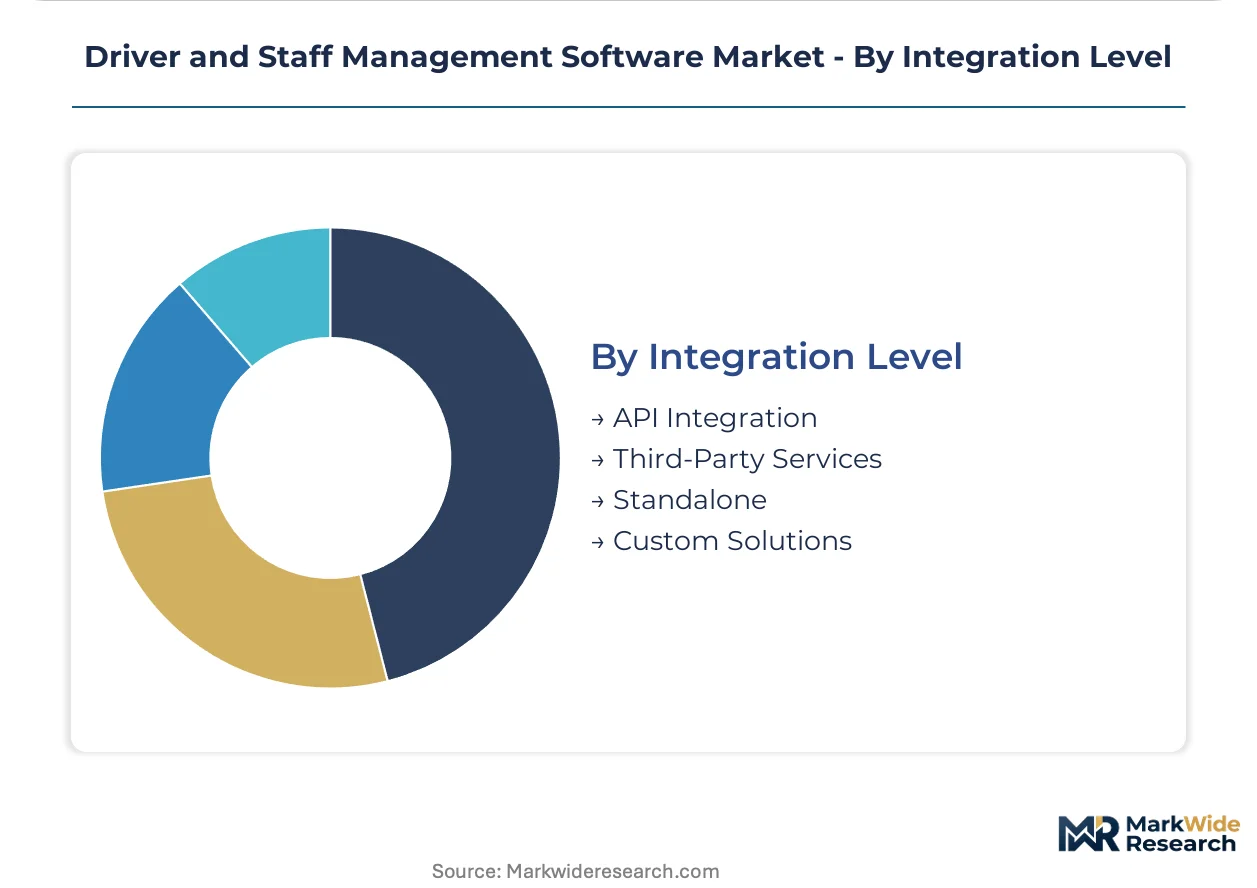
- API Integration:REST and GraphQL interfaces connect driver management platforms to ERP, TMS, and insurance data exchanges. Real-time webhooks enable instant safety alert propagation to dispatch centers. Engineering investment in documentation and SDK maintenance separates committed platform vendors from thin wrappers.
- Third-Party Services:Pre-built connectors to fuel card providers, weigh station bypass systems, and DOT medical certification databases reduce implementation timelines. Fragmented state-level examiner registries force costly custom development for national fleet deployments.
- Standalone:Self-contained systems serve small operators with limited IT infrastructure.
- Custom Solutions:Bespoke development addresses unique workflow requirements in specialized hauling segments.
API Integration carries the highest development investment while Third-Party Services capture procurement preference for speed-to-value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
In-house fleet operators concentrate procurement authority in the United States, while European logistics providers navigate algorithmic compliance mandates. Cloud-native platforms penetrate emerging digitization programs across India and Southeast Asia.
United States
Large for-hire carriers and private fleet operators drive integrated scheduling and analytics procurement. DOT hours-of-service enforcement and FMCSA ELD mandates shape platform functionality requirements. Dallas-Fort Worth and Atlanta logistics corridors anchor enterprise deployment clusters for cross-border freight operators.
Germany
Automotive and chemical logistics providers prioritize GDPR Article 22 audit capabilities for driver scoring systems. KBA vehicle certification and EU AI Act compliance timelines accelerate legacy platform replacement cycles. The Rhine-Ruhr industrial belt concentrates demand among chemical tanker and automotive parts carriers.
India
Third-party logistics expansion and e-commerce fulfillment networks fuel workforce coordination platform adoption. FASTag toll integration and upcoming national logistics platform standards create compliance-driven procurement windows. Mumbai-Pune and Bengaluru corridors concentrate digitization investment among surface transport operators.
United Kingdom
Last-mile delivery consolidation and urban congestion charging schemes elevate route optimization priorities. DVSA operator compliance scoring and emerging clean air zone mandates embed emissions tracking into driver performance systems. The Midlands logistics triangle anchors fleet technology procurement for pan-European operators.
Japan
Aging driver demographics and strict cargo safety regulations propel predictive analytics adoption. METI logistics efficiency guidelines and labor shortage mitigation programs subsidize workforce management digitization. The Tokyo-Osaka freight corridor concentrates platform deployment among parcel and temperature-controlled carriers.
Driver and Staff Management Software Market Competitive Landscape
Player mix skews toward IoT-native platform specialists and telematics incumbents with cellular network partnerships. The vendor base stratifies across enterprise-grade subscription providers, mid-market SaaS challengers, and hardware-anchored incumbents. Two archetypes dominate: telemetry-integrated platforms bundling compliance and analytics, and pure-software challengers unbundling scheduling from fleet hardware. Competitive moves center on API ecosystem expansion and insurance partnership anchoring.
Within the telemetry-integrated tier, Samsara and Motive exemplify IoT-native architectures that embed edge AI inference directly into dashcam hardware. Verizon Connect occupies a position anchored by dense North American cellular infrastructure partnerships. These three represent contrasting strategic postures: silicon-forward platform depth, AI-powered safety extension, and network-locked geographic dominance.
| Leading Market Players |
|---|
| Verizon Connect |
| Fleetio |
| Motive |
| Azuga |
| Omnitracs |
| Samsara |
| Lytx |
| Driver Schedule |
| Locus |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS architectures displacing on-premises installations are redrawing procurement geography toward US and EU software hubs while compressing price premiums for legacy single-tenant systems. This substitution simultaneously concentrates vendor development resources in cellular-dense metropolitan corridors and erodes margin buffers for hardware-anchored incumbents facing API commoditization.
Pricing Analysis
Next-generation edge AI inference platforms command substantial premiums over legacy cloud-upload dashcam systems and basic GPS logging hardware. Three-tier pricing structure across premium, standard, and economy levels separates real-time coaching systems with embedded silicon from delayed analytics and stripped compliance modules. Price differentiation hinges on GDPR Article 22 audit certification and insurance-linked data feed integration. Cost compression in the mid-market tier is intensifying because ERP vendors bundle lightweight fleet modules as loss-leader attachments. Small fleet operators acquiring through OEM captive finance show lowest price sensitivity, while independent third-party logistics providers face acute margin pressure.
Supply Chain Analysis
Telematics hardware inventory cycles have compressed from quarterly to monthly replenishment as semiconductor availability stabilizes and cellular module lead times normalize. Manufacturing concentrates in Taiwan for edge AI chip fabrication, Mexico for final device assembly serving North American demand, and Vietnam for cost-optimized GPS module production. Raw material dependencies span lithium-ion cells for battery-constrained installations, automotive-grade cellular modems, and CMOS image sensors for dashcam integration. Single-source vulnerability around Taiwan Semiconductor Manufacturing for advanced inference silicon creates concentration risk. Distribution runs through cellular carrier partnership channels and OEM captive finance arms rather than traditional software marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
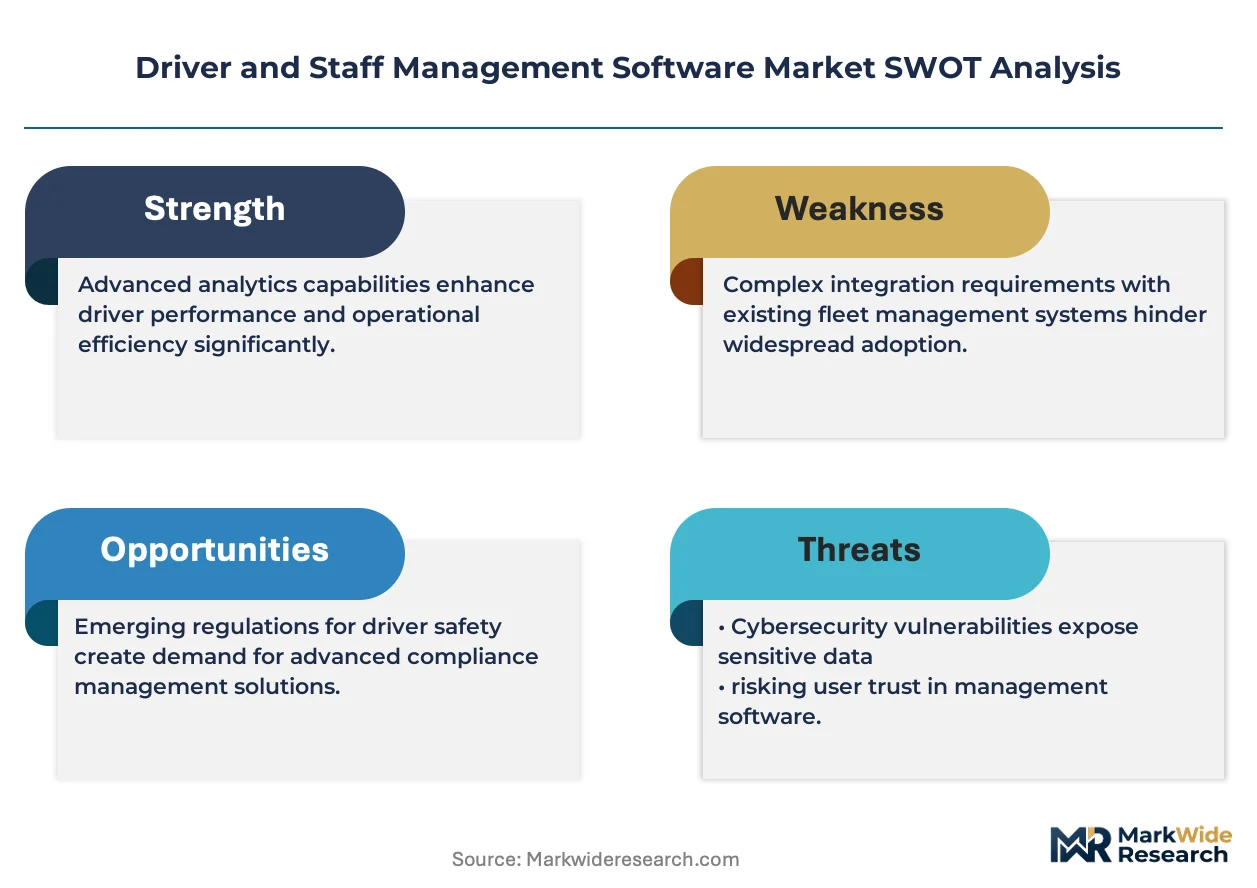
Firmware engineering talent capable of optimizing battery-constrained telematics installations represents the critical chokepoint constraining vendor expansion timelines and platform differentiation velocity.
For Market Incumbents: Consolidate API ecosystem control through exclusive partnerships with DOT-certified medical examiner databases, reducing fragmentation exposure that elevates integration costs for challengers. Deepen backward integration into edge AI silicon design partnerships to defend margin position against commodity dashcam vendors. Prioritize GDPR Article 22 compliance certification as a competitive moat against non-EU imports facing audit trail mandates. For New Entrants and Emerging Players: Lead with FASTag-compliant workforce coordination platforms targeting India's surface transport operators ahead of national logistics platform standardization. Focus initial penetration on mid-market delivery services in congested urban corridors where real-time traffic integration commands premium pricing. Pursue insurance partnership anchoring as the primary go-to-market mechanism, converting software from operational tool to policy prerequisite. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors IoT-native platforms with embedded regulatory engines over legacy scheduling specialists. Long-term viability across the analysis window hinges on recurring telematics subscription economics rather than perpetual license models. Target acquisition candidates with dense cellular carrier distribution partnerships and existing California CARB emissions scorecard deployments. Watch for EU AI Act enforcement actions against non-compliant driver scoring systems as the inflection signal indicating regulatory premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telematics, compliance logging, and performance analytics through API-connected data feeds. |
| Acquisition of Specialist Firm | Absorbs embedded systems engineering talent scarce in open labor markets. |
| Strategic Partnership | Secures exclusive cellular carrier distribution channels in North American logistics corridors. |
| Geographic Expansion | Establishes EU-sovereign cloud instances ahead of German and French national certification deadlines. |
| Product Launch | Introduces predictive maintenance modules marrying driver behavior with engine diagnostics. |
Research Methodology
Desk research of SEC filings from telematics platform vendors, FMCSA enforcement data, and EU regulatory impact assessments preceded structured interviews with fleet operations directors, DOT compliance officers, insurance underwriters, and cellular carrier IoT product managers. Primary fieldwork validated secondary findings around deployment timelines and procurement authority shifts. Bottom-up vehicle installation estimates triangulated against top-down SaaS subscription revenue disclosures.
Variance decomposition across cloud versus on-premises deployment models, fleet size tiers, and integration complexity levels structured the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product type, deployment architecture, end-user industry, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to historical ELD mandate penetration patterns. Forecast inputs incorporated insurance-linked contract penetration rates and EU AI Act compliance replacement cycle assumptions.
The analysis sits within stated boundaries; outcomes outside sustained cellular data cost stability and DOT medical examiner database standardization would require recalibration. Forecasts reflect documented assumptions around regulatory enforcement intensity and hardware miniaturization trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Anti-Plagiarism Software Market
Software & Services
Lawn Care Software Market
Software & Services
Orchestration Tools Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
BIM Objects Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Server Operating System Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Commercial Drone Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Asia-Pacific IT Services Market