
 Global Stereotactic Radiosurgery (Gamma Knife) Market | 2026-2036
Global Stereotactic Radiosurgery (Gamma Knife) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stereotactic Radiosurgery (Gamma Knife) Market Foresight
MDR certification timelines in Europe are decoupling smaller OEMs from premium hospital tenders. Elekta AB leverages its installed base across Nordic proton centers to sustain service-contract renewal rates above industry norms. Varian Medical Systems anchors North American academic medical centers through long-term linear accelerator trade-in programs. Masep Medical Science & Technology Development competes on capital-light leasing structures for tier-two hospitals in Shenzhen and Chengdu.
Stereotactic radiosurgery deploys multiple convergent cobalt-60 gamma beams or X-band linear accelerators to deliver sub-millimeter-precision ablative doses to intracranial and extracranial lesions without cranial fixation or incision. The Perfexion and Icon platforms dominate head-and-neck applications through automated collimator repositioning and real-time motion tracking during treatment. CyberKnife systems occupy the fastest-expanding slice of robotic radiosurgery, particularly for lung and pancreatic lesions where respiratory gating integrates with optical tracking. Oncology applications generate the deepest margin pools, though pain management and functional neurology cases are growing fastest in ambulatory surgery centers seeking to diversify beyond spinal injections.
FDA 510(k) pathways and MDR technical documentation requirements shape product development cadences and geographic launch sequencing for all active vendors. EMA notified body capacity constraints extend European approval timelines, pushing some manufacturers to prioritize Health Canada or TGA submissions. China's NMPA innovation fast-track channel accelerates domestic approvals for Huiheng Medical and Zhuhai Hokai Medical Instruments. Stakeholders must monitor cobalt-60 reactor maintenance schedules in Canada and Russia, as isotope supply interruptions would force treatment centers toward electron-based alternatives faster than capital replacement cycles allow.
Market Dynamics
Cobalt-60 supply concentration in Canadian and Russian reactor facilities is forcing treatment centers to accelerate electron-based system evaluation ahead of planned capital cycles, while CMS episode-based reimbursement models in the United States reshape hospital procurement mathematics.
Growth Catalysts
- MDR fast-track pathways:China's NMPA innovation channel accelerates domestic manufacturer approvals, compressing time-to-tender for university hospital networks in Shenzhen and Chengdu.
- Episode-based payment models:United States CMS frameworks reward outpatient radiosurgery completion, pulling cases from inpatient surgical queues into ambulatory settings.
- Respiratory gating integration:Optical tracking convergence with robotic delivery systems is expanding treatable lesion pools beyond intracranial to lung and pancreatic sites.
Market Restraints
- Isotope supply fragility:Cobalt-60 sourcing from NRU Chalk River and Mayak Production Association reactors creates single-point vulnerability for gamma-based treatment centers.
- Capital intensity barriers:Shielding requirements and vault construction costs exclude community hospitals from radiosurgery program launches.
- MDR technical documentation:EMA notified body capacity constraints extend European approval timelines, delaying platform launches by 18-24 months.
Strategic Opportunities
- Ambulatory surgery center penetration:Pain management and functional neurology cases in United States outpatient settings remain underpenetrated relative to oncology volumes.
- Proton-photon consolidation:German university hospital networks are merging capabilities under single rooflines, creating integrated service contract opportunities.
- Leasing structure innovation:Capital-light models for tier-two hospitals in China's interior provinces bypass traditional equipment financing bottlenecks.
Industry Challenges
- Medical physics talent scarcity:Treatment planning complexity and quality assurance protocols outpace specialized workforce supply in emerging markets.
- Legacy linear accelerator integration:Trade-in programs require seamless data migration from cobalt-based historical treatment records to new platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stereotactic Radiosurgery (Gamma Knife) Market |
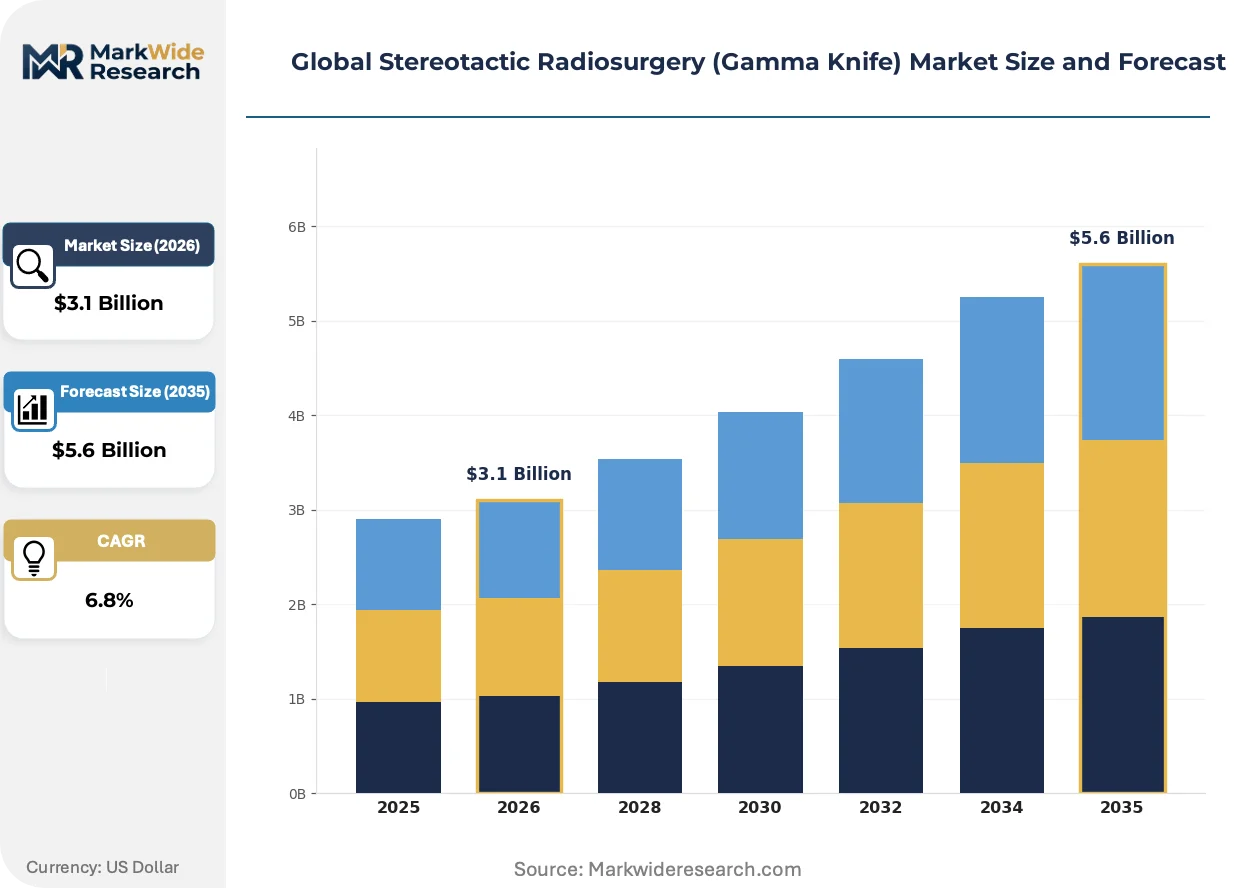
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Gamma Knife, Perfexion, Icon, CyberKnife End User: Hospitals, Clinics, Ambulatory Surgery Centers, Research Institutions Application: Oncology, Neurology, Pain Management, Vascular Disorders Technology: Robotic Radiosurgery, Linear Accelerators, Stereotactic Techniques, Imaging Integration |
| Companies Covered | Zhuhai Hokai Medical Instruments, Huiheng Medical, Elekta AB, Solera Health Company, Akesis, Varian Medical Systems, Masep Medical Science & Technology Development (Shenzhen), ET Medical Group, Accuray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stereotactic Radiosurgery (Gamma Knife) Market Shifts & Advancements
Real-time motion tracking during treatment delivery is compressing the precision gap between cranial fixation systems and frameless extracranial applications, while regulatory documentation requirements reshape product development cadences across all active vendors.
Robotic optical tracking is rewriting the treatable anatomy map for radiosurgery systems. Frameless intracranial delivery through real-time patient position monitoring eliminates invasive fixation hardware. Academic medical centers in Germany and the United States are adopting these platforms for spinal and lung lesions previously excluded from radiosurgery protocols. The technology is rewriting capital allocation patterns as hospitals defer proton center investments in favor of photon-based robotic systems.
MDR technical documentation requirements in Europe are extending approval timelines beyond historical CE-marking windows. EMA notified body capacity constraints force manufacturers to sequence geographic launches, prioritizing Health Canada or TGA submissions ahead of European market entry. High-complexity class III devices face the longest delays, pushing some vendors toward 510(k) FDA pathways for initial revenue recognition.
Service contract unbundling is fragmenting the traditional equipment-plus-maintenance bundle. Hospital procurement teams in the United States are negotiating separate technical support, software upgrade, and isotope logistics agreements. Academic medical centers with in-house medical physics capabilities increasingly self-perform quality assurance, purchasing parts-only coverage. This pattern is most visible in Medicare-dependent systems seeking to reduce per-case overhead denominators.
Global Stereotactic Radiosurgery (Gamma Knife) Market Segmentation
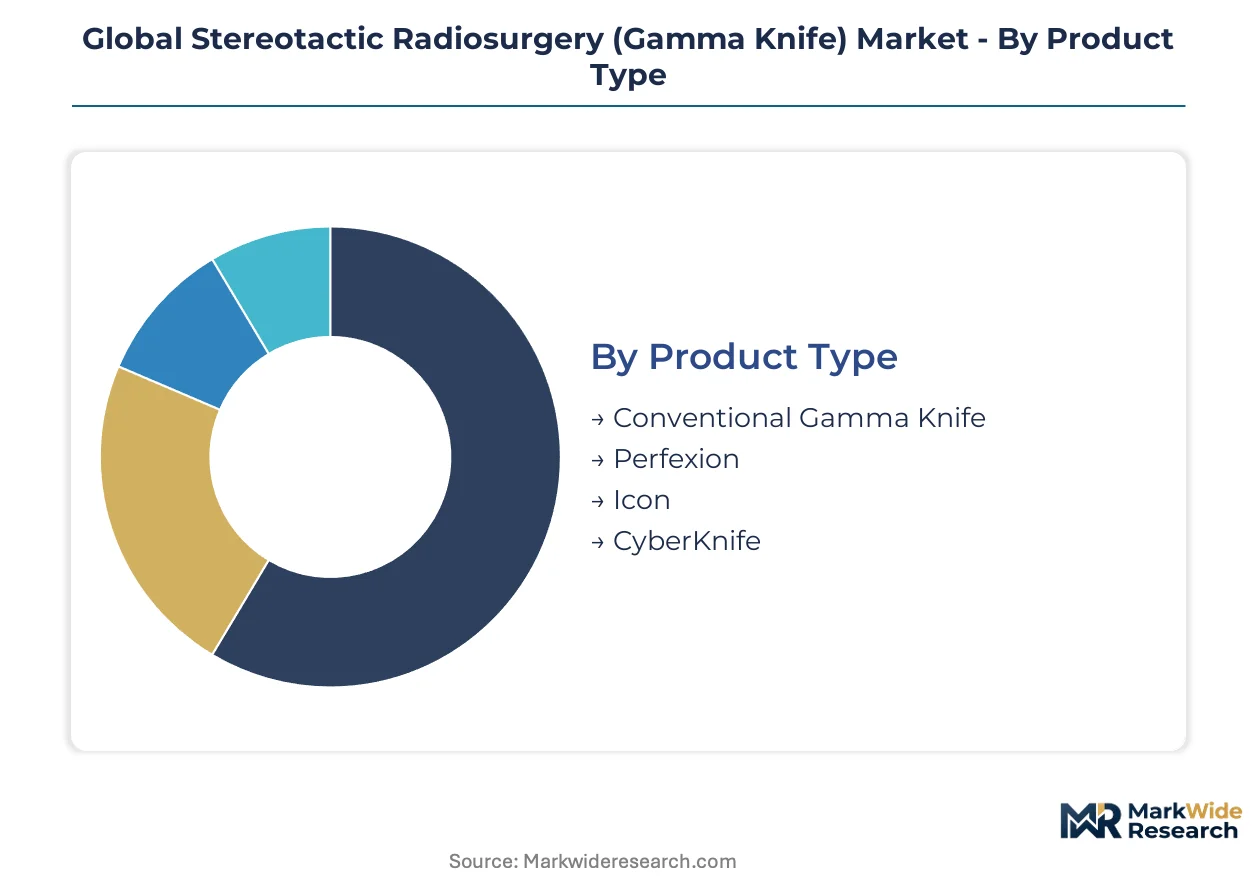
Segmentation in the stereotactic radiosurgery market reveals distinct capital requirements, clinical workflows, and reimbursement pathways that shape vendor go-to-market strategies. Product platforms diverge sharply in shielding costs and isotope dependencies, while end-user settings determine service contract structures and utilization economics.
Product Type:
Capital intensity varies dramatically across product platforms, with cobalt-60-based systems demanding specialized vault construction and robotic alternatives requiring precision motion control infrastructure.
- Conventional Gamma Knife:Legacy cobalt-60 beam array systems with fixed collimator helmets and invasive cranial fixation frames. Demand concentrates in established academic medical centers in Germany and Japan seeking high-throughput intracranial programs; isotope supply fragility from Canadian and Russian reactors constrains new installations.
- Perfexion:Automated collimator repositioning platform eliminating manual helmet changes and expanding treatable lesion coordinates. University hospital networks in the United States and Nordic proton centers prioritize Perfexion for its throughput advantages; CMS episode-based reimbursement rewards outpatient completion rates this platform enables.
- Icon:Frameless intracranial delivery through real-time patient position monitoring and integrated cone-beam CT. Tier-one hospitals in Shenzhen and Chengdu deploy Icon for expanded patient eligibility.
- CyberKnife:Robotic optical tracking system with respiratory gating for lung and pancreatic lesions. Ambulatory surgery centers in the United States favor CyberKnife for extracranial expansion without proton center investments.
Conventional Gamma Knife absorbs the bulk of installed capacity; CyberKnife is expanding most quickly.
End User:
Customer type determines procurement authority, with consolidated health systems leveraging volume commitments against independent centers negotiating equipment-only arrangements.
- Hospitals:Comprehensive oncology and neurosurgery departments with in-house medical physics capabilities. German university hospital networks consolidate proton and photon capabilities under single rooflines, creating integrated service opportunities.
- Clinics:Specialized neuro-oncology and pain management facilities with limited vault construction budgets. Clinics in India's tier-two cities face capital intensity barriers from shielding requirements.
- Ambulatory Surgery Centers:Outpatient settings diversifying beyond spinal injections into functional neurology and pain management. United States Medicare-dependent systems seek to reduce per-case overhead through self-performed quality assurance.
- Research Institutions:Academic medical centers with NIH or EU Horizon funding for clinical trial infrastructure. Research Institutions in Boston and Heidelberg drive protocol development for novel indications.
Hospitals command the deepest equipment budgets; Ambulatory Surgery Centers are climbing the fastest as CMS frameworks pull cases from inpatient queues.
Application:
Clinical indication shapes treatment planning complexity and reimbursement coding, with oncology generating established margin pools and emerging applications requiring indication-specific training investments.
- Oncology:Primary brain metastases, skull base tumors, and recurrent gliomas with established radiosurgery protocols. Oncology applications dominate revenue concentration in United States academic medical centers with long-term linear accelerator trade-in programs.
- Neurology:Arteriovenous malformations, trigeminal neuralgia, and essential tremor with functional targeting requirements. Neurology cases are gaining share fastest in German university networks combining proton and photon expertise.
- Pain Management:Spinal metastases and phantom limb syndrome with frameless extracranial delivery. Pain Management represents underpenetrated volume in United States ambulatory settings seeking surgical alternatives.
- Vascular Disorders:Cavernous malformations and dural arteriovenous fistulas requiring sub-millimeter precision. Vascular Disorders attract research funding at institutions with integrated imaging capabilities.
Oncology retains the largest treatment volume base; Pain Management shows the steepest expansion trajectory as outpatient settings diversify service lines.
Technology:
Technical architecture determines regulatory pathway complexity, with robotic systems facing novel device scrutiny and imaging integration platforms leveraging predicate device clearances.
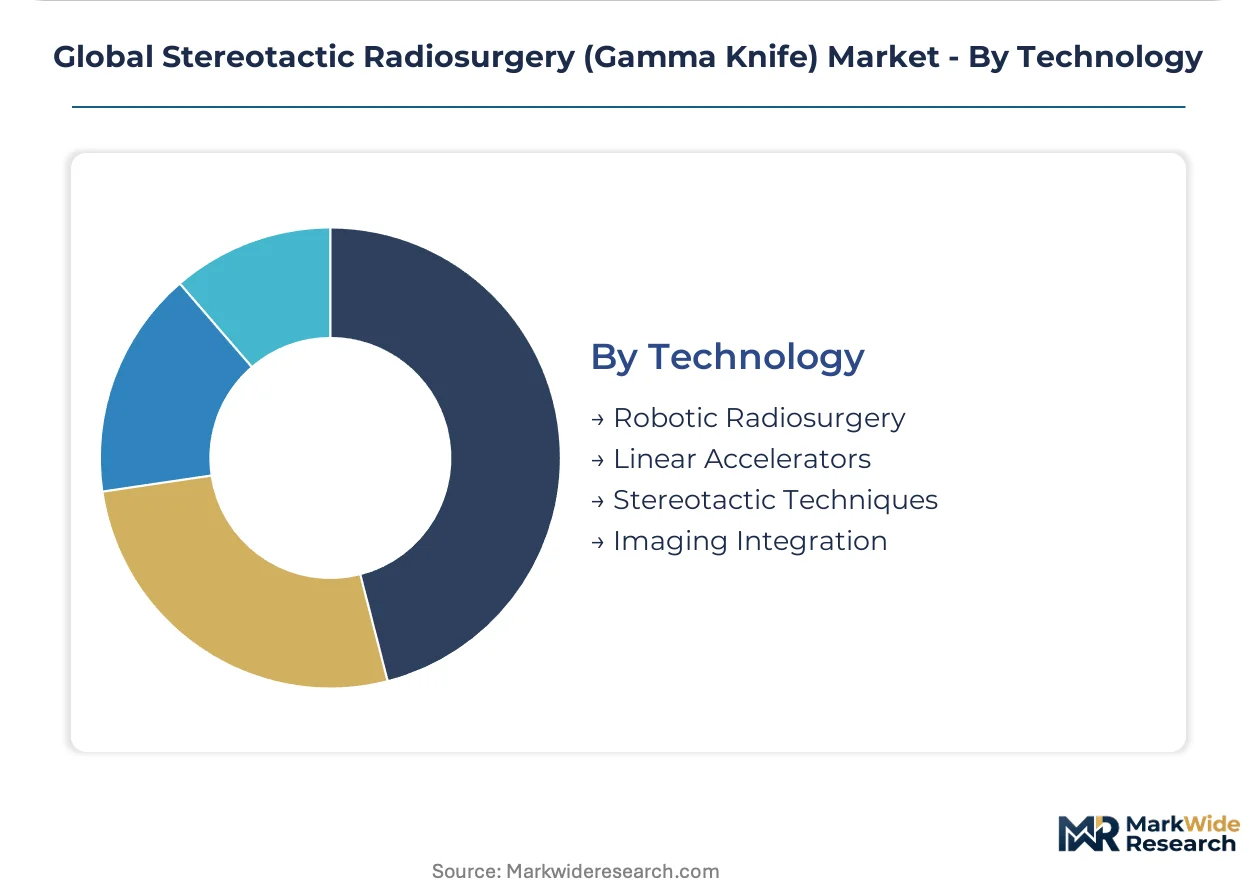
- Robotic Radiosurgery:Optical tracking convergence with six-axis robotic delivery for real-time motion compensation. Robotic Radiosurgery platforms occupy the fastest-expanding slice of lung and pancreatic applications.
- Linear Accelerators:X-band and C-band systems with flattening-filter-free beams for high dose-rate delivery. Linear Accelerators benefit from cobalt-60 supply fragility pushing centers toward electron-based alternatives.
- Stereotactic Techniques:Frame-based and frameless coordinate systems with invasive and non-invasive fixation. Stereotactic Techniques span all product platforms with technique selection driven by lesion location.
- Imaging Integration:Cone-beam CT, MRI fusion, and real-time planar imaging for adaptive planning. Imaging Integration requirements extend MDR technical documentation timelines for European launches.
Linear Accelerators capture the majority of new system evaluations; Robotic Radiosurgery is expanding most quickly as respiratory gating opens extracranial treatable anatomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, China, Japan, and India, where university hospital networks and ambulatory surgery centers drive system procurement. Each market exhibits distinct regulatory pathways and reimbursement frameworks that shape vendor entry strategies.
United States
Academic medical centers in Boston and Houston anchor system installations through long-term linear accelerator trade-in programs. FDA 510(k) pathways enable faster platform launches than European MDR timelines. CMS episode-based payment models pull cases from inpatient surgical queues into ambulatory settings across Medicare-dependent systems in the Southeast and Midwest.
Germany
University hospital networks in Heidelberg and Munich consolidate proton and photon capabilities under single rooflines. EMA notified body capacity constraints extend technical documentation reviews for new platform entries. Baden-Württemberg and Bavaria host the deepest installed bases of Perfexion and Icon systems in Europe.
China
Tier-one hospitals in Shenzhen and Chengdu deploy Icon platforms for expanded patient eligibility. NMPA innovation fast-track channels accelerate domestic manufacturer approvals for Huiheng Medical and Zhuhai Hokai Medical Instruments. Interior provinces face capital intensity barriers that capital-light leasing structures attempt to bypass.
Japan
Established academic medical centers in Tokyo and Osaka maintain high-throughput intracranial programs on legacy cobalt-60 systems. PMDA regulatory frameworks align with FDA precedent, enabling synchronized launch sequencing. METI industrial policy supports domestic imaging integration capabilities for next-generation platforms.
India
Tier-two cities face exclusion from radiosurgery program launches due to shielding requirements and vault construction costs. CDSCO regulatory pathways remain underdeveloped for high-complexity class III devices. Maharashtra and Karnataka concentrate private hospital investments in robotic optical tracking systems.
Global Stereotactic Radiosurgery (Gamma Knife) Market Competitive Landscape
Swedish and American producers anchor the premium equipment tier; Chinese specialists hold the capital-efficient mid-market segment. The vendor base organizes around three strategic archetypes: integrated radiation therapy conglomerates with linear accelerator portfolios, dedicated radiosurgery pure-plays with cobalt-60 heritage, and domestic challengers leveraging regulatory fast-tracks. Competitive moves center on service contract unbundling and proton-photon consolidation partnerships.
Within the integrated therapy tier, Elekta AB and Varian Medical Systems exemplify archetypes with divergent geographic emphases. Masep Medical Science & Technology Development occupies a distinct position among Shenzhen-based challengers capitalizing on NMPA acceleration channels. These three anchors represent the spectrum from premium academic medical center penetration to tier-two hospital leasing innovation.
| Leading Market Players |
|---|
| Zhuhai Hokai Medical Instruments |
| Huiheng Medical |
| Elekta AB |
| Solera Health Company |
| Akesis |
| Varian Medical Systems |
| Masep Medical Science & Technology Development (Shenzhen) |
| ET Medical Group |
| Accuray |
| Others |
Supply & Pricing Matrix
Academic medical centers in the United States and university hospital networks in Germany concentrate procurement authority for gamma knife systems, anchoring contract-based long-term offtake pricing that bundles equipment, isotope logistics, and service coverage into multi-year agreements. This buyer concentration creates pricing power asymmetries that favor established OEMs with installed base leverage while squeezing tier-two vendors competing on capital-light leasing structures.
Pricing Analysis
Short lead times for cobalt-60 isotope replenishment command premium pricing from treatment centers facing reactor maintenance schedules in Canada and Russia. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive service contracts from parts-only coverage and bare equipment procurement. Cost compression in the mid-market tier is intensifying because NMPA fast-track approvals enable domestic Chinese manufacturers to undercut imported platform pricing. Community hospitals and ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers with NIH funding prioritize throughput optimization over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements for cobalt-60 isotopes mandate multi-supplier qualification across NRU Chalk River in Canada and Mayak Production Association in Russia, though reactor concentration creates persistent single-point vulnerability. System manufacturing draws from precision machining clusters in Germany, electronic motion control suppliers in Japan, and software development centers in the United States. Tariff exposure on medical device components shipped into China threatens margin stability for non-domestic vendors. Distribution runs through direct OEM sales forces for tier-one hospitals and specialized medical device distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDR technical documentation requirements in Europe construct a cost-of-compliance moat that disadvantages smaller OEMs and protects incumbents with dedicated regulatory affairs infrastructure. EMA notified body capacity constraints extend approval timelines, creating barrier-to-entry dynamics that reward early certification investments.
For Market Incumbents: Deepen service contract unbundling capabilities to capture self-performed quality assurance trends among Medicare-dependent systems. Fortify cobalt-60 supply relationships through forward isotope purchase agreements that lock in reactor capacity ahead of maintenance cycles. Acquire robotic optical tracking specialists to defend against CyberKnife displacement in lung and pancreatic applications.
For New Entrants and Emerging Players: Enter via capital-light leasing structures for tier-two hospitals in China's interior provinces, bypassing traditional equipment financing bottlenecks that exclude community facilities. Target pain management and functional neurology cases in United States ambulatory surgery centers, the most penetrable segment relative to established oncology volumes. Pursue NMPA innovation fast-track channel qualification to compress time-to-tender against imported competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic Chinese manufacturers with regulatory fast-track access in Shenzhen and Chengdu, positioned to consolidate as capital intensity barriers eliminate smaller competitors. Long-term viability hinges on electron-based system portfolios that circumvent cobalt-60 supply fragility. Watch FDA 510(k) pathway prioritization as signal of vendor geographic launch sequencing and revenue recognition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA notified body engagement accelerates European market entry for MDR-compliant platforms. |
| Hospital System Partnership | Integrated service contracts with German university networks consolidate proton-photon capabilities under single rooflines. |
| Reimbursement Strategy | CMS episode-based payment model alignment pulls inpatient surgical cases into outpatient radiosurgery settings. |
| Software Companion Development | Real-time motion tracking integration expands treatable lesion pools beyond intracranial to lung and pancreatic sites. |
| Backward Integration into Isotope Supply | Direct reactor relationships with Canadian and Belgian facilities mitigate cobalt-60 sourcing concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and medical physicists across the United States, Germany, China, and Japan. FDA 510(k) clearances, EMA MDR technical documentation submissions, NMPA innovation fast-track approvals, and CMS reimbursement rulemaking provided structured regulatory intelligence. Bottom-up installation database construction triangulated against top-down equipment manufacturer revenue segmentation.
Country-level modeling captured regulatory pathway complexity, reimbursement framework evolution, and hospital procurement authority concentration across the projection horizon. Product platform segmentation modeled capital intensity variations, isotope dependencies, and service contract structures. End-user segmentation distinguished academic medical center, community hospital, ambulatory surgery center, and research institution economics. Application segmentation tracked oncology, neurology, pain management, and vascular disorder case volumes. Technology segmentation evaluated robotic radiosurgery, linear accelerator, stereotactic technique, and imaging integration adoption trajectories. CAGRs derived from equipment shipment forecasts, replacement cycle assumptions, and indication expansion rates.
Revisions become necessary when cobalt-60 reactor maintenance schedules extend beyond planned outages, MDR notified body capacity constraints worsen, or CMS episode-based payment models shift reimbursement thresholds. Deviation in isotope supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Autoclaves Market
Medical Equipment
Cath Lab Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Operating Table Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Proctologic Table Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market