
 Global Punch and Die Storage Cabinet Market | 2026-2036
Global Punch and Die Storage Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Punch and Die Storage Cabinet Market Outlook
ISO 9001 quality management certification is unwinding the competitive field for punch and die storage cabinet suppliers, filtering out fabricators lacking documented traceability protocols. LISTA International Corporation leverages its vertical integration across sheet metal forming and locking hardware to sustain premium positioning in North American tooling supply chains. Rousseau Metal Inc. anchors its competitiveness through Quebec-based manufacturing scale serving Canadian and US automotive stamping plants. Stanley Vidmar differentiates via modular drawer systems engineered for heavy die sets up to 2,000-pound capacity.
Punch and die storage cabinets are enclosed, lockable industrial furniture systems fabricated from cold-rolled steel or aluminum extrusion, designed to organize, protect, and inventory metal forming tools through configurable drawer heights, load-rated slides, and identification labeling systems. Their primary commercial purpose is reducing tool changeover downtime and preventing corrosion or dimensional drift in precision stamping environments. Steel material construction dominates current procurement volumes due to its load-bearing capacity and weldability, though aluminum segments are gaining traction in aerospace cleanroom applications where weight reduction and non-sparking properties matter. Mobile cabinet configurations represent the fastest-expanding product type as just-in-time manufacturing layouts demand reconfigurable shop floors rather than fixed tool crib installations.
OSHA workplace safety standards in the United States govern load labeling and tip-prevention anchoring for industrial storage systems exceeding specified height-to-depth ratios. The EU Machinery Directive, enforced through CE marking requirements, mandates interlock mechanisms on sliding door cabinets to prevent crushing hazards during tool retrieval. China's GB standards for metal furniture specify corrosion resistance testing protocols that shape export qualification costs for foreign suppliers. Stakeholders must monitor evolving national building codes for seismic zone requirements that could force structural reinforcement redesigns in Pacific Rim manufacturing clusters.
Market Dynamics
Automotive stamping plants are consolidating tool crib footprints into centralized inventory hubs, compressing procurement timelines and forcing cabinet suppliers to engineer higher-density drawer configurations that accommodate heavier die sets within shrinking floor space allocations.
Growth Catalysts
- Automotive Stamping Inventory Programs:Tier-1 suppliers are expanding tooling management infrastructure to support electric vehicle platform launches, creating sustained demand for load-rated storage systems.
- REACH Compliance in the European Union:Powder-coated steel finishes with reduced volatile organic compound emissions are displacing solvent-based coatings, qualifying compliant cabinet fabricators for premium public-sector contracts.
- Stuttgart-Dortmund Industrial Belt:Germany's precision metalworking cluster is driving specification upgrades toward corrosion-resistant configurations with integrated RFID tracking capabilities.
Market Restraints
- Cold-Rolled Steel Input Volatility:Raw material price swings compress margin stability for fabricators lacking long-term supply agreements with integrated mills.
- Chinese Export Qualification Costs:GB standards corrosion resistance testing protocols impose non-trivial compliance burdens on foreign suppliers seeking market access.
- Fixed Tool Crib Substitution:Mobile racking systems and vertical lift modules are capturing share in greenfield facilities with reconfigurable layout requirements.
Strategic Opportunities
- Aerospace Cleanroom Applications:Aluminum extrusion cabinets with non-sparking properties are penetrating precision aircraft component facilities where weight reduction commands specification priority.
- Seismic Zone Building Codes:Pacific Rim manufacturing clusters facing reinforced structural requirements create upgrade cycles for anchored heavy-load storage systems.
- Just-in-Time Manufacturing Layouts:Mobile cabinet configurations with castor-mounted bases are displacing fixed installations as automotive plants adopt modular production cells.
Industry Challenges
- Weld Certification Talent Scarcity:Fabricators face pipeline constraints for AWS-certified welders capable of executing load-bearing joint specifications on heavy-capacity drawer systems.
- CE Marking Interlock Integration:EU Machinery Directive compliance timelines extend product development cycles for sliding door mechanisms with crush-prevention electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Punch and Die Storage Cabinet Market |
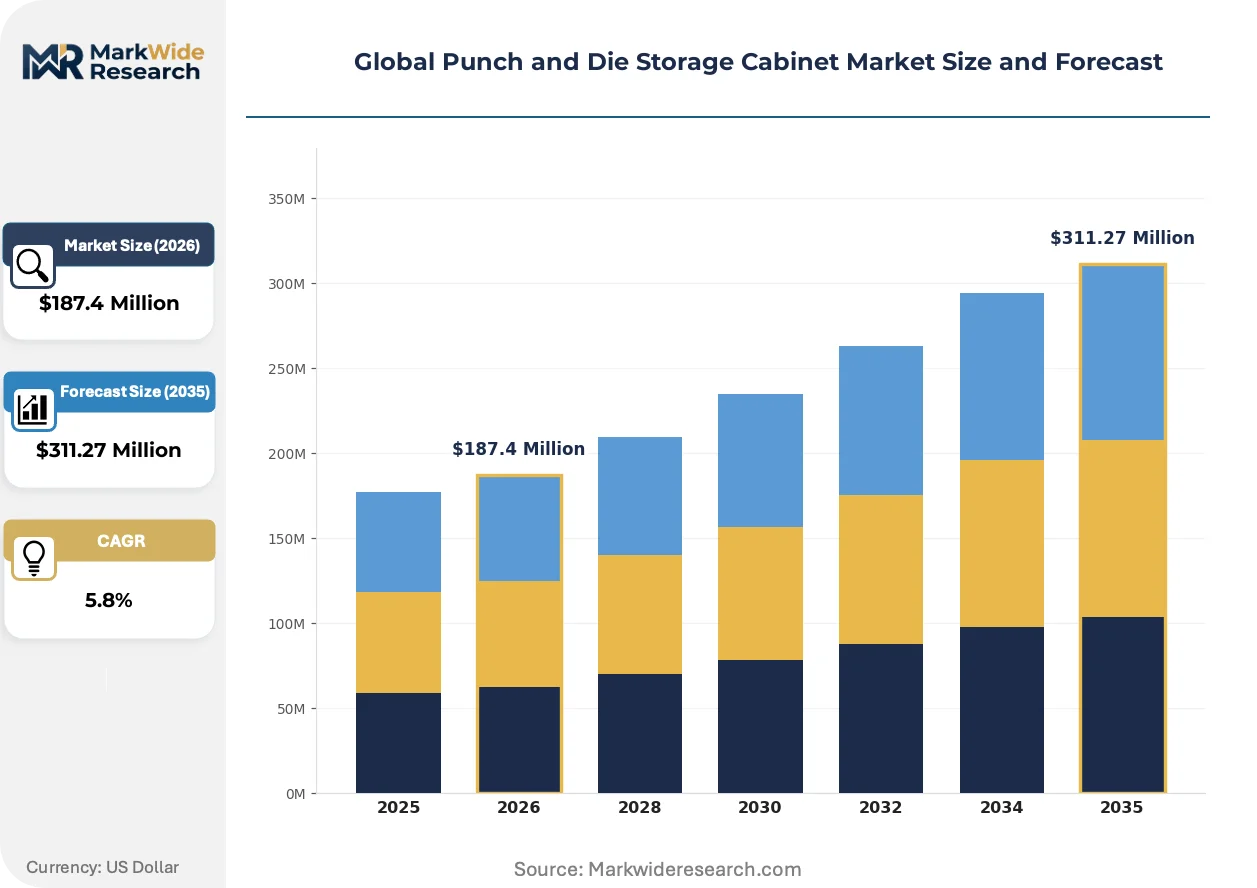
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Door, Double Door, Sliding Door, Mobile Cabinet Material: Steel, Aluminum, Plastic, Wood Application: Manufacturing, Automotive, Aerospace, Electronics End User: OEMs, Tooling Companies, Repair Shops, Fabricators |
| Companies Covered | LISTA International Corporation, Stanley Vidmar, Rousseau Metal Inc., Hanel Storage Systems, Strong Hold Products, Husky Rack & Wire, Akro-Mils, Lyon Workspace Products, Durham Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Punch and Die Storage Cabinet Market Strategic Shifts
Storage system architecture is splitting between maximal-density fixed installations and reconfigurable mobile platforms, with specification divergence accelerating as end-users prioritize either inventory consolidation or floor plan flexibility.
RFID-enabled drawer tracking is bifurcating the supplier base between integrated smart-system providers and commodity fabricators. Aerospace and medical device stampers are adopting embedded sensor arrays at pace, while general metalworking shops delay capital deployment. This technology compression is forcing mid-tier suppliers to choose between licensing IoT platforms or ceding specification authority to vertically integrated competitors.
OSHA load labeling mandates are tightening enforcement across US metalworking facilities. Inspectors are flagging unmarked cabinets exceeding height-to-depth thresholds, triggering retrofit orders. Heavy-capacity die storage lines face the steepest compliance costs as tip-prevention anchoring requirements add engineering complexity to existing installations.
Buyer concentration among automotive OEMs is compressing vendor qualification timelines. Tier-1 stampers now demand ISO 9001 traceability documentation as a baseline entry requirement, displacing uncertified regional fabricators from approved supplier lists. This consolidation is most visible in Michigan and Ontario automotive corridors where tooling procurement has centralized under consolidated supplier development programs.
Global Punch and Die Storage Cabinet Market Segmentation
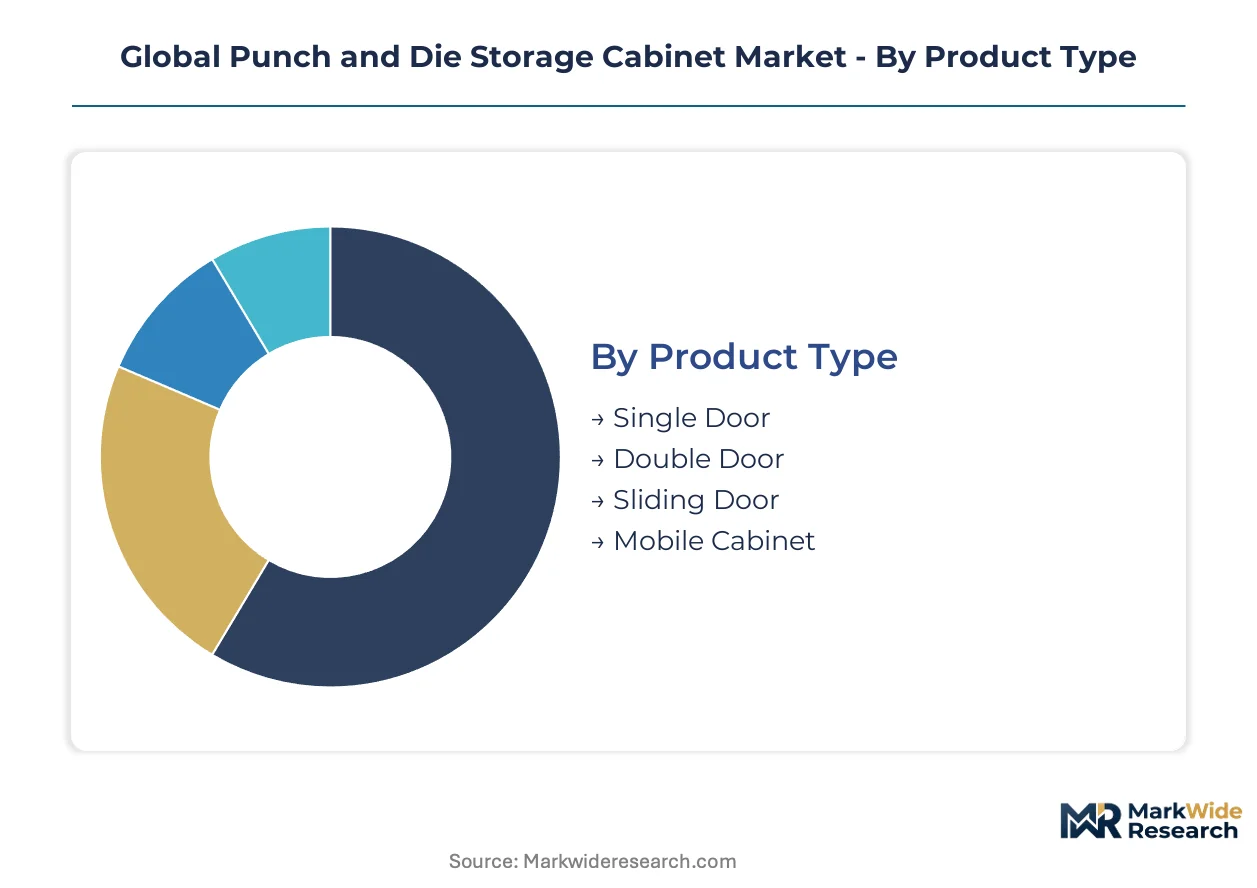
Punch and die storage cabinets serve heterogeneous operational requirements across metalworking environments. Specification divergence between fixed industrial installations and mobile reconfigurable units creates distinct procurement channels with different margin structures and certification demands.
Product Type:
Geographic demand spreads unevenly across these configurations, with fixed installations dominating established industrial corridors while mobile units penetrate export markets and greenfield facilities seeking layout flexibility.
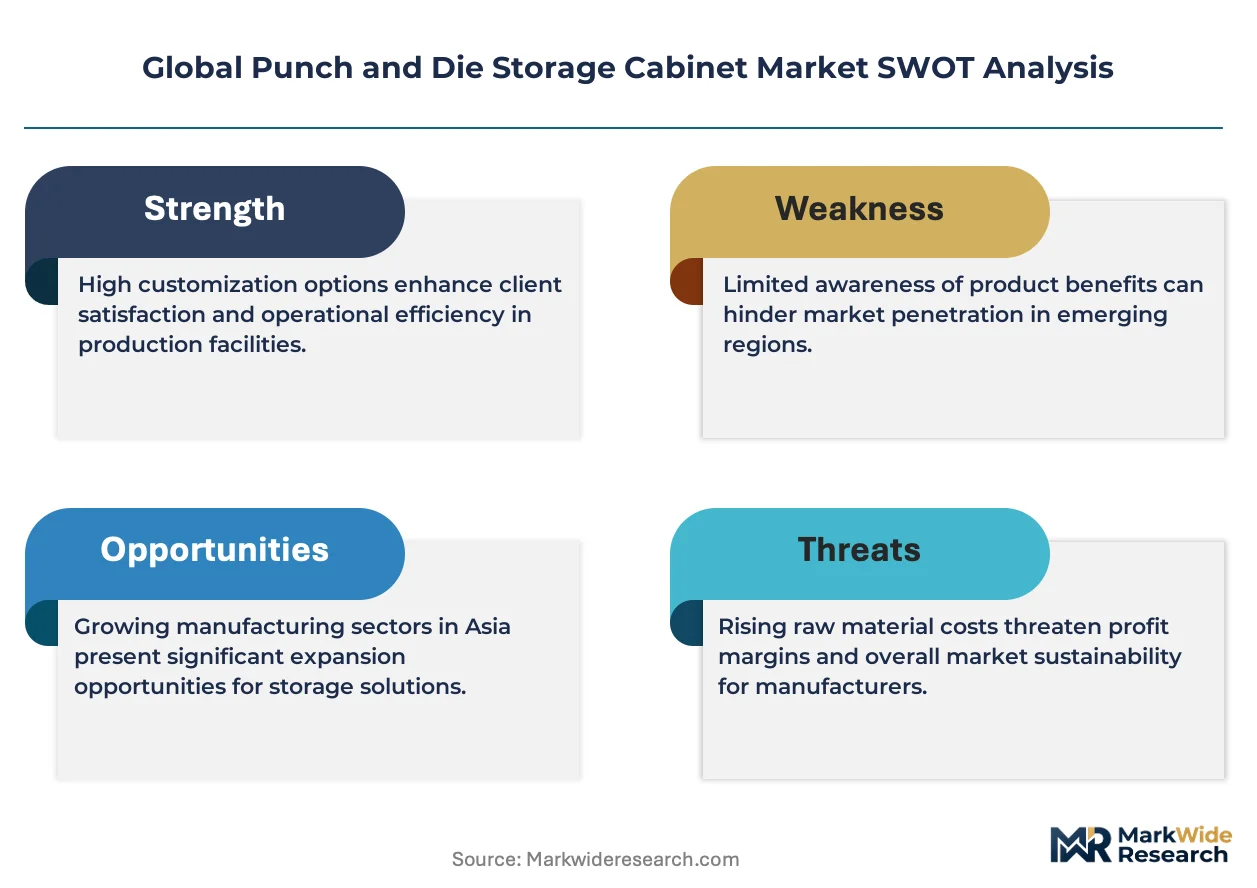
- Single Door:Compact vertical units with hinged access panels suit confined tool crib footprints in legacy stamping plants. Procurement concentrates in Germany's Stuttgart-Dortmund belt where space-constrained facilities prioritize density over reconfigurability.
- Double Door:Wide-opening cabinet architecture accommodates oversized die sets through dual hinged panels. Demand clusters in US automotive stamping corridors where OSHA load labeling mandates and tip-prevention anchoring requirements shape specification priorities.
- Sliding Door:Horizontal access mechanisms with interlock electronics satisfy EU Machinery Directive CE marking requirements for crush prevention. Export qualification costs limit penetration by uncertified fabricators.
- Mobile Cabinet:Castor-mounted bases enable just-in-time manufacturing cell reconfiguration. Fastest-expanding configuration as automotive plants abandon fixed tool crib models.
Single Door holds the largest share; momentum sits with Mobile Cabinet.
Material:
Cost tiers separate premium load-bearing specifications from economy alternatives, with raw material volatility compressing margin stability at the commodity end of the spectrum.
- Steel:Cold-rolled construction dominates procurement volumes through superior weldability and load ratings up to 2,000-pound capacity. REACH-compliant powder-coated finishes displace solvent-based coatings in EU public-sector contracts.
- Aluminum:Extrusion-based cabinets with non-sparking properties penetrate aerospace cleanrooms and precision aircraft component facilities where weight reduction commands specification priority.
- Plastic:Polymer construction serves light-duty organizational requirements in electronics assembly environments with minimal load demands and corrosion sensitivity.
- Wood:Limited to specialty workshop applications requiring acoustic dampening or aesthetic integration with existing furniture systems.
Steel commands volume leadership; Aluminum climbs the fastest on aerospace specification upgrades.
Application:
End-use maturity varies sharply, with established metalworking sectors maintaining replacement cycles while emerging precision manufacturing segments drive technology integration requirements.
- Manufacturing:General metalworking shops represent the installed base majority, though RFID adoption lags aerospace and medical device stampers due to capital deployment delays.
- Automotive:Tier-1 suppliers expanding tooling management infrastructure for electric vehicle platform launches create sustained demand for load-rated storage systems with ISO 9001 traceability documentation.
- Aerospace:Cleanroom-grade specifications with embedded sensor arrays and aluminum construction command premium positioning against commodity fabricators.
- Electronics:Precision component facilities prioritize non-sparking properties and weight reduction in high-value, low-volume production environments.
Manufacturing retains the deepest installed base; Automotive generates the steepest expansion trajectory.
End User:
Customer type concentration shapes vendor qualification intensity, with consolidated procurement programs filtering uncertified suppliers from approved vendor lists.
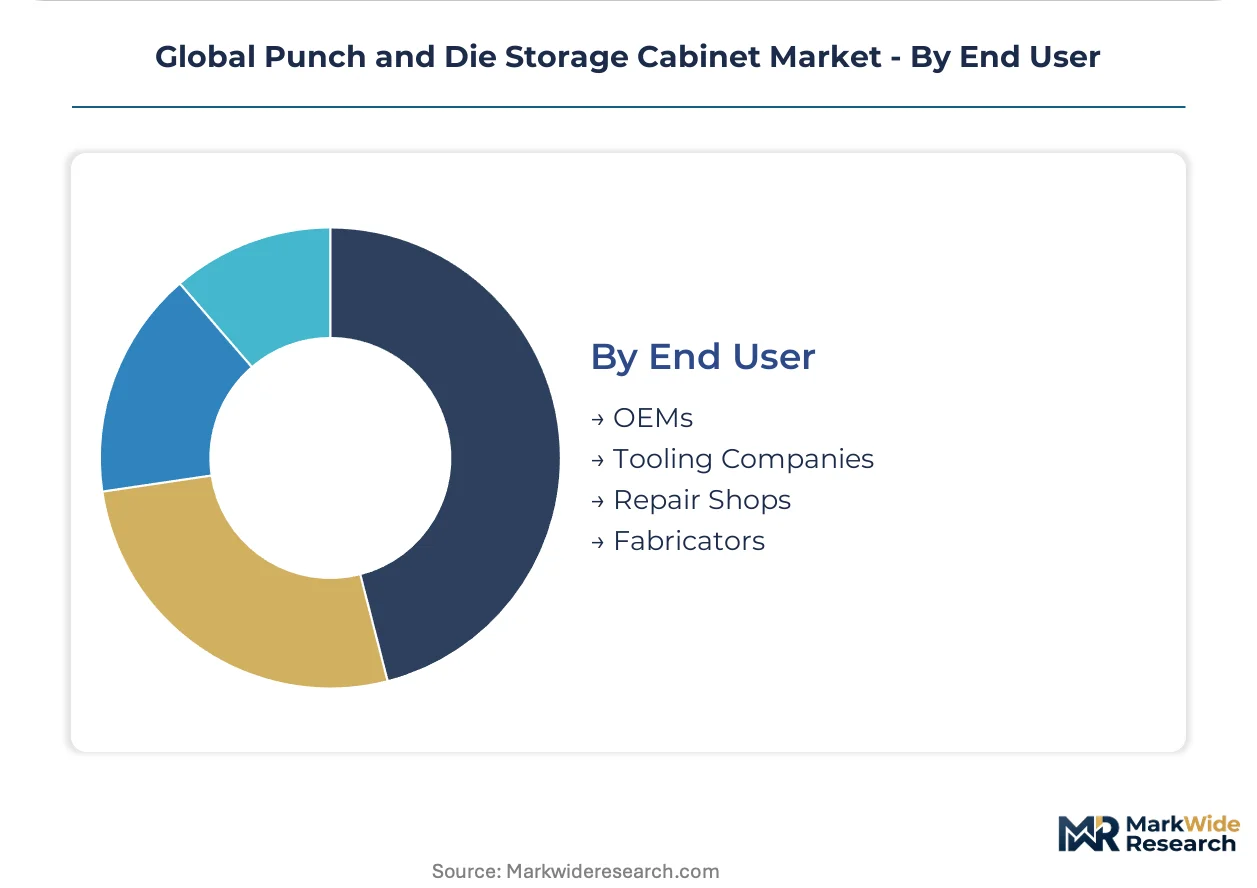
- OEMs:Original equipment manufacturers operate centralized supplier development programs demanding documented quality management certification as baseline entry requirement.
- Tooling Companies:Specialized die and mold producers maintain diverse cabinet inventories across multiple client specifications, requiring flexible procurement relationships.
- Repair Shops:Independent maintenance facilities prioritize cost efficiency over advanced tracking capabilities, sustaining demand for standard steel configurations.
- Fabricators:Custom metalworking job shops favor mobile reconfigurable units supporting variable production layouts and rapid tool changeover protocols.
OEMs anchor procurement volume; Fabricators show the fastest uptake of mobile configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's central European logistics position for precision metalworking equipment distribution. Rail corridors from Rotterdam and Antwerp feed industrial clusters across the continent. Pacific container traffic through the Ports of Los Angeles and Long Beach underwrites North American tooling supply chains.
United States
Automotive stamping plants in Michigan and Ohio are consolidating tool crib footprints into centralized inventory hubs. OSHA workplace safety standards govern load labeling and tip-prevention anchoring for industrial storage systems exceeding specified height-to-depth ratios. The Detroit-Windsor corridor drives specification upgrades toward heavy-capacity die storage lines with documented ISO 9001 traceability.
Germany
REACH compliance is pushing manufacturers toward powder-coated steel finishes with lower volatile organic compound emissions. The EU Machinery Directive, enforced through CE marking requirements, mandates interlock mechanisms on sliding door cabinets to prevent crushing hazards. Demand concentrates in the Stuttgart-Dortmund industrial belt where precision metalworking clusters specify corrosion-resistant configurations with integrated RFID tracking.
China
GB standards for metal furniture specify corrosion resistance testing protocols that shape export qualification costs for foreign suppliers. The country's national manufacturing regulator enforces dual carbon goals that influence coating process selection. Yangtze River Delta manufacturing clusters are adopting mobile cabinet configurations as just-in-time production layouts demand reconfigurable shop floors.
Japan
METI industrial standards shape specification requirements for precision tooling storage in automotive component facilities. JIS standards for metal furniture provide the technical baseline for domestic procurement and regional export qualification. The Chubu-Nagoya manufacturing corridor sustains demand for high-density drawer configurations serving Toyota's consolidated supplier development programs.
Canada
Health Canada workplace safety guidelines align with US OSHA standards for cross-border automotive stamping operations. The Ontario-Quebec manufacturing corridor anchors North American tooling procurement volume through tier-1 supplier concentration. Rousseau Metal Inc.'s Quebec-based manufacturing scale exemplifies regional supply chain integration serving Canadian and US automotive plants.
Global Punch and Die Storage Cabinet Market Competitive Environment
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The vendor base stratifies between vertically integrated sheet metal formers and regional fabricators lacking documented quality protocols. Three archetypes dominate: premium-tier providers with captive hardware production, mid-scale specialists in mobile reconfigurable systems, and commodity steel fabricators serving repair shop demand. Consolidation pressure is accelerating through tier-1 automotive supplier development programs that filter uncertified vendors from approved lists.
Within the premium-tier segment, LISTA International Corporation and Stanley Vidmar occupy positions defined by load-rated engineering capabilities. Rousseau Metal Inc. anchors the North American regional specialist archetype. These three companies exemplify the competitive divergence between integrated hardware producers and assembly-dependent competitors. LISTA's vertical integration across sheet metal forming and locking hardware sustains premium positioning. Stanley Vidmar's modular drawer systems engineered for heavy die sets represent the heavy-capacity specialization vector. Rousseau's Quebec-based manufacturing scale demonstrates regional production concentration serving cross-border automotive corridors.
| Leading Market Players |
|---|
| LISTA International Corporation |
| Stanley Vidmar |
| Rousseau Metal Inc. |
| Hanel Storage Systems |
| Strong Hold Products |
| Husky Rack & Wire |
| Akro-Mils |
| Lyon Workspace Products |
| Durham Manufacturing Company |
| Others |
Value Chain & Pricing Dynamics
Powder-coated steel finishes displacing solvent-based coatings in EU public-sector procurement simultaneously redraws supplier geography toward REACH-compliant fabricators and compresses margin structures for coating-dependent tier-two producers lacking long-term mill agreements.
Pricing Analysis
Certification level (ISO 9001/CE marking) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO-certified suppliers commanding sustained premiums from automotive OEMs while uncertified fabricators compete on spot pricing for repair shop demand. Cost compression in the standard tier is intensifying because cold-rolled steel input volatility erodes fixed-contract profitability. Tier-1 automotive stampers show least price sensitivity due to consolidated supplier development programs, whereas independent fabricators and repair shops exhibit acute sensitivity to per-unit differentials.
Supply Chain Analysis
Strait of Malacca transit underwrites Pacific Rim raw material flows for cold-rolled steel coils feeding Southeast Asian fabrication clusters. Supply concentrates in China, Germany, and the United States, with Chinese mills dominating commodity-grade coil production and German producers anchoring precision-grade specifications for EU automotive corridors. The chain draws from iron ore, coking coal, and zinc coating inputs, with energy costs representing a volatile cost layer. Single-source vulnerability concentrates in Chinese GB standards certification capacity for export qualification. Distribution runs through tier-1 automotive supplier development programs and industrial distribution channels serving metalworking job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical lift modules and mobile racking systems pose credible substitution threats that incumbent cabinet suppliers must neutralize through specification anchoring and service bundling.
For Market Incumbents: Compound defensive positioning by embedding RFID tracking capabilities into heavy-capacity die storage lines, locking in automotive OEMs before vertical lift module suppliers achieve equivalent load ratings. Deepen backward integration into captive locking hardware production to sustain margin buffers against raw material volatility. Prioritize certification maintenance as tier-1 supplier development programs filter uncertified vendors from approved lists. For New Entrants and Emerging Players: Lead with aluminum extrusion configurations targeting aerospace cleanroom applications where weight reduction and non-sparking properties command specification priority and incumbent penetration remains shallow. Target precision aircraft component facilities in North America and Western Europe with embedded sensor array offerings. Pursue direct engagement with biomedical device stampers seeking corrosion-resistant storage with documented traceability protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated sheet metal formers with captive hardware production and established automotive OEM relationships. Long-term viability hinges on specification authority retention as smart-system integration requirements bifurcate the supplier base. Watch for inflection signals in seismic zone building code adoptions across Pacific Rim manufacturing clusters that would trigger upgrade cycles for anchored heavy-load systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Locking Hardware | Captive production of load-rated slides and interlock mechanisms insulates margin structures from component price volatility. |
| RFID Tracking Platform Development | Embedded sensor arrays differentiate premium offerings against commodity fabricators in aerospace and medical device segments. |
| REACH-Compliant Coating Process Investment | Powder-coated steel finishes qualify fabricators for EU public-sector contracts and German automotive procurement programs. |
| Seismic Zone Certification Expansion | Anchored heavy-load system engineering captures upgrade demand from Pacific Rim manufacturing clusters facing reinforced structural requirements. |
| Mobile Configuration Manufacturing Scale-Up | Castor-mounted bases align with just-in-time manufacturing cell reconfiguration trends displacing fixed tool crib installations. |
Study Parameters
Desk research of trade association filings, customs and import-export databases, and regulatory submission records preceded structured interviews with plant engineers at automotive stamping facilities, procurement leads at tier-1 suppliers, aftermarket service heads at industrial distributors, and certification auditors at ISO registrars. Primary fieldwork combined with secondary validation across SEC filings, OSHA enforcement databases, and EU Machinery Directive technical documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, material grade, application end-use, and geographic production cluster shaped the analytical framework. Segmentation modeling captured fixed versus mobile configuration splits, steel versus aluminum material preferences, and automotive versus aerospace demand trajectories. CAGRs derived from slope analysis of normalized shipment trends and value-per-unit trajectories across the projection horizon. Industry-specific inputs included die set weight distribution patterns, tool changeover frequency benchmarks, and coating process transition timelines.
The analysis sits within stated boundaries; outcomes outside sustained automotive platform launch cadence or abrupt steel tariff regime shifts would require recalibration. Forecasts reflect documented assumptions regarding REACH compliance phase-in schedules and tier-1 supplier consolidation trajectories. Practitioners should keep alternative scenarios live as seismic code adoption timelines and vertical lift module load rating improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Cleaning Equipment Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Turning Tools Market
Tools
Construction Nails Market
Tools
Landscaping Tools Market
Tools
Global Tools Storage Products Market
Tools
Coil Thread Insert Market
Tools
Floor Polishing Machine Market
Tools
Global Cutting Discs Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Theodolite Market
Tools
Power Nibbler Market
Tools
Rivet Gun Market
Tools
Multi-Tasking Machine Tools Market
Tools
Global Standard Parts for Tool Making Market
Tools
Automatic Lathe Machines Market