

Cordless Multi Rotary Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Multi Rotary Tools Market Insights
Professional construction sites is consolidating demand as general contractors replace pneumatic and corded systems with battery-powered rotary platforms for finishing and detail work. Bosch leverages its brushless motor IP and European manufacturing base to sustain premium positioning in industrial channels. DEWALT anchors North American professional demand through its 20V Max cordless ecosystem and jobsite-focused distribution. Makita competes across Asia-Pacific commercial workshops with compact lithium-ion platforms optimized for extended runtime.
Cordless multi rotary tools integrate interchangeable collet systems, variable-speed brushless motors, and lithium-ion battery packs to perform cutting, grinding, sanding, and engraving operations without tethered power supply. Units typically operate between 5,000 and 35,000 RPM with 12V to 20V battery architectures, serving applications from jewelry precision work to construction site material finishing. The product type dimension shows grinders and cutters commanding the largest volume share due to metal fabrication demand, while engravers generate premium margins in artisan and jewelry designer channels. Technology segmentation reveals brushless motor configurations outpacing brushed alternatives as torque efficiency and thermal management improve operational runtime for construction site and metalworking shop end users.
The EPA enforces energy efficiency standards for cordless power tool battery systems under appliance regulations, while OSHA workplace safety rules mandate vibration exposure limits affecting rotary tool design specifications. The EU's CE marking and RoHS compliance requirements restrict hazardous substances in battery electronics and motor components, creating certification barriers for non-compliant manufacturers. Stakeholders must monitor evolving battery recycling mandates and cordless platform interoperability standards as regulatory frameworks tighten across primary demand geographies.
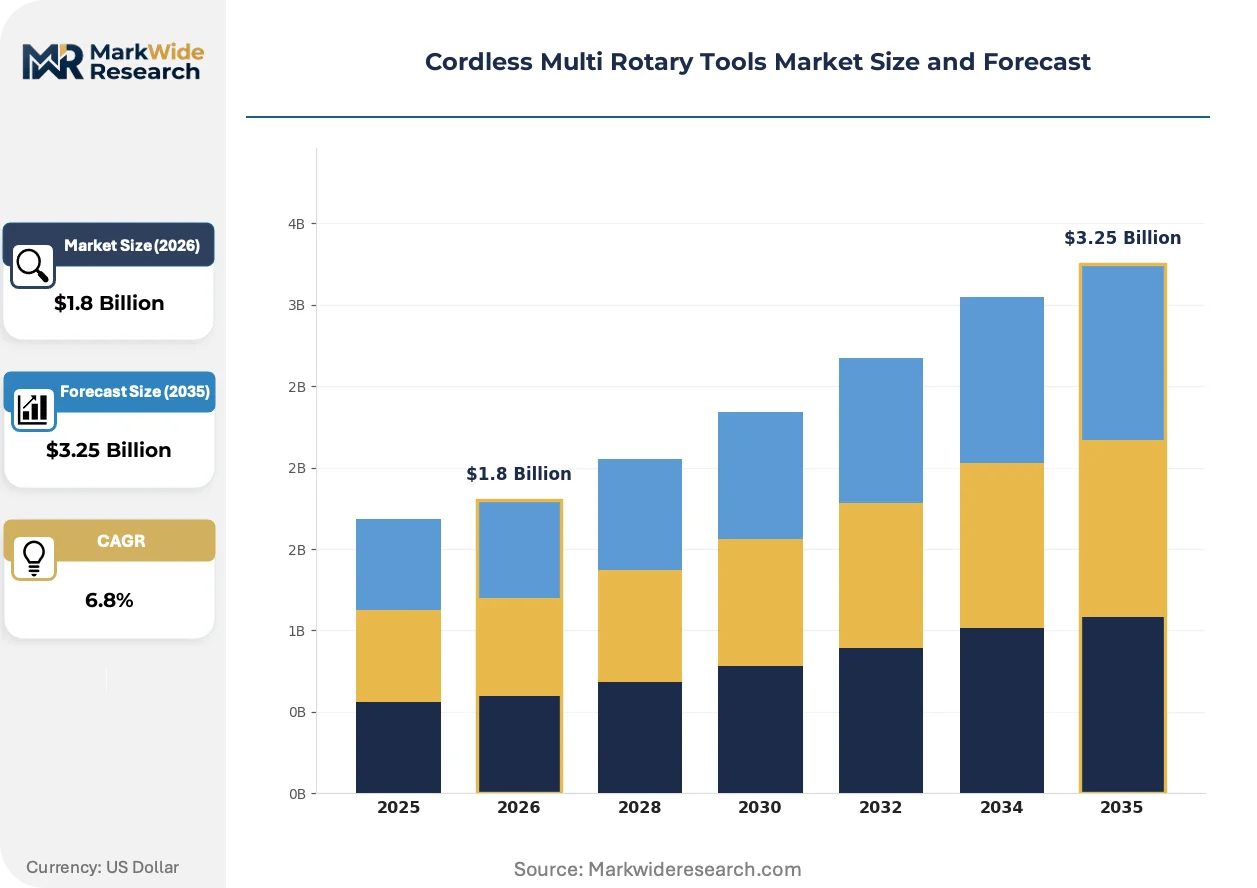
Market Dynamics
The cordless multi rotary tools market is experiencing structural compression as brushless motor architectures and lithium-ion battery density improvements simultaneously extend runtime and reduce unit weight, forcing incumbent manufacturers to retool production lines or cede professional segments to battery-native platforms.
Growth Catalysts
- EPA cordless equipment efficiency standards:United States regulatory mandates for battery system performance are accelerating replacement cycles among construction contractors seeking compliant platforms for federal project eligibility.
- Automotive supplier workshop consolidation:Metal fabrication and precision finishing operations across Germany are standardizing on battery-powered rotary systems to eliminate pneumatic infrastructure maintenance and compressed air distribution costs.
- Brushless motor torque efficiency:Thermal management improvements in permanent magnet motor designs are extending continuous operation windows for construction site material finishing applications.
Market Restraints
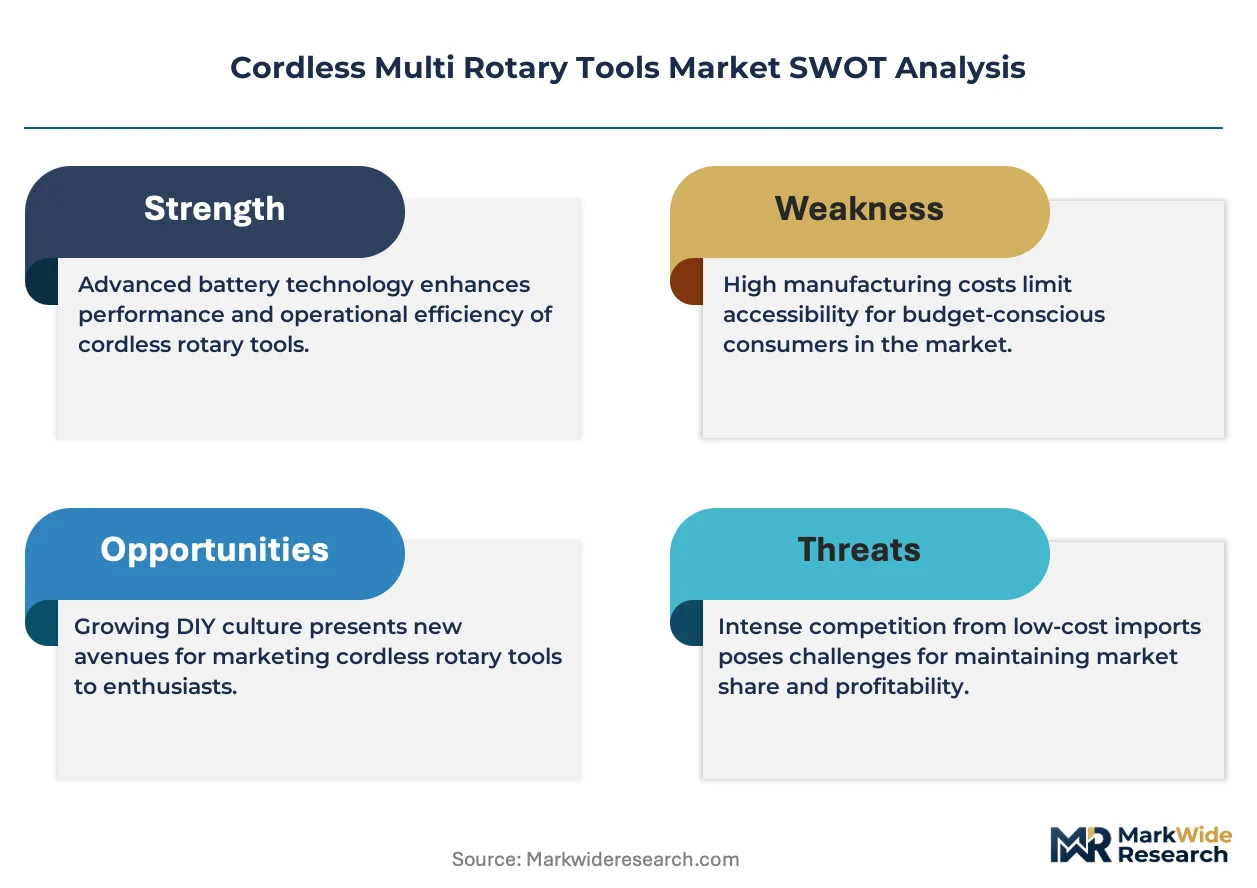
- Lithium-ion cell cost volatility:Cathode material price fluctuations and cobalt supply concentration in the Democratic Republic of Congo are compressing gross margins for battery pack assemblers.
- EU F-Gas Regulation compliance:Battery cooling system certification requirements are extending product development timelines and increasing engineering overhead for thermal management design.
- Pneumatic tool installed base inertia:Existing compressed air infrastructure investments in mature manufacturing economies are delaying platform switching decisions among cost-sensitive maintenance departments.
Strategic Opportunities
- India PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives are creating localized supply chain opportunities for rotary tool assemblers targeting price-sensitive commercial workshops.
- Jewelry and artisan engraving applications:Premium-margin precision work segments remain underpenetrated by established construction-focused brands, offering margin expansion potential.
- Interchangeable collet system standardization:Universal attachment architectures are enabling aftermarket accessory ecosystems that lock users into proprietary battery platforms.
Industry Challenges
- Brushless motor controller firmware development:Embedded systems engineering talent scarcity is bottlenecking product iteration cycles for mid-tier manufacturers lacking in-house semiconductor design capabilities.
- RoHS and CE marking compliance documentation:Hazardous substance tracking and technical file assembly are extending time-to-market for new product introductions in European distribution channels.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Multi Rotary Tools Market Trends and Innovations
Product architecture decisions are increasingly driven by thermal management requirements and battery platform interoperability rather than mechanical performance specifications alone, reshaping competitive differentiation around ecosystem lock-in rather than isolated tool capability.
Variable-speed brushless motor control systems with integrated temperature sensing are decentralizing precision work from fixed workshop stations to field construction environments. General contractors in commercial building finishing are adopting these platforms for on-site material edge treatment. The technology is decentralizing task allocation patterns that previously required dedicated grinding stations in centralized tool cribs.
The EU F-Gas Regulation imposes strict certification requirements on battery cooling systems containing fluorinated greenhouse gases. Manufacturers must redesign thermal management architectures or secure alternative cooling technology qualifications. German automotive supplier workshops are prioritizing compliant platforms to maintain CE marking eligibility for exported finished components.
Construction procurement departments are consolidating vendor relationships around integrated battery ecosystems rather than single-tool purchases. Distributor inventory models are shifting from SKU breadth to platform depth with dedicated service agreements. This concentration is most visible in North American commercial general contracting where DEWALT and Milwaukee battery compatibility dictates rotary tool selection.
Cordless Multi Rotary Tools Market Segmentation
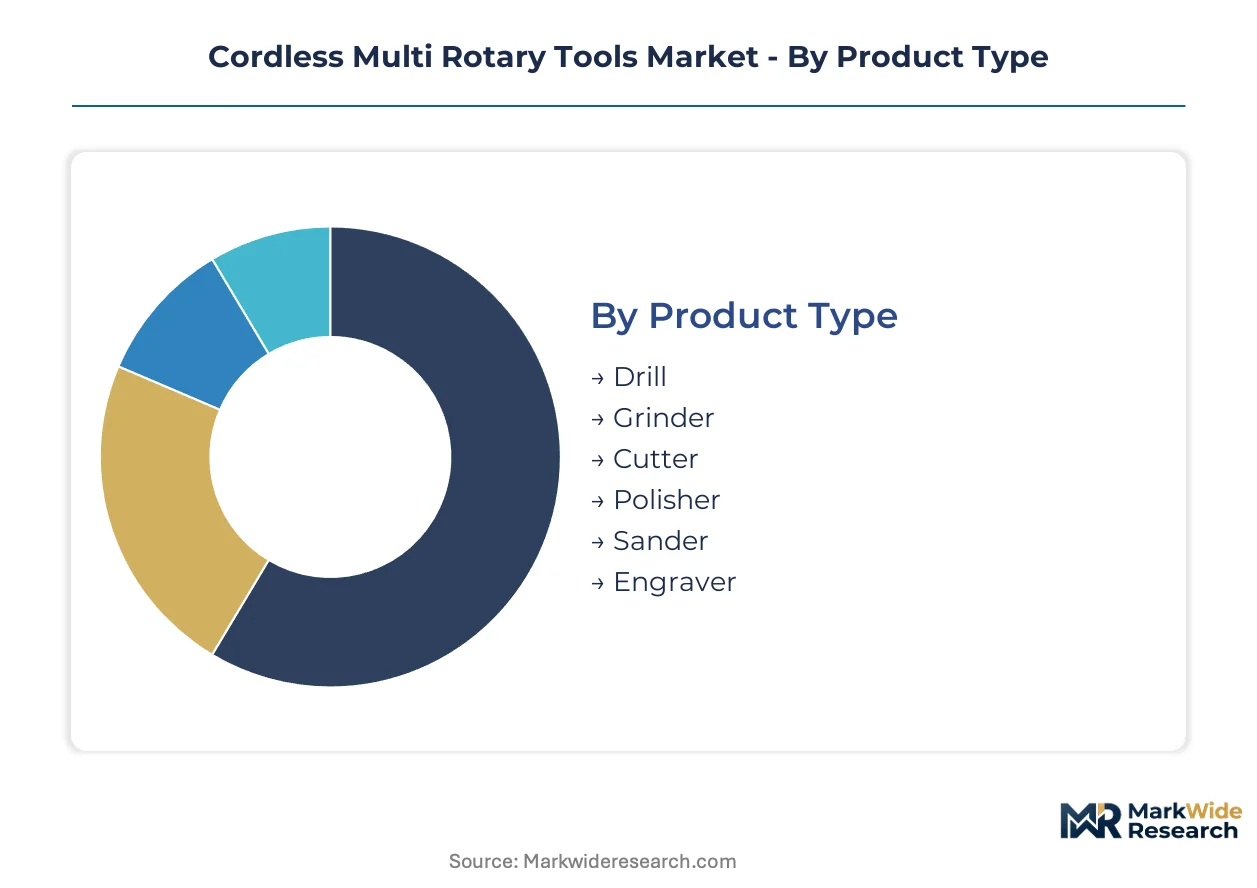
Cordless multi rotary tool purchasing decisions hinge on matching motor architecture and battery platform to specific material removal rates and precision tolerances. Segmentation reveals where professional contractors prioritize runtime over acquisition cost, and where artisan users accept premium pricing for ergonomic control.
Product Type:
Workpiece material density and surface finish requirements dictate collet selection and RPM range specifications across professional and consumer tiers.
- Grinder:Aggressive material removal heads rely on brushless torque curves for sustained metal grinding without thermal shutdown. German automotive supplier workshops specify these units for deburring stamped components where pneumatic line installation proves uneconomical.
- Cutter:Thin-kerf rotary cutters with variable depth stops enable plunge cuts in drywall and fiberglass composite panels. North American commercial contractors deploy battery-native platforms for on-site rough-in work previously assigned to corded jigsaws.
- Drill:Compact collet configurations accept micro-bit sets for pilot hole drilling in hardwood and acrylic stock.
- Polisher:Low-RPM orbital heads with foam pad interfaces serve automotive detailers and furniture restoration specialists.
- Sander:Triangular and finger sanding attachments access tight contours in cabinetry and trim carpentry.
- Engraver:Precision spindle bearings maintain sub-thousandth runout tolerances for jewelry designer and gunsmith applications.
Grinders lead on scale; engravers lead on momentum.
Technology:
Powertrain architecture determines total cost of ownership through battery cycle life and motor maintenance intervals.
- Brushless Motor:Electronic commutation eliminates brush wear and enables closed-loop torque control across 5,000-35,000 RPM ranges. EPA cordless equipment efficiency standards favor these configurations for federal construction project eligibility.
- Lithium-Ion Battery:12V to 20V cell architectures with 2.0Ah to 6.0Ah capacities dominate professional replacement cycles. Cobalt supply concentration in the Democratic Republic of Congo generates cell cost volatility that compresses assembler margins.
- NiMH Battery:Legacy nickel-metal hydride packs persist in price-sensitive hobbyist channels where runtime demands remain modest.
- Corded Power:Tethered AC motors retain share in fixed workshop stations with continuous duty cycles.
- Pneumatic:Compressed air systems defend installed base in high-volume metal fabrication facilities with existing compressor infrastructure.
- Solar-Powered:Photovoltaic charging integration targets off-grid construction and remote maintenance applications.
Lithium-Ion Battery leads on scale; Brushless Motor leads on momentum.
Application:
Material hardness and dust generation profiles shape respiratory protection requirements and extraction system integration.
- Metal Fabrication:Ferrous and non-ferrous stock removal generates conductive dust requiring sealed switch housings and grounded battery enclosures. OSHA workplace safety rules mandate vibration exposure limits that influence tool mass distribution and handle isolation design.
- Woodworking:Hardwood routing and softwood shaping applications drive demand for variable-speed control and edge guide compatibility. Carpentry workshops in Germany standardize on battery platforms to eliminate pneumatic hose trip hazards.
- Stone Carving:Diamond burr operations on granite and marble demand water suppression integration and IP-rated motor housings.
- Jewelry Making:Micro-engraving and stone setting operations prioritize spindle concentricity and foot-pedal speed control.
- Ceramic Cutting:Glass and tile scoring attachments require plunge depth limiting and water cooling interfaces.
- Model Building:Precision plastic and resin shaping tolerates lower torque outputs in exchange for compact form factors.
Metal Fabrication leads on scale; Jewelry Making leads on momentum.
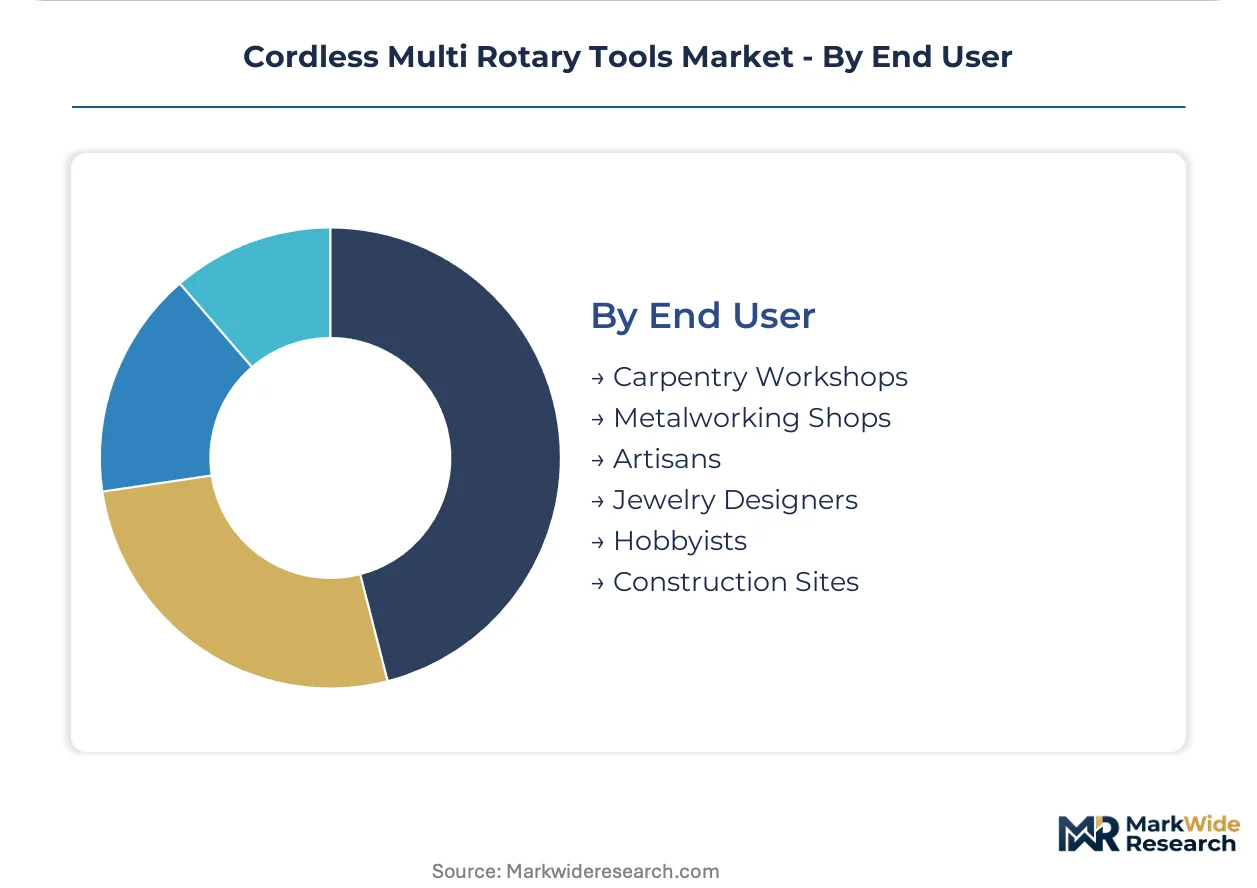
End User:
Procurement authority and tool utilization rates separate enterprise fleet purchases from individual artisan acquisitions.
- Construction Sites:General contractors consolidate vendor relationships around integrated battery ecosystems with dedicated service agreements. DEWALT and Milwaukee battery compatibility frequently dictates rotary tool selection in North American commercial building finishing.
- Metalworking Shops:Job shop environments balance pneumatic legacy infrastructure against battery platform flexibility for layout work.
- Artisans:Independent craftspersons prioritize ergonomic weight distribution and low-vibration operation for extended hand-held use.
- Jewelry Designers:Bench-top precision work demands sub-0.001 inch runout specifications and quick-change collet systems.
- Hobbyists:Entry-tier pricing sensitivity accepts reduced runtime and brushed motor architectures.
- Carpentry Workshops:Custom furniture builders require dust extraction compatibility and edge guide repeatability.
Construction Sites lead on scale; Jewelry Designers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting cordless multi rotary tool assembly toward jurisdictions with streamlined battery certification pathways and localized cell manufacturing incentives, compressing time-to-market for compliant platforms.
United States
General contractors across Texas and Florida commercial construction markets are consolidating procurement around integrated battery ecosystems. EPA cordless equipment efficiency standards are accelerating replacement cycles among federal project bidders. Dallas-Fort Worth metro area distributors report platform depth agreements supplanting SKU breadth inventory models.
Germany
Automotive supplier workshops in Stuttgart and Wolfsburg are standardizing on battery-powered rotary systems to eliminate pneumatic infrastructure maintenance. EU F-Gas Regulation compliance requirements are reshaping thermal management design specifications for CE marking eligibility. Bavarian metal fabrication clusters prioritize brushless motor configurations for deburring stamped components.
China
Domestic battery pack assemblers in Guangdong and Jiangsu provinces are capturing share in price-sensitive commercial workshop segments. MIIT industrial equipment efficiency guidelines are tightening motor controller certification requirements. Shenzhen-based electronics manufacturers are verticalizing into rotary tool controller firmware development.
India
Maharashtra and Gujarat commercial carpentry workshops are adopting compact lithium-ion platforms to eliminate pneumatic hose trip hazards. PLI scheme incentives for advanced chemistry cell manufacturing are creating localized supply chain opportunities for rotary tool assemblers. Mumbai distributor networks report accelerating battery-native platform adoption among furniture builders.
Japan
Precision metalworking shops in Aichi Prefecture and Osaka industrial corridors specify brushless torque curves for sustained grinding operations. METI energy efficiency standards for cordless industrial equipment are favoring electronic commutation architectures. Nagoya automotive component manufacturers are transitioning from pneumatic legacy systems to battery platforms for layout work flexibility.
Cordless Multi Rotary Tools Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with construction-focused brands commanding fleet purchasing through integrated battery ecosystems while precision-tool specialists capture premium-margin artisan channels. The vendor base concentrates around three strategic archetypes: diversified power tool conglomerates with proprietary battery platforms, precision-tool specialists serving jewelry and engraving applications, and regional fabricators competing on price-sensitive commercial workshop demand. Dominant competitive moves include strategic partnerships for battery cell supply security and geographic expansion into localized assembly operations near emerging demand clusters.
Among diversified power tool conglomerates, Bosch, DEWALT, and Makita occupy positions spanning construction site and commercial workshop demand. Bosch exemplifies European manufacturing-based premium positioning through industrial channel anchoring. DEWALT represents North American professional demand concentration through jobsite-focused distribution ecosystems. Makita sits within Asia-Pacific commercial workshop penetration with compact platform specialization. Fein and Proxxon anchor precision-tool specialist archetypes serving German automotive supplier and jewelry designer segments respectively.
| Leading Market Players |
|---|
| Bosch |
| Dremel |
| DEWALT |
| BLACK+DECKER |
| Makita |
| Milwaukee Electric Tool Corporation |
| Ryobi |
| Proxxon |
| Fein |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance mandates are gating qualified supply access for battery cooling system manufacturers, restricting premium-tier pricing participation to platforms with certified thermal management architectures and documented technical file assemblies for CE marking eligibility.
Pricing Analysis
Distributor margin layers compress as construction procurement departments consolidate vendor relationships around integrated battery ecosystems with dedicated service agreements. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor platforms with EPA efficiency certification from brushed alternatives and hobbyist-grade NiMH configurations. Cost compression in mid-tier lithium-ion packs is intensifying because cathode material price fluctuations and cobalt supply concentration compress assembler margins. Hobbyist segments exhibit acute price sensitivity, while German automotive supplier workshops prioritize runtime performance over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for battery-native platform fulfillment. Cell production draws from cathode material processing in the Democratic Republic of Congo, separator manufacturing in Japan, and electrolyte formulation in South Korea. Single-source vulnerability in cobalt concentrate supply generates acute exposure to export restriction shocks. Distribution runs through construction-focused distributor networks with platform depth agreements supplanting SKU breadth inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways as brushless motor controller firmware development costs concentrate among semiconductor-capable manufacturers, enabling premium-tier pricing power for compliant platforms.
For Market Incumbents: Cement ecosystem lock-in through proprietary collet system standardization and aftermarket accessory architectures that raise switching costs for construction site fleet operators. Battery cell supply security agreements with qualified thermal management suppliers defend against cobalt price volatility and EU F-Gas Regulation compliance delays. Backward integration into controller firmware development insulates product iteration cycles from embedded systems engineering talent scarcity.
For New Entrants and Emerging Players: The mid-tier price-point gap between Bosch premium positioning and BLACK+DECKER economy channels creates white-space territory for brushless motor platforms with simplified feature sets. Jewelry designer and gunsmith precision work segments remain underpenetrated by construction-focused brands, offering margin expansion with sub-thousandth runout specifications. Direct-to-artisan digital distribution bypasses incumbent distributor relationships concentrated in commercial contracting channels.
For Investors and Strategic Acquirers: Roll-up economics work for precision-tool specialists because artisan channel fragmentation across regional engraving equipment fabricators permits consolidation around shared spindle bearing supply chains and foot-pedal control IP. Five-to-ten year viability hinges on battery platform interoperability standardization rather than isolated tool capability differentiation. Monitor India PLI scheme advanced chemistry cell manufacturing uptake as inflection indicator for localized supply chain cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability Investment | CE marking and EPA efficiency certification unlock federal project eligibility for construction contractors. |
| Brushless Motor Controller Firmware Acquisition | Embedded systems capabilities accelerate product iteration cycles beyond mid-tier competitors. |
| India PLI Scheme Localization | Domestic cell manufacturing incentives reduce cathode material cost exposure for price-sensitive workshops. |
| Artisan Channel Direct Distribution Launch | Jewelry designer segments generate premium margins absent from construction-focused incumbent portfolios. |
| Thermal Management Architecture Redesign | EU F-Gas Regulation compliance maintains CE marking eligibility for German automotive supplier exports. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market combining interviews with maintenance directors at construction sites, procurement leads at automotive supplier workshops, distributor inventory managers, aftermarket service heads, and jewelry designer artisans. Secondary validation draws from EPA appliance regulation filings, EU F-Gas Regulation technical documentation, MIIT industrial equipment efficiency guidelines, METI energy efficiency standards, and India PLI scheme policy circulars. Bottom-up segment sizing triangulates against top-down macroeconomic indicators for cordless power tool replacement cycle analysis.
Rate-of-change decomposition separates volume growth from mix shift effects across the projection horizon. Segmentation dimensions modeled include product type, motor technology architecture, battery voltage tier, application material hardness, and end-user procurement authority. CAGRs derive from regression analysis against construction spending indices, automotive production forecasts, and artisan craft sector employment trends. Industry-specific inputs incorporate brushless motor penetration curves and lithium-ion cell cost trajectories.
Caveats apply where cobalt supply disruption, EU F-Gas Regulation enforcement intensity, or brushless motor controller talent scarcity could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.