
 Residential Cooking Grills Market | 2026-2036
Residential Cooking Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Cooking Grills Market Outlook
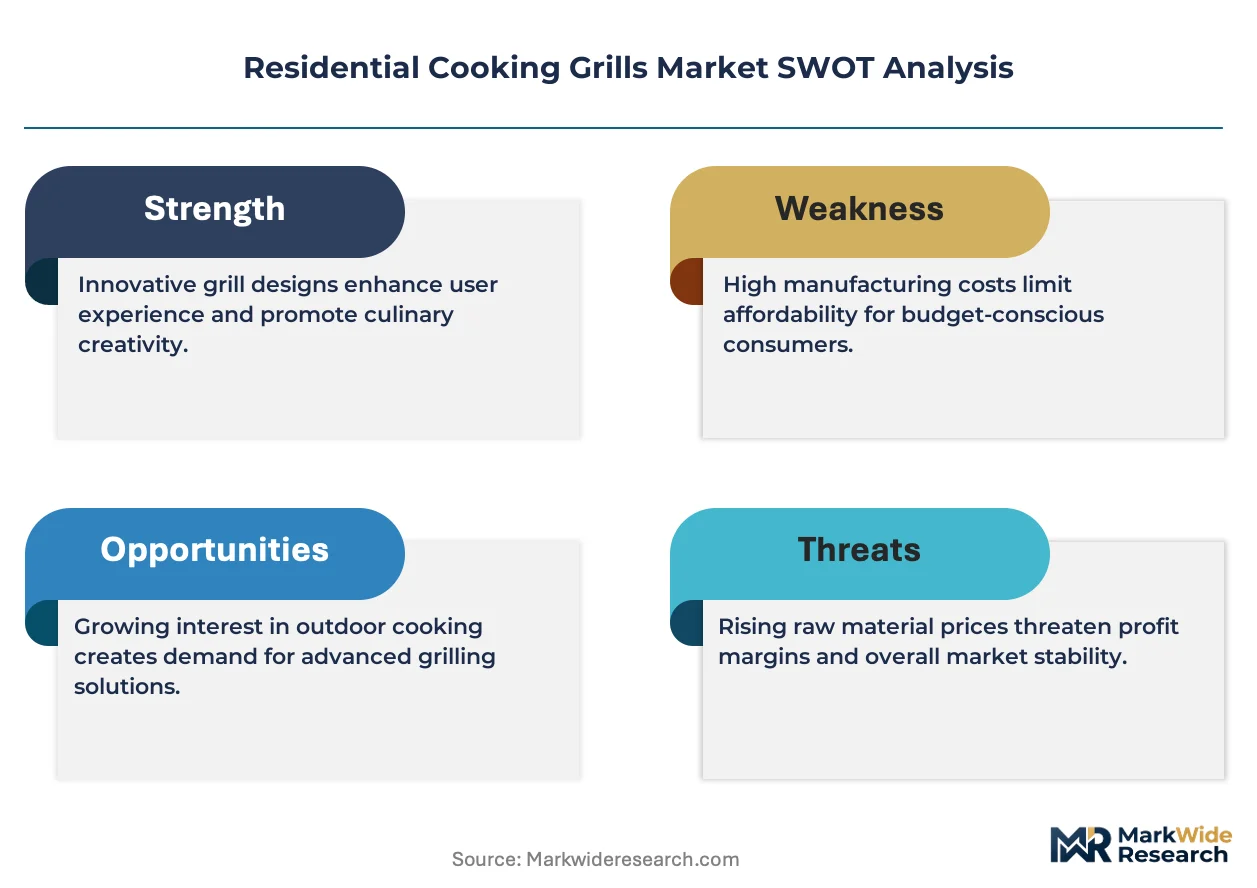
Premium-grade stainless steel construction is rotating the Residential Cooking Grills market toward higher-margin offerings with extended warranty profiles and superior heat retention. Weber Inc. leverages its foundry-to-retail vertical integration to control alloy sourcing and finished-goods quality. Traeger Grills specializes in pellet-fired automation systems that anchor its position among tech-forward outdoor cooks. Napoleon Grills dominates North American distribution through dealer networks and direct-to-consumer channels.
Residential cooking grills are metal-enclosed combustion or electric heating appliances designed for food preparation in outdoor domestic settings, typically constructed from 304-grade stainless steel or porcelain-coated cast iron with BTU outputs ranging from 8,000 to 100,000 depending on configuration and burner count. Their primary purpose centers on enabling flame-based or controlled-heat cooking for home entertainment, flavor differentiation, and seasonal outdoor dining. Gas grills command the largest installed base among product types due to convenience and speed, while pellet grills represent the fastest-growing category as precision temperature management attracts enthusiast segments. Compact and portable sizes are gaining traction among renters and outdoor enthusiasts seeking mobility, whereas large-format units concentrate margin pools in the homeowner segment.
EPA emissions standards for outdoor combustion equipment and CSA/ANSI certification requirements for gas appliance safety shape product design and market access for manufacturers selling into the United States. The EU F-Gas Regulation and REACH compliance on coated metal surfaces constrain material choices for European-bound exports. Stakeholders must monitor evolving efficiency mandates and smart-device interoperability standards as regulators and consumers alike demand lower emissions and connected functionality.
Market Dynamics
Pellet-fired automation systems are compressing the traditional gas grill installed base as precision temperature management becomes a baseline expectation rather than a premium feature. This technology shift is forcing incumbent manufacturers to reengineer combustion architectures and source electronic control modules from adjacent appliance sectors.
Growth Catalysts
- Backyard entertaining culture:Suburban homeowners in the United States are investing in permanent outdoor kitchen installations that anchor multi-zone cooking configurations and built-in refrigeration.
- REACH compliance on coated surfaces:European-bound exports must reformulate porcelain coatings to eliminate restricted substances, accelerating R&D into ceramic-based alternatives with superior thermal shock resistance.
- Smart-device interoperability standards:Wi-Fi-enabled temperature monitoring and recipe-guided cooking cycles attract tech-forward outdoor enthusiasts seeking remote control functionality.
Market Restraints
- 304-grade stainless steel input volatility:Nickel and chromium price swings compress margin predictability for foundry-dependent manufacturers during contract bidding cycles.
- CSA/ANSI certification timelines:Gas appliance safety testing creates 4-6 month market access delays for new burner configurations entering the United States.
- Electric grill substitution:High-rise dwellers facing open-flame restrictions increasingly adopt infrared and induction alternatives that eliminate combustion hardware entirely.
Strategic Opportunities
- Compact portable segments:Renters and camping enthusiasts in Germany and France represent underpenetrated demand for collapsible pellet units with 12-volt power compatibility.
- EU F-Gas Regulation phase-down:Propane cylinder refill infrastructure investments align with regulatory pressure to reduce refrigerant-equivalent emissions across outdoor fuel distribution.
- Direct-to-consumer channel expansion:Dealer network bypass enables margin capture and first-party data collection on usage patterns and accessory attachment rates.
Industry Challenges
- Embedded software engineering talent scarcity:Pellet grill automation requires firmware developers with combustion control and wireless stack expertise that traditional metalworking suppliers rarely retain in-house.
- Multi-certification burden:Products targeting both EPA emissions standards and EU CE marking face divergent test protocols that extend development cycles and strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Cooking Grills Market |
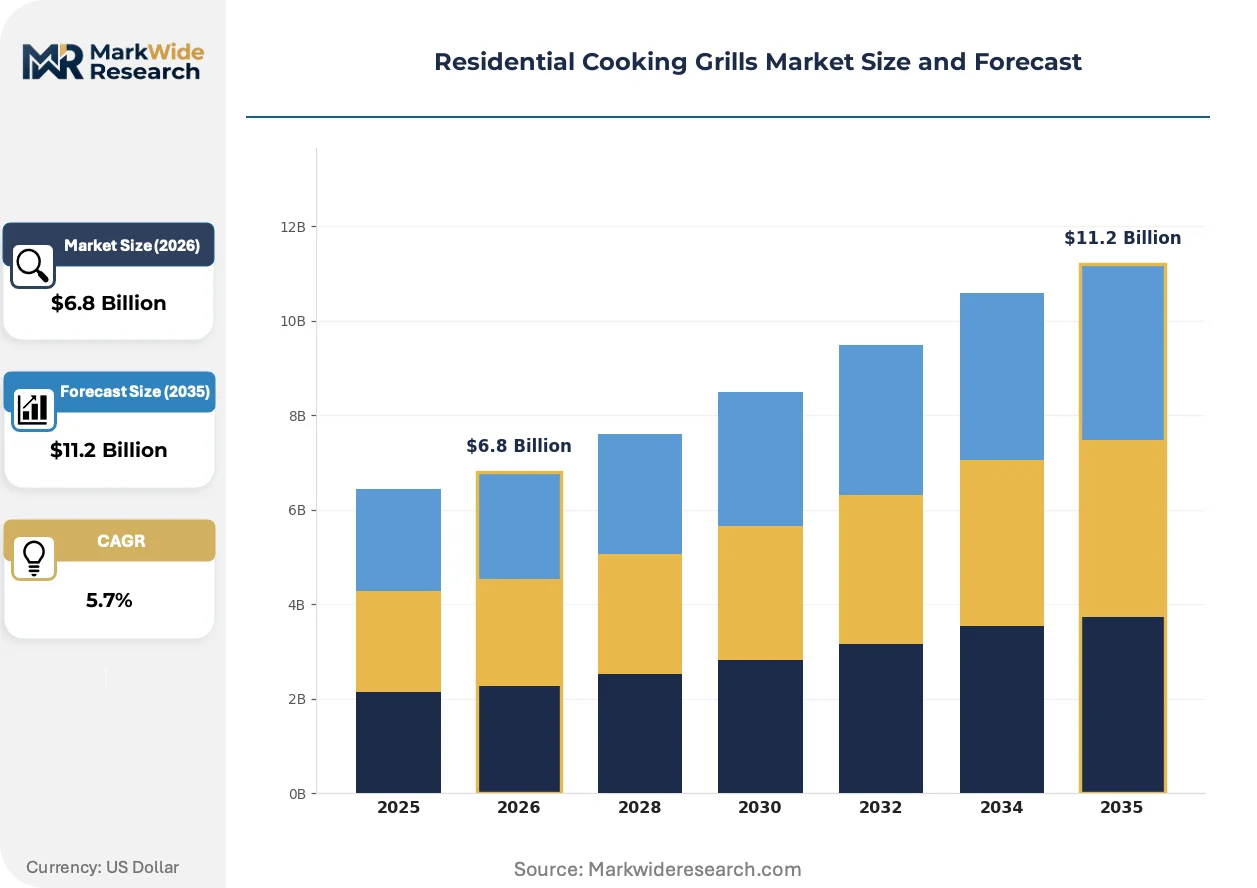
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grills, Charcoal Grills, Electric Grills, Pellet Grills Fuel Type: Natural Gas, Propane, Charcoal, Electric End User: Homeowners, Renters, Outdoor Enthusiasts, Chefs Size: Compact, Medium, Large, Portable |
| Companies Covered | Weber Inc., Traeger Grills, Char-Broil LLC, Blackstone Products, The Middleby Corporation, Napoleon Grills, Pit Boss Grills, Camp Chef, W.C. Bradley Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Cooking Grills Market Strategic Shifts
Connected functionality and modular outdoor kitchen systems are redefining how manufacturers architect product ecosystems. The shift from standalone appliances to integrated entertainment infrastructure is reshaping R&D priorities across the supplier base.
Pellet hopper and auger systems are miniaturizing into suitcase-format portable units that retain PID temperature control algorithms previously confined to full-size residential installations. Camping enthusiasts and tailgating segments are adopting these compact configurations at accelerating rates. This miniaturization is compressing the addressable market for traditional charcoal portable grills while opening accessory revenue streams around battery packs and vehicle power adapters.
The EPA's evolving emissions standards for outdoor combustion equipment are mandating secondary burn systems and particulate filtration in wood-fired configurations. Manufacturers serving the United States must redesign fireboxes and add catalytic converters that increase unit cost and complexity. Pellet grill producers with existing electronic combustion management are adapting firmware to optimize burn efficiency, while gas grill specialists face steeper hardware retrofit requirements.
Renter households are driving a behavioral pivot toward appliance-as-accessory purchasing rather than permanent installation commitments. Big-box retailers and specialty dealers are responding with subscription-style financing and seasonal trade-in programs that compress ownership cycles. This pattern concentrates in coastal United States cities where outdoor space constraints and mobility preferences limit large-format grill penetration.
Residential Cooking Grills Market Segmentation
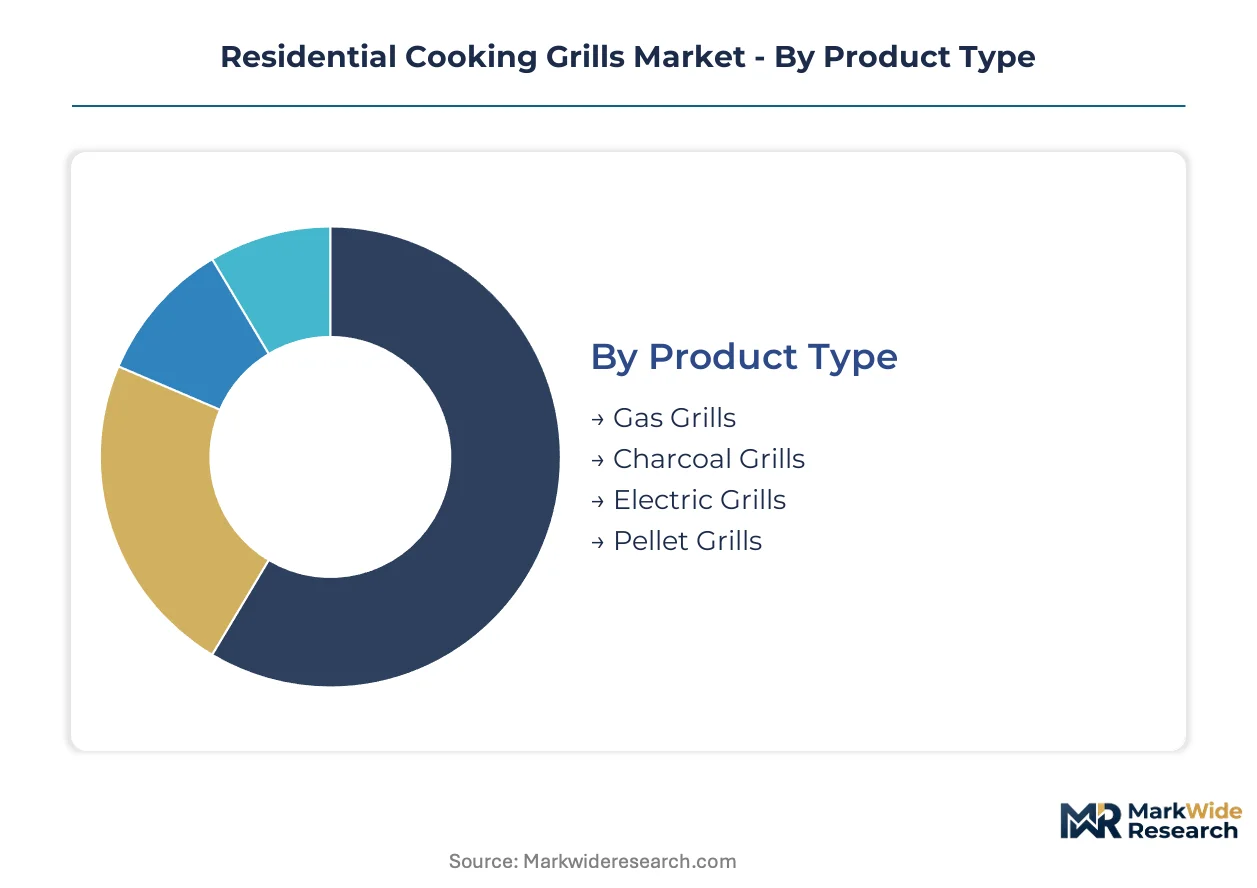
Product architecture in the Residential Cooking Grills market fragments across combustion technologies, fuel logistics, user commitment levels, and spatial constraints. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
EPA emissions standards and CSA/ANSI certification requirements create divergent compliance burdens across combustion architectures, directly affecting time-to-market and unit economics.
- Gas Grills:These units deploy propane or natural gas through manifold-fed burner arrays, typically delivering 8,000-100,000 BTU across 2-6 burner configurations. Homeowners in the United States dominate procurement, prioritizing ignition speed and temperature uniformity for large-format entertaining. CSA/ANSI certification timelines for new burner geometries extend 4-6 months, constraining annual model refresh cycles.
- Pellet Grills:Auger-fed hardwood pellet systems with PID-controlled combustion management enable precision temperature holding across smoking, roasting, and searing modes. Outdoor enthusiasts in Germany and France are adopting portable 12-volt compatible variants for camping applications. Embedded software engineering scarcity limits firmware development bandwidth for smaller manufacturers entering this category.
- Charcoal Grills:Open-combustion kettle or kamado designs relying on lump charcoal or briquette fuel. EPA secondary burn mandates are forcing catalytic converter additions that increase unit cost.
- Electric Grills:Infrared or resistive heating elements eliminating combustion hardware entirely. High-rise dwellers facing open-flame restrictions in coastal United States cities drive substitution demand.
Gas grills handle the majority of throughput; pellet grills are climbing the fastest on share as precision temperature management becomes baseline expectation.
Fuel Type:
Supply chain configuration and infrastructure availability determine fuel accessibility, with propane cylinder distribution networks and natural gas line penetration creating divergent addressable markets.
- Propane:Portable 20-pound cylinder exchange systems dominate suburban United States installations where permanent gas line extension proves cost-prohibitive. EU F-Gas Regulation phase-down pressures are accelerating refill infrastructure investments across outdoor fuel distribution.
- Natural Gas:Hard-plumbed permanent installations anchor outdoor kitchen configurations in new construction and renovation projects. Homeowners with existing residential gas service favor this fuel for elimination of cylinder handling and infinite runtime capacity.
- Charcoal:Lump hardwood and compressed briquette formats serve flavor-prioritizing users accepting longer preheat cycles and ash management. REACH compliance on coated surfaces is accelerating ceramic-based alternative development for European-bound exports.
- Electric:120V or 240V grid connection eliminates fuel logistics entirely, constraining peak temperature output but enabling balcony and indoor-adjacent deployment where fire codes prohibit open flame.
Propane commands the largest installed base; natural gas is gaining share fastest through outdoor kitchen permanence trends.
End User:
Ownership duration and mobility requirements segment demand across installation commitment levels, from permanent built-in configurations to collapsible transportable units.
- Homeowners:Permanent outdoor kitchen investments with multi-zone cooking configurations and built-in refrigeration anchor this segment. Suburban United States markets concentrate demand for large-format units with extended warranty profiles.
- Outdoor Enthusiasts:Camping, tailgating, and overlanding applications prioritize compact pellet systems with 12-volt power compatibility and collapsible footprints. This segment is expanding most quickly as portable PID-controlled units miniaturize previously full-size technology.
- Renters:Appliance-as-accessory purchasing patterns with subscription financing and seasonal trade-in programs dominate. Mobility constraints limit large-format penetration in coastal United States cities.
- Chefs:Professional-grade specifications with higher BTU density and precision control for recipe development and content creation applications.
Homeowners generate the majority of revenue; outdoor enthusiasts are the steepest expansion trajectory as portable automation technology matures.
Size:
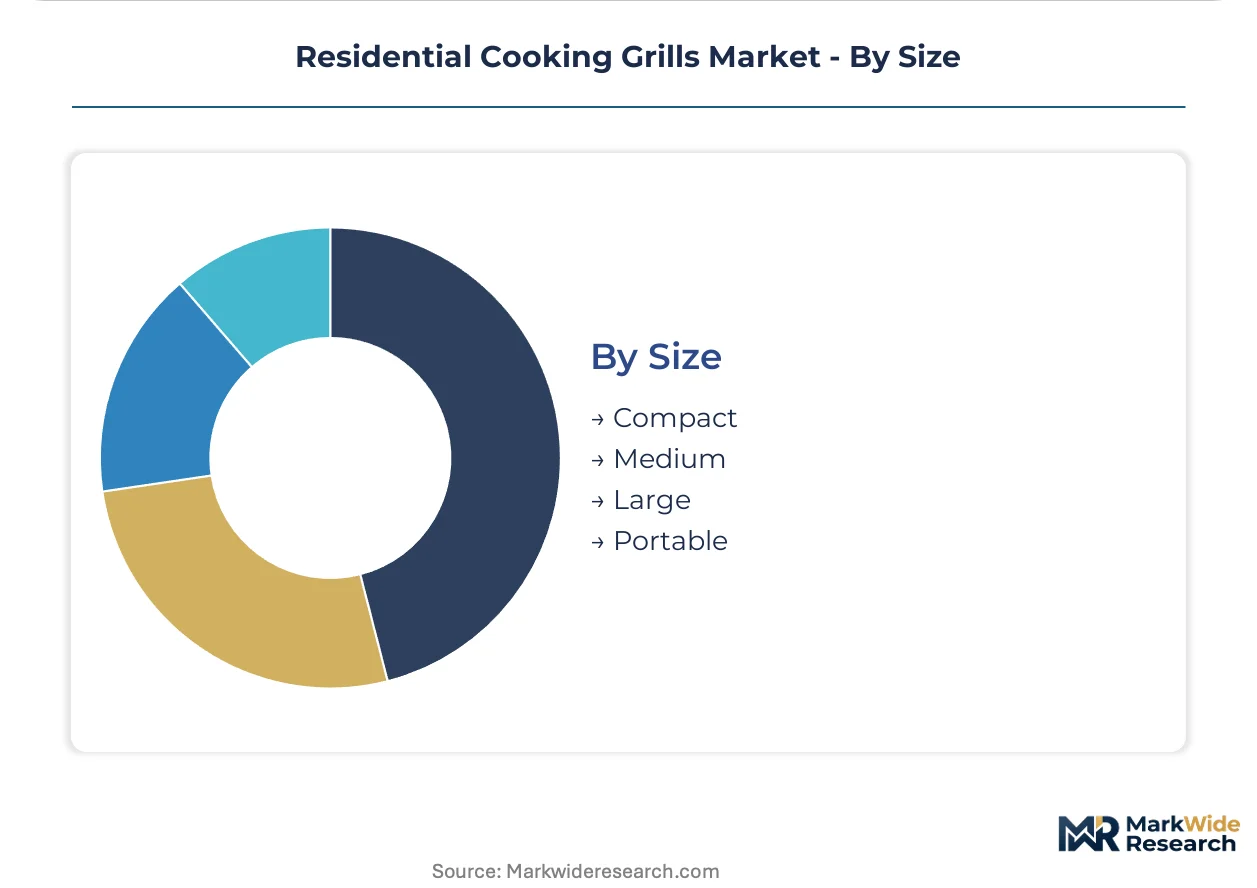
Physical footprint directly correlates with burner count, hopper capacity, and thermal mass, creating tiered price positioning and channel placement strategies.
- Large:36-inch and greater cooking surfaces with 4+ burners or 24-pound pellet hopper capacity anchor permanent outdoor kitchen islands. Margin concentration peaks here through built-in configuration and accessory attachment.
- Portable:Collapsible or suitcase-format units under 25 pounds with 12-volt or battery power options. Camping and tailgating segments in Germany and France show underpenetrated demand for pellet-fired portable variants.
- Medium:Freestanding cart-mounted configurations balancing cooking area with mobility, typically 24-30 inches in width.
- Compact:Tabletop or balcony-scale units under 20 inches width targeting space-constrained urban households.
Large formats capture the dominant profit pool; portable configurations are gaining share fastest through miniaturization of pellet automation technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in residential cooking grills tilt toward net deficit positions in Europe and Asia-Pacific, while North American manufacturers maintain surplus capacity directed toward premium segments abroad. Trade patterns concentrate in stainless steel alloy inputs from South Korea and finished goods distribution through Rotterdam and Long Beach corridors.
United States
Suburban homeowners in Texas and Florida drive permanent outdoor kitchen installations with multi-zone cooking configurations. EPA emissions standards for outdoor combustion equipment mandate secondary burn systems in wood-fired configurations. The Dallas-Fort Worth metroplex anchors dealer network distribution for large-format gas grill deployments.
Germany
Camping enthusiasts in Bavaria and Baden-Württemberg adopt portable pellet systems with 12-volt power compatibility for overlanding applications. EU F-Gas Regulation phase-down pressures accelerate propane refill infrastructure investments across outdoor fuel distribution. Stuttgart industrial clusters concentrate precision auger and PID control module manufacturing for European-bound exports.
France
Renter households in Paris and Lyon exhibit appliance-as-accessory purchasing patterns with seasonal trade-in program participation. REACH compliance on coated metal surfaces forces reformulation of porcelain grill coatings to eliminate restricted substances. The Auvergne-Rhône-Alpes region hosts ceramic-based alternative R&D facilities serving reformulation mandates.
Canada
High-rise dwellers in Toronto and Vancouver facing open-flame restrictions substitute electric infrared alternatives for balcony deployment. CSA certification requirements for gas appliance safety create 4-6 month market access timelines for new burner configurations. Ontario manufacturing corridors supply compact electric units to coastal United States cities with similar fire code constraints.
Australia
Outdoor entertaining culture in Sydney and Melbourne sustains demand for large-format stainless steel configurations with extended warranty profiles. ISO standards for outdoor appliance safety influence product testing protocols beyond domestic regulatory requirements. Queensland coastal clusters concentrate corrosion-resistant alloy fabrication for marine-environment grill deployments.
Residential Cooking Grills Market Competitive Environment
Concentration sits with vertically integrated foundry operators and specialty combustion technology developers rather than pure-play assemblers. The vendor base spans three tiers: mass-market retailers with private-label sourcing, mid-cap specialists with captive alloy production, and premium automation-focused developers. Strategic moves center on backward integration into stainless steel supply and firmware acquisition from adjacent appliance sectors.
Within the premium automation tier, Traeger Grills and Weber Inc. exemplify divergent technology anchoring strategies. Napoleon Grills occupies a position across North American distribution architecture. Mid-cap fabricators with foundry-to-retail control include Char-Broil LLC and W.C. Bradley Co., representing scale-driven manufacturing archetypes. Blackstone Products and Pit Boss Grills sit within specialty category development, while Camp Chef anchors portable configuration expertise. The Middleby Corporation represents portfolio diversification across commercial and residential combustion equipment.
| Leading Market Players |
|---|
| Weber Inc. |
| Traeger Grills |
| Char-Broil LLC |
| Blackstone Products |
| The Middleby Corporation |
| Napoleon Grills |
| Pit Boss Grills |
| Camp Chef |
| W.C. Bradley Co. |
| Others |
Value Chain & Pricing Dynamics
Foundry capacity utilization above 85 percent in South Korean stainless steel clusters concentrates alloy pricing power among three dominant suppliers, compressing margin flexibility for mid-tier grill fabricators while anchoring price floors for 304-grade construction across all product tiers.
Pricing Analysis
Homeowner buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by burner count and smart-control integration. Price erosion runs through economy gas configurations as private-label imports from Mexico compress entry-level positioning. Outdoor enthusiasts exhibit lowest price sensitivity, accepting 40-60 percent premiums for PID-controlled pellet systems with Wi-Fi connectivity.
Supply Chain Analysis
Ningbo port congestion periodically chokes containerized auger motor shipments from Chinese contract manufacturers, exposing pellet grill assemblers to 6-8 week production delays. Supply concentrates in China for electronic control modules, South Korea for 304-grade stainless coil, and Vietnam for porcelain-coated cast iron grates. Distribution runs through big-box retail consolidation in the United States and specialized dealer networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with portable automation segments where incumbent firmware development lags behind camper demand for 12-volt compatible precision control, creating niche entry points for specialized engineering teams.
For Market Incumbents: Consolidate backward integration into stainless foundry capacity to offset nickel volatility exposure. Lock in multi-year propane cylinder distribution partnerships before EU F-Gas infrastructure investments mature. Prioritize firmware talent acquisition from adjacent appliance sectors to defend against pellet automation specialists.
For New Entrants and Emerging Players: Firmware-as-a-service gaps in rental and subscription financing models present immediate white-space opportunity. Target renter households in coastal United States cities with compact electric configurations and seasonal trade-in logistics. Lead with direct-to-consumer channel control to capture first-party usage data for accessory targeting.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pellet grill manufacturers with consumables attachment and subscription recipe platforms. Five-to-ten year viability favors targets with captive alloy sourcing and embedded software IP rather than pure-play metal fabricators. Monitor EPA secondary burn mandate compliance timelines as inflection signal for restructuring-ready gas grill portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Foundry Capacity | Captive 304-grade supply insulates margin from nickel volatility and CSA certification delays. |
| Firmware Development Acquisition | Combustion control expertise closes capability gap against Traeger and Camp Chef automation platforms. |
| Direct-to-Consumer Channel Expansion | Dealer network bypass captures first-party data on accessory attachment and replacement part cycles. |
| Portable Pellet System Miniaturization | 12-volt compatible suitcase formats address underpenetrated camping demand in Germany and France. |
| EU REACH Compliance Reformulation | Ceramic-based coating alternatives eliminate restricted substances and unlock European export volume. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with outdoor kitchen installers, propane distribution logistics managers, big-box category buyers, foundry operations directors, and camping equipment specialty retailers. Secondary validation drew from EPA emissions filings, CSA certification registries, EU F-Gas implementation reports, stainless steel trade association data, and customs import records. Bottom-up unit shipment estimates triangulated against top-down consumer expenditure surveys.
Across the analysis window, volume and value outputs were modeled by product type, fuel configuration, end-user commitment level, and physical size tier. CAGRs were derived from regression analysis of historical shipment patterns against macroeconomic indicators including suburban homeownership rates and outdoor recreation expenditure indices. Pellet hopper miniaturization curves and smart-device adoption slopes informed segment-specific trajectory assumptions.
Underlying assumptions cover regulatory implementation timelines and alloy price stabilization, with deviation risk concentrated in EPA secondary burn mandate enforcement intensity and EU F-Gas infrastructure buildout pace. Practitioners should keep alternative scenarios live as emissions standards and camping culture penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Tabletop Kitchen Products Market