
 Three Wheel E-Scooter Market | 2026-2036
Three Wheel E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Three Wheel E-Scooter Market Analytics
Multi-source battery procurement is repositioning supply chain economics for three-wheel e-scooter assemblers. Gogoro leverages its proprietary swap-station network to secure captive cell supply. Bintelli competes through Florida-based manufacturing and direct dealership control across the southeastern United States.
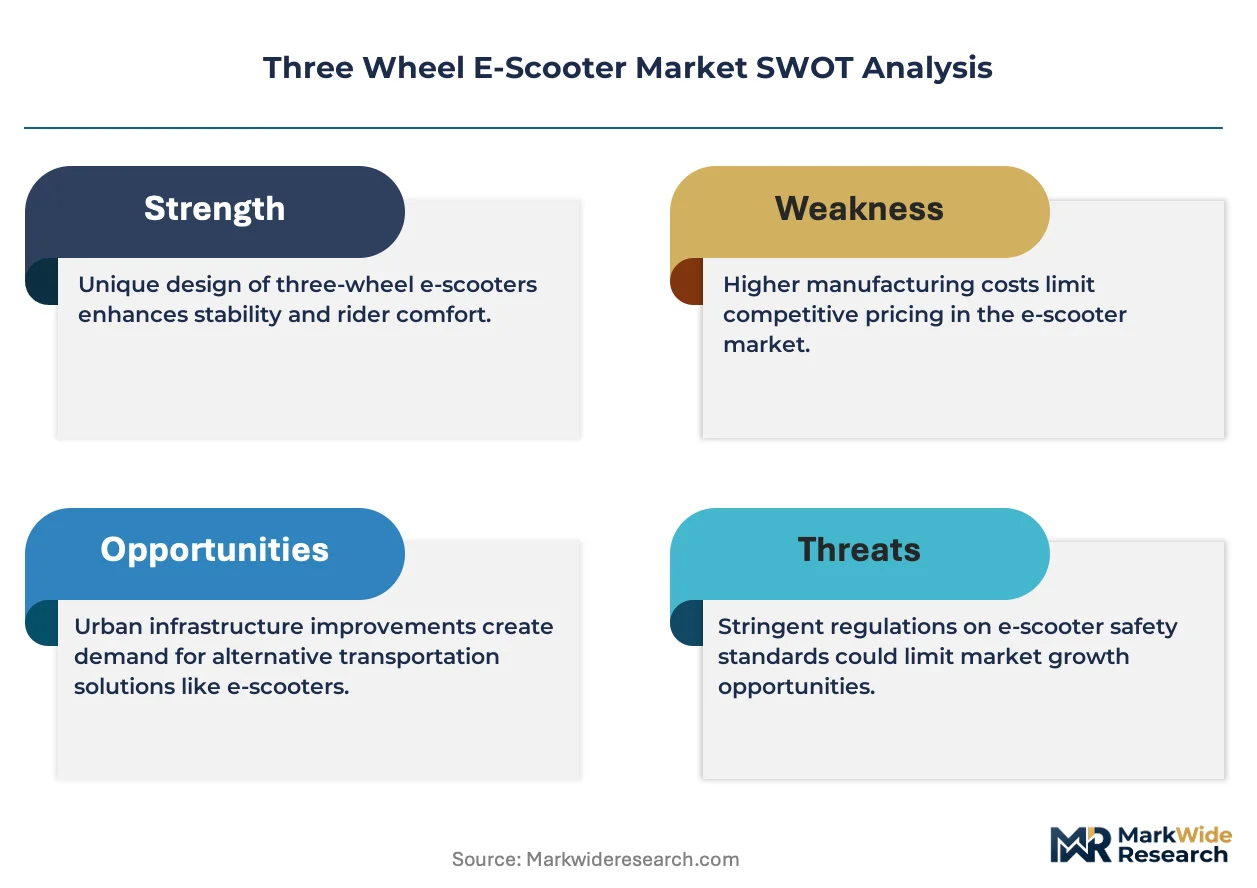
A three-wheel e-scooter is a battery-powered personal mobility device with a triangular wheelbase configuration, typically incorporating dual front wheels with independent suspension for stability, and rear-hub or mid-drive electric motors rated between 350W and 2000W. These vehicles serve urban commuters, commercial delivery operators, and mobility-impaired users requiring greater balance assurance than two-wheeled alternatives. The lithium-ion battery technology segment captures the dominant margin pool as energy density improvements reduce per-unit pack costs. Delivery services represent the fastest-expanding end-user category as logistics firms replace gasoline-powered trikes with electric equivalents for urban parcel distribution.
The US Consumer Product Safety Commission and the European Union's Machinery Directive jointly shape crashworthiness standards and electrical safety certifications for three-wheel e-scooter entry. The EU AI Act's impending requirements for autonomous mobility systems will force firmware transparency and algorithmic accountability disclosures from connected fleet operators. Stakeholders must monitor evolving battery passport regulations and second-life cell certification pathways to preserve market access.
Market Dynamics
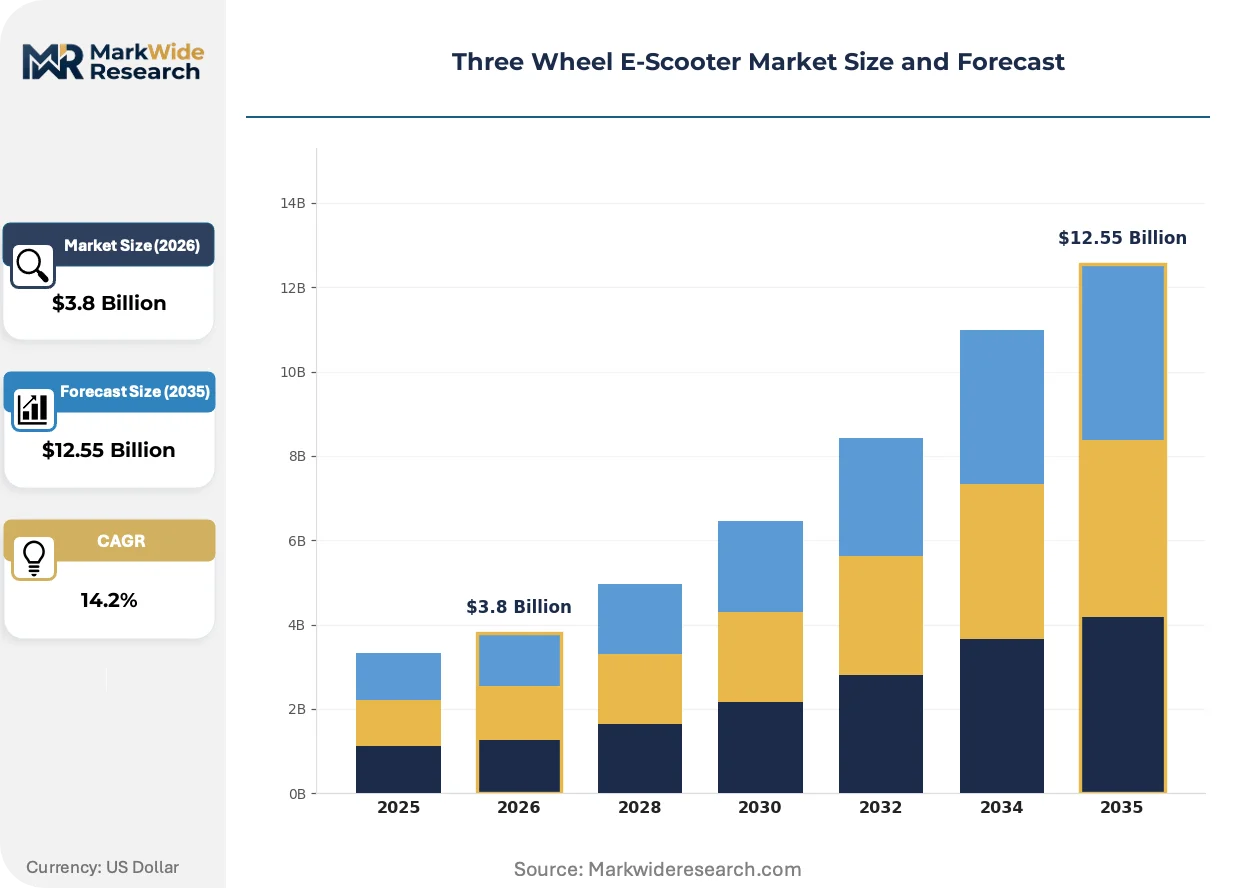
Delivery fleet electrification mandates and battery swap infrastructure deployment are restructuring competitive economics for three-wheel e-scooter procurement across urban logistics networks.
Growth Catalysts
- EU Green Deal transport electrification:Vehicle homologation requirements accelerate fleet replacement timelines for commercial operators in Germany, France, and the Netherlands.
- Last-mile logistics density:Parcel distribution networks prioritize three-wheel configurations for stability under variable load conditions in dense urban cores.
- Lithium-ion energy density improvements:Pack cost reductions per kilowatt-hour expand addressable demand into price-sensitive commuter segments.
Market Restraints
- Cell supply concentration:Cathode material processing and precursor refining cluster in China, exposing assemblers to input volatility and trade policy friction.
- Swap station capex intensity:Network deployment requires substantial upfront capital for real estate, electrical infrastructure, and battery float inventory.
- Two-wheeled substitution:Lower acquisition cost and maneuverability advantages of dual-wheel e-scooters constrain three-wheel penetration in individual consumer markets.
Strategic Opportunities
- Mobility-impaired accessibility services:Aging demographics in Japan and Germany drive demand for stability-assured personal transport with medical-grade certification pathways.
- Second-life battery integration:Degraded automotive cells repurposed for stationary scooter charging infrastructure reduce network operating costs.
- Commercial leasing programs:German cities expanding municipal micro-mobility infrastructure create fleet procurement channels distinct from direct retail.
Industry Challenges
- Firmware transparency mandates:The EU AI Act requires algorithmic accountability disclosures from connected fleet operators, extending certification timelines.
- Skill scarcity in power electronics:Motor controller design and battery management system engineering talent concentrates at tier-one automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Wheel E-Scooter Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Premium, Off-Road, Lightweight End User: Consumers, Corporate, Delivery Services, Tour Operators Battery Technology: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Others Range: Up to 20 miles, 21-40 miles, 41-60 miles, 61 miles & above |
| Companies Covered | Gogoro, Bintelli, Karma, Razor, Xiaomi, Segway, Inokim, Super Soco, E-Twow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Wheel E-Scooter Market Evolving Landscape
Intelligent connectivity layers and modular battery architectures are redefining how three-wheel e-scooter fleets are deployed, monitored, and monetized across urban environments.
Vehicle-to-grid bidirectional charging hardware is converging with scooter battery packs, enabling fleet operators to sell stored energy back to distribution networks during peak demand windows. Logistics providers in California and Texas pilot this capability to offset charging infrastructure costs. The technology is converging with dynamic electricity pricing algorithms to create new revenue streams that subsidize vehicle acquisition.
The EU AI Act's autonomous mobility provisions impose firmware transparency and algorithmic accountability requirements on connected three-wheel e-scooter fleets. Manufacturers must document decision logic for collision avoidance and geofencing systems. Commercial operators in Germany and the Netherlands face extended type-approval timelines as notified bodies develop assessment protocols for machine-learning-enabled safety systems.
Leasing-based fleet procurement is displacing direct ownership among last-mile delivery contractors, transferring residual value risk to financing entities. Third-party mobility-as-a-service platforms aggregate vehicle access across multiple city contracts. This shift concentrates most visibly in German urban logistics markets where municipal procurement rules favor operational expenditure models over capital purchases.
Three Wheel E-Scooter Market Segmentation
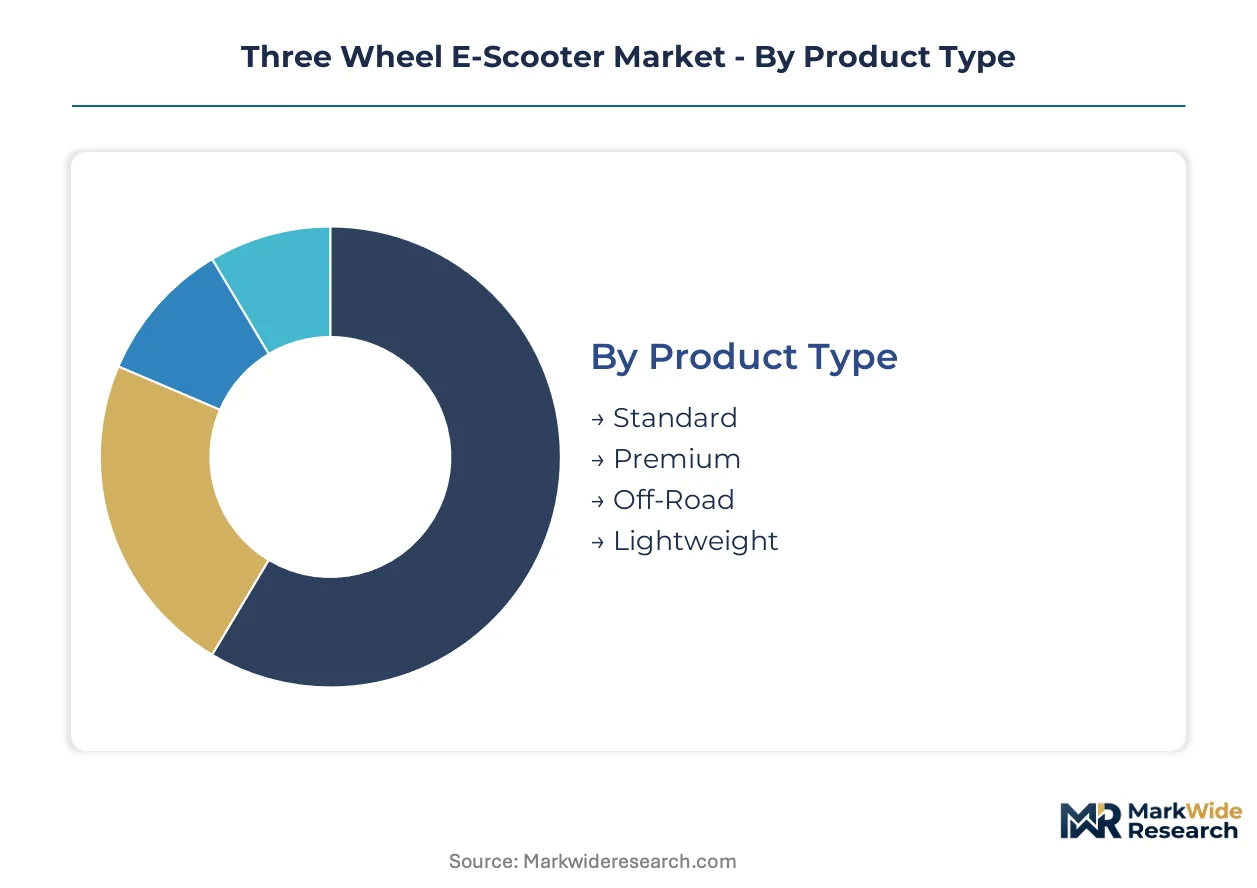
Segmentation reveals how capital deployment and technical specifications diverge across use cases in the three-wheel e-scooter market. Product positioning and procurement economics vary sharply between consumer leisure purchases and commercial fleet deployments.
Product Type:
Capital intensity escalates from basic commuter configurations to specialized off-road architectures with reinforced suspension and waterproofing.
- Standard:Entry-level configurations with 350W-750W hub motors and basic lead-acid or small lithium-ion packs. Demand concentrates in German municipal leasing programs where procurement rules favor operational expenditure models over capital purchases.
- Premium:Mid-drive motors, regenerative braking, and connected telemetry for fleet monitoring. Corporate mobility managers in the Netherlands specify these for employee shuttle services and campus logistics.
- Off-Road:Reinforced frames, all-terrain tires, and sealed electronics rated for IP67 ingress protection. Tour operators in California and Colorado deploy these for guided trail experiences.
- Lightweight:Folding mechanisms and sub-30kg mass for multi-modal commuting. Urban commuters in Tokyo and Osaka prioritize these for train-station connectivity.
Premium absorbs the bulk of installed capacity; Delivery Services is expanding most quickly as logistics firms electrify last-mile fleets.
End User:
Procurement patterns split between individual retail transactions and volume fleet contracts with diverging service-level requirements.
- Consumers:Individual purchasers seeking personal mobility or recreational use. Price sensitivity dominates in this segment, with German buyers showing particular willingness to pay for extended warranty coverage.
- Corporate:Facility management and employee mobility programs. Campus operators in Texas and California specify vehicle-to-grid compatibility to offset charging infrastructure costs through peak demand response.
- Delivery Services:Parcel and food distribution fleets operating 12-16 hour daily cycles. Stability under variable load conditions drives preference for three-wheel configurations over two-wheeled alternatives in dense urban cores.
- Tour Operators:Guided rental experiences and destination mobility services. Coastal operators in Florida and Mediterranean Spain favor ruggedized builds for salt-air exposure.
Delivery Services commands the steepest expansion trajectory; Consumers retains the largest addressable population base.
Battery Technology:
Cell chemistry selection determines pack cost, cycle life, and regulatory compliance burden across deployment scenarios.
- Lead-Acid:Mature chemistry with established recycling infrastructure but energy density limitations. Price-sensitive commuter segments in India continue specifying these for short-range urban trips.
- Lithium-Ion:Dominant chemistry capturing the margin pool as energy density improvements reduce per-unit pack costs. Fleet operators in Germany and France prioritize these for swap-station compatibility.
- Nickel-Metal Hydride:Intermediate performance with reduced thermal runaway risk. Niche applications in temperature-extreme climates where lithium-ion management complexity adds cost.
- Others:Emerging solid-state and sodium-ion prototypes in pilot deployment. Japanese manufacturers test these for second-life automotive cell integration.
Lithium-Ion carries the majority of current production volume; Others is climbing the fastest as next-generation chemistries mature.
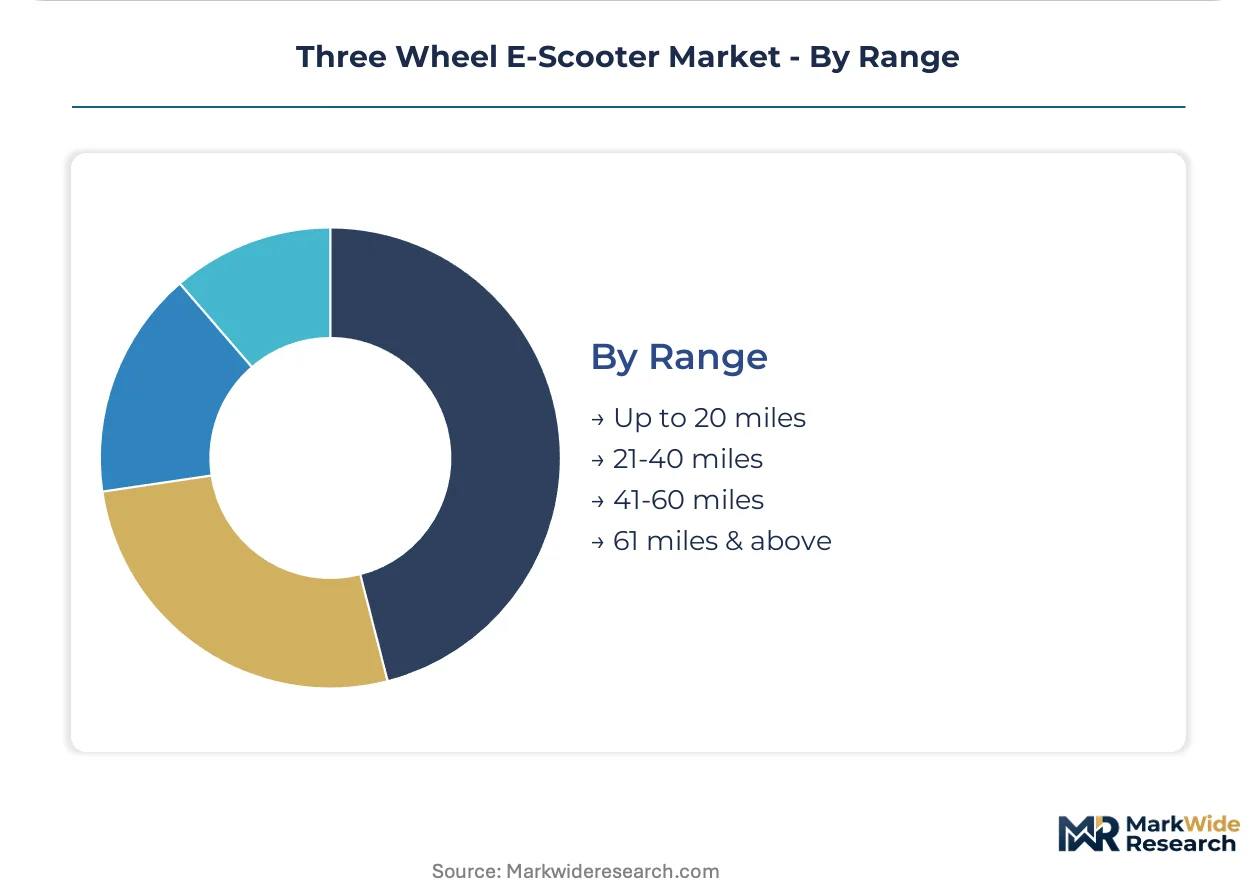
Range:
Energy capacity scaling directly influences vehicle weight, charging frequency, and total cost of ownership calculations.
- Up to 20 miles:Compact packs for neighborhood errands and short commutes. Retirees in Japan and Germany select these for medical-grade stability-assured personal transport.
- 21-40 miles:Standard commuter specification balancing weight and daily utility. German corporate leasing programs standardize on this band for predictable duty cycles.
- 41-60 miles:Extended range for suburban-rural connections and tour operator full-day rentals. California logistics pilots evaluate these for rural last-mile coverage.
- 61 miles & above:Maximum capacity configurations with dual-battery architectures. Premium tour operators in the American Southwest specify these for desert expedition services.
21-40 miles holds the greatest installed base; 61 miles & above is gaining share fastest as battery density improvements reduce pack mass penalties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cities concentrate procurement volume through municipal micro-mobility infrastructure expansion and commercial leasing programs. The EU Green Deal's transport electrification mandates accelerate fleet replacement timelines across multiple member states.
Germany
Municipal leasing programs in Berlin and Hamburg drive standard-segment procurement for predictable duty cycles. The EU Green Deal's vehicle homologation requirements compress replacement timelines for commercial operators. Baden-Württemberg hosts manufacturing clusters serving corporate mobility managers specifying premium configurations with connected telemetry.
United States
California and Texas logistics providers pilot vehicle-to-grid bidirectional charging to offset infrastructure costs through peak demand response. The US Consumer Product Safety Commission shapes crashworthiness standards for entry certification. Florida-based manufacturing and direct dealership control anchor southeastern distribution networks.
Netherlands
Corporate campus operators specify premium mid-drive configurations for employee shuttle services. The EU Machinery Directive governs electrical safety certifications for commercial fleet entry. Rotterdam and Amsterdam logistics networks prioritize three-wheel stability for dense urban core parcel distribution.
Japan
Aging demographics in Tokyo and Osaka drive demand for medical-grade stability-assured personal transport. METI oversees standards for second-life automotive cell integration into charging infrastructure. Kanto region manufacturers test solid-state and sodium-ion prototypes for next-generation chemistry deployment.
France
Corporate fleet managers in Paris and Lyon accelerate electrification under EU Green Deal compliance deadlines. The EU AI Act's autonomous mobility provisions extend type-approval timelines for machine-learning-enabled safety systems. Île-de-France concentrates notified body assessment protocol development for connected fleet operators.
Three Wheel E-Scooter Market Competitive Landscape
Capacity expansion dominates the current landscape as assemblers secure captive cell supply and deploy swap-station networks. The vendor base stratifies across three tiers: integrated battery-fleet operators, regional manufacturing specialists, and component-assembly traders. Two strategic archetypes have emerged: swap-network integrators leveraging proprietary infrastructure, and geography-anchored fabricators controlling dealership density. M&A activity and strategic partnerships concentrate around battery technology access and last-mile logistics contracting.
Within the swap-network integrator tier, Gogoro exemplifies the captive infrastructure model. Among regional manufacturing specialists, Bintelli occupies a position reflecting southeastern US market concentration. Segway sits within the scale-driven tier representing diversified personal mobility portfolio breadth. These three anchors illustrate how competitive positioning diverges between infrastructure-heavy and geography-anchored strategies.
| Leading Market Players |
|---|
| Gogoro |
| Bintelli |
| Karma |
| Razor |
| Xiaomi |
| Segway |
| Inokim |
| Super Soco |
| E-Twow |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap assemblers in Germany and Taiwan anchor supply-side discipline through captive dealership networks and direct fleet contracting, translating procurement scale into pricing power over battery pack negotiations while insulating premium-tier margins from spot-market volatility in cathode materials.
Pricing Analysis
Volume procurement by delivery fleet operators absorbs margin compression while individual consumer segments retain price sensitivity. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified configurations from municipal leasing specifications and basic commuter units. Pricing pressure stems from lithium-ion cell cost volatility as cathode material processing concentrates in China. Delivery services exhibit least price sensitivity due to total cost of ownership advantages over gasoline-powered alternatives.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Los Angeles anchor hub-and-spoke patterns for finished vehicle logistics. Cathode material processing and precursor refining cluster in China, South Korea, and Japan. Cell assembly draws from automotive-grade production lines with nickel-cobalt-manganese and lithium-iron-phosphate chemistries. Single-source vulnerability in semiconductor motor controllers creates exposure to foundry capacity constraints. Distribution runs through direct dealership networks in the United States and swap-station integrators in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The three-wheel e-scooter market sits in a lithium-ion battery transition phase as solid-state and sodium-ion prototypes displace legacy lead-acid and first-generation lithium-ion packs in commercial deployments.
For Market Incumbents: Extend swap-station network density in German and Dutch urban cores to lock in fleet operator loyalty before municipal leasing programs consolidate procurement. Secure captive cell supply agreements with Korean and Japanese tier-one suppliers to defend against cathode material price spikes. Invest in firmware transparency documentation to preempt EU AI Act certification delays for connected vehicle deployments. For New Entrants and Emerging Players: Vehicle-to-grid bidirectional charging hardware offers a technology-first wedge into California and Texas logistics markets where peak demand response revenue subsidizes acquisition costs. Target medical-grade stability-assured configurations for aging demographics in Japan and Germany where certification barriers deter mass-market competitors. Pursue direct contracting with municipal micro-mobility infrastructure programs rather than retail channel buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional manufacturing specialists with captive dealership control in underserved southeastern United States markets. Long-term viability hinges on battery technology access and swap-station infrastructure deployment scale. Watch for EU battery passport regulation implementation as inflection indicator for second-life cell certification pathway winners.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swap Network Expansion | Gogoro's proprietary station density in Taipei and Berlin locks fleet operators into captive cell ecosystems. |
| Vehicle-to-Grid Integration | California ISO participation allows logistics providers to monetize stored energy during peak demand windows. |
| Medical-Grade Certification Pathway | German KBA and Japan METI standards open accessibility segments with premium pricing and regulatory moats. |
| Second-Life Battery Repurposing | Automotive cell degradation curves enable stationary charging infrastructure cost reduction for network operators. |
| Direct Dealership Control | Florida-based manufacturing and southeastern distribution networks bypass swap-station capex for price-sensitive consumer segments. |
Research Methodology
Trade databases, EU transport electrification filings, and customs import records formed the secondary backbone for volume and value estimation. Primary interviews with fleet procurement managers at logistics operators, battery swap network engineers, municipal micro-mobility program directors, and tier-one cell supplier account executives validated demand assumptions. Bottom-up triangulation across vehicle registration data and top-down cross-check against battery pack shipment records ensured segmentation integrity.
Bottom-up modeling aggregated unit economics across product tiers while top-down verification tracked against lithium-ion cell demand absorption rates. Segmentation dimensions spanned motor configuration, battery chemistry, range specification, and end-use deployment pattern. CAGRs derived from logistic curve penetration modeling for fleet electrification mandates and consumer adoption saturation points. Forecast inputs incorporated EU Green Deal compliance timelines and swap-station deployment capex trajectories.
Several conditions sit outside the modeled scope, including autonomous mobility algorithm certification delays, trade policy friction affecting cathode material flows, and unannounced solid-state battery commercialization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Electric Car Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Norway Electric Cars Market