
 Electric Water Pump for Electric Vehicles Market | 2026-2036
Electric Water Pump for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Water Pump for Electric Vehicles Market Insights
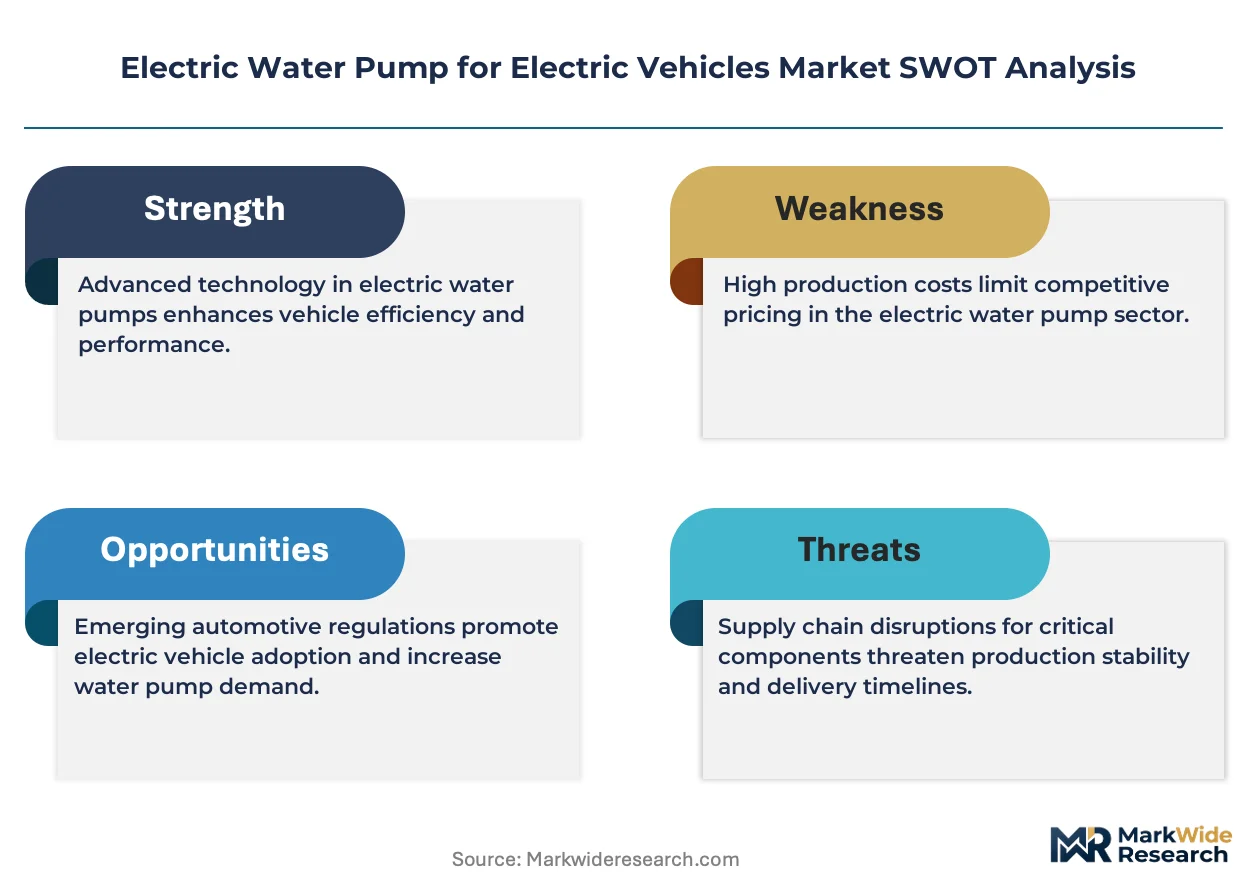
The capital-intensity divergence between integrated thermal system suppliers and standalone pump manufacturers is collapsing as battery cooling demands intensify. Robert Bosch GmbH leverages its powertrain electronics integration to bundle pump controllers with inverter assemblies, reducing wiring complexity for OEM customers. Continental AG sustains engineering presence across multiple magnetic drive platforms, competing on motor-pump efficiency benchmarks. Denso Corporation anchors its position through captive supply relationships with Toyota and Lexus electrified platforms.
An electric water pump for electric vehicles is an electronically actuated fluid circulation device, typically operating at 12V or 48V with brushless DC motors and rare-earth magnetic couplings, designed to manage coolant flow through battery packs, power electronics, and cabin heating circuits without mechanical dependence on engine rotation. Magnetic drive technology leads in new platform designs due to elimination of shaft seals and reduced maintenance liability, while centrifugal configurations dominate aftermarket replacement channels where cost sensitivity shapes procurement. OEM end users command the largest value pools as they specify integrated thermal modules, whereas fleet operators represent a concentrated growth vector as commercial electrification accelerates and uptime requirements demand predictive pump monitoring.
China's NMPA enforces GB standards for EV thermal safety, MIIT mandates energy consumption testing that rewards efficient auxiliary loads, and the EU's F-Gas Regulation restricts refrigerant choices that cascade into pump material specifications. These frameworks collectively elevate product certification costs while filtering out suppliers lacking in-house validation laboratories. Stakeholders must monitor how 800V platform proliferation alters flow-rate specifications and whether regional content rules reshape supplier geography faster than technology roadmaps evolve.
Market Dynamics
The transition to 800V battery architectures is compressing development cycles for thermal management suppliers, forcing simultaneous redesigns of pump flow curves, motor efficiency maps, and controller integration protocols to match faster charging speeds and extended-range drivetrains.
Growth Catalysts
- GB Standard Tightening:China's NMPA and MIIT enforcement of stricter EV component efficiency benchmarks accelerates magnetic drive adoption by penalizing parasitic losses in legacy pump designs.
- Commercial Fleet Electrification:Logistics operators deploying heavy-duty battery electric trucks generate concentrated demand for high-flow pumps with predictive monitoring capabilities to maximize vehicle uptime.
- 800V Platform Proliferation:OEM thermal system redesigns to support ultra-fast charging create specification windows for next-generation pumps with expanded operating temperature ranges.
Market Restraints
- Neodymium Price Volatility:Rare-earth magnet cost fluctuations constrain margin stability for magnetic drive pump manufacturers dependent on Chinese-processed rare-earth supply chains.
- Validation Laboratory Concentration:In-house thermal cycling and EMC testing capabilities cluster among integrated Tier 1 suppliers, elevating certification barriers for standalone pump specialists.
- Mechanical Seal Aftermarket Persistence:Cost-sensitive fleet maintenance channels continue specifying conventional shaft-seal pumps for replacement cycles, slowing magnetic drive penetration in service parts.
Strategic Opportunities
- India PLI Scheme Alignment:Component localization incentives under India's production-linked incentive framework attract pump manufacturing investments serving domestic EV assembly growth.
- Inverter-Pump Controller Integration:Convergence of power electronics and fluid actuation enables bundled thermal module offerings that reduce OEM wiring harness complexity.
- Predictive Service Contracts:IoT-enabled pump monitoring creates recurring revenue streams through condition-based maintenance agreements with commercial fleet operators.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Coupled thermal-fluid-electromagnetic modeling expertise remains concentrated among automotive Tier 1 engineering centers, constraining supplier R&D velocity.
- Dual Certification Timelines:Parallel NMPA GB validation and EU F-Gas material compliance extends product launch cycles by 8-14 months for China-exporting manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Water Pump for Electric Vehicles Market |
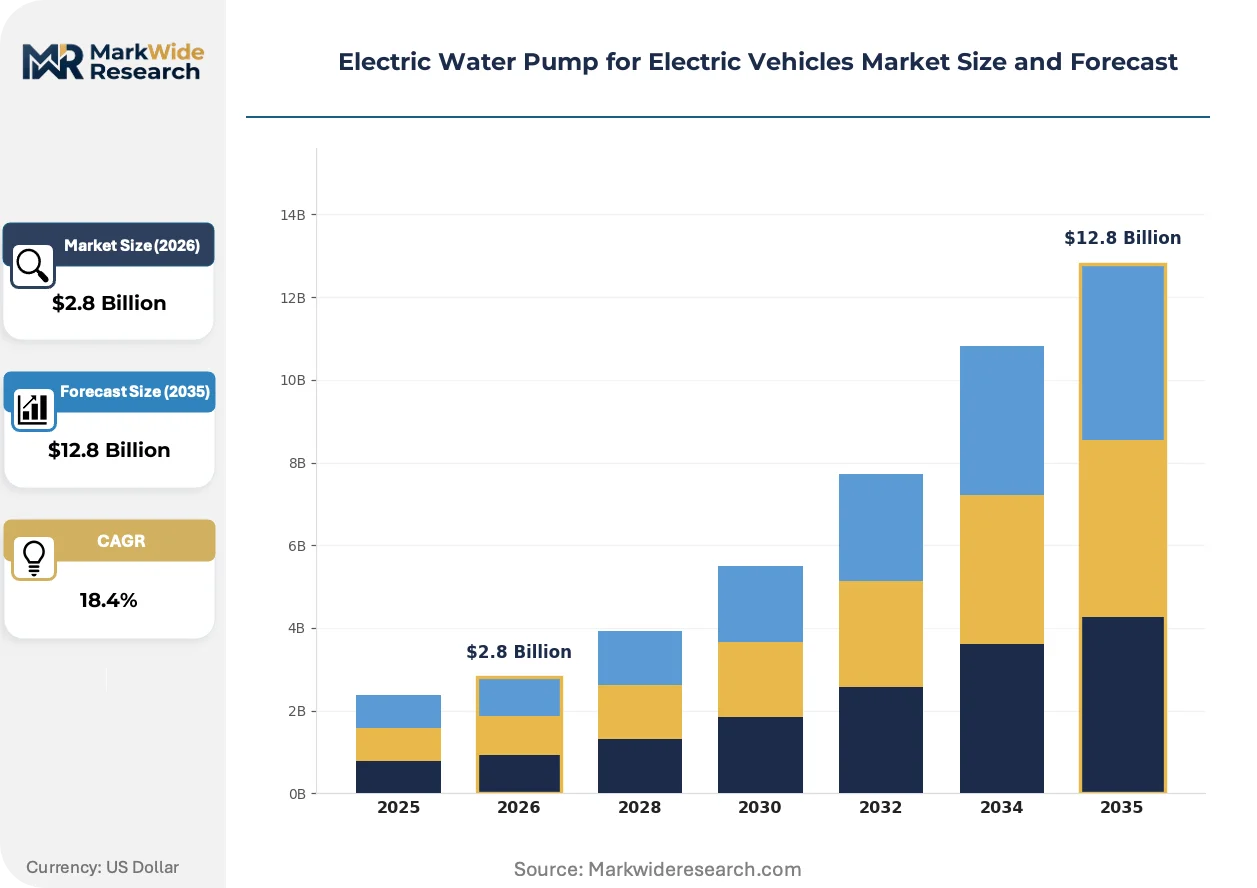
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Drive, Centrifugal, Submersible, Diaphragm End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Application: Cooling System, Heating, Battery Management, Thermal Regulation Installation: Integrated, Standalone, Modular, Custom |
| Companies Covered | Robert Bosch GmbH, Continental AG, Aisin Corporation, Rheinmetall AG, Hanon Systems, MAHLE GmbH, Denso Corporation, Valeo S.A., Gates Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Water Pump for Electric Vehicles Market Trends and Innovations
Magnetic drive architectures are overtaking mechanical seal designs across new EV platform specifications, while regulatory pressure on auxiliary energy consumption and commercial buyer demands for uptime visibility reshape supplier engineering priorities and service model economics.
Integrated motor-pump units with embedded Hall-effect position sensing are displacing externally commutated designs in premium BEV thermal modules. Luxury and performance EV platforms specify these compact assemblies to reclaim package space and eliminate controller-to-pump wiring. The technology is displacing discrete component sourcing strategies that previously allowed OEMs to separate motor and pump vendor selection.
Europe's F-Gas Regulation restricts refrigerant chemistries compatible with conventional pump elastomers, forcing material specification reviews across coolant circuit designs. Suppliers must validate new seal compounds and housing polymers against evolving propylene glycol and dielectric fluid formulations. Battery pack manufacturers serving EU-bound vehicle programs face compressed timelines to requalify thermal loop components.
Fleet procurement teams now require telematics-enabled pumps with CAN bus diagnostic outputs as standard specifications, unbundling hardware from traditional warranty-only service relationships. Predictive failure algorithms embedded in pump controllers enable third-party service providers to offer uptime guarantees. This shift concentrates most visibly in North American and European commercial vehicle electrification programs where total cost of ownership contracts dominate procurement evaluation.
Electric Water Pump for Electric Vehicles Market Segmentation
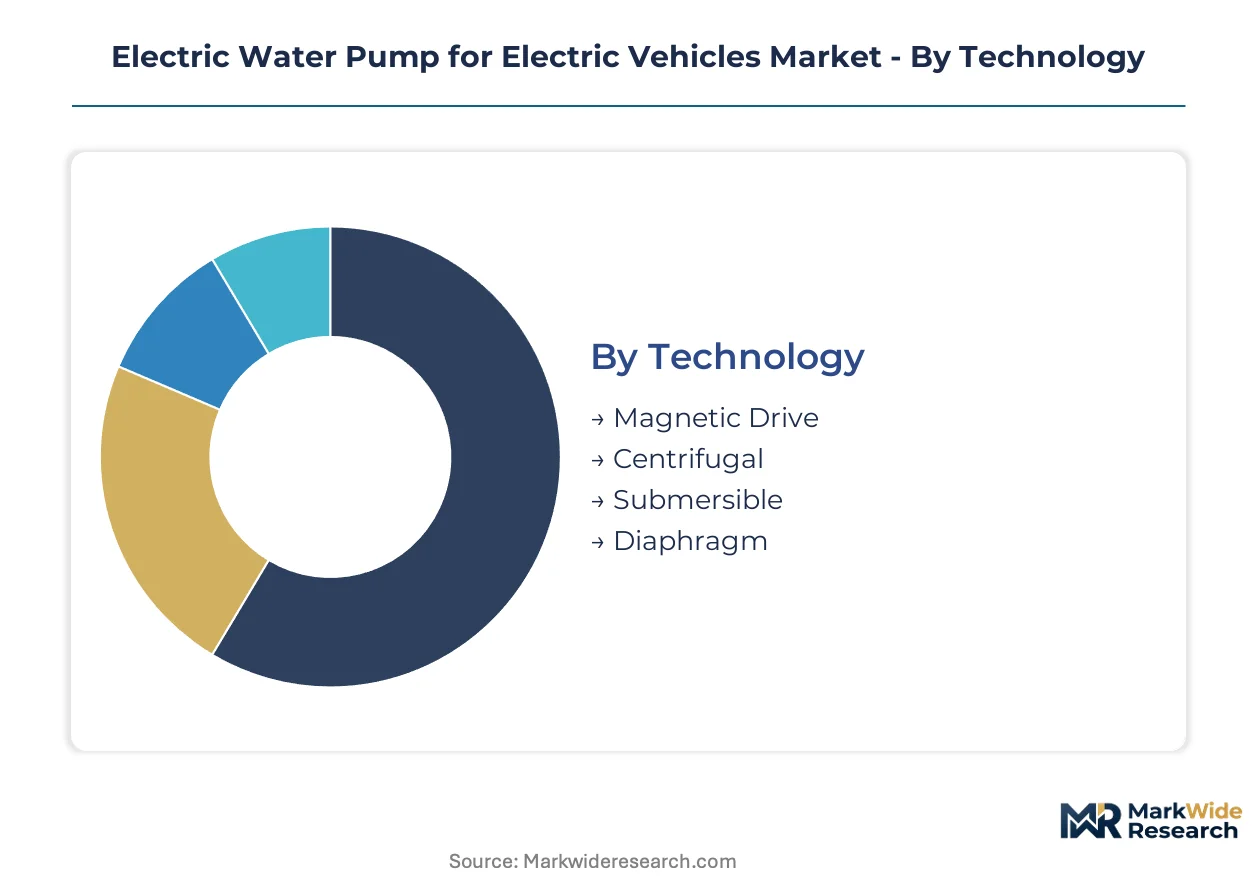
Thermal management architectures in electric vehicles fragment pump demand across multiple technical and commercial dimensions. Segment boundaries blur as 800V platforms force simultaneous redesigns of motor efficiency, flow curves, and controller integration.
Technology:
Magnetic drive platforms face substitution pressure from mechanically sealed designs in cost-sensitive aftermarket channels, while centrifugal configurations defend their position through established service infrastructure.
- Magnetic Drive:Rare-earth magnetic couplings eliminate shaft seals and reduce maintenance liability. OEM battery electric platforms specify these for 800V charging architectures, though neodymium supply concentration constrains margin stability.
- Centrifugal:Impeller-based flow generation dominates replacement cycles where fleet operators prioritize procurement simplicity over efficiency gains. Cost-sensitive maintenance channels sustain demand despite higher parasitic losses.
- Submersible:Immersed motor configurations suit compact battery pack layouts with limited external plumbing.
- Diaphragm:Positive displacement mechanisms handle viscous dielectric fluids in specialized power electronics cooling loops.
Centrifugal technology anchors the volume base through aftermarket persistence while magnetic drive gains share at the steepest rate on new platform specifications.
End User:
Procurement concentration varies sharply by customer type, with integrated thermal module sourcing diverging from discrete component purchasing.
- OEMs:Vehicle manufacturers specify embedded pump controllers within inverter assemblies to reduce wiring harness complexity. Bundled thermal modules command premium positioning through captive supply relationships with electrified platform programs.
- Fleet Operators:Logistics electrification programs generate concentrated demand for telematics-enabled pumps with CAN bus diagnostic outputs. Predictive monitoring capabilities support uptime guarantees under total cost of ownership contracts.
- Aftermarket Providers:Independent service channels favor mechanical seal replacements for installed base maintenance.
- Research Institutions:Validation laboratories procure specialized flow rigs for thermal cycling protocol development.
OEMs anchor the volume base through platform-scale procurement while fleet operators expand most quickly as commercial electrification accelerates.
Application:
Cooling intensity requirements diverge across vehicle subsystems, with battery thermal regulation imposing the most stringent flow-rate specifications.
- Cooling System:Power electronics and drivetrain thermal loops demand continuous coolant circulation independent of vehicle speed. Brushless DC motors with Hall-effect sensing displace externally commutated designs in premium module integration.
- Battery Management:Cell-level temperature uniformity requires multi-zone pump arrays with variable flow control. China's NMPA GB standards enforce thermal safety margins that elevate pump redundancy specifications.
- Heating:Cabin comfort circuits integrate with heat pump architectures for coefficient-of-performance optimization.
- Thermal Regulation:Combined heating and cooling loops in unified thermal management systems consolidate pump count through valve-controlled distribution.
Cooling system applications anchor the volume base through drivetrain ubiquity while battery management climbs the fastest on extended-range platform proliferation.
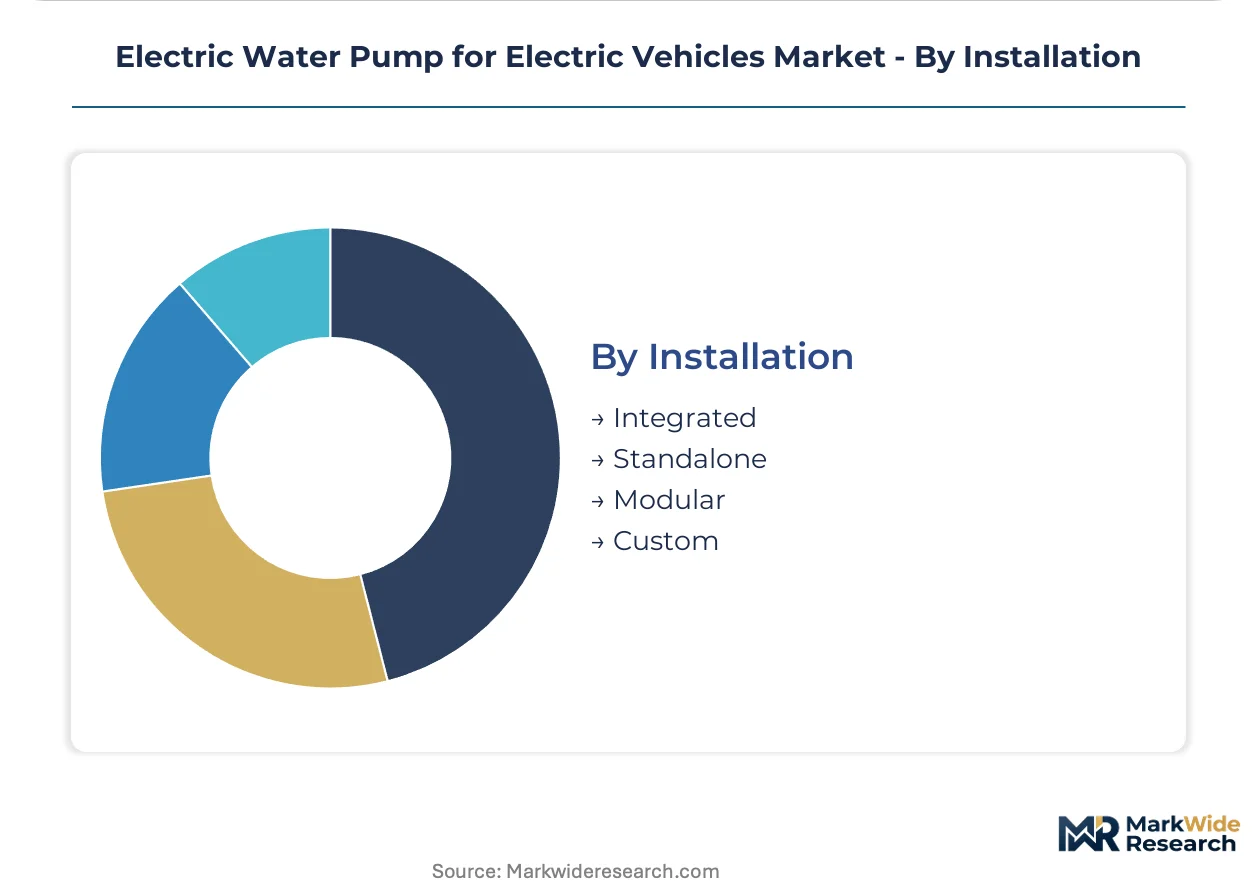
Installation:
Packaging constraints in electric vehicle architectures reshape how pump assemblies integrate with surrounding thermal hardware.
- Integrated:Motor-pump-controller units mount directly onto battery pack housings or power electronics enclosures. Space reclamation and wiring elimination drive specification in luxury BEV platforms.
- Standalone:Discrete pump assemblies persist in retrofit applications and legacy platform derivatives where thermal module redesign economics prove unfavorable.
- Modular:Standardized pump cartridges enable field-replaceable configurations for commercial vehicle uptime requirements.
- Custom:Application-specific flow curves and port geometries address niche performance EV and heavy-duty truck thermal architectures.
Standalone installations anchor the volume base through aftermarket persistence while integrated configurations gain share fastest on new platform clean-sheet designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in India and Southeast Asia negotiate hardest on unit price, while German and Chinese OEMs absorb premium magnetic-drive costs to secure platform integration contracts.
China
Domestic EV production exceeds all other national markets combined, creating unmatched pump procurement volumes. NMPA GB standards enforce thermal safety margins that elevate pump redundancy specifications. Shanghai and Shenzhen anchor supplier engineering centers where magnetic-drive platforms undergo validation for 800V architectures.
Germany
Premium OEM thermal module sourcing concentrates demand for integrated motor-pump-controller units. The EU F-Gas Regulation restricts refrigerant chemistries compatible with conventional pump elastomers, forcing material requalification. Stuttgart and Munich host Tier 1 engineering clusters developing Hall-effect sensing assemblies for luxury BEV platforms.
United States
Commercial fleet electrification programs generate concentrated demand for telematics-enabled pumps with predictive monitoring. NHTSA safety protocols influence thermal management system design specifications. Michigan and California anchor supplier technical centers serving Detroit Three and Silicon Valley EV programs.
Japan
Hybrid-to-battery-electric platform transitions sustain engineering relationships with integrated thermal system suppliers. METI energy efficiency guidelines reward auxiliary load reductions in pump motor designs. Nagoya and Tokyo metropolitan areas concentrate automotive electronics expertise for brushless DC motor development.
India
Domestic EV assembly growth attracts component manufacturing investments under PLI scheme incentives. BIS efficiency testing protocols shape local supplier product development priorities. Tamil Nadu and Maharashtra industrial corridors host emerging pump fabrication capacity serving Tata Motors and Mahindra electrified platforms.
Electric Water Pump for Electric Vehicles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive supply relationships and bundled thermal modules distinguishing the upper layer from discrete component vendors. The middle tier fragments across magnetic-drive specialists and centrifugal aftermarket suppliers competing on procurement simplicity. Three archetypes dominate: integrated thermal system houses with inverter-pump bundling capability, standalone pump manufacturers defending aftermarket channels, and rare-earth magnet processors controlling upstream material flows. Competitive moves center on backward integration into magnetic material supply and geographic expansion through localized assembly plants.
Within the integrated thermal system tier, Robert Bosch GmbH and Continental AG exemplify the bundled module approach, while Denso Corporation anchors the captive supply archetype through Toyota and Lexus platform relationships. These three occupy positions where powertrain electronics integration reduces OEM wiring complexity and commands premium positioning in electrified vehicle programs.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Aisin Corporation |
| Rheinmetall AG |
| Hanon Systems |
| MAHLE GmbH |
| Denso Corporation |
| Valeo S.A. |
| Gates Corporation |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week neodymium magnet lead times from Chinese processors compress inventory buffers for magnetic-drive pump manufacturers, concentrating pricing power among integrated Tier 1 suppliers with captive rare-earth sourcing while forcing standalone specialists toward spot-market exposure.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates OEM bundled thermal modules from fleet telematics-enabled units and aftermarket mechanical-seal replacements. Cost compression in economy tiers intensifies because centrifugal aftermarket suppliers compete on procurement simplicity. Fleet operators exhibit highest price sensitivity, while German and Chinese OEMs absorb magnetic-drive premiums for platform integration access.
Supply Chain Analysis
China dominates rare-earth magnet processing and brushless DC motor winding, while Germany anchors precision controller manufacturing and Japan supplies Hall-effect position sensors. Magnetic-drive pump production draws from neodymium-praseodymium alloy feedstock, copper winding wire, and silicon carbide power semiconductors. Single-source vulnerability concentrates in Chinese-processed rare-earth supply chains subject to export license volatility. Distribution runs through Tier 1 thermal system integrators bundling pump-inverter assemblies for OEM platform sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates on an electrification capex cycle tied to 800V platform rollout schedules, with thermal management supplier fortunes rising and falling with OEM battery architecture refresh cadence.
For Market Incumbents: Compound engineering presence across multiple magnetic-drive platforms to defend against emerging rare-earth magnet processors backward-integrating into pump assembly. Deepen captive supply relationships with Toyota and Lexus electrified platforms while adding validation laboratory capacity to filter out standalone pump specialists lacking in-house EMC testing. For New Entrants and Emerging Players: Differentiate on predictive monitoring algorithms for commercial fleet uptime guarantees, targeting North American and European logistics electrification programs where total cost of ownership contracts dominate procurement evaluation. Enter through modular pump cartridges for field-replaceable commercial vehicle configurations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming fluid power divisions lacking EV-specific magnetic-drive expertise. Five-to-ten-year viability hinges on 800V platform penetration sustaining flow-rate specification upgrades. Watch NMPA GB standard enforcement velocity as inflection indicator for magnetic-drive adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Secures neodymium processing capacity against Chinese export license volatility for magnetic-drive pump margins. |
| Inverter-Pump Controller Integration | Reduces OEM wiring harness complexity while commanding premium positioning in 800V thermal modules. |
| Predictive Service Contract Rollout | Creates recurring revenue streams through IoT-enabled condition-based maintenance with fleet operators. |
| India PLI Scheme Manufacturing Footprint | Captures localization incentives serving Tata Motors and Mahindra electrified platform growth. |
| Dual Certification Laboratory Investment | Compresses NMPA GB and EU F-Gas validation timelines for China-exporting manufacturers. |
Research Methodology
The analysis maps magnetic-drive pump platforms, centrifugal aftermarket configurations, and integrated thermal module architectures, each validated through procurement directors at OEM electrified platform programs, thermal system engineering leads at Tier 1 suppliers, fleet maintenance managers at commercial logistics operators, and aftermarket distribution channel heads. Primary interview insights triangulate against vehicle production databases, NMPA GB standard filings, EU F-Gas Regulation material compliance records, and customs trade data for rare-earth magnet flows. Bottom-up pump unit demand estimates reconcile with top-down thermal management system market sizing.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by technology platform, end-user procurement archetype, vehicle subsystem application, and installation packaging configuration, with CAGRs derived from fitted growth curves applied to segment-level base values. Modeled inputs incorporate 800V charging architecture proliferation rates, commercial fleet electrification program announcements, and regional content rule evolution.
Material uncertainties — neodymium price volatility, NMPA enforcement intensity variations, and 800V platform adoption delays — sit outside the modeled envelope. Forecasts reflect assumptions about magnetic-drive technology substitution rates and aftermarket mechanical-seal persistence. Recalibration cycles align with material shifts in OEM battery architecture roadmaps and rare-earth supply policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
New Energy Vehicle (NEV) Market