
 Data Center Construction Market | 2026-2036
Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Construction Market Intelligence
The EU Green Deal is expanding power efficiency mandates for data center operators across member states. AECOM leverages its integrated design-build platform to capture hyperscale contracts in Northern Virginia and Frankfurt. Turner Construction Company anchors its position through self-perform electrical and mechanical capabilities that compress delivery schedules. DPR Construction Inc. differentiates via lean construction methodologies that reduce material waste on large-scale campuses.
Data center construction encompasses the design, engineering, and physical build-out of facilities housing compute, storage, and networking infrastructure, typically requiring power densities exceeding 150 watts per square foot and precision cooling systems maintaining temperatures within strict bands. The primary purpose is creating controlled environments that ensure continuous uptime for digital service delivery. Hyperscale facilities command the largest capital allocation pools as cloud service providers and colocation providers expand footprint. Modular and prefabricated construction types are gaining share by enabling parallel manufacturing of power and cooling modules while site work progresses, compressing overall project duration.
EPA Energy Star certification and EU Code of Conduct for Data Centres establish operational efficiency baselines that shape design specifications and equipment selection. OSHA workplace safety standards and national electrical codes govern construction-phase protocols and commissioning requirements. Stakeholders must monitor evolving carbon disclosure rules and local permitting timelines that increasingly determine project feasibility and total cost of ownership.
Market Dynamics
Hyperscale cloud operators are compressing delivery timelines for multi-hundred-megawatt campuses, forcing contractors to modularize power and cooling systems while site preparation proceeds in parallel. This structural acceleration is reshaping contractor capability requirements and procurement patterns across Northern Virginia, Frankfurt, and Mumbai.
Growth Catalysts
- EU Green Deal efficiency mandates:The EU Green Deal tightens power usage effectiveness thresholds for new facilities, compelling operators to adopt advanced cooling architectures and renewable energy integration.
- Hyperscale cloud expansion:Cloud service providers in the United States, Germany, and India are commissioning record-breaking campus developments to support generative AI training workloads.
- Liquid cooling adoption:Direct-to-chip and immersion cooling technologies are enabling power densities exceeding 150 kilowatts per rack, unlocking facility designs previously thermally constrained.
Market Restraints
- Electrical equipment supply concentration:High-voltage switchgear and uninterruptible power supply systems face extended lead times from concentrated European and Asian manufacturing bases.
- Skilled craft labor scarcity:Certified electricians and precision HVAC technicians command premium wages in Northern Virginia and Frankfurt, inflating installed cost structures.
- Utility interconnection queues:Grid connection approvals in the United States stretch 36-48 months, freezing project commencements despite site readiness.
Strategic Opportunities
- India data center buildout:Mumbai, Chennai, and Hyderabad offer greenfield development potential with improving submarine cable connectivity and state-level data center policies.
- Carbon-neutral certification demand:LEED and BREEAM certifications are becoming table stakes for enterprise colocation contracts, creating differentiation for early adopters.
- Prefabricated modular integration:Factory-built power modules and cooling skids are converging with containerized compute, enabling deployment cycles measured in months rather than years.
Industry Challenges
- Commissioning complexity:Integrated systems testing for hyperscale facilities requires specialized protocols that extend handover timelines and strain quality assurance teams.
- Permitting fragmentation:Local zoning authorities in the United States, German Länder environmental offices, and Indian state pollution control boards impose inconsistent requirements that stall project approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Construction Market |
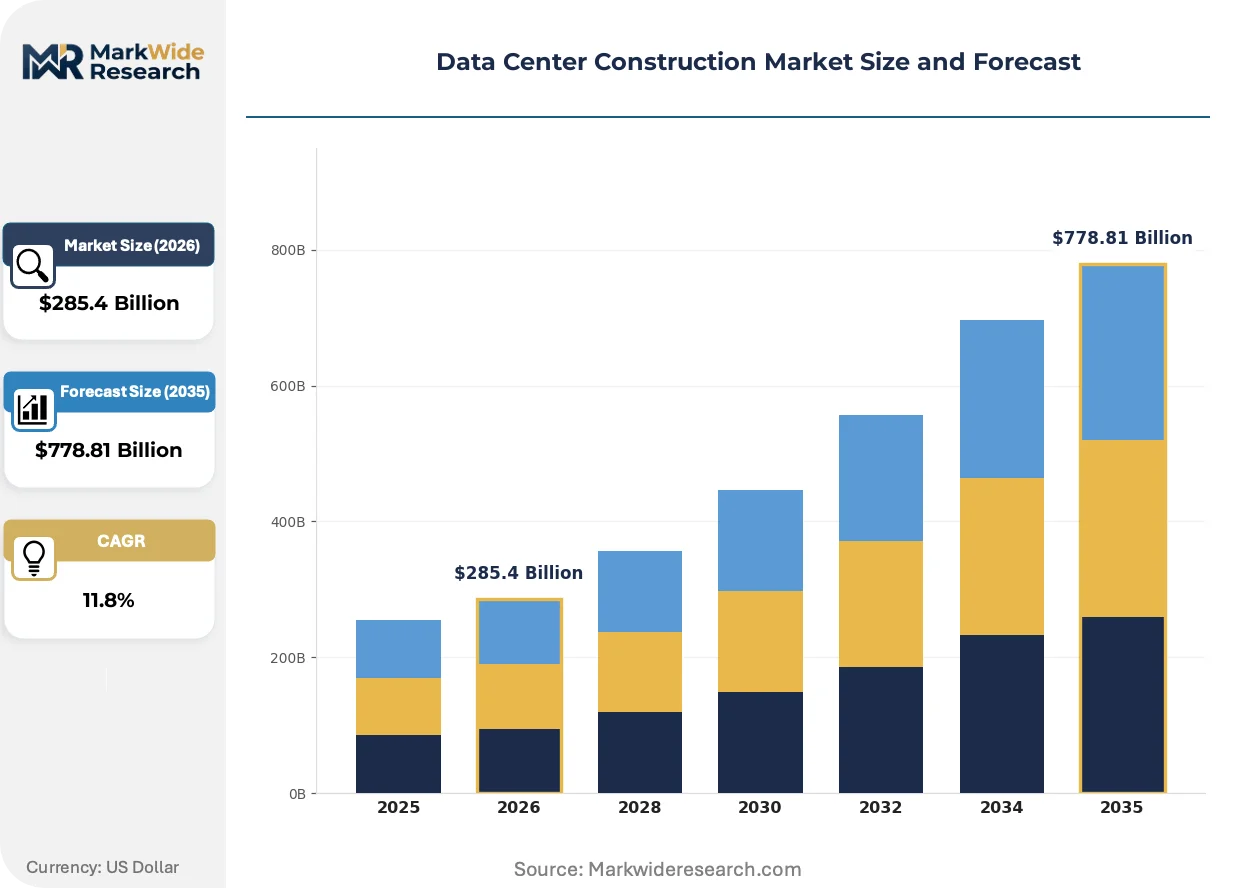
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $778.81 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Greenfield, Brownfield, Modular, Prefabricated Facility Size: Small-Scale, Medium-Scale, Hyperscale, Mega-Scale Application: Cloud Service Providers, Colocation Providers, Content Delivery Networks, Telecommunication Providers End User: Enterprise IT, Managed Service Providers, Government Agencies, Research Institutions |
| Companies Covered | AECOM, Turner Construction Company, DPR Construction Inc., Holder Construction Company, Jacobs, Skanska, Mace, Equans, Collen Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Construction Market Strategic Shifts & Innovations
Construction methodologies are converging with manufacturing disciplines as data center projects scale beyond traditional building delivery models. Three distinct vectors are compressing project timelines while tightening environmental performance.
Prefabricated electrical houses and skid-mounted cooling plants are unifying factory quality control with site construction speed. Hyperscale operators in Northern Virginia and Frankfurt are specifying 90% factory-completion targets for critical infrastructure modules. This shift is unifying supply chain management with construction project management, collapsing the traditional design-bid-build sequence into integrated delivery platforms.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in precision cooling equipment, accelerating adoption of natural refrigerant systems and liquid cooling architectures. Equipment manufacturers are reengineering chiller product lines to comply with tightened global warming potential thresholds. Colocation providers in Germany and the Netherlands are responding fastest, driven by corporate sustainability commitments and regulatory disclosure requirements under the EU Green Deal.
Enterprise buyers are consolidating vendor relationships around design-build contractors with self-perform electrical and mechanical capabilities. This concentration displaces fragmented subcontractor management models that dominated previous development cycles. The United States exhibits the most pronounced shift, with cloud operators preferring single-source accountability for schedule and cost performance on multi-phase campus rollouts.
Data Center Construction Market Segmentation
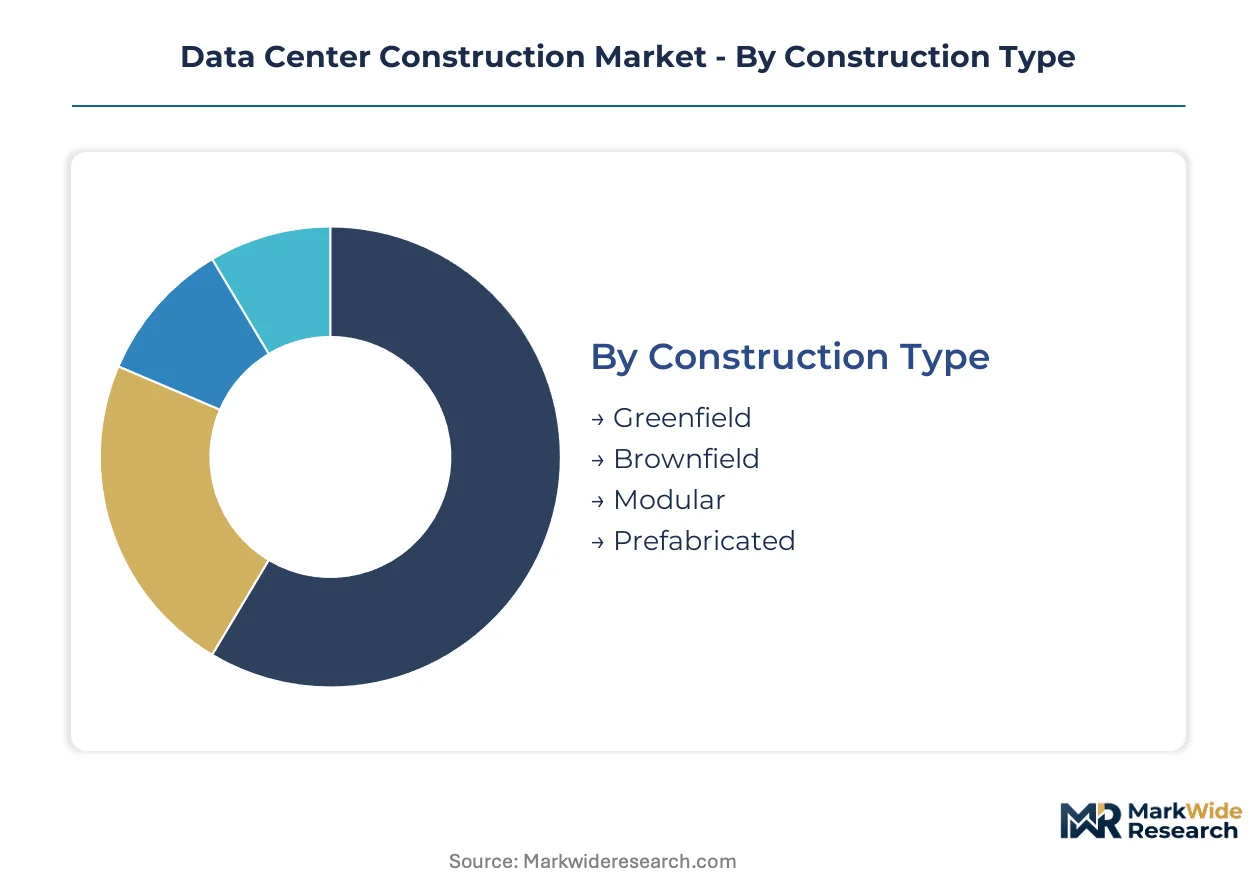
Segmentation reveals how contractor capabilities, delivery timelines, and capital intensity vary across project archetypes. Understanding these divisions clarifies where procurement budgets concentrate and which construction methodologies command premium pricing.
Construction Type:
Supply concentration in electrical equipment and precision HVAC systems favors contractors with pre-established vendor relationships and modular fabrication partnerships.
- Greenfield:Ground-up development on undeveloped land requiring full civil, electrical, and mechanical infrastructure. Cloud service providers in Northern Virginia and Frankfurt dominate this segment as they commission multi-hundred-megawatt campuses with dedicated substations and on-site renewable generation.
- Modular:Factory-built power and cooling modules integrated with site-built shells, enabling parallel workstreams. Hyperscale operators specify 90% factory-completion targets for critical infrastructure, compressing delivery schedules from years to months.
- Brownfield:Retrofit and expansion of existing facilities with constrained power and cooling headroom. Colocation providers use this approach in mature markets where land scarcity limits greenfield options.
- Prefabricated:Containerized or skid-mounted systems shipped to site for rapid deployment. Content delivery networks and edge computing operators favor this format for distributed infrastructure rollouts.
Greenfield absorbs the bulk of installed capacity; modular is expanding most quickly.
Facility Size:
Cost tier stratification separates hyperscale megaprojects with billion-dollar capital envelopes from smaller deployments with standardized design templates.
- Hyperscale:Facilities exceeding 50 megawatts with power densities above 150 kilowatts per rack. These projects demand integrated design-build delivery and self-perform electrical capabilities that only a handful of contractors possess.
- Small-Scale:Edge and enterprise deployments under 5 megawatts with shorter commissioning cycles. Managed service providers and regional enterprises drive demand for rapid-deployment formats with simplified permitting pathways.
- Mega-Scale:Campus developments exceeding 200 megawatts with phased expansion capacity. Cloud service providers in India and Germany are commissioning these complexes to support generative AI training clusters.
- Medium-Scale:Colocation facilities between 5 and 50 megawatts serving multi-tenant requirements. These projects balance customization demands with repeatable design elements.
Hyperscale commands the largest capital allocation pools; mega-scale is climbing the fastest as AI workloads reshape facility specifications.
Application:
Customer type determines thermal design, redundancy tier, and connectivity requirements with minimal overlap between segments.
- Cloud Service Providers:Purpose-built facilities with proprietary server architectures and liquid cooling integration. These operators specify direct-to-chip cooling to support power densities exceeding 150 kilowatts per rack.
- Content Delivery Networks:Distributed edge nodes prioritizing network latency over compute density. These deployments favor prefabricated formats with minimal on-site construction.
- Colocation Providers:Multi-tenant facilities with flexible power and cooling configurations to accommodate diverse client requirements. Carbon-neutral certification under LEED and BREEAM standards is becoming a contract prerequisite.
- Telecommunication Providers:Facilities integrating cellular infrastructure with centralized compute pools. 5G network densification is driving demand for hybrid edge-core architectures.
Cloud service providers absorb the bulk of installed capacity; colocation providers are gaining share fastest as enterprises outsource infrastructure ownership.
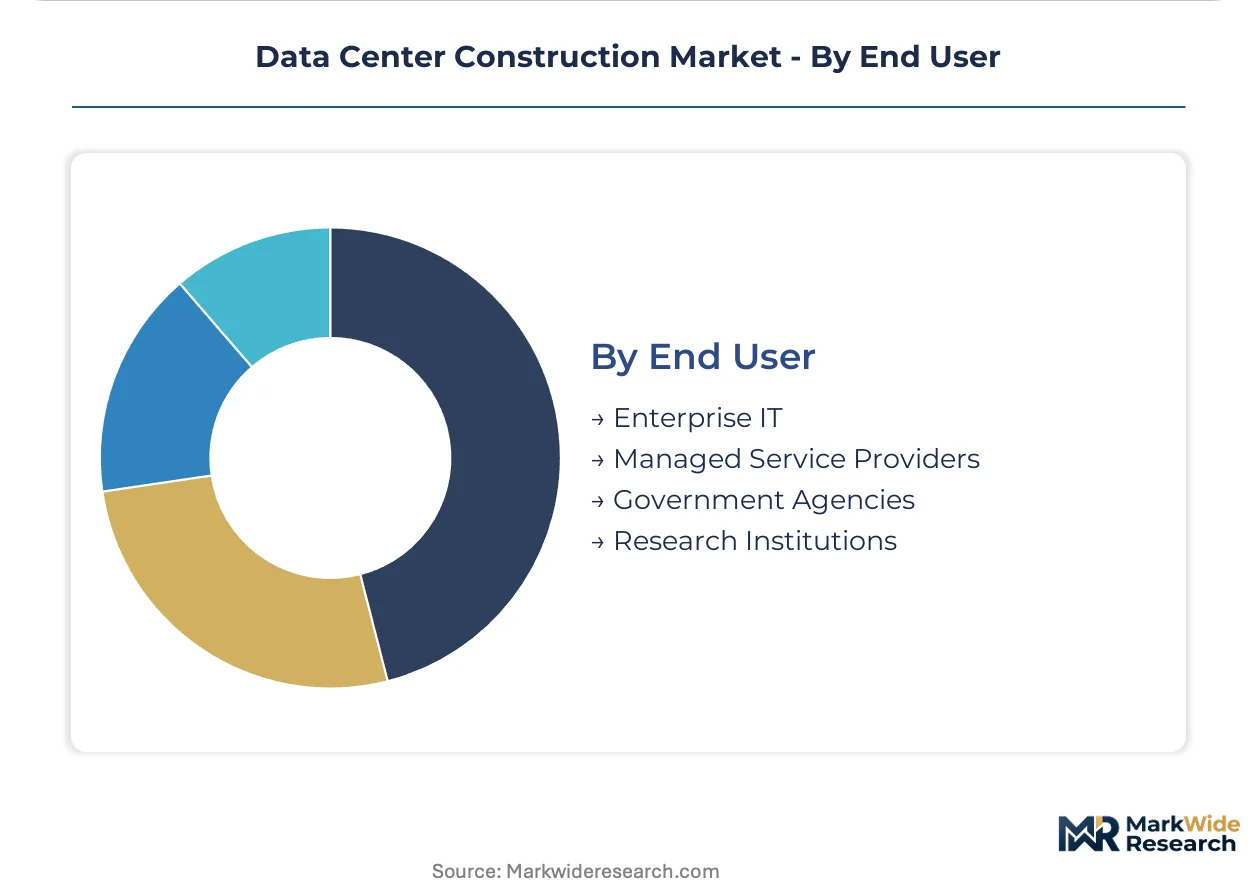
End User:
Maturity levels vary significantly, with government and research segments imposing unique security and performance specifications that fragment contractor specialization.
- Enterprise IT:Corporate-owned facilities with varying redundancy requirements based on business criticality. Financial services and healthcare verticals drive demand for Tier III and Tier IV certifications.
- Government Agencies:Classified and unclassified facilities with FedRAMP, FISMA, or comparable security mandates. These projects require cleared personnel and specialized commissioning protocols.
- Managed Service Providers:Outsourced infrastructure operations for mid-market enterprises without internal data center expertise. These customers prioritize operational SLAs over capital ownership.
- Research Institutions:High-performance computing clusters with extreme power density and specialized cooling architectures. National laboratories and university consortia in the United States and Germany anchor this segment.
Enterprise IT retains the largest installed base; government agencies are expanding most quickly as sovereign cloud mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley anchors global construction activity, with Loudoun County hosting the world's densest concentration of hyperscale facilities. Cloud operators commission multi-hundred-megawatt campuses here, compressing delivery timelines through modular power integration.
United States
Hyperscale cloud operators drive demand across Northern Virginia, Dallas-Fort Worth, and Phoenix markets. EPA Energy Star certification shapes cooling equipment specifications for new builds. Loudoun County's Data Center Alley hosts the world's densest facility concentration, with developers pursuing 90% factory-completion targets for critical infrastructure modules.
Germany
Frankfurt's financial hub status attracts colocation and cloud investment requiring Tier III+ redundancy. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, accelerating natural refrigerant adoption in precision cooling systems. The Rhine-Main region concentrates development activity, with operators integrating renewable energy to meet EU Green Deal disclosure requirements.
India
Mumbai, Chennai, and Hyderabad emerge as primary hyperscale destinations with improving submarine cable connectivity. State-level data center policies in Maharashtra and Telangana streamline permitting for foreign operators. The Mumbai-Pune corridor anchors initial development waves, with developers navigating Central Electricity Authority grid interconnection protocols.
United Kingdom
Slough and London's Docklands sustain colocation demand from financial services and media verticals. BREEAM certification requirements tighten environmental performance benchmarks for planning approvals. The Thames Valley corridor maintains development momentum despite land constraints, with operators retrofitting existing industrial estates for brownfield expansion.
Netherlands
Amsterdam's connectivity hub attracts cloud and content delivery network investment. National moratoriums on hyperscale development in certain municipalities redirect activity to peripheral provinces. The Eemshaven industrial zone emerges as an alternative concentration point, leveraging direct North Sea cable landing access and renewable energy procurement.
Data Center Construction Market Key Industry Players
Premium-margin players sit above commodity-margin players across self-perform electrical and mechanical capability depth. The contractor base concentrates around integrated design-build platforms capable of compressing multi-phase campus delivery schedules. Three archetypes dominate: full-service design-build contractors with self-perform trades, specialized data center pure-plays with lean methodologies, and diversified construction conglomerates with modular fabrication partnerships. Competitive intensity manifests through capacity pre-commitments to hyperscale operators and vertical integration into factory-built power module production.
Among North American integrated contractors, AECOM, Turner Construction Company, and DPR Construction Inc. exemplify the design-build archetype with self-perform capabilities. AECOM leverages its engineering heritage across Northern Virginia and Frankfurt hyperscale contracts. Turner Construction Company anchors market position through electrical and mechanical self-performance that compresses commissioning timelines. DPR Construction Inc. represents lean construction methodology adoption, reducing material waste on large-scale campus developments. These three occupy positions where single-source accountability for schedule and cost performance commands procurement preference from cloud operators.
| Leading Market Players |
|---|
| AECOM |
| Turner Construction Company |
| DPR Construction Inc. |
| Holder Construction Company |
| Jacobs |
| Skanska |
| Mace |
| Equans |
| Collen Construction |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between LEED Platinum hyperscale campuses and uncertified brownfield retrofits drives divergent pricing architectures and procurement configurations across the data center construction market. Premium-tier contracts in Northern Virginia and Frankfurt command substantial uplifts for integrated design-build delivery with self-perform electrical capabilities, while commodity-tier pricing prevails in secondary Indian markets where fragmented subcontractor models dominate procurement.
Pricing Analysis
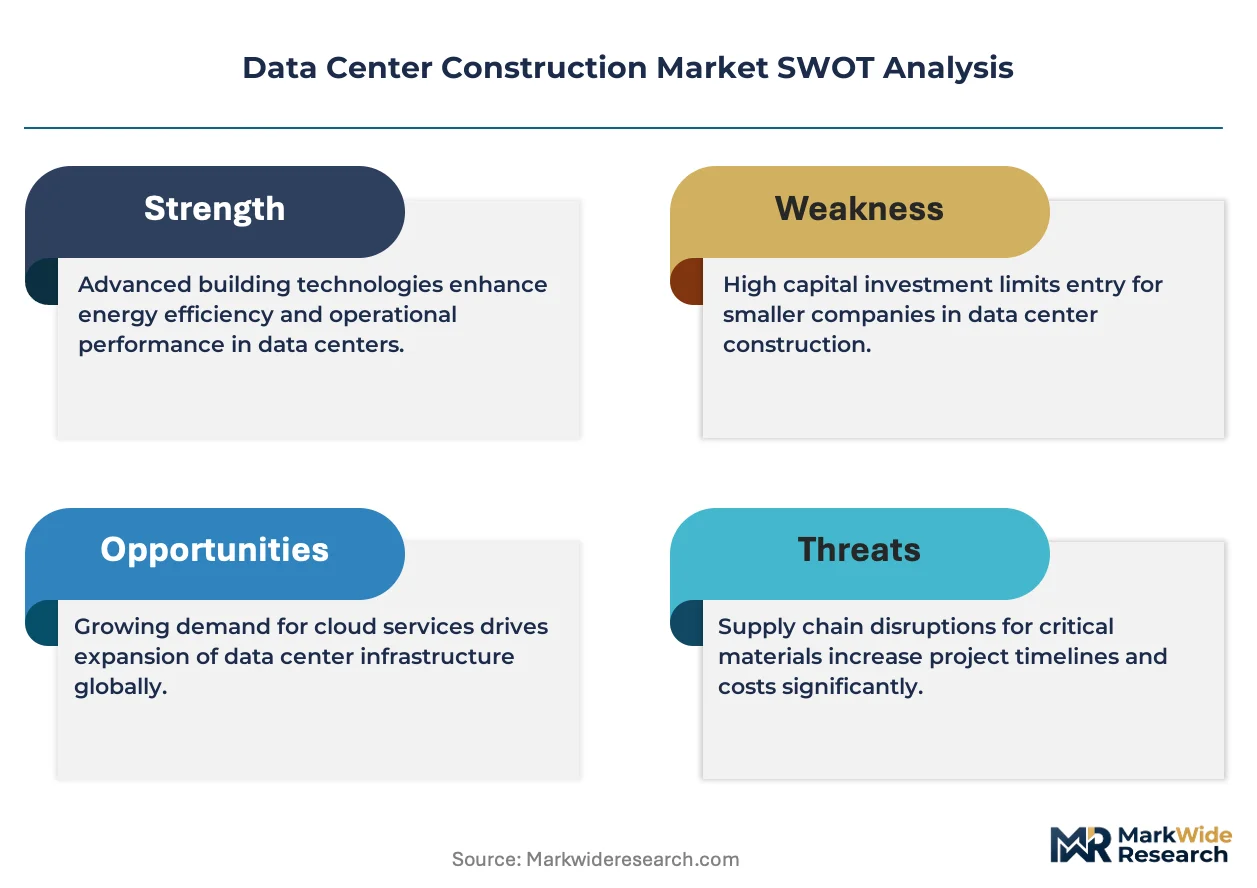
Uptime guarantee pricing anchors contract structures, with Tier III and Tier IV certification premiums reflecting redundancy architecture investments and operational continuity commitments. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale cloud operators with billion-dollar capital envelopes from regional colocation providers and edge computing deployments. Cost compression in the economy tier intensifies because modular prefabrication is displacing traditional stick-built methods, eroding margins for contractors lacking factory partnerships. Managed service providers exhibit the highest price sensitivity, prioritizing operational SLAs over capital ownership, while cloud service providers demonstrate the lowest sensitivity given throughput-dependent revenue models.
Supply Chain Analysis
Refurbishment flows for switchgear and precision HVAC components are emerging as secondary supply channels as extended lead times from European and Asian manufacturing bases strain project timelines. High-voltage electrical equipment concentrates in Germany, China, and South Korea, while precision cooling systems draw from Japanese and Dutch engineering centers. Copper busbar, fluorinated refrigerants, and silicon steel laminations constitute critical input dependencies. Single-source vulnerability in uninterruptible power supply systems poses structural risk as concentrated manufacturing faces export control scrutiny. Distribution runs through direct OEM relationships with hyperscale operators, bypassing traditional construction material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center construction is becoming a vertical-integration race as contractors pursue captive supply of factory-built power modules to compress delivery timelines and capture margin pools previously allocated to equipment vendors.
For Market Incumbents: To counter modular pure-plays eroding market share in Northern Virginia, AECOM and Turner Construction Company should deepen backward integration into electrical house fabrication and secure exclusive partnerships with European switchgear manufacturers. Capacity addition in Frankfurt's Rhine-Main corridor and captive supply of skid-mounted cooling plants represent critical defensive levers against schedule compression demands from hyperscale operators. For New Entrants and Emerging Players: Capture greenfield development waves in India's Mumbai-Pune corridor where state-level data center policies are streamlining permitting for foreign operators. State-level incentive arbitrage in Telangana and Maharashtra offers the most penetrable geographic entry point. A go-to-market angle anchored in liquid cooling integration for generative AI training clusters differentiates against established contractors with legacy air-cooled expertise. For Investors and Strategic Acquirers: Re-rating potential sits with lean construction specialists given EU Green Deal disclosure requirements accelerating demand for material waste reduction and carbon-neutral certification capabilities. Long-term viability over the next decade hinges on design-build platforms with self-perform electrical and mechanical trades. The signal to watch is hyperscale operator pre-commitment announcements for multi-phase campus rollouts, indicating contractor capacity allocation and pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Partnership | Factory-built power modules compress Northern Virginia delivery timelines from years to months. |
| Self-Perform Electrical Capability | In-house electrical trades reduce commissioning timelines and capture margin from subcontractor displacement. |
| Natural Refrigerant Transition | EU F-Gas Regulation compliance opens German colocation contracts with corporate sustainability mandates. |
| India Greenfield Expansion | Maharashtra state policies and submarine cable connectivity anchor Mumbai-Pune corridor development. |
| Carbon-Neutral Certification Program | LEED and BREEAM credentials become table stakes for enterprise colocation procurement decisions. |
Research Approach
SEC filings, hyperscaler capital expenditure disclosures, and EU regulatory databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with data center development executives, EPC contractor project directors, utility interconnection planners, and precision HVAC procurement managers validated demand assumptions and construction timeline benchmarks. Bottom-up project pipeline aggregation across Northern Virginia, Frankfurt, Mumbai, and Amsterdam combined with top-down infrastructure investment flow analysis to triangulate market value estimates.
Bottom-up modeling traced individual hyperscale campus developments through permitting, construction, and commissioning phases, while top-down analysis tracked cloud service provider and colocation provider capital allocation patterns. Segmentation dimensions included construction type, facility size tier, application archetype, and regional regulatory cluster. CAGRs were derived from installed capacity growth trajectories and capital intensity per megawatt assumptions. Forecast inputs incorporated utility interconnection queue dynamics and EU Green Deal efficiency mandate compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to utility interconnection approval timelines and refrigerant phase-down regulations. Forecasts reflect documented assumptions regarding modular adoption rates and skilled labor availability in concentrated construction markets. Material deviation in hyperscale operator pre-commitment velocity or F-Gas Regulation enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Germany Data Center Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Data Center As a Service Market