
 Global Sodium Lauryl Sulfate Market | 2026-2036
Global Sodium Lauryl Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Lauryl Sulfate Market Foresight
Asset-light toll manufacturing and third-party surfactant leasing arrangements are reshaping competitive entry barriers in sodium lauryl sulfate production. Stepan Company leverages its integrated alkyl sulfate chain to sustain cost discipline across North American supply. Sasol Limited anchors its position through Fischer-Tropsch-derived feedstock control in South Africa and Europe. BASF SE competes via broad formulation-grade portfolios spanning cosmetic and industrial specifications.
Sodium lauryl sulfate is an anionic surfactant synthesized through sulfation of lauryl alcohol followed by neutralization with sodium carbonate or sodium hydroxide, typically yielding active matter concentrations between 28% and 30% in liquid form. It functions primarily as a foaming agent, emulsifier, and wetting agent across consumer and industrial formulations. Liquid SLS dominates volume flows due to ease of handling in continuous detergent manufacturing, while pharmaceutical-grade powder commands concentrated margin pools in oral care and topical drug delivery. Personal care applications lead value contribution, though agriculture chemical formulations represent the fastest-expanding demand segment as adjuvant requirements intensify.
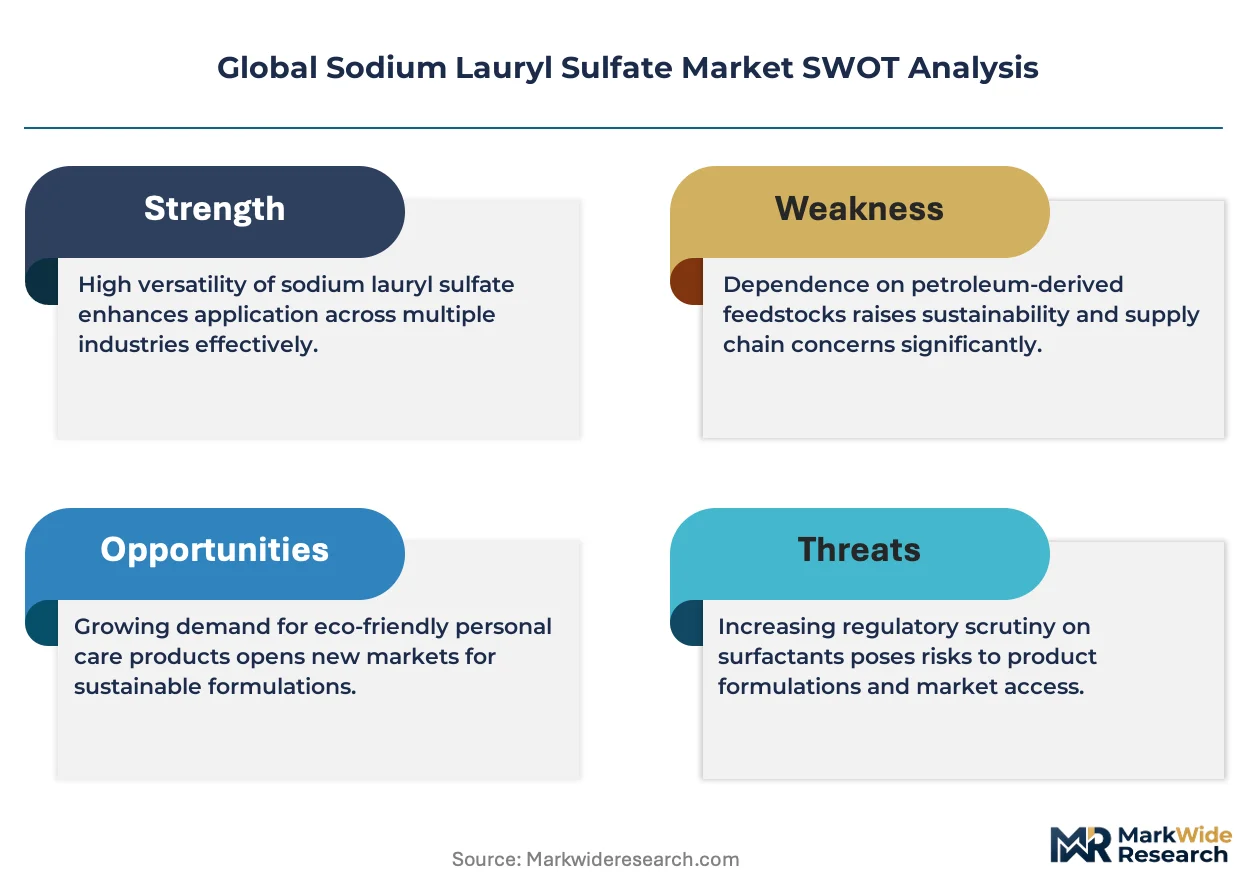
FDA oversight of cosmetic-grade SLS purity, REACH registration mandates for surfactant importers into Europe, and China's GB standards for industrial chemical safety collectively elevate compliance costs and favor producers with certified multi-grade capabilities. The EU Green Deal's biodegradability thresholds are forcing reformulation investments across European supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to optimize grade-mix decisions and avoid stranded inventory in cross-border trade.
Market Dynamics
REACH registration mandates and the EU Green Deal's biodegradability thresholds are forcing simultaneous compliance investments and feedstock transitions across European supply chains, compressing margins for non-integrated producers while advantaging those with certified multi-grade capabilities.
Growth Catalysts
- EU Green Deal mandates:Biodegradability thresholds for anionic surfactants are accelerating reformulation investments, creating certified-grade premiums for compliant producers.
- Agricultural adjuvant demand:Crop protection formulators in India and Brazil are expanding SLS procurement for pesticide wetting agents as intensive farming spreads.
- China's GB standard harmonization:Industrial chemical safety certifications are consolidating domestic production, streamlining export qualification for certified Chinese manufacturers.
Market Restraints
- Lauryl alcohol feedstock volatility:Palm kernel and coconut oil price swings transmit directly to SLS cost structures, squeezing toll manufacturers without backward integration.
- South African supply concentration:Fischer-Tropsch-derived feedstock control by a limited producer base creates single-source vulnerability for European and Asian buyers.
- Sulfate-free substitution pressure:Personal care brands are reformulating around milder surfactants in premium shampoo and facial cleanser segments.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Production-linked incentives are attracting capacity investments for export-oriented surfactant manufacturing.
- Pharmaceutical-grade powder expansion:Oral care and topical drug delivery applications command concentrated margin pools with limited qualified suppliers.
- Bio-based lauryl alcohol convergence:Fermentation-derived feedstocks are hybridizing with traditional oleochemical routes, opening certification pathways for EU market access.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB standard compliance requires 18-24 month qualification cycles that strand development capital.
- Continuous manufacturing integration:Liquid SLS handling systems demand capex-heavy process redesign for detergent producers shifting from batch operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Lauryl Sulfate Market |
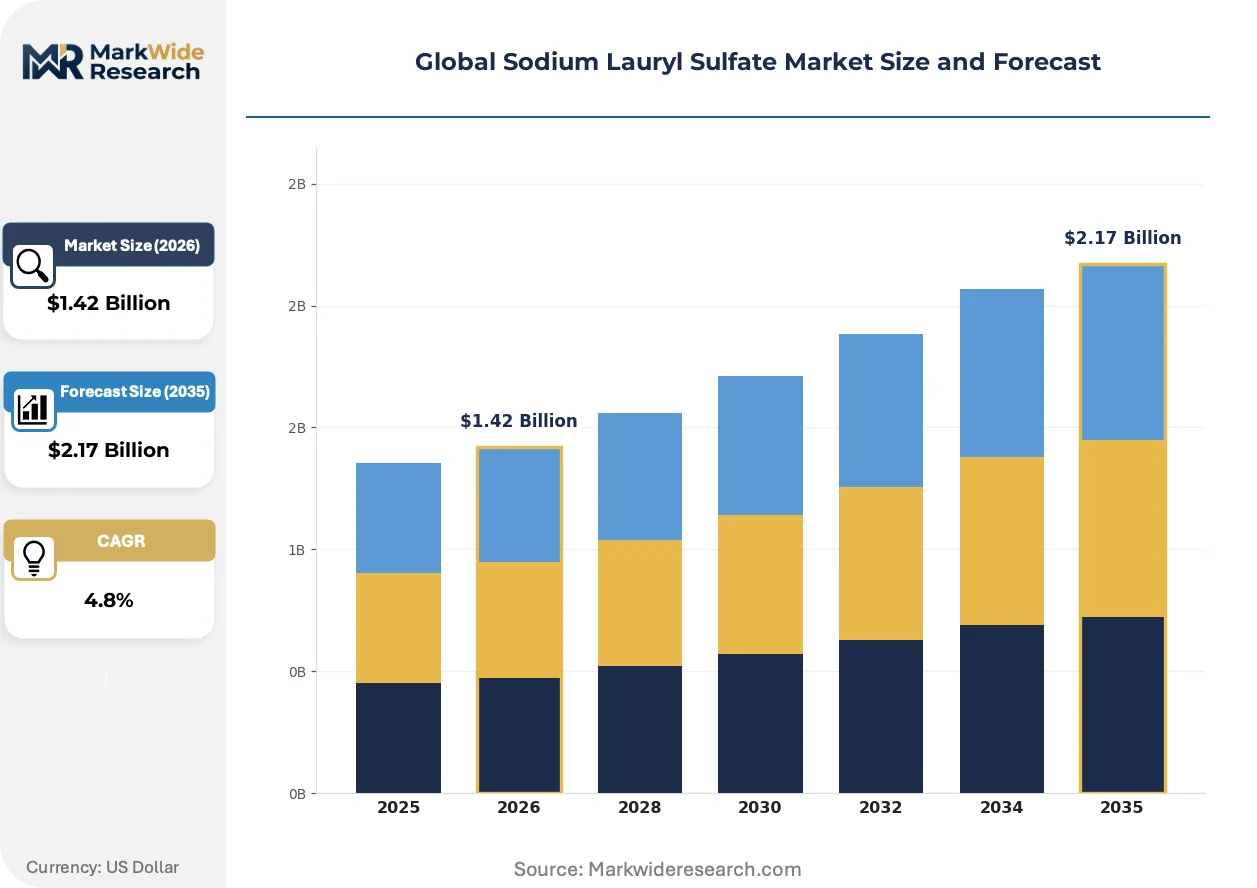
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granular, Paste Formulation Grade: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Personal Care, Household Cleaning, Textile Processing, Agriculture Chemicals, Paints & Coatings End User: Detergent Manufacturers, Paper Mills, Leather Processing, Water Treatment, Oilfield Chemicals |
| Companies Covered | Stepan Company, Sasol Limited, BASF SE, KLK OLEO, Galaxy Surfactants, Solvay, Clariant, Kao Corporation, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Lauryl Sulfate Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine competitive advantage, with feedstock provenance and biodegradability certification displacing traditional price-per-kilogram metrics in procurement decisions.
Enzymatic sulfation processes are hybridizing conventional chemical sulfation routes, enabling milder reaction conditions and reduced byproduct formation. Specialty chemical producers in Germany and the Netherlands are piloting these biocatalytic systems for pharmaceutical-grade output. The technology is compressing energy intensity benchmarks while opening pathways to bio-based carbon certification.
REACH registration mandates for surfactant importers are tightening purity documentation and supply chain transparency requirements. European formulators must now maintain substance volume tracking and exposure scenario reporting across downstream uses. Cosmetic and industrial grade producers are responding by consolidating supplier bases to reduce audit burden.
Third-party surfactant leasing arrangements are displacing traditional spot purchasing in North American detergent manufacturing. Toll manufacturing contracts with guaranteed offtake clauses are reducing working capital requirements for mid-tier brands. This procurement evolution is most visible in contract packaging hubs around Chicago and New Jersey.
Global Sodium Lauryl Sulfate Market Segmentation
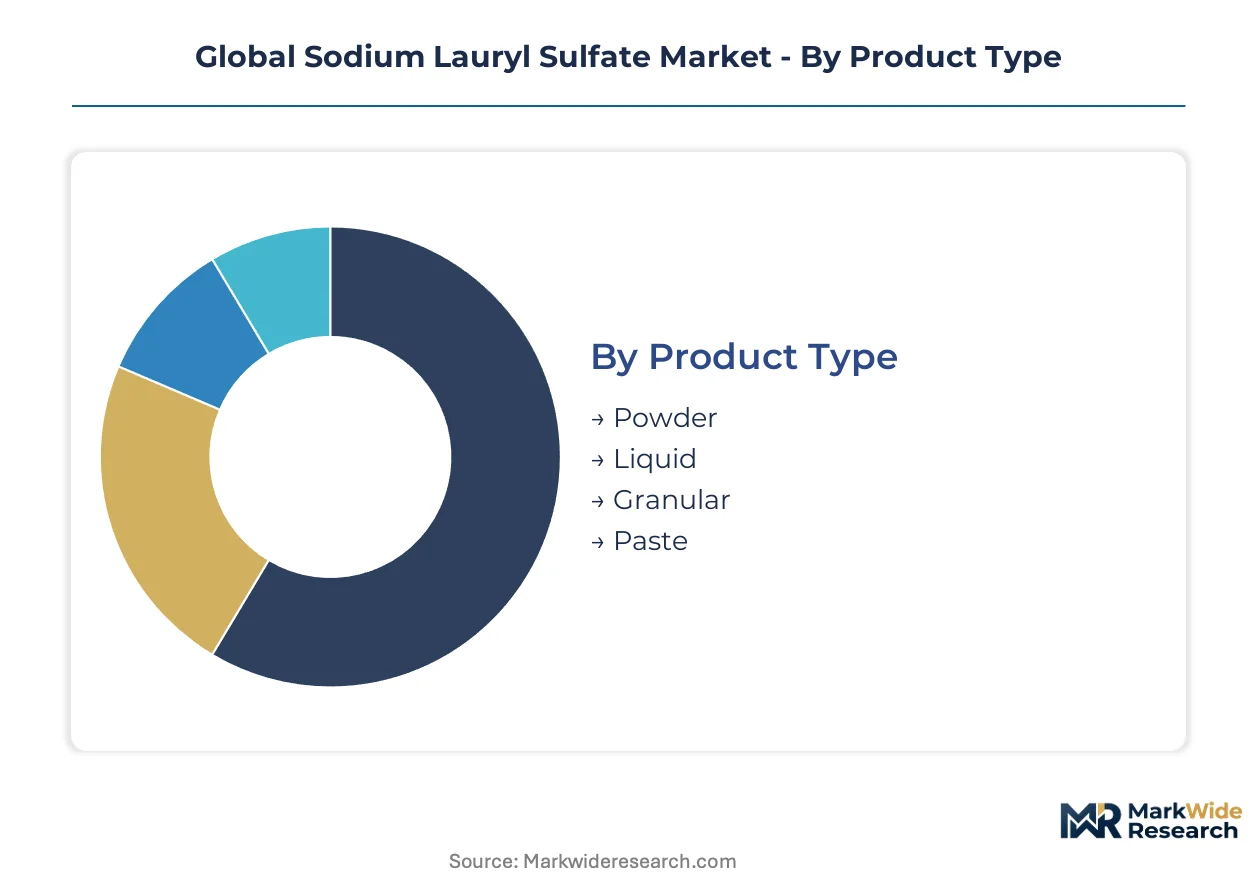
SLS procurement patterns diverge sharply across physical forms, purity grades, and end-use specifications. Formulators select segments based on handling economics, regulatory compliance burdens, and performance thresholds in target applications.
Product Type:
The use-case spectrum spans continuous manufacturing integration to precision dosing requirements.
- Liquid:Active matter concentrations of 28-30% enable direct pump-fed integration into continuous detergent production lines. Demand concentrates in North American contract manufacturing hubs around Chicago and New Jersey where toll arrangements dominate procurement.
- Powder:Spray-dried crystalline form delivers precise dosing control for pharmaceutical and food-grade applications. Demand clusters in Germany and Switzerland for oral care and topical drug delivery formulations where purity documentation requirements are most stringent.
- Granular:Free-flowing particulate form bridges handling convenience with reduced dust exposure versus fine powder. Industrial compounders in India favor this format for agricultural adjuvant blending operations.
- Paste:Semi-solid consistency suits small-batch cosmetic formulators requiring manual incorporation without specialized liquid handling infrastructure. Artisan personal care producers in France and Italy source this grade for premium positioning.
Established volume favors Liquid; emerging adoption favors Powder.
Formulation Grade:
Cost tier stratification separates commodity industrial supply from certified premium streams.
- Cosmetic Grade:Heavy metal limits and microbial specifications meet FDA cosmetic safety thresholds. Personal care formulators in the United States and Brazil procure this grade for sulfate-based cleansers amid steady surfactant demand.
- Pharmaceutical Grade:USP-NF monograph compliance enables excipient use in oral and topical drug products. European and Japanese pharmaceutical manufacturers absorb qualification premiums for this limited-supply tier.
- Industrial Grade:Relaxed purity specifications serve textile wetting and emulsion polymerization applications. Chinese and Indian textile processors drive volume procurement of this cost-optimized grade.
- Food Grade:FCC compliance permits use as a whipping aid and processing aid in food manufacturing. North American and European food additive formulators maintain qualified supplier lists for this regulated category.
Cosmetic Grade commands the broadest demand base; Pharmaceutical Grade extracts the steepest margin premiums.
Application:
Volume concentration maps to consumer product manufacturing scale while growth velocity aligns with agricultural intensification.
- Personal Care:Shampoo, body wash, and facial cleanser formulations consume the largest value share. Brazilian and Indonesian formulators are expanding procurement despite sulfate-free substitution pressure in premium segments.
- Agriculture Chemicals:Pesticide wetting agents and fertilizer coatings represent the steepest expansion trajectory. Indian and Brazilian crop protection formulators are scaling SLS procurement as intensive farming spreads.
- Household Cleaning:Dishwashing liquids and laundry detergents anchor commodity-grade demand. Private-label manufacturers in Poland and Turkey source this application for export-oriented production.
- Textile Processing:Scouring and dye-leveling applications depend on SLS wetting efficiency. Bangladeshi and Vietnamese textile mills integrate this grade into garment finishing operations.
- Paints & Coatings:Emulsion stabilization and pigment dispersion utilize industrial-grade material. Mexican and South Korean coatings producers specify this segment for architectural paint manufacturing.
Personal Care sustains the revenue base; Agriculture Chemicals is climbing the fastest.
End User:
Customer-type segmentation reveals divergent procurement sophistication and specification stringency.
- Detergent Manufacturers:Large-scale continuous operations demand liquid SLS in bulk tanker deliveries. Brazilian and Nigerian consumer goods producers dominate procurement volume in this category.
- Oilfield Chemicals:Enhanced oil recovery and drilling fluid applications require specialized emulsion-grade specifications. Saudi and Norwegian oilfield service companies specify this segment for offshore and shale operations.
- Paper Mills:Pulping and deinking processes utilize industrial-grade surfactant for fiber separation. Finnish and Canadian pulp producers integrate SLS into mechanical pulping lines.
- Water Treatment:Foam generation for aeration and pollutant flotation employs technical-grade material. Australian and Chilean municipal utilities specify this application for wastewater processing.
- Leather Processing:Degreasing and wetting operations in tanning utilize standard industrial grades. Italian and Pakistani tanneries source this segment for finished leather production.
Detergent Manufacturers anchor volume commitments; Oilfield Chemicals is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for specialty chemicals is attracting capacity investments for export-oriented surfactant manufacturing, reshaping regional supply dynamics. China's GB standard harmonization is consolidating domestic production and streamlining export qualification for certified manufacturers. Germany's REACH enforcement and EU Green Deal mandates are compressing margins for non-integrated producers while advantaging certified multi-grade suppliers.
China
Agricultural adjuvant demand from crop protection formulators is accelerating SLS procurement for pesticide wetting agents. GB standards for industrial chemical safety are tightening certification requirements for surfactant exporters. Manufacturing clusters in Jiangsu and Zhejiang provinces are scaling pharmaceutical-grade powder output for oral care applications.
India
Intensive farming expansion is driving agricultural chemical formulators to scale SLS procurement for fertilizer coatings and pesticide formulations. The PLI scheme for specialty chemicals is subsidizing production-linked capacity investments in Gujarat and Maharashtra. Surfactant manufacturing hubs in Mumbai-Pune corridor are targeting export markets in Southeast Asia and Africa.
Germany
REACH registration mandates for surfactant importers are elevating purity documentation and supply chain transparency burdens. ECHA biodegradability thresholds are forcing reformulation investments across European detergent supply chains. Industrial chemical clusters in North Rhine-Westphalia are piloting enzymatic sulfation processes for pharmaceutical-grade output.
United States
FDA oversight of cosmetic-grade SLS purity is elevating compliance costs for personal care formulators sourcing sulfate-based cleansers. Third-party surfactant leasing arrangements are displacing spot purchasing in contract manufacturing hubs around Chicago and New Jersey. Stepan Company's integrated alkyl sulfate chain sustains cost discipline across North American supply.
Brazil
ANVISA cosmetic safety regulations are tightening microbial specifications for imported surfactant materials. Crop protection formulators are expanding SLS procurement as intensive soybean and corn farming spreads across Mato Grosso and Paraná. São Paulo-based detergent manufacturers are absorbing qualification premiums for multi-grade certified supply.
Global Sodium Lauryl Sulfate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated grade tiers. The vendor base spans integrated petrochemical conglomerates, oleochemical specialists, and toll manufacturing operators. Three archetypes dominate: Fischer-Tropsch feedstock controllers, integrated alkyl sulfate chain operators, and formulation-grade portfolio diversifiers. Capacity expansion and certified multi-grade capability acquisition represent the dominant competitive moves.
Within the integrated petrochemical tier, Sasol Limited and BASF SE exemplify divergent feedstock strategies. Sasol anchors its position through Fischer-Tropsch-derived feedstock control in South Africa and Europe. BASF SE occupies a broad formulation-grade portfolio spanning cosmetic and industrial specifications. Stepan Company represents the North American integrated operator archetype with captive alkyl sulfate production. Galaxy Surfactants and KLK OLEO sit within the Asia-Pacific oleochemical specialist tier, serving export-oriented demand from Malaysian and Indian manufacturing bases.
| Leading Market Players |
|---|
| Stepan Company |
| Sasol Limited |
| BASF SE |
| KLK OLEO |
| Galaxy Surfactants |
| Solvay |
| Clariant |
| Kao Corporation |
| Croda International Plc |
| Others |
Supply & Pricing Matrix
South African Fischer-Tropsch feedstock concentration funnels margin capture toward integrated alkyl sulfate producers, while toll manufacturers absorb lauryl alcohol volatility without pricing power.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade powder and industrial-grade liquid. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects REACH documentation burden and FDA purity thresholds. Pricing pressure stems from sulfate-free substitution in premium personal care segments. Contract detergent manufacturers exhibit highest price sensitivity; European pharmaceutical formulators absorb steepest qualification premiums.
Supply Chain Analysis
Lauryl alcohol feedstock draws from Malaysian and Indonesian palm kernel oil estates, with coconut oil alternatives anchored in Philippine and Indian supply. Sulfation capacity concentrates in Germany, China, and South Africa. Single-source vulnerability runs through Sasol's Fischer-Tropsch-derived feedstock control. Distribution runs through bulk tanker liquid deliveries to North American contract manufacturing hubs and containerized powder shipments to European pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large detergent manufacturers consolidating procurement through third-party surfactant leasing arrangements, fragmenting pricing leverage among smaller formulators.
For Market Incumbents: Entrench multi-grade certification capabilities across FDA, REACH, and GB standards to capture compliance premiums. Deepen backward integration into lauryl alcohol supply through Malaysian or Indonesian oleochemical partnerships. Defend against enzymatic sulfation disruptors by piloting biocatalytic production for pharmaceutical-grade output. For New Entrants and Emerging Players: Establish a beachhead in India's agricultural adjuvant segment where PLI-subsidized capacity meets unmet crop protection demand. Target pharmaceutical-grade powder production for oral care applications with limited qualified suppliers. Pursue toll manufacturing partnerships with guaranteed offtake clauses to reduce working capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed oleochemical specialists lacking REACH-compliant European distribution. Five-to-ten year viability hinges on biodegradability certification convergence with EU Green Deal thresholds. Watch for fermentation-derived lauryl alcohol cost parity as inflection signal for bio-based feedstock transition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lauryl Alcohol | Captive feedstock supply insulates Stepan and Sasol from palm kernel oil volatility. |
| Enzymatic Sulfation Pilot Programs | German and Dutch specialty producers compress energy intensity for pharmaceutical-grade certification. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, REACH, and GB compliance opens premium margin pools in cross-border trade. |
| Third-Party Surfactant Leasing Expansion | Chicago and New Jersey contract hubs reduce working capital for mid-tier detergent brands. |
| India PLI Scheme Capacity Buildout | Gujarat and Maharashtra investments target Southeast Asian and African export markets. |
Research Methodology
A spread of perspectives from plant managers at integrated alkyl sulfate producers, procurement leads at downstream detergent OEMs, distribution channel partners in North American contract manufacturing hubs, and technical R&D directors at enzymatic sulfation pilots converged on the working assumptions. Secondary validation drew from customs and trade data, ACC and Cefic surfactant reports, SEC 10-K filings of listed chemical producers, and ECHA registration databases. Bottom-up volume estimates triangulated against top-down market sizing across grade tiers and regional production hubs.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation across formulation grade, physical form, end-use industry, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and forward-looking capacity announcements. Industry-specific inputs included lauryl alcohol feedstock price indices, REACH registration renewal timelines, and agricultural adjuvant formulation growth in target geographies.
Macroeconomic conditions sit as an overlay; deviation in palm kernel oil prices, euro-dollar exchange rates, or EU Green Deal implementation pace would shift the trajectory. Cross-checking against ECHA substance volume tracking and customs export data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Glycol Monostearate Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Wax Emulsion Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Amino Silicone Oil Market
Surfactants
MDEA Esterquats Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Global Biosurfactant Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Micellar Water Market
Surfactants
Powder Defoamers Market
Surfactants
Cetyl Chloride Market