
 Polyoxyethylene Sorbitan Tristearate Market | 2026-2036
Polyoxyethylene Sorbitan Tristearate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyoxyethylene Sorbitan Tristearate Market Analytics
Plant-derived sorbitan esters is repositioning petroleum-based emulsifiers in cost-sensitive formulations. Croda International Plc leverages botanical feedstock integration to sustain premium positioning across European cosmetic supply chains. BASF SE anchors industrial-scale output through backward integration into ethoxylation capacity. Evonik Industries AG differentiates via high-purity grades for pharmaceutical injectable applications.
Polyoxyethylene sorbitan tristearate is a nonionic surfactant synthesized by ethoxylating sorbitan tristearate to yield approximately 20 moles of ethylene oxide, functioning primarily as an emulsifier and solubilizer in oil-in-water systems. The liquid product type dominates volume throughput due to ease of handling in continuous manufacturing, while powder grades command margin premiums from food additive clients seeking shelf-stable dry blends. Cosmetics applications lead absolute consumption, though pharmaceutical-grade demand accelerates fastest as parenteral formulation standards tighten.
EMA pharmaceutical guidelines and REACH chemical registration frameworks in Europe enforce purity thresholds that reshape supplier qualification requirements. FDA food additive regulations and EPA chemical handling standards in the United States further segment market access by application category. Stakeholders must monitor evolving biobased certification schemes and regional ethylene oxide supply constraints to secure formulation partnerships.
Market Dynamics
REACH compliance in Europe is compressing supplier margins while simultaneously opening premium positions for biobased-certified producers, creating a bifurcation between commodity-grade and pharmaceutical-grade supply tiers.
Growth Catalysts
- Clean-label food additive mandates:FSSAI tightening in India and FDA guidance in the United States favor plant-derived emulsifiers over synthetic alternatives in processed foods.
- Ethoxylation capacity expansion:Domestic surfactant production scaling in China reduces import dependency and shortens lead times for regional formulators.
- Pharmaceutical-grade purity requirements:EMA injectable formulation standards are disqualifying lower-purity suppliers and consolidating procurement around certified manufacturers.
Market Restraints
- Ethylene oxide supply volatility:Feedstock concentration in Gulf Coast petrochemical clusters exposes margins to hurricane-related disruptions and export quota fluctuations.
- Technical performance ceiling:Polyoxyethylene sorbitan tristearate exhibits limited thermal stability above 80°C, restricting high-temperature food processing applications.
- Substitution pressure from sucrose esters:Japanese and South Korean food manufacturers are piloting sucrose-based alternatives with comparable HLB values and cleaner dissolution profiles.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya present whitespace for shelf-stable emulsifier distribution as processed food manufacturing localizes.
- Dual-carbon policy alignment:China's MEE biobased certification scheme rewards ethoxylated sorbitan esters with carbon-intensity scores below petroleum benchmarks.
- Direct-to-manufacturer e-procurement:Specialty chemical platforms are disintermediating traditional distributors for mid-volume cosmetic compounders in Southeast Asia.
Industry Challenges
- Pharmaceutical-grade validation timelines:EMA and FDA concurrent review processes extend qualification cycles to 18-24 months for new manufacturing sites.
- Legacy batch reactor integration:Continuous ethoxylation technology requires capital retrofitting that stranded-asset producers cannot finance without dilutive equity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyoxyethylene Sorbitan Tristearate Market |
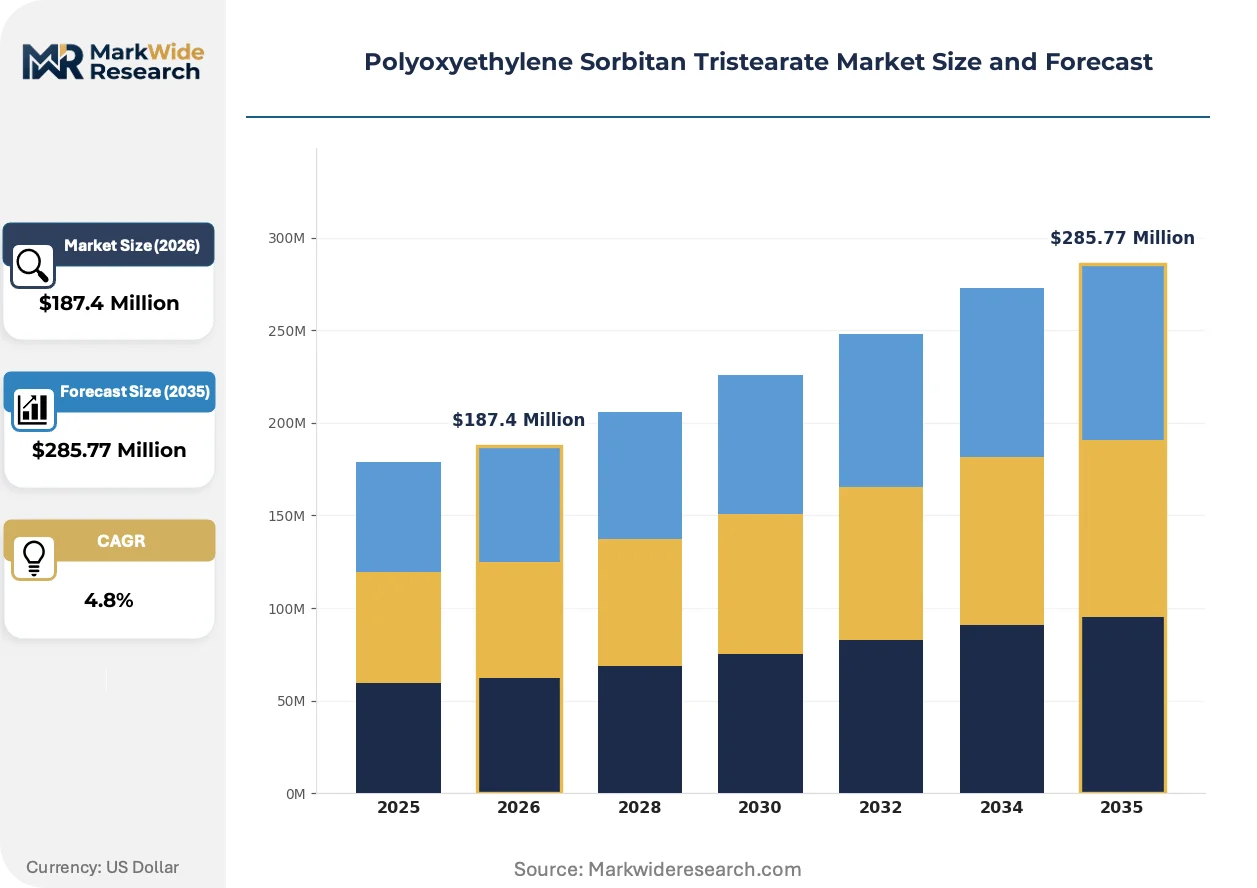
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Emulsion, Granule Application: Cosmetics, Food Additive, Pharmaceuticals, Personal Care End User: Manufacturers, Distributors, Retailers, Research Institutions Packaging Type: Bottles, Bags, Drums, Pouches |
| Companies Covered | BASF SE, Croda International Plc, Evonik Industries AG, Merck KGaA, Kao Group, ERCA Group, Dow Chemical Company, Kawaken Fine Chemicals Co., Ltd., Coast Southwest, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyoxyethylene Sorbitan Tristearate Market Evolving Landscape
Continuous processing technology is compressing unit economics for ethoxylated surfactants while regulatory purity thresholds are rewiring supplier qualification protocols across pharmaceutical and food additive segments.
Enzymatic esterification is electrifying production economics for high-purity sorbitan tristearate precursors. European cosmetic compounders are adopting enzymatic routes to meet RSPO certification requirements. The technology is electrifying margin structures by eliminating solvent recovery costs and enabling smaller-batch pharmaceutical-grade output.
REACH Annex XVII restrictions on ethylene oxide residuals are tightening testing protocols for imported surfactant lots. ECHA enforcement has disqualified three Asian suppliers from EU pharmaceutical supply chains since 2023. Food additive clients in Germany and France are now demanding third-party residual testing certificates as standard procurement terms.
Compounders are consolidating supplier panels from twelve-plus vendors to three qualified partners with backward-integrated ethoxylation capabilities. This concentration is compressing switching flexibility but securing volume commitments that justify dedicated production lines. The shift is most pronounced in Italian and Spanish cosmetic manufacturing clusters where just-in-time inventory models dominate.
Polyoxyethylene Sorbitan Tristearate Market Segmentation
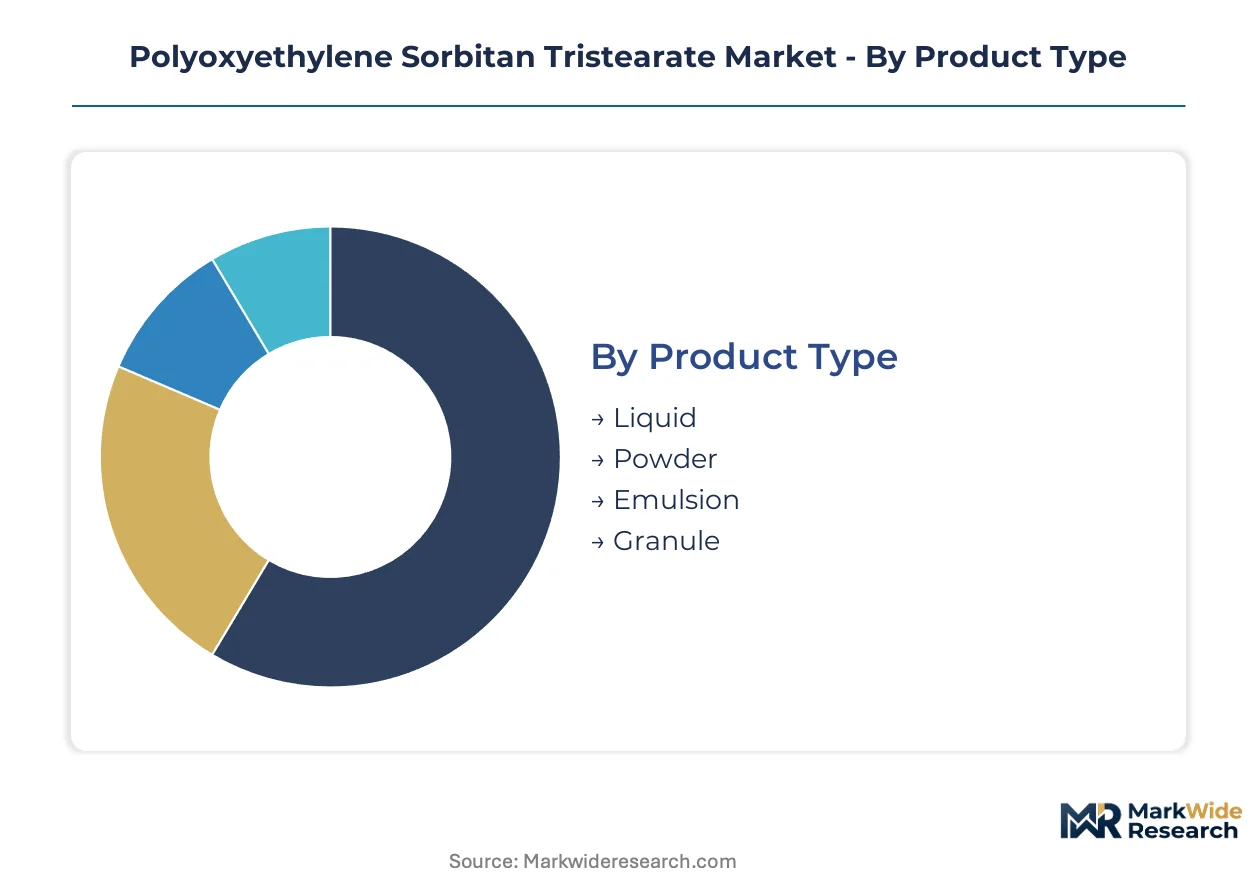
Segmentation in the polyoxyethylene sorbitan tristearate market reveals how physical form, regulatory grade, and supply chain position determine margin capture. Manufacturers configure production assets around specific segment requirements rather than serving all tiers equally.
Product Type:
Supply concentration in continuous ethoxylation lines favors liquid output, while batch-capable assets serve specialty solid grades.
- Liquid:Dominates volume throughput due to seamless integration into automated cosmetic and food manufacturing lines. Demand concentrates in Chinese surfactant plants scaling domestic ethoxylation capacity for regional formulators seeking shortened lead times.
- Powder:Commands margin premiums through spray-drying investments that eliminate solvent residues for pharmaceutical and clean-label food clients. European compounders in Germany and France now require third-party residual testing certificates as standard procurement terms.
- Emulsion:Pre-dispersed formats reduce handling complexity for mid-scale cosmetic compounders lacking in-house homogenization equipment.
- Granule:Shelf-stable dry blends target African processed food manufacturers in Nigeria and Kenya where cold-chain infrastructure remains limited.
Today's leader: Liquid. Tomorrow's challenger: Powder.
Application:
Cost tier separation between commodity emulsifiers and certified pharmaceutical grades is widening qualification barriers.
- Cosmetics:Oil-in-water emulsification for skincare and color cosmetics represents the largest absolute consumption segment. Italian and Spanish manufacturing clusters are consolidating supplier panels to three qualified partners with backward-integrated ethoxylation capabilities.
- Pharmaceuticals:Parenteral and injectable formulation standards are climbing fastest. EMA guidelines and FDA concurrent review processes extend qualification cycles to 18-24 months for new manufacturing sites, consolidating procurement around certified producers.
- Food Additive:Clean-label mandates from FSSAI in India and FDA guidance in the United States favor plant-derived emulsifiers over synthetic alternatives in processed foods.
- Personal Care:Shampoo and body wash formulations drive steady demand for mid-HLB emulsifiers with proven skin tolerance profiles.
Volume anchor: Cosmetics. Steepest expansion trajectory: Pharmaceuticals.
End User:
Customer type determines whether procurement flows through distributor markups or direct manufacturer relationships.
- Manufacturers:Large-scale compounders in personal care and food processing drive bulk volume with multi-year supply agreements.
- Distributors:Traditional channel partners face disintermediation pressure from specialty chemical e-procurement platforms targeting mid-volume Southeast Asian cosmetic compounders.
- Retailers:Private-label skincare brands require small-batch flexibility with rapid formulation turnaround.
- Research Institutions:Academic and clinical trial sponsors generate demand for high-purity reference grades with full analytical documentation.
Margin concentration: Manufacturers. Channel disruption risk: Distributors.
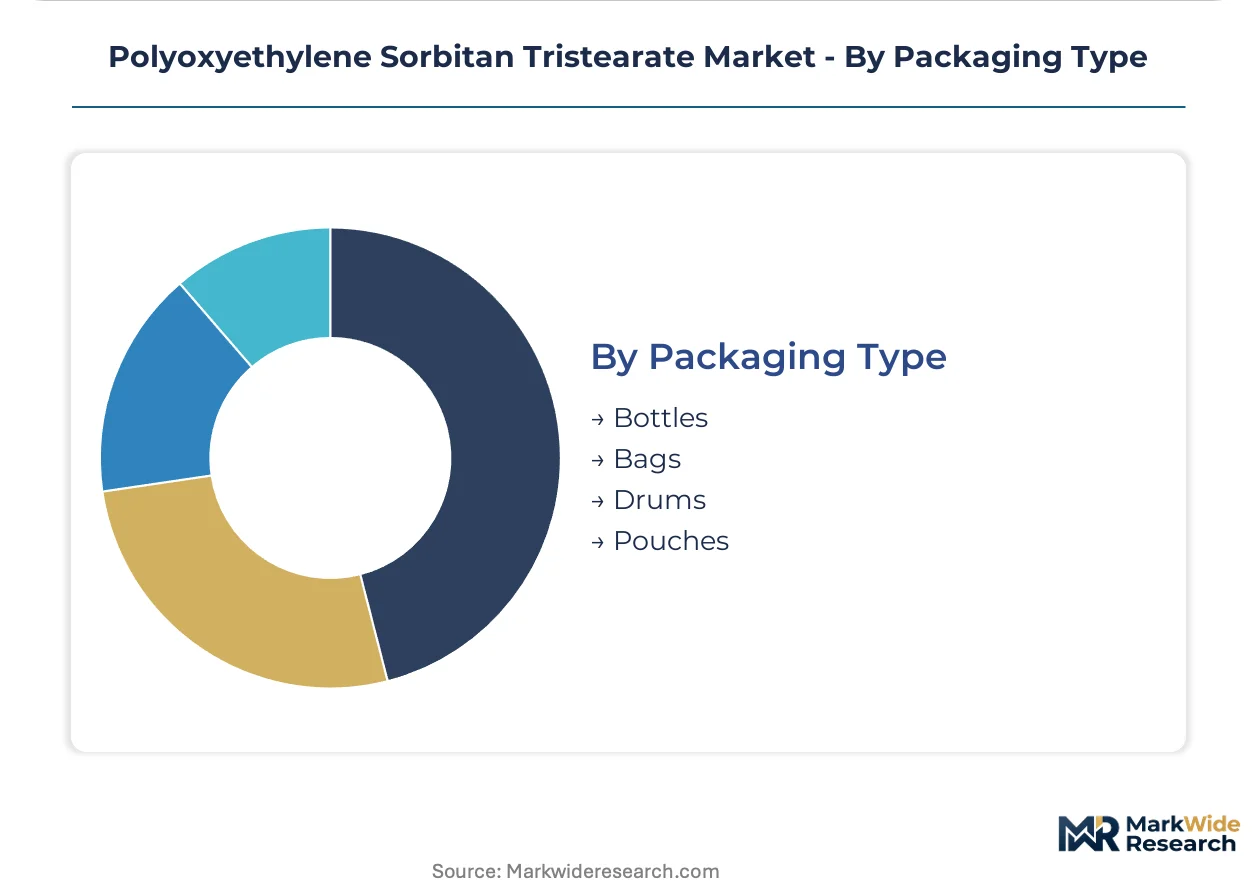
Packaging Type:
Packaging selection tracks handling infrastructure and contamination risk tolerance across end-use segments.
- Drums:Standard bulk format for industrial-scale cosmetic and food manufacturing with established handling protocols.
- Bags:Flexible intermediate bulk containers reduce storage footprint for powder grades in warehouse-constrained facilities.
- Bottles:Small-volume packaging serves research institutions and pilot-scale formulation labs requiring precise dosing control.
- Pouches:Single-use formats minimize cross-contamination risk in pharmaceutical cleanroom environments.
Scale efficiency leader: Drums. Growth format: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors global ethoxylation capacity expansion for sorbitan ester surfactants. Domestic surfactant plants in Jiangsu and Zhejiang provinces are scaling continuous processing lines to serve regional cosmetic and food formulators. Regulatory pressure from MEE biobased certification schemes is accelerating carbon-intensity benchmarking across supply chains.
United States
Gulf Coast petrochemical clusters concentrate ethylene oxide feedstock supply for domestic emulsifier production. FDA food additive regulations and EPA chemical handling standards segment market access by application tier. Houston-area surfactant plants face margin pressure from hurricane-related disruption exposure and export quota volatility.
Germany
REACH Annex XVII enforcement is disqualifying lower-purity surfactant imports from pharmaceutical supply chains. ECHA residual testing protocols now mandate third-party certification for ethylene oxide content. North Rhine-Westphalia's chemical corridor hosts backward-integrated producers serving cosmetic compounders in Cologne and Düsseldorf manufacturing clusters.
India
FSSAI clean-label mandates favor plant-derived emulsifiers in processed food formulations. Domestic surfactant demand concentrates in Maharashtra and Gujarat where pharmaceutical contract manufacturing is expanding. Mumbai-Pune industrial belt formulators are consolidating supplier panels to reduce qualification burden.
Japan
Sucrose ester substitution pressure is reshaping emulsifier procurement in food manufacturing. METI industrial standards for biobased content are tightening formulation disclosure requirements. Osaka-Kobe chemical clusters are piloting enzymatic esterification routes to meet RSPO certification demands from cosmetic exporters.
Polyoxyethylene Sorbitan Tristearate Market Competitive Landscape
Global majors compete with regional champions across ethoxylation capacity and pharmaceutical-grade certification tiers. The supplier base bifurcates between commodity-scale continuous processors and batch-capable specialty producers. Three archetypes dominate: backward-integrated petrochemical giants, enzymatic-route biobased specialists, and pharmaceutical-grade purity validators. Competitive moves concentrate on M&A for ethoxylation assets and strategic partnerships for biobased feedstock security.
Within the premium certification tier, BASF SE and Evonik Industries AG exemplify pharmaceutical-grade positioning through integrated production architectures. Croda International Plc occupies a distinct botanical-feedstock position serving European cosmetic supply chains with RSPO-aligned output. These three anchors represent divergent strategic vectors: petrochemical scale, purity validation, and biobased premiumization.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Evonik Industries AG |
| Merck KGaA |
| Kao Group |
| ERCA Group |
| Dow Chemical Company |
| Kawaken Fine Chemicals Co., Ltd. |
| Coast Southwest, Inc. |
| Others |
Value Network & Pricing Analysis
China's MEE biobased certification scheme gates qualified supply for premium-tier pricing access, compressing margins for uncertified producers while rewarding carbon-intensity leaders with procurement preference from European cosmetic compounders and Indian food manufacturers seeking clean-label credentials.
Pricing Analysis
Ethylene oxide feedstock pass-through dominates pricing volatility for commodity-grade liquid output, with Gulf Coast petrochemical clusters transmitting hurricane-related disruption costs downstream. Pharmaceutical-grade powder commands three-tier pricing structure across premium, standard, and economy levels, with EMA-certified batches capturing substantial premiums over REACH-compliant food additive grades. Pricing pressure stems from sucrose ester substitution in Japanese food manufacturing, while mid-volume Southeast Asian cosmetic compounders exhibit highest price sensitivity due to disintermediation via e-procurement platforms.
Supply Chain Analysis
Single-source vulnerability sits with ethylene oxide production concentrated in Texas and Louisiana petrochemical corridors, exposing surfactant manufacturers to export quota fluctuations and weather-related outages. Feedstock sourcing draws from Saudi ethylene crackers, US shale gas liquids, and Chinese coal-to-olefins complexes, while sorbitan tristearate precursors originate from Malaysian palm oil derivatives and European rapeseed processing. Tariff exposure on ethoxylated imports into the European Union threatens Asian exporter margins. Distribution runs through backward-integrated chemical majors for bulk pharmaceutical and food additive volumes, with specialty distributors serving fragmented cosmetic compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with pharmaceutical-grade certification requirements and clean-label food additive mandates driving steady replacement demand across formulation supply chains.
For Market Incumbents: Anchor backward integration into ethoxylation capacity to defend against stranded-asset risk from continuous processing technology adoption. Secure RSPO-aligned botanical feedstock partnerships to preempt biobased certification displacement in European cosmetic supply chains. Prioritize EMA and FDA concurrent qualification investments to consolidate procurement around certified manufacturing sites. For New Entrants and Emerging Players: Enter via enzymatic esterification routes serving mid-scale pharmaceutical compounders seeking smaller-batch high-purity output with eliminated solvent recovery costs. Target underpenetrated African processed food markets in Nigeria and Kenya where shelf-stable dry blend demand outpaces local emulsifier production. Pursue direct-to-manufacturer e-procurement positioning for Southeast Asian cosmetic formulators lacking homogenization infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for batch-capable specialty producers because pharmaceutical-grade validation timelines create durable switching costs and consolidate procurement around qualified manufacturing sites. Five-to-ten year viability hinges on carbon-intensity benchmarking alignment with China's MEE certification scheme and European REACH Annex XVII enforcement trajectories. Monitor ECHA disqualification actions as inflection indicators for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethoxylation Capacity | BASF SE and Dow Chemical Company secure captive ethylene oxide supply against Gulf Coast disruption exposure. |
| Enzymatic Esterification Technology Adoption | Croda International Plc eliminates solvent recovery costs while meeting RSPO certification requirements from European cosmetic clients. |
| Pharmaceutical-Grade Certification Investment | Evonik Industries AG extends EMA and FDA qualification cycles to consolidate injectable formulation procurement. |
| Biobased Feedstock Partnership | Merck KGaA secures Malaysian palm oil derivative supply chains for carbon-intensity scoring below petroleum benchmarks. |
| Direct E-Procurement Platform Launch | Kao Group disintermediates traditional distributors for mid-volume Southeast Asian cosmetic compounders seeking shortened lead times. |
Research Methodology
Bottom-up emulsifier consumption modeling reconciled against top-down ethoxylation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Jiangsu and Zhejiang surfactant facilities, procurement leads at Italian and Spanish cosmetic compounders, distribution channel partners in Mumbai-Pune industrial belt, and technical R&D directors at enzymatic esterification pilots were cross-validated against secondary sources including customs and trade data from China Customs and Eurostat, ACC and Cefic surfactant industry reports, SEC 10-K filings from disclosed chemical majors, and ECHA registration dossiers for REACH-compliant substances.
Input-output matrix framing connects ethylene oxide feedstock availability through continuous and batch reactor configurations to segmented output volumes across liquid, powder, emulsion, and granule formats. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs were derived from ethoxylation capacity expansion trajectories, pharmaceutical-grade purity requirement adoption curves, and clean-label food additive mandate implementation schedules.
Inputs from primary stakeholder interviews and disclosed regulatory filings were available through the study window; gaps in proprietary production cost structures at enzymatic esterification pilots and unreported ethylene oxide contract pricing introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding REACH Annex XVII enforcement continuity, MEE biobased certification scheme expansion, and FSSAI clean-label mandate progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Polymer Surfactants Market
Surfactants
Detergent Chemicals Market
Surfactants
Global Rhamnolipid Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Emulsifying Wax Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Natural Surfactants Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Wax Emulsion Market
Surfactants
Procream Market